
 Vegan Noodles Market | 2026-2036
Vegan Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Noodles Market Analytics
Southeast Asia is rewriting competitive dynamics in vegan noodle manufacturing as Thailand and Vietnam expand rice noodle processing capacity. Nestlé S.A. leverages its refrigerated supply chain to dominate European retail placement. Nissin Foods Holdings anchors its position through instant-format R&D intensity in Japan. Lotus Foods specializes in heirloom rice varietals that command premium shelf positioning in North American health stores.
Vegan noodles are wheat-free or egg-free pasta products manufactured from legume, grain, or root starches, typically extruded at moisture levels below 12% to achieve al dente texture upon rehydration. Rice noodles currently lead volume due to established Southeast Asian export infrastructure, while chickpea noodles represent the fastest-growing product type as protein fortification appeals to fitness-oriented households. Supermarkets capture the largest share of distribution value, though online retailers are gaining traction among subscription-based repeat buyers seeking bulk formats.
The EU Green Deal and EFSA nutrition claims standards shape ingredient transparency requirements across European supply chains, while FDA allergen labeling rules in the United States mandate clear egg-free declarations. India's FSSAI plant-based food categorization creates new compliance thresholds for imported brands. Stakeholders must monitor how evolving carbon footprint disclosure rules in the EU and emerging GB standards in China will reshape sourcing decisions and facility certification requirements.
Market Dynamics
EU Green Deal carbon footprint disclosure mandates are forcing Southeast Asian rice noodle processors to reconfigure supply chains around certified sustainable sourcing, compressing margins for uncertified competitors while rewarding early adopters with preferential retail placement.
Growth Catalysts
- EU Green Deal sustainable food system targets:Tightening ingredient sourcing requirements create compliance-driven demand for traceable legume and grain starches across European retail channels.
- Quick-service restaurant chains:Southeast Asian QSR expansion of plant-based menu offerings generates institutional-scale procurement contracts for instant-format vegan noodles.
- Protein fortification technology:Chickpea and lentil flour extrusion advances enable texture parity with wheat-based noodles, unlocking fitness-oriented household segments.
Market Restraints
- Input cost volatility:Chickpea and mung bean prices fluctuate with Indian monsoon patterns, squeezing margin stability for protein-fortified product lines.
- Supply concentration risk:Thai and Vietnamese rice noodle processing infrastructure dominates export volume, creating single-point vulnerability for global distribution.
- Technical limitation:Egg-free binding agents fail to replicate wheat gluten elasticity in fresh refrigerated formats, constraining texture innovation.
Strategic Opportunities
- South Korea urban retail corridors:Demand concentration in Seoul and Busan convenience store networks supports premium positioning for single-serve fortified formats.
- Subscription-based bulk channels:Online retailers capture repeat buyers through automated replenishment, reducing customer acquisition costs versus supermarket slotting fees.
- India FSSAI plant-based categorization:New compliance thresholds for imported brands create first-mover advantage for early certification investments.
Industry Challenges
- Refrigerated supply chain capex intensity:Cold-chain infrastructure requirements for fresh vegan noodle distribution demand capital deployment that mid-scale processors struggle to fund.
- Allergen labeling compliance timelines:FDA egg-free declaration mandates and EFSA nutrition claims standards require reformulation cycles that delay product launches.
- Extrusion technician scarcity:Specialized knowledge of low-moisture legume starch processing commands wage premiums that inflate facility operating costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Noodles Market |
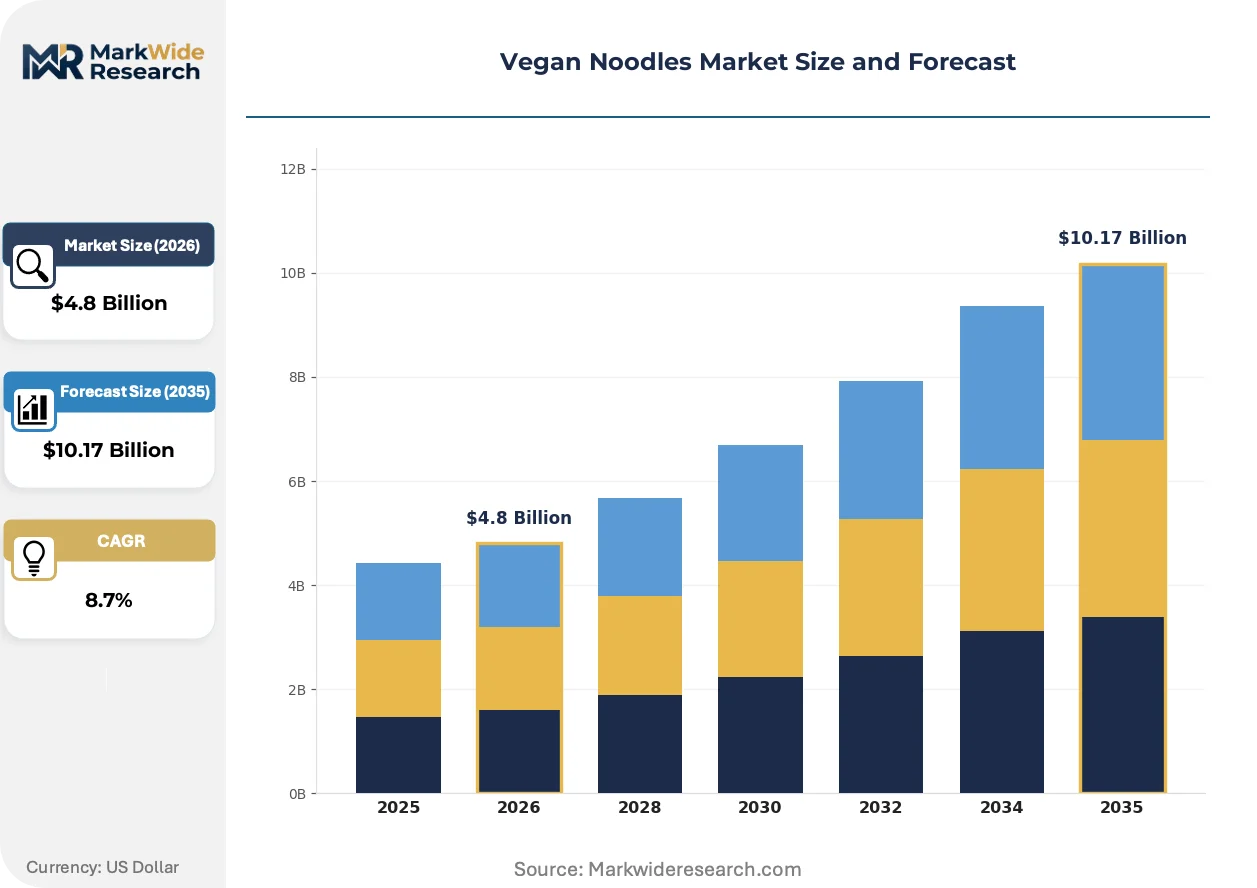
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice Noodles, Buckwheat Noodles, Chickpea Noodles, Quinoa Noodles Distribution Channel: Supermarkets, Online Retailers, Health Stores, Specialty Stores End User: Households, Restaurants, Cafes, Food Services Packaging Type: Bulk Packaging, Retail Packaging, Eco-friendly Packaging, Vacuum Packaging |
| Companies Covered | Nestlé S.A., Nissin Foods Holdings, Unilever, Annie Chun’s, Lotus Foods, Dr. McDougall's Right Foods, Master Kong, Uni-President, Explore Cuisine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Noodles Market Evolving Landscape
Digital twin modeling of extrusion parameters is compressing product development cycles while regulatory transparency mandates reshape ingredient sourcing protocols across multi-jurisdictional supply chains.
High-pressure processing technology is virtualizing traditional thermal pasteurization in fresh vegan noodle manufacturing. Premium refrigerated brands in South Korea and Japan are adopting HPP systems at accelerating rates. This shift is virtualizing shelf-life extension without chemical preservatives, enabling clean-label positioning that commands retail price premiums.
EFSA nutrition claims standards and EU Green Deal carbon footprint disclosure rules are tightening ingredient provenance requirements. European supply chains now demand batch-level traceability documentation from Southeast Asian processors. Fresh and instant-format exporters to Germany, France, and the Netherlands are restructuring supplier audit protocols to maintain market access.
Bulk subscription purchasing is displacing single-unit supermarket trials among repeat vegan noodle consumers. Direct-to-consumer channels capture fitness-oriented households seeking protein-fortified multi-pack formats. This behavioral shift concentrates most visibly in North American urban markets where delivery infrastructure supports frozen and ambient bulk shipments.
Vegan Noodles Market Segmentation
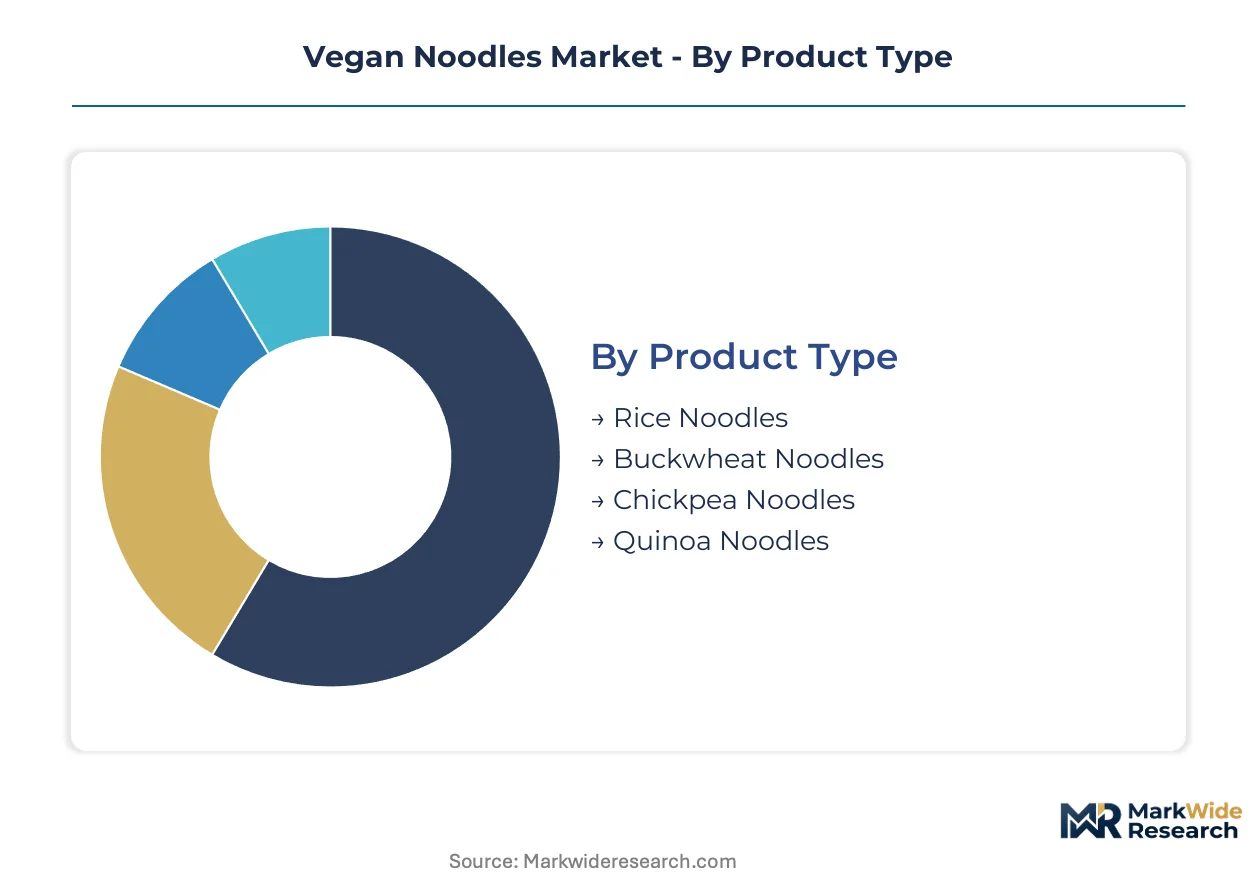
Product format and channel configuration determine margin capture in vegan noodles. Rice and legume starch extrusion technologies diverge across price tiers, while refrigerated versus ambient distribution splits working capital requirements.
Product Type:
Cost tier differentiation separates commodity grain formats from protein-fortified premium positioning.
- Rice Noodles:Extruded from milled rice flour at moisture levels below 12%, achieving translucent al dente texture upon rehydration. Thai and Vietnamese processors dominate export infrastructure, though EU Green Deal carbon disclosure mandates are compressing margins for uncertified suppliers.
- Chickpea Noodles:High-protein legume flour extrusion enables texture parity with wheat-based alternatives, unlocking fitness-oriented household segments in North American urban markets. Indian monsoon volatility creates input cost instability for protein-fortified lines.
- Buckwheat Noodles:Soba-style formats command traditional Japanese culinary positioning with established JIS quality benchmarks.
- Quinoa Noodles:Andean grain sourcing supports premium health-store placement with complete amino acid profiles.
Rice noodles hold installed capacity. Chickpea noodles are rotating up the share rankings.
Distribution Channel:
Application context shapes procurement scale and replenishment frequency across institutional versus consumer endpoints.
- Supermarkets:Slotting fee structures favor established brands with refrigerated supply chain scale, capturing repeat pantry stocking in South Korean urban corridors and European retail networks.
- Online Retailers:Subscription-based bulk formats reduce customer acquisition costs versus physical retail, concentrating among fitness-oriented households seeking protein-fortified multi-packs.
- Health Stores:Heirloom rice varietals and clean-label positioning command premium shelf placement in North American natural products channels.
- Specialty Stores:Asian grocery networks anchor authentic format distribution for immigrant diaspora demand.
Supermarkets anchor volume throughput. Online retailers are climbing the fastest on repeat purchase automation.
End User:
Customer type determines batch size requirements and specification stringency across consumption occasions.
- Households:Single-serve fortified formats concentrate in Seoul and Busan convenience store networks, with South Korean urban retail corridors supporting premium positioning.
- Restaurants:Quick-service chains across Southeast Asia generate institutional-scale procurement contracts for instant-format vegan noodles.
- Cafes:Health-forward menu integration drives ambient bulk purchasing for broth-based applications.
- Food Services:Contract catering demands standardized portion control with extended ambient shelf stability.
Households anchor unit volume. Restaurants are rotating up the share rankings on QSR plant-based menu expansion.
Packaging Type:
Volume scale and sustainability positioning split procurement decisions across retail and institutional buyers.
- Bulk Packaging:Food service and subscription channels favor multi-kilogram formats with reduced per-unit material costs.
- Retail Packaging:Single-serve and family-size SKUs dominate supermarket shelf placement with barcode traceability for inventory management.
- Eco-friendly Packaging:EU Green Deal compliance pressures are accelerating compostable film adoption for European export qualification.
- Vacuum Packaging:Oxygen exclusion extends ambient shelf life without chemical preservatives, enabling clean-label positioning in premium segments.
Retail packaging holds installed capacity. Eco-friendly packaging is rotating up the share rankings on regulatory compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA nutrition claims standards and EU Green Deal carbon disclosure mandates anchor European demand, while Southeast Asian processing infrastructure and East Asian retail innovation shape supply-side dynamics across the forecast window.
Germany
Retail chains in Berlin and Munich drive certified sustainable sourcing requirements for imported rice noodles. The EU Green Deal's carbon footprint disclosure rules compel Thai and Vietnamese processors to submit batch-level traceability documentation. Frankfurt's logistics corridor hosts cold-chain distribution hubs serving Central European markets.
United States
Fitness-oriented households in Los Angeles and New York Metro accelerate chickpea noodle adoption through subscription bulk channels. FDA allergen labeling mandates enforce clear egg-free declarations on all plant-based pasta imports. Chicago's food service distribution network anchors institutional procurement for restaurant chains.
South Korea
Seoul and Busan convenience store networks concentrate demand for single-serve fortified formats. MFDS nutrition labeling standards shape protein content claims on domestic and imported products. Daegu-Gyeongbuk's manufacturing belt hosts extrusion facilities serving both retail and export markets.
Thailand
Bangkok-centered rice noodle processors dominate export infrastructure for ambient and instant formats. The country's national food regulator enforces hygiene standards for legume starch facilities targeting European qualification. Chonburi's industrial zone clusters extrusion capacity serving QSR procurement contracts.
Japan
Tokyo and Osaka retail networks sustain premium positioning for buckwheat soba and clean-label fresh formats. METI's sustainability guidelines pressure processors to adopt carbon accounting for supply chain disclosure. Nagoya's food technology corridor hosts R&D facilities advancing high-pressure processing systems.
Vegan Noodles Market Competitive Landscape
Multinational packaged food conglomerates and specialized plant-based innovators split the market along refrigerated supply chain scale versus clean-label positioning vectors. Nestlé S.A. and Nissin Foods Holdings anchor consolidated retail placement through existing distribution infrastructure, while mid-scale specialists concentrate on heirloom ingredient differentiation. Three archetypes dominate: diversified food conglomerates leveraging refrigerated networks, instant-format specialists driving R&D intensity, and heritage-grain purveyors commanding premium health-store positioning. Competitive moves center on sustainable sourcing certification investments and high-pressure processing technology licensing for fresh format shelf-life extension.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever occupy positions defined by refrigerated supply chain reach and European retail slotting leverage. Nissin Foods Holdings exemplifies the instant-format specialist archetype through concentrated R&D in low-moisture extrusion. Lotus Foods and Dr. McDougall's Right Foods sit within the heritage-grain premium tier, representing positioning built on heirloom varietal sourcing and clean-label transparency rather than scale economics.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Nissin Foods Holdings |
| Unilever |
| Annie Chun's |
| Lotus Foods |
| Dr. McDougall's Right Foods |
| Master Kong |
| Uni-President |
| Explore Cuisine |
| Others |
Value Network & Pricing Analysis
Bangkok-centered rice noodle processors wield disproportionate pricing power over European retail channels, as EU Green Deal carbon disclosure mandates compress margins for uncertified competitors while rewarding early adopters with preferential shelf placement. Input cost volatility in Indian legume markets and refrigerated supply chain capex intensity further stratify price tiers across the value chain.
Pricing Analysis
Geographic price spreads between Southeast Asian export hubs and European retail terminals reflect certification premiums and cold-chain logistics differentials. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-certified sustainable lines from conventional rice noodles and protein-fortified chickpea formats. Price differentiation rests on certification grade and volume scale, with institutional QSR contracts commanding discounts unavailable to subscription-channel households. Pricing pressure stems from Indian monsoon-driven legume input volatility, squeezing margin stability for protein-fortified product lines. Fitness-oriented North American households show lowest price sensitivity, while Southeast Asian QSR procurement teams negotiate aggressively on bulk instant-format contracts.
Supply Chain Analysis
EU Green Deal carbon footprint disclosure rules function as de facto export controls, restricting market access for Thai and Vietnamese processors lacking batch-level traceability documentation. Geographic supply concentrates in Thailand, Vietnam, and India, with raw material dependencies on milled rice flour, chickpea and mung bean starches, and egg-free binding agents. Single-source vulnerability pervades the Thai-Vietnamese rice noodle processing infrastructure, where monsoon disruptions or regulatory enforcement actions propagate rapidly through global distribution. Distribution runs through refrigerated logistics corridors serving European retail networks and ambient bulk channels anchoring North American subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan noodle market fragmentation creates multiple viable positioning arcs, as protein fortification technology and clean-label certification standards splinter demand across incompatible buyer archetypes. Subscription automation and QSR procurement centralization are accelerating niche specialization faster than scale economics can consolidate share.
For Market Incumbents: Pre-empt emerging chickpea noodle specialists by securing backward integration into Indian legume sourcing corridors before monsoon volatility hardens into structural cost disadvantage. Accelerate high-pressure processing technology licensing to extend fresh format shelf life without chemical preservatives, defending refrigerated placement against ambient-format insurgents. Nestlé S.A.'s European retail slotting leverage and Nissin Foods Holdings' instant-format R&D intensity exemplify defensible moats requiring replication.
For New Entrants and Emerging Players: Establish a beachhead in South Korea's urban retail corridors, where Seoul and Busan convenience store networks concentrate demand for single-serve fortified formats with limited incumbent saturation. Target health-store channels in North American metropolitan markets with heirloom rice varietal differentiation, exploiting Lotus Foods' premium positioning without replicating its supply chain scale. Direct-to-consumer subscription automation reduces customer acquisition costs versus supermarket slotting fees, enabling viable entry below incumbent radar.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage-grain specialists with clean-label transparency and established supplier audit protocols over diversified conglomerates facing refrigerated supply chain capex intensity. Long-term viability across the projection horizon hinges on sustainable sourcing certification investments and extrusion technician capability retention. Acquisition target archetype: mid-scale processors with EU Green Deal-compliant supplier relationships and installed high-pressure processing capacity. The signal to watch is EFSA nutrition claims enforcement tightening, which would accelerate consolidation around pre-certified assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Sourcing Certification | EU Green Deal compliance unlocks preferential retail placement in German and French supermarket chains. |
| High-Pressure Processing Adoption | Virtualizes thermal pasteurization for South Korean and Japanese fresh format shelf-life extension. |
| Direct-to-Consumer Channel Launch | Subscription automation captures repeat fitness-oriented households seeking protein-fortified bulk formats. |
| Backward Integration into Legume Supply | Captive sourcing from Indian processing regions insulates margin stability against monsoon price spikes. |
| Extrusion Technician Training Programs | Specialized low-moisture legume starch knowledge commands wage premiums that inflate facility operating costs. |
Research Methodology
Desk research of trade flow databases, regulatory filing repositories, and food technology patent landscapes preceded structured interviews with extrusion facility managers, European retail category buyers, Southeast Asian QSR procurement directors, and cold-chain logistics operators. Secondary validation drew from customs records, EFSA guidance documents, and industry association capacity surveys. Bottom-up facility capacity modeling triangulated against top-down retail channel value capture estimates.
Forecast assumptions held fixed the EU Green Deal carbon disclosure enforcement timeline and Indian monsoon pattern distributions, while varying protein fortification technology adoption curves and subscription channel penetration rates across the analysis window. Segmentation dimensions modeled include product format, distribution channel, end-user type, and packaging configuration, with regional regulatory clusters treated as distinct demand environments. CAGRs derived from fitted growth curves anchored to disclosed capacity expansion announcements and retail placement velocity indicators.
Macroeconomic conditions sit as an overlay; deviation in Indian legume commodity prices, EU carbon border adjustment implementation speed, or refrigerated logistics fuel costs would shift the trajectory. Material shifts in EFSA nutrition claims enforcement or FSSAI plant-based categorization thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Germany Soy Protein Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Plant-Based Sausages Market