
 India Plant Based Milk Market | 2026-2036
India Plant Based Milk Market Size, Share, and Industry Trends Forecast 2026-2036
India Plant Based Milk Market Insights
Buyer concentration across Indian retail is restructuring as organized modern trade and quick-commerce platforms absorb volume once scattered through kirana networks. Dabur India Ltd. leverages its Ayurveda-rooted brand trust to anchor shelf presence in traditional and modern channels alike. Nestle S.A. competes through manufacturing scale and cold-chain infrastructure that sustains consistent product availability in tier-one cities. ProSoya Foods specializes in soya-based formulations, occupying a defensible niche in institutional supply to food manufacturers seeking cost-stable dairy alternatives.
India plant based milk denotes aqueous extracts from oilseeds, cereals, or nuts formulated to emulate the functional and sensory properties of bovine milk, typically standardized to protein contents between one and four percent and homogenized for suspension stability; its primary commercial purpose serves lactose-intolerant consumers, vegan dietary adherents, and foodservice operators requiring stable foaming and emulsification performance. Almond milk leads the product type landscape on perceived premium positioning, while oat milk represents the fastest-growing format as barista-grade formulations gain traction in café channels. The price tier dimension stratifies sharply, with organic and premium labels capturing disproportionate margin pools relative to their volume share.
FSSAI governs compositional standards and additive permissions for plant-based beverages, while BIS certification requirements shape quality benchmarks for imported ingredient streams. The PLI scheme for food processing indirectly incentivizes domestic capacity expansion in extrusion and enzymatic hydrolysis infrastructure. Stakeholders must monitor how regulatory clarity on dairy-alternative nomenclature intersects with evolving consumer litigation risk around nutritional equivalence claims.
Market Dynamics
FSSAI's evolving nomenclature standards for plant-based beverages are forcing immediate reformulation across the India plant based milk sector, compressing product development cycles and reshaping how manufacturers communicate nutritional equivalence to consumers.
Growth Catalysts
- Lactose Intolerance Prevalence:Rising diagnosed cases among urban Indian populations are pulling consumers toward almond and oat milk alternatives as functional substitutes in daily consumption routines.
- PLI Scheme Incentives:India's food processing infrastructure subsidies are accelerating domestic extrusion and enzymatic hydrolysis capacity expansion, reducing import dependency for critical ingredient streams.
- Café Channel Expansion:Barista-grade oat milk formulations are capturing dedicated menu placements across Mumbai, Delhi, and Bangalore coffee chains, creating habitual trial among millennial demographics.
Market Restraints
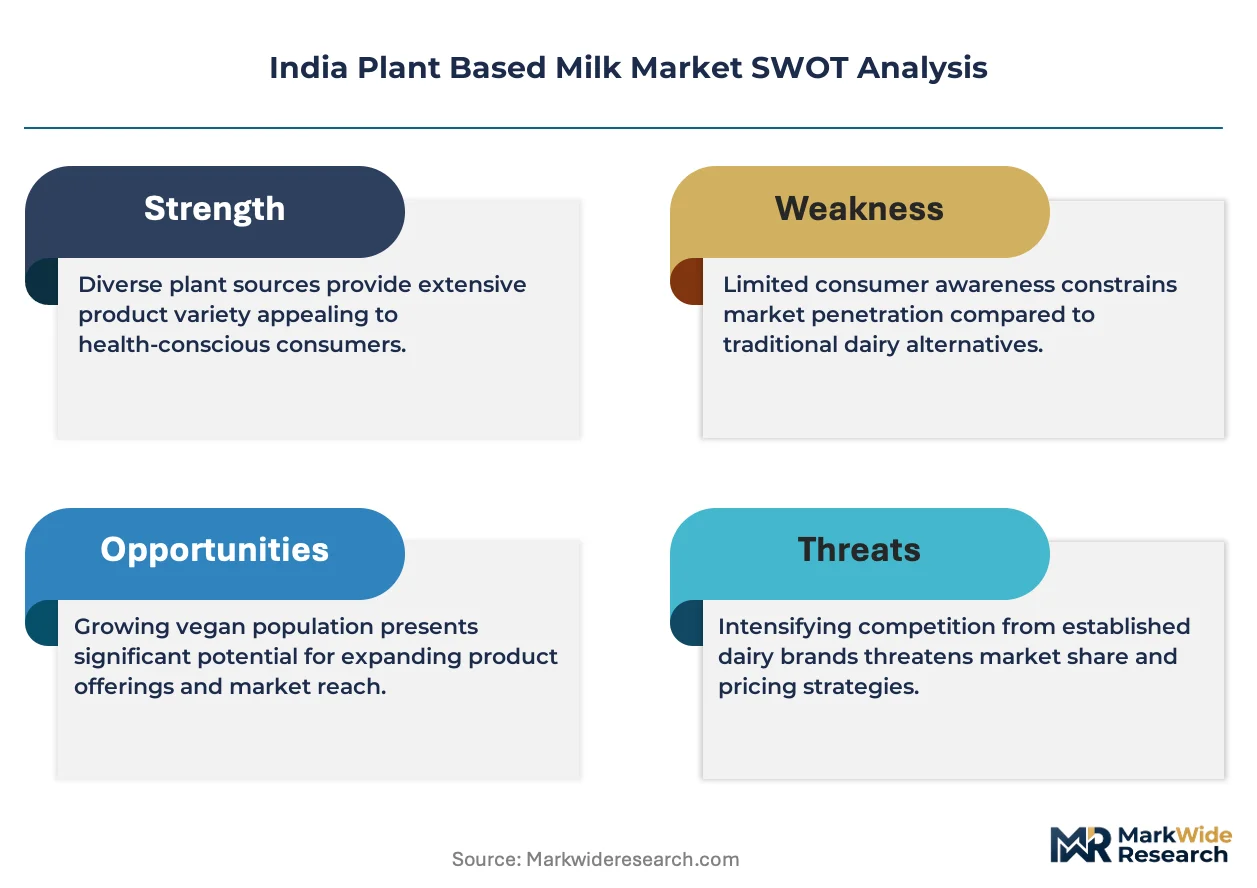
- Almond Input Cost Volatility:California drought cycles and rupee-dollar exchange fluctuations are destabilizing landed costs for premium nut milk raw materials, squeezing margin pools at the top tier.
- Domestic Soya Concentration:ProSoya Foods and limited institutional suppliers control bulk soya protein isolate availability, creating bottleneck risk for mid-market brands dependent on cost-stable formulations.
- FSSAI Labeling Friction:Pending clarity on "milk" terminology restrictions is freezing new product launches and forcing defensive label redesigns ahead of enforcement timelines.
Strategic Opportunities
- Tier-Two Urban Penetration:Pune, Hyderabad, and Chennai present underdeveloped modern trade and quick-commerce infrastructure for plant-based beverage distribution relative to saturated Mumbai-Delhi corridors.
- Foodservice Bulk Supply:Institutional bakeries and ice cream manufacturers represent emerging volume accounts seeking stable dairy alternatives with consistent foaming performance.
- Organic Certification Tailwinds:India Organic and NPOP accreditation pathways are opening premium export channels to European markets with aligned regulatory recognition under EU equivalence agreements.
Industry Challenges
- Enzymatic Process Talent Scarcity:Formulation chemists with expertise in oat beta-glucan stabilization and protein suspension engineering command premium compensation, constraining R&D scaling.
- Cold-Chain Capex Burden:UHT alternatives require substantial retort infrastructure investment, while chilled formats demand refrigerated logistics networks that fragment working capital across temperature zones.
- BIS Import Certification Delays:Bureau of Indian Standards testing backlogs for foreign ingredient streams are extending procurement lead times and forcing safety stock accumulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plant Based Milk Market |
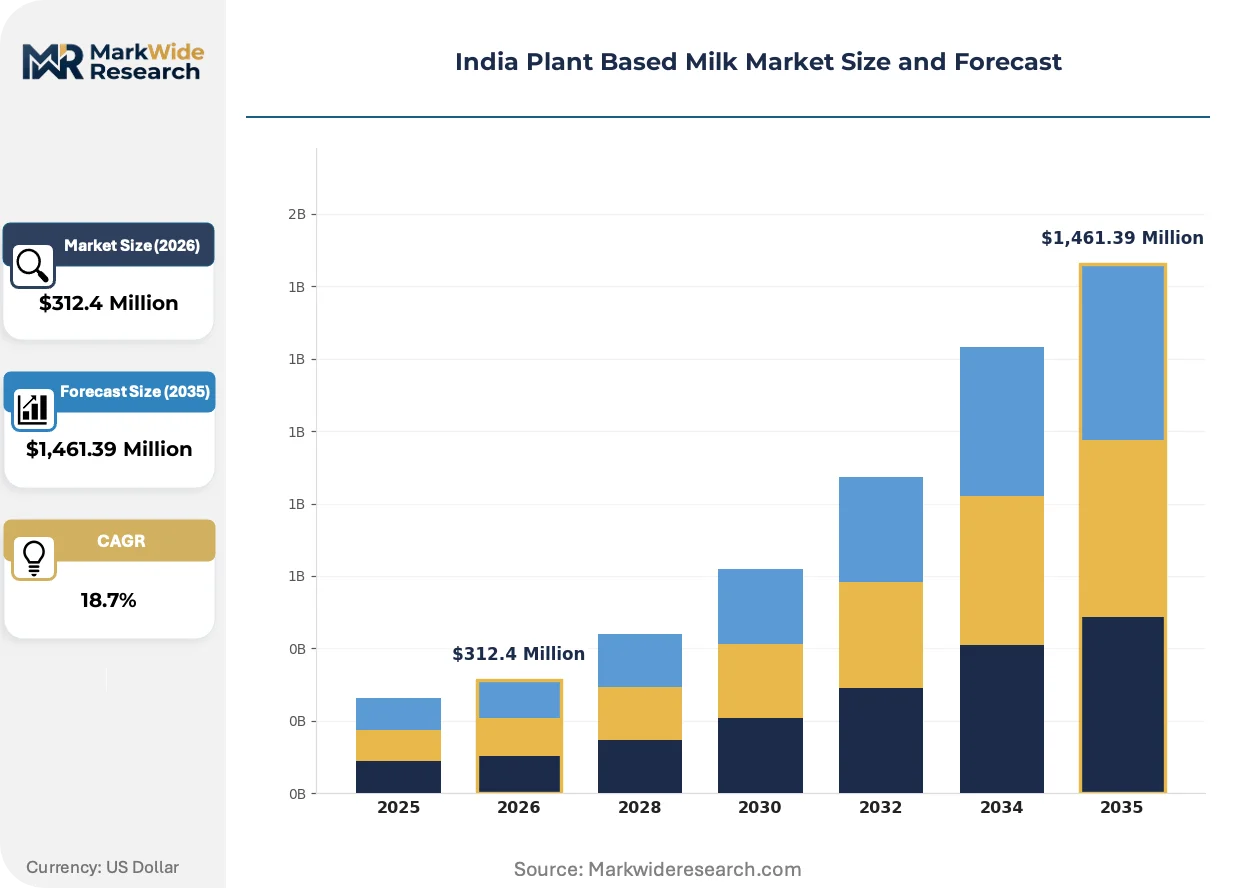
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Almond Milk, Coconut Milk, Oat Milk Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores End User: Households, Cafés, Restaurants, Food Manufacturers Price Tier: Premium, Mid-Range, Economy, Organic |
| Companies Covered | Danone S.A., Blue Diamond Growers, Dabur India Ltd., The Hershey Company, Life Health Foods, Nestle S.A., ProSoya Foods, Raw Pressery, Epigamia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plant Based Milk Market Trends and Innovations
Technological convergence between enzymatic processing and precision fermentation is compressing formulation development timelines, while regulatory pressure and channel fragmentation are simultaneously reshaping how plant-based milk reaches Indian consumers.
High-pressure processing (HPP) systems are automating microbial load reduction without thermal degradation, preserving sensory profiles in oat and almond bases. Premium domestic brands are adopting HPP lines at pilot scale, enabling clean-label positioning that bypasses traditional preservative dependencies. This automation is compressing the gap between artisanal freshness claims and industrial shelf stability.
FSSAI's draft notification on plant-based beverage standards is mandating minimum protein disclosure thresholds and restricting dairy-analogous imagery on packaging. Manufacturers are responding with reformulated blends incorporating pea protein isolates to hit compositional benchmarks. The regulatory shift most acutely affects almond-dominant SKUs with naturally lower protein content, forcing portfolio rebalancing toward blended formats.
Quick-commerce platforms are disintermediating traditional kirana and modern trade stocking patterns for plant-based milk in metropolitan India. Swiggy Instamart and Blinkit are capturing trial-driven purchase occasions through 10-minute delivery promises, compressing consumer consideration cycles. This channel pivot is most pronounced in Bangalore and Mumbai, where subscription-based reordering is displacing monthly grocery stock-up behavior.
India Plant Based Milk Market Segmentation
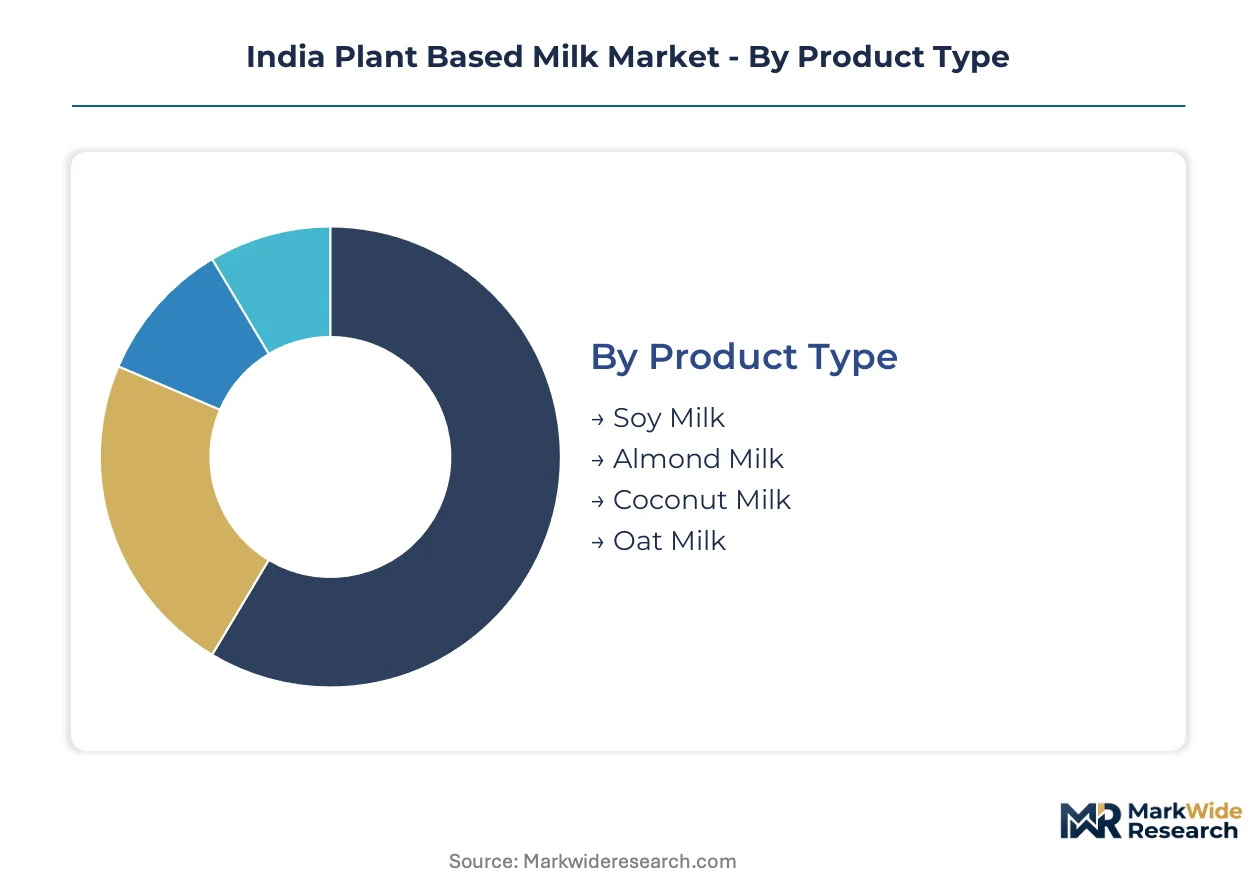
Segmentation in India's plant-based milk sector reveals how supply concentration, channel fragmentation, and price stratification create distinct competitive arenas. Manufacturers must align formulation investments with specific end-use performance requirements and distribution infrastructure capabilities.
Product Type:
Supply concentration in raw ingredient sourcing shapes competitive dynamics across formulation categories, with domestic soya availability contrasting import-dependent nut and cereal bases.
- Soy Milk:Formulated from protein isolates with one to four percent protein standardization, soya-based beverages leverage India's established oilseed processing infrastructure. Maharashtra and Karnataka food manufacturers source bulk volumes for institutional bakery and ice cream applications where cost stability outweighs premium positioning.
- Almond Milk:California-origin nut bases command premium shelf positioning through perceived health associations and clean-label appeal. Mumbai and Delhi modern trade channels absorb the majority of volume despite landed cost volatility from rupee-dollar fluctuations and drought-cycle supply disruptions.
- Coconut Milk:Kerala and Tamil Nadu coastal processing clusters supply traditional culinary applications with established extraction infrastructure.
- Oat Milk:Barista-grade beta-glucan formulations are scaling through enzymatic hydrolysis investments in Bangalore and Pune manufacturing facilities.
Almond milk absorbs the bulk of installed premium capacity; oat milk is expanding most quickly through café channel penetration and domestic production scaling.
Distribution Channel:
Channel economics stratify sharply between temperature-controlled logistics requirements and margin structures, with quick-commerce platforms disrupting traditional kirana and modern trade stocking patterns.
- Supermarkets:Temperature-zone segregation between UHT ambient shelving and refrigerated dairy-alternative sections shapes brand visibility. Dabur and Nestle leverage established modern trade relationships to secure prime placement in Mumbai, Delhi, and Bangalore hypermarket formats.
- Online Retail:Swiggy Instamart and Blinkit capture trial-driven purchase occasions through 10-minute delivery promises, compressing consumer consideration cycles and enabling subscription-based reordering that displaces monthly stock-up behavior.
- Health Food Stores:Curated organic and NPOP-certified SKUs serve concentrated health-conscious demographics in metropolitan clusters.
- Convenience Stores:Limited refrigerated footprint restricts chilled format availability to UHT alternatives with extended ambient stability.
Supermarkets retain the largest share of volume throughput; online retail is climbing the fastest through quick-commerce platform expansion.
End User:
Application-specific performance requirements—foaming stability, emulsification, and protein content—determine formulation specifications and procurement contract structures.
- Households:Daily consumption routines in urban Mumbai, Delhi, and Bangalore drive recurring purchases of one-liter SKUs through modern trade and quick-commerce channels. Lactose intolerance prevalence among diagnosed urban populations pulls sustained demand for almond and oat alternatives as direct dairy substitutes.
- Cafés:Coffee chains across metropolitan India specify barista-grade oat milk with dedicated beta-glucan stabilization for latte art performance and steam-foam consistency.
- Restaurants:Foodservice operators prioritize cost-stable soya formulations for sauce and dessert applications where sensory differentiation matters less.
- Food Manufacturers:Institutional bakeries and ice cream producers represent emerging volume accounts seeking consistent foaming and emulsification performance from bulk soya protein isolates.
Households dominate current volume absorption; food manufacturers are gaining share fastest through industrial dairy-alternative adoption.
Price Tier:
Margin pool distribution inversely correlates with volume concentration, with organic and premium labels capturing disproportionate returns relative to their unit sales.
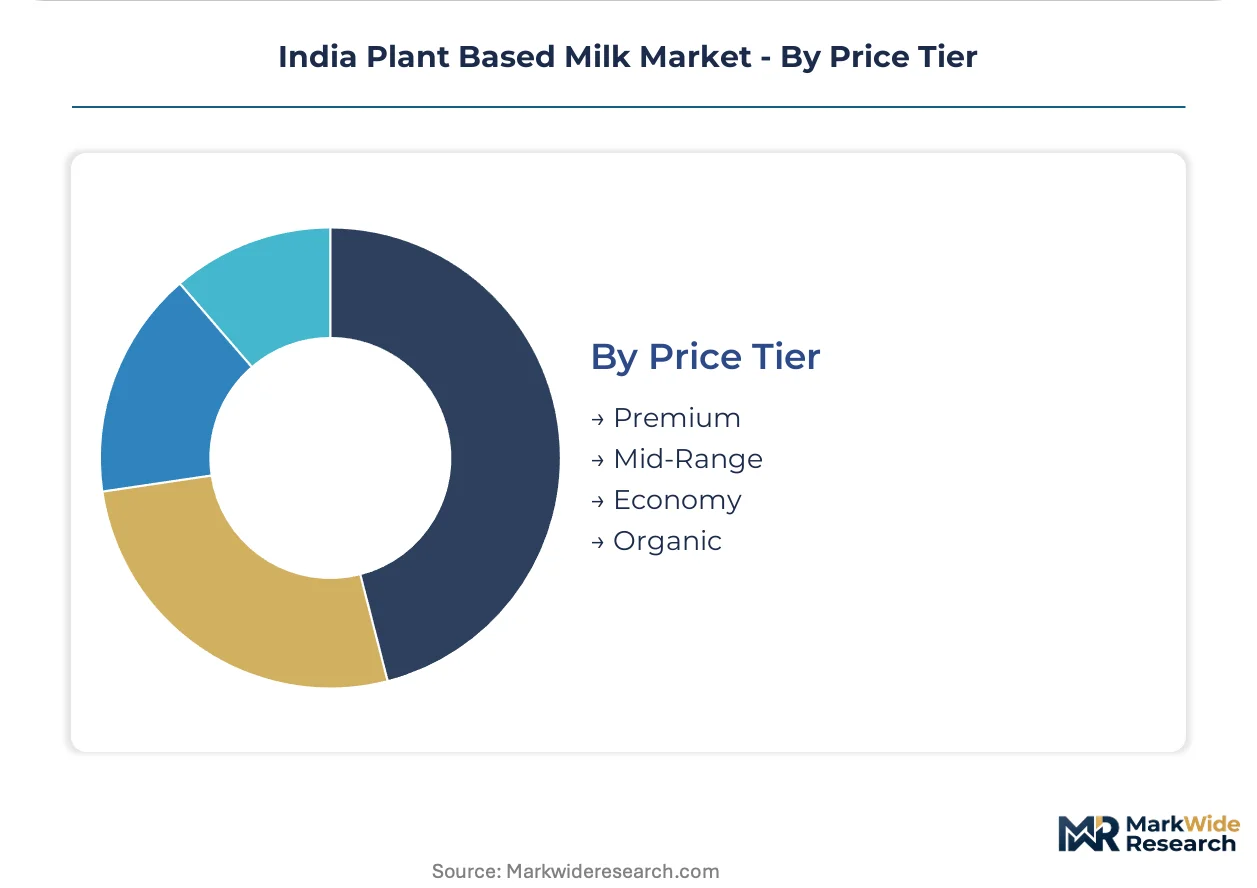
- Premium:Imported almond bases and specialized oat formulations command shelf prices reflecting California sourcing costs and enzymatic processing investments. Urban millennial and Gen Z demographics in Bangalore and Mumbai sustain demand despite significant per-liter premiums over dairy equivalents.
- Mid-Range:Blended formulations incorporating domestic soya with imported nut or cereal bases balance cost stability with sensory performance for mainstream retail penetration.
- Economy:Commodity soya beverages serve price-sensitive institutional and mass-market channels with minimal formulation differentiation.
- Organic:India Organic and NPOP accreditation pathways enable premium export positioning to European markets with aligned regulatory recognition under EU equivalence agreements.
Economy tier absorbs maximum volume throughput; organic certification is expanding most quickly through export channel development and domestic health-conscious segment maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban consumption clusters in Maharashtra, Karnataka, and Delhi-NCR concentrate the bulk of India's plant-based milk demand. Health-conscious millennials and Gen Z demographics drive premium segment uptake through modern trade and quick-commerce channels. State-level food processing policies and metropolitan infrastructure shape regional competitive positioning.
Maharashtra
Mumbai's café culture and organized retail density sustain the highest per-capita consumption of almond and oat milk variants. FSSAI's evolving labeling standards intersect with Maharashtra's food safety enforcement framework, accelerating product reformulation timelines. Pune's emerging manufacturing corridor hosts enzymatic hydrolysis facilities supplying barista-grade oat formulations to western India.
Karnataka
Bangalore's technology workforce sustains premium-priced organic and NPOP-certified plant-based milk adoption through subscription platforms. The state's PLI scheme beneficiaries include domestic extrusion infrastructure investments reducing import dependency. Whitefield and Electronic City industrial zones concentrate pilot-scale HPP processing lines for clean-label oat milk production.
Delhi-NCR
Delhi's quick-commerce penetration exceeds national averages, with Swiggy Instamart and Blinkit capturing trial-driven purchase occasions in under 10 minutes. BIS certification requirements for imported almond bases create procurement friction at the region's distribution hubs. Gurugram's cold-chain logistics parks enable refrigerated format availability across NCR's modern trade network.
Tamil Nadu
Chennai's underdeveloped plant-based milk infrastructure relative to Mumbai-Delhi corridors presents whitespace opportunity for mid-range soya and coconut formulations. The state's coastal processing clusters supply traditional coconut milk extraction for culinary applications. Coimbatore's food manufacturing base represents emerging institutional demand for bulk dairy alternatives in bakery and dessert production.
Telangana
Hyderabad's pharmaceutical and IT workforce generates nascent demand for functional beverages targeting lactose-intolerant professionals. State-level food processing subsidies under Telangana's industrial policy framework incentivize domestic capacity expansion. The city's modern trade footprint remains concentrated in Banjara Hills and HITEC City retail clusters, constraining mass-market penetration.
India Plant Based Milk Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue premium positioning through certification and channel differentiation. Market structure fragments across three operational tiers: multinational FMCG conglomerates with cold-chain infrastructure, domestic Ayurveda-rooted brands leveraging traditional trust, and specialist soya processors serving institutional accounts. Two dominant competitive moves reshape positioning: portfolio diversification into blended protein formats and geographic expansion through quick-commerce platform partnerships.
Within the multinational tier, Danone S.A. and Nestle S.A. exemplify scale-driven market presence through manufacturing infrastructure and distribution reach. Dabur India Ltd. occupies a distinctive position bridging traditional Ayurveda credibility with modern retail penetration. Among specialist processors, ProSoya Foods represents the soya-dominant archetype serving food manufacturers with cost-stable bulk formulations. These three company types—multinational FMCG, domestic heritage brand, and ingredient specialist—collectively illustrate how competitive positioning stratifies across price tiers and channel requirements in India's plant-based milk sector.
| Leading Market Players |
|---|
| Danone S.A. |
| Blue Diamond Growers |
| Dabur India Ltd. |
| The Hershey Company |
| Life Health Foods |
| Nestle S.A. |
| ProSoya Foods |
| Raw Pressery |
| Epigamia |
| Others |
Pricing and Supply Chain Analysis
Quick-commerce platforms and modern trade buyers in Mumbai, Delhi, and Bangalore concentrate procurement volume, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects cold-chain infrastructure access and certification grade rather than commodity dynamics alone.
Pricing Analysis
Volume concentrates in economy-tier soya formulations while margin pools accrue disproportionately to premium almond and organic-certified SKUs. Price differentiation rests on India Organic certification status and barista-grade performance specifications. Cost compression in the premium tier is intensifying because California almond input volatility and rupee-dollar exchange fluctuations squeeze landed costs. Quick-commerce subscribers demonstrate lowest price sensitivity; institutional food manufacturers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Gurugram, Pune, and Whitefield operate hub-and-spoke patterns feeding tier-one metropolitan retail. Raw material sourcing draws from the United States for almond bases, Canada for oat groats, and domestic Maharashtra and Karnataka clusters for soya protein isolates. Single-source vulnerability concentrates in California almond supply exposed to drought-cycle disruption. Distribution runs through temperature-segregated logistics networks separating UHT ambient from chilled refrigerated formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic enzymatic hydrolysis capacity scarcity props pricing power for barista-grade oat formulations, constraining supply response to café channel demand surges.
For Market Incumbents: To counter quick-commerce platform disintermediation of traditional kirana networks, Dabur and Nestle should deepen direct-to-retailer data partnerships while expanding backward integration into domestic oat extrusion infrastructure in Pune and Bangalore manufacturing corridors. For New Entrants and Emerging Players: Begin with Chennai and Hyderabad whitespace where modern trade penetration lags Mumbai-Delhi saturation. Target mid-range blended formulations for institutional bakery accounts in Coimbatore and food manufacturing clusters seeking cost-stable dairy alternatives with consistent foaming performance. For Investors and Strategic Acquirers: The window for entry favors specialist soya processors with captive Maharashtra oilseed supply and NPOP certification pathways. Monitor FSSAI enforcement timelines on plant-based beverage nomenclature as the inflection signal determining portfolio rebalancing urgency toward protein-fortified blended formats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Oat Processing | Pune and Bangalore enzymatic hydrolysis investments reduce California import dependency for barista-grade formulations. |
| NPOP Organic Certification Investment | India Organic accreditation unlocks EU equivalence export channels with premium margin capture. |
| Quick-Commerce Platform Partnership | Swiggy Instamart and Blinkit integration enables 10-minute delivery trial conversion and subscription retention. |
| Blended Protein Format Development | Pea protein isolate incorporation addresses FSSAI minimum protein disclosure thresholds for almond-dominant SKUs. |
| Tier-Two Urban Distribution Expansion | Chennai and Hyderabad modern trade penetration captures underdeveloped demand relative to saturated metropolitan corridors. |
Research Methodology
Independent corroboration across formulation chemists at enzymatic processing facilities, category buyers at quick-commerce platforms, and procurement leads at institutional bakeries underwrites the qualitative findings. Secondary validation draws from FSSAI draft notification records, BIS certification databases, PLI scheme beneficiary disclosures, and customs import data for almond and oat raw material streams. Bottom-up channel volume estimates triangulate against top-down addressable population calculations for lactose-intolerant and vegan dietary adherents.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-use application, and price tier. CAGRs derive from rolling average growth rate analysis applied to channel shipment data and consumer panel adoption curves. Industry-specific forecast inputs incorporate café outlet expansion trajectories and FSSAI regulatory clarity timelines.
Underlying measurement precision varies by segment; quick-commerce and modern trade channels carry tighter precision than kirana network estimates. Forecasts reflect documented assumptions around regulatory enforcement timing and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Global Tofu Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Tempeh Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Rice Protein Market
Plant Based Food
Soy- Based Food Market