
 United Kingdom Tofu Market | 2026-2036
United Kingdom Tofu Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Tofu Market Analytics
The UK Plastic Packaging Tax is restructuring procurement priorities across the tofu supply chain. The Tofoo Co Ltd leverages its Yorkshire manufacturing base to sustain domestic sourcing credibility. Monde Nissin Corp. (Marlow Foods Limited) anchors the category through its Quorn-tofu hybrid portfolio in major retail multiples. Clearspring Ltd differentiates via organic certification and Japanese import heritage in premium channels.
Tofu denotes a protein-rich curd produced by coagulating soymilk—typically with calcium sulfate or nigari—then pressing the resulting curd to varying densities ranging from silken to extra-firm. The coagulant choice and pressing duration determine moisture content, protein density, and culinary application suitability. Firm Tofu dominates volume through its versatility in stir-fry and grilling applications across restaurant and household segments. Silken Tofu occupies expanding margin pools in dessert formulations and smoothie applications where texture premiumization commands price separation. Smoked Tofu leads specialty store velocity as flavor-forward positioning attracts flexitarian trial.
The Food Standards Agency enforces allergen labeling and novel protein safety standards that shape product claims and import clearance protocols. The Competition and Markets Authority monitors retail pricing conduct in plant-based categories as shelf-space allocation intensifies. HMRC's Plastic Packaging Tax directly increases cost exposure for tray-packed and vacuum-sealed formats. Stakeholders must monitor enforcement patterns around front-of-pack nutritional scoring and prepare for potential extension of Extended Producer Responsibility fees into food-contact materials.
Market Dynamics
HMRC's Plastic Packaging Tax is compressing margins for tray-packed formats while redirecting capital toward flow-wrap and bulk retail configurations. This fiscal pressure intersects with the Food Standards Agency's tightening allergen protocols to reshape formulation and packaging investment priorities simultaneously.
Growth Catalysts
- Front-of-pack labeling mandates:The UK's nutritional scoring regulations are accelerating clean-label reformulation. Manufacturers stripping back ingredient decks to secure favorable traffic-light ratings.
- Metropolitan restaurant procurement:London's independent dining sector is expanding center-plate tofu applications beyond traditional Asian cuisine. Chefs in Manchester and Bristol are driving volume through menu innovation.
- Soy protein concentrate imports:Yorkshire processing infrastructure is capturing value from EU-origin raw material flows. Domestic coagulation and pressing capacity reduces lead times to English retail multiples.
Market Restraints
- Soybean price volatility:Ukrainian sunflower oil disruptions have tightened EU crushing margins. UK manufacturers face input cost spikes with limited pass-through elasticity in supermarket price architecture.
- Single-region production concentration:Yorkshire hosts the majority of domestic pressing capacity. Flooding or energy grid stress in this corridor would cascade through national availability.
- Calcium-set texture limitations:Nigari coagulation delivers superior mouthfeel but requires import dependency on Japanese magnesium chloride. Domestic sulfate alternatives constrain premium positioning.
Strategic Opportunities
- Scottish retail corridor expansion:Edinburgh and Glasgow health food networks remain underpenetrated relative to English density. Specialist independents in these cities show stronger margin tolerance than national multiples.
- Extended Producer Responsibility extension:Pending DEFRA consultations on food-contact material fees will favor early movers with compostable film capabilities. First-movers capture shelf-space reallocation.
- Fermentation hybridization:Mycoprotein-tofu blended formats are rewriting texture expectations in flexitarian segments. Co-development with fungal protein suppliers opens patentable formulation space.
Industry Challenges
- Coagulation chemistry expertise scarcity:Traditional tofu craftsmanship resides in aging workforce cohorts. Yorkshire technical colleges lack dedicated plant-protein processing curricula.
- Organic certification timelines:Soil Association audits for imported soy extend lead times by eight to fourteen months. Working capital intensity rises before premium pricing activates.
- Cold-chain reconfiguration costs:Refrigerated last-mile capacity for chilled tofu blocks requires fleet investment. Third-party logistics providers are consolidating routes, reducing frequency to secondary retail locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Tofu Market |
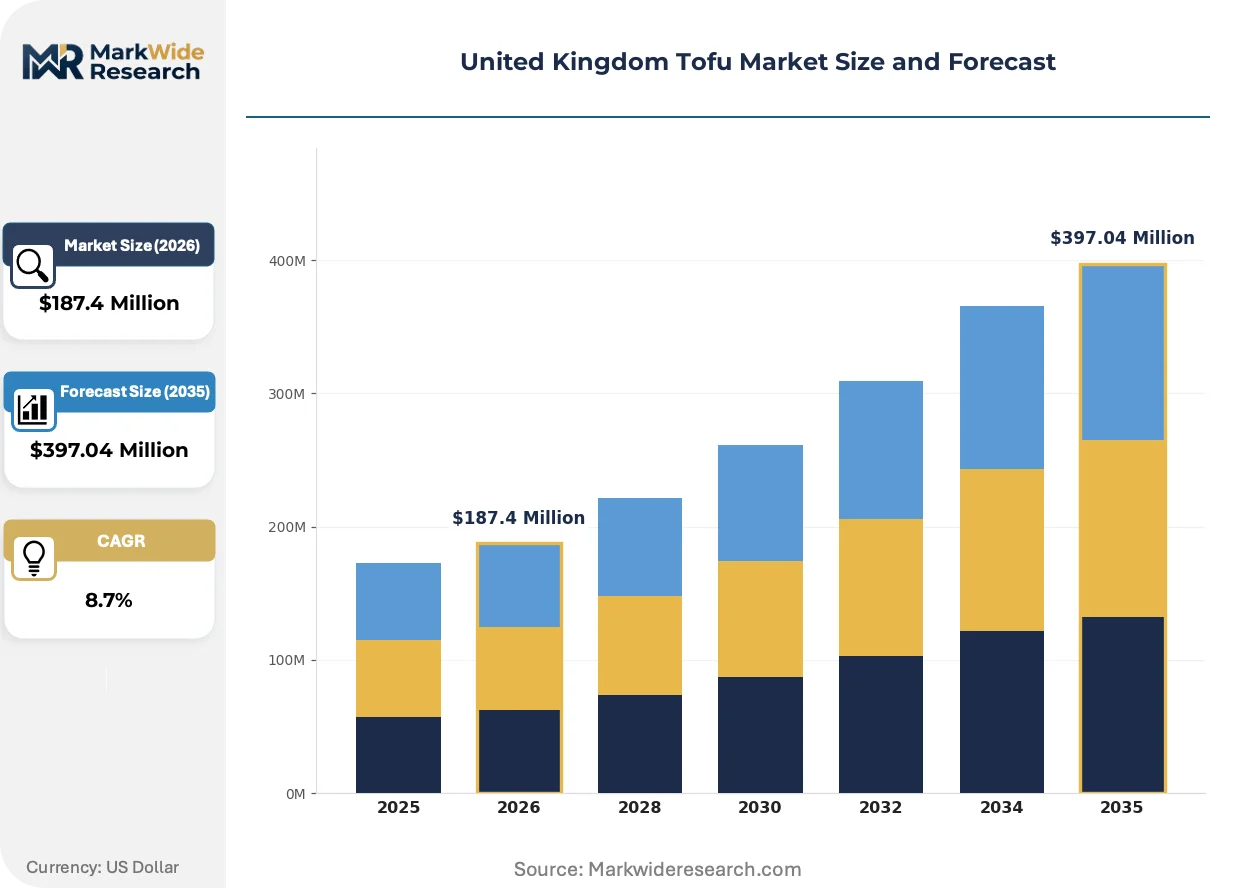
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Tofu, Soft Tofu, Silken Tofu, Smoked Tofu End User: Restaurants, Retail Chains, Health Food Stores, Households Packaging Type: Plastic Tray, Vacuum Pack, Bulk Packaging, Canned Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Farmers Markets |
| Companies Covered | The Tofoo Co Ltd, Monde Nissin Corp. (Marlow Foods Limited), Clearspring Ltd, Taifun-Tofu GmbH, Associated British Foods (AB World Foods Limited), Cauldron Foods, Kikkoman Corp., Yutaka, Morinaga Milk Industry Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Tofu Market Evolving Landscape
High-pressure processing is rewriting spoilage timelines while clean-label fermentation is displacing chemical preservatives. These technologies intersect with regulatory tightening to accelerate premium tier bifurcation.
High-pressure processing is rewriting shelf-life economics for silken and firm formats alike. Waitrose and Ocado chilled ranges are adopting HPP-treated blocks to secure fourteen-day code dates. This compression of spoilage risk is enabling direct-to-retailer distribution models that bypass traditional wholesaler markups.
The Food Standards Agency's novel protein consultation framework is tightening safety dossier requirements for fermented soy derivatives. Manufacturers must demonstrate compositional equivalence to traditional coagulation methods. Smoked and flavored specialty lines face the steepest compliance burden as additive and process innovation outpaces guidance issuance.
Flexitarian households are rotating protein procurement toward subscription box channels. Abel & Cole and Riverford organic deliveries are displacing supermarket tofu purchases in southern England commuter belts. This channel shift concentrates demand in higher-margin branded formats while private-label supermarket blocks face volume pressure.
United Kingdom Tofu Market Segmentation
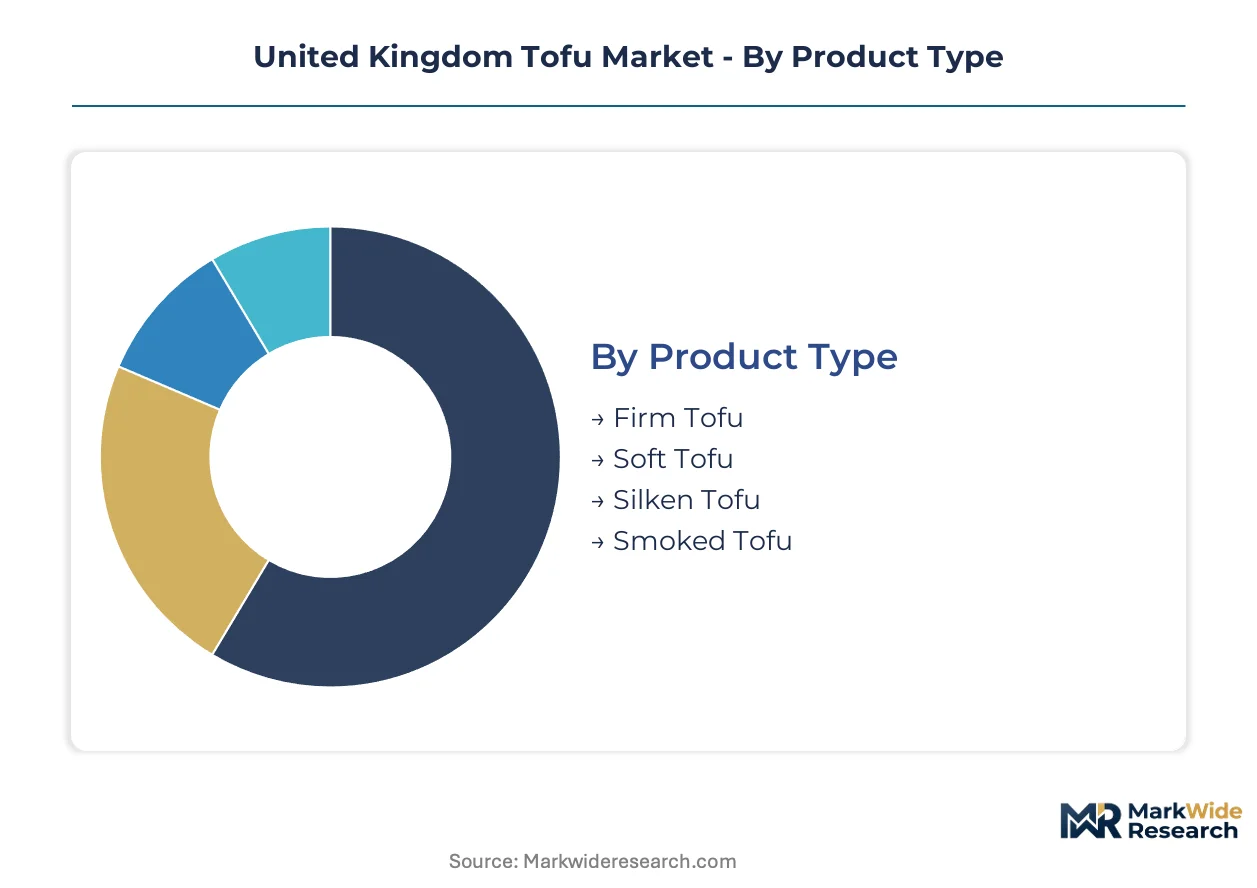
Tofu demand fragments across protein application contexts rather than unified consumer segments. Manufacturers configure pressing density, coagulant chemistry, and packaging format around specific channel requirements rather than pursuing horizontal scale.
Product Type:
Yorkshire pressing facilities concentrate capacity around density-calibrated output, with coagulant selection and duration determining moisture retention and culinary application suitability.
- Firm Tofu:High-protein curd pressed to 70-80% moisture extraction delivers structural integrity for stir-fry and grilling applications. London's independent restaurant sector drives procurement volume through center-plate positioning in non-Asian cuisine formats.
- Silken Tofu:Minimal pressing preserves custard-like texture ideal for dessert formulations and smoothie integration. Premium pricing activates in southern England commuter belts where Abel & Cole and Riverford subscription channels displace supermarket purchases.
- Soft Tofu:Intermediate moisture content suits soup and stew applications with moderate structural demands.
- Smoked Tofu:Flavor-forward positioning through beechwood or liquid smoke infusion attracts flexitarian trial in specialty retail.
Today's leader: Firm Tofu. Tomorrow's challenger: Silken Tofu.
End User:
Procurement patterns diverge sharply between foodservice specification requirements and retail velocity constraints.
- Restaurants:Menu innovation in Manchester and Bristol expands center-plate applications beyond traditional Asian cuisine. Chef-driven procurement favors consistent block dimensions and neutral flavor profiles for sauce integration.
- Retail Chains:Major multiples demand fourteen-day chilled code dates achievable through high-pressure processing adoption. Waitrose and Ocado ranges are bypassing traditional wholesaler markups via direct distribution.
- Health Food Stores:Edinburgh and Glasgow networks show stronger margin tolerance than national multiples, with organic certification commanding shelf-space priority.
- Households:Flexitarian rotation patterns concentrate protein procurement in branded formats with transparent ingredient decks.
Restaurants anchor current volume. Health food stores are climbing the fastest.
Packaging Type:
HMRC's Plastic Packaging Tax is compressing margin structures and redirecting capital toward alternative configurations.
- Plastic Tray:Rigid format dominates supermarket chilled aisles but faces direct tax exposure. Manufacturers stripping back tray specifications to reduce polymer weight per unit.
- Vacuum Pack:Film-based configuration reduces plastic content while extending shelf life through oxygen exclusion. Early movers with compostable film capabilities capture shelf-space reallocation pending DEFRA consultations.
- Bulk Packaging:Foodservice-oriented formats bypass retail packaging tax exposure but require cold-chain reconfiguration for last-mile delivery.
- Canned:Ambient-stable format occupies niche positioning in ethnic grocery channels with limited UK manufacturing presence.
Vacuum pack is gaining share fastest. Plastic tray faces structural decline.
Distribution Channel:
Channel fragmentation reflects divergent consumer convenience preferences and certification transparency demands.
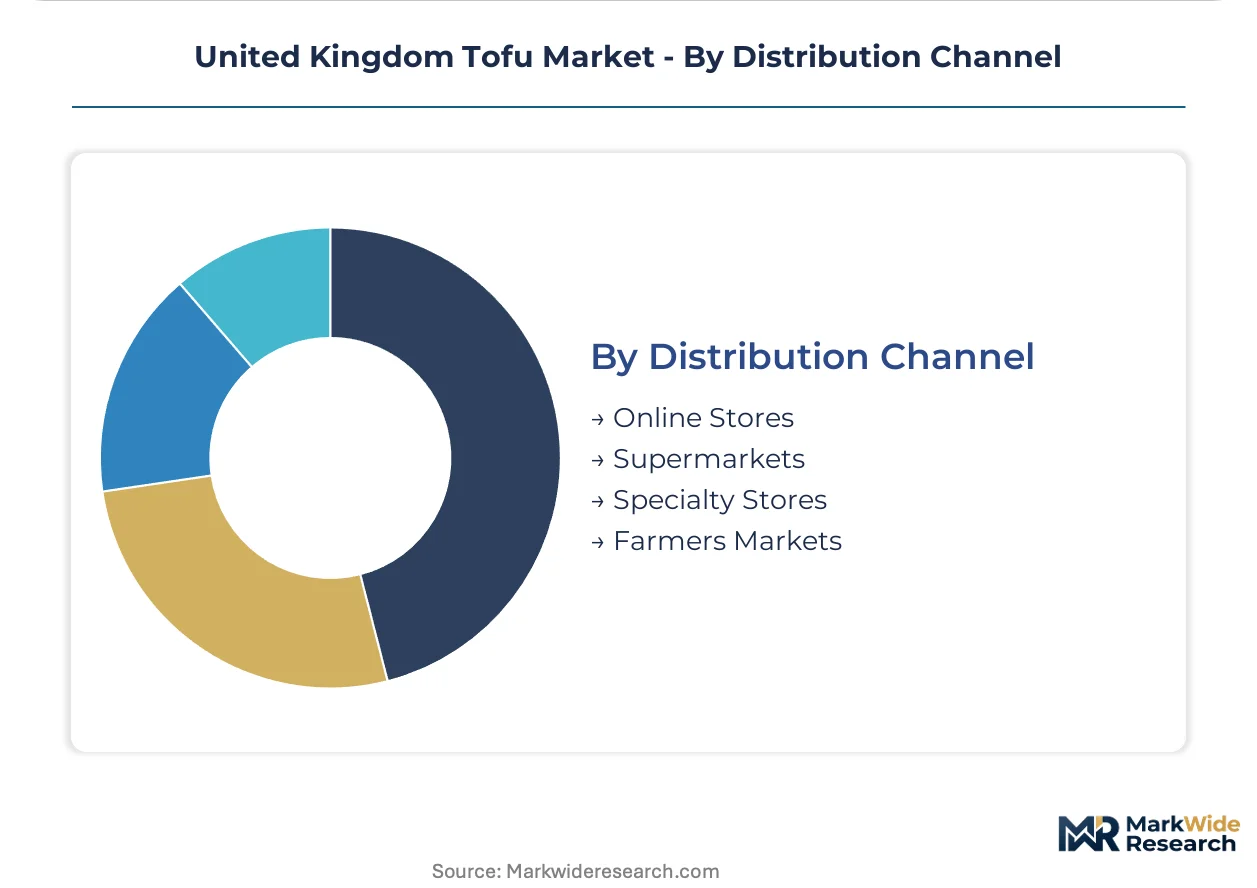
- Online Stores:Subscription box concentration in southern England enables higher-margin branded format penetration. Direct-to-consumer models bypass wholesaler markups but require refrigerated fleet investment.
- Supermarkets:National multiples enforce traffic-light labeling compliance and squeeze private-label pricing architecture. Front-of-pack nutritional scoring mandates accelerate clean-label reformulation.
- Specialty Stores:Japanese import heritage and organic certification differentiate positioning in premium channels. Clearspring Ltd leverages this route for margin separation.
- Farmers Markets:Local production claims activate in Yorkshire corridor with domestic sourcing credibility.
Supermarkets dominate volume. Online stores show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tofu production in Britain traces its commercial roots to post-war Asian migration patterns that established soy processing in Yorkshire during the 1970s. This northern corridor remains the dominant manufacturing cluster today.
London and the Southeast
Restaurant procurement concentrates in Shoreditch, Soho, and Brixton markets where independent chefs deploy center-plate tofu applications. The Food Standards Agency enforces allergen labeling protocols that shape menu disclosure requirements. Waitrose and Ocado chilled distribution hubs in Enfield bypass traditional wholesaler networks through direct-to-retailer models.
Yorkshire and the Humber
Domestic pressing capacity clusters around Leeds and Sheffield with coagulation infrastructure serving national retail multiples. HMRC's Plastic Packaging Tax compresses margins for tray-packed formats manufactured in this corridor. The Tofoo Co Ltd anchors regional employment and domestic sourcing credibility through its established production base.
Northwest England
Manchester's independent dining sector drives menu innovation beyond traditional Asian cuisine formats. Chef-driven procurement favors consistent block dimensions for sauce integration. Trafford Park distribution infrastructure supports cold-chain reconfiguration for chilled tofu blocks reaching secondary retail locations.
Southwest England
Bristol's flexitarian household concentration rotates protein procurement toward subscription box channels. Abel & Cole and Riverford organic deliveries displace supermarket purchases in commuter belts surrounding the city. Health food store networks in Bath and Exeter show stronger margin tolerance than national multiples.
Scotland
Edinburgh and Glasgow health food networks remain underpenetrated relative to English density. Specialist independents in these cities demonstrate stronger margin tolerance for organic certified formats. Soil Association audit timelines for imported soy extend lead times before premium pricing activates in Scottish channels.
United Kingdom Tofu Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and import heritage dimensions in the UK tofu category. The vendor base organizes into three distinct tiers: domestic manufacturers with Yorkshire production bases, multinational food conglomerates with hybrid protein portfolios, and Japanese import specialists with organic certification positioning. Two dominant competitive moves define current rivalry: direct distribution partnerships with major retail multiples that bypass wholesaler markups, and early investment in compostable film capabilities pending DEFRA Extended Producer Responsibility consultations.
Within the domestic manufacturing tier, The Tofoo Co Ltd represents Yorkshire-based production credibility and domestic sourcing positioning. Monde Nissin Corp. (Marlow Foods Limited) exemplifies multinational scale through its Quorn-tofu hybrid portfolio anchoring major retail multiples. Clearspring Ltd occupies the premium import specialist position through organic certification and Japanese heritage channels.
| Leading Market Players |
|---|
| The Tofoo Co Ltd |
| Monde Nissin Corp. (Marlow Foods Limited) |
| Clearspring Ltd |
| Taifun-Tofu GmbH |
| Associated British Foods (AB World Foods Limited) |
| Cauldron Foods |
| Kikkoman Corp. |
| Yutaka |
| Morinaga Milk Industry Co. Ltd |
| Others |
Value Network & Pricing Analysis
Captive Yorkshire pressing infrastructure anchors both supply security and margin control for domestic manufacturers serving English retail multiples. This backward integration into coagulation and pressing capacity insulates producers from EU import volatility while compressing logistics overhead into pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified Japanese imports from Yorkshire domestic production and private-label supermarket blocks. Price differentiation rests on Soil Association certification status and front-of-pack nutritional scoring compliance. Cost compression in the economy tier is intensifying because HMRC's Plastic Packaging Tax erodes already thin margins on tray-packed formats. Flexitarian households in southern England commuter belts show lowest price sensitivity, while supermarket private-label purchasers remain most elastic.
Supply Chain Analysis
Domestic-content credibility requirements under UK post-EU procurement standards are reshaping sourcing toward Yorkshire coagulation facilities and away from continental pressing partners. Soy protein concentrate draws from EU crushing operations in Germany and the Netherlands, with nigari magnesium chloride tethered to Japanese import channels. Single-region production concentration in Yorkshire presents flood and energy grid vulnerability. Distribution runs through chilled last-mile networks serving Waitrose and Ocado direct-to-retailer models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK tofu tracks compostable packaging substitution and subscription channel premiumization. High-pressure processing adoption compresses spoilage risk while enabling price separation in direct distribution.
For Market Incumbents: Anticipate DEFRA Extended Producer Responsibility extension by securing compostable film capabilities ahead of shelf-space reallocation. Consolidate Yorkshire pressing capacity through equipment upgrades that reduce energy exposure. Defend against mycoprotein-tofu hybrid entrants by patenting fermentation-coagulation formulation space. For New Entrants and Emerging Players: Enter via Edinburgh and Glasgow health food networks where organic certification commands stronger margin tolerance than English multiples. Target Scottish specialist independents with Japanese import heritage positioning. Build go-to-market through Abel & Cole and Riverford subscription channels displacing supermarket purchases in Bristol commuter belts. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Yorkshire manufacturers because domestic sourcing credibility concentrates procurement power with national retail multiples. Five-to-ten year viability hinges on cold-chain infrastructure ownership reducing third-party logistics dependency. Watch HMRC enforcement patterns around Plastic Packaging Tax expansion as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Film Transition | Early movers capture Waitrose and Ocado shelf-space reallocation pending DEFRA consultations. |
| High-Pressure Processing Adoption | HPP-treated blocks secure fourteen-day code dates enabling direct-to-retailer distribution bypass. |
| Scottish Retail Corridor Expansion | Edinburgh and Glasgow health food networks show stronger organic margin tolerance than national multiples. |
| Fermentation Hybridization | Mycoprotein-tofu blends open patentable formulation space in flexitarian segments. |
| Subscription Channel Integration | Abel & Cole and Riverford partnerships concentrate demand in higher-margin branded formats. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant-protein processing directors, category buyers at major retail multiples, supply chain managers at chilled logistics providers, and fermentation R&D leads with secondary validation. Customs records, Nielsen retail audit data, Food Standards Agency enforcement disclosures, and Soil Association certification databases anchored bottom-up volume estimates against top-down market sizing.
Historical reference periods anchored the projection horizon to pre-pandemic baselines and post-EU transition volatility windows. Segmentation modeling spanned product density tiers, coagulant chemistry types, packaging format categories, and distribution channel structures. CAGRs were derived from regression analysis against soybean input cost indices and retail velocity trends. Forecast inputs incorporated HMRC tax policy consultation timelines and DEFRA Extended Producer Responsibility consultation trajectories.
Inputs from retail buyer interviews and logistics provider disclosures were available through the study window; gaps in real-time soybean crushing margin data from EU origins introduce uncertainty bands around input cost assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and subscription channel penetration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Vegan Food Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Rice Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Middle East and Africa Meat Substitute Market