
 Australia Plant Protein Market | 2026-2036
Australia Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Plant Protein Market Outlook
Pea protein isolate is restructuring cost structures across Australian alt-meat and dairy-analogue formulations, displacing costlier whey concentrates in mid-tier product lines. Australian Plant Proteins Pty Ltd anchors domestic output through its Victorian extraction facility, supplying local manufacturers with traceable non-GMO feedstock. Cargill Incorporated leverages global procurement networks to secure competitive pea and canola protein positions in Australian ingredient channels. Kerry Group plc differentiates through integrated taste-modulation systems that mask off-notes in high-concentration plant formulations.
Plant protein encompasses extracted, concentrated, or isolated protein fractions derived from legumes, oilseeds, and cereal grains, typically achieving protein content ranging from 50% to 90% dry weight depending on processing intensity; these ingredients function as functional texturizers, emulsifiers, and nutritional fortifiers across formulated foods. Pea protein leads Australian volume consumption due to its neutral flavour profile and strong water-binding capacity in meat analogues, while hemp protein occupies a premium niche driven by omega-3 positioning and allergen-free claims among health food shops. Rice protein competes in hypoallergenic infant nutrition and sports recovery segments where digestibility scores command formulation priority.
FSANZ governs novel protein ingredient approvals and nutrition content claims, while Food Standards Australia mandates allergen labelling that shapes formulation choices for soy and hemp variants. The ACCC monitors greenwashing enforcement, pressuring brands to substantiate sustainability credentials tied to plant-based positioning. Stakeholders must track emerging protein fractionation technologies and evolving FSANZ guidance on precision-fermented and hybrid protein classifications to anticipate competitive displacement risks.
Market Dynamics
FSANZ novel food approval pathways are compressing time-to-market for precision-fermented and hybrid protein ingredients, forcing domestic manufacturers to accelerate reformulation cycles ahead of import parity shifts.
Growth Catalysts
- Clean-label processing:Australian food and beverage manufacturers are reformulating mid-tier product lines around traceable non-GMO feedstocks to capture health-conscious consumers in New South Wales and Victoria retail corridors.
- FSANZ regulatory clarity:Streamlined novel protein ingredient approvals are reducing commercialization barriers for domestic extraction facilities, enabling faster scale-up of pea and canola protein fractions.
- Manufacturing cluster concentration:Victorian food innovation hubs are anchoring domestic protein R&D through co-located pilot plants and shared fractionation infrastructure.
Market Restraints
- Input cost volatility:Drought-sensitive Australian pulse crop yields are exposing alt-meat formulators to supply disruptions and price spikes in pea protein concentrate feedstock.
- Single-source supply risk:Domestic extraction capacity concentrates in Victorian facilities, creating geographic vulnerability to regional logistics bottlenecks and climate events.
- Technical limitation:Off-note masking in high-concentration hemp protein formulations remains unresolved for infant nutrition applications, constraining premium segment penetration.
Strategic Opportunities
- Queensland underpenetration:Northern Australian food manufacturing corridors lack dedicated plant protein extraction infrastructure, presenting first-mover advantages for regional facility deployment.
- Precision fermentation convergence:Hybrid protein classifications combining extracted plant fractions with microbial biomass are opening regulatory white space ahead of FSANZ guidance finalization.
- Direct-to-manufacturer channels:Bypassing traditional ingredient distributors through captive supply agreements is reducing margin leakage for mid-scale Australian alt-dairy producers.
Industry Challenges
- Fractionation skill scarcity:Australian universities are producing insufficient protein chemists and process engineers to staff expanding extraction facilities in Victoria and New South Wales.
- Clean-label certification timelines:Non-GMO and organic accreditation for imported canola protein is extending procurement cycles by six to nine months, constraining just-in-time formulation.
- Legacy dairy integration:Traditional Australian dairy cooperatives face technical friction retrofitting spray-drying infrastructure for plant protein isolate handling and allergen segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Plant Protein Market |
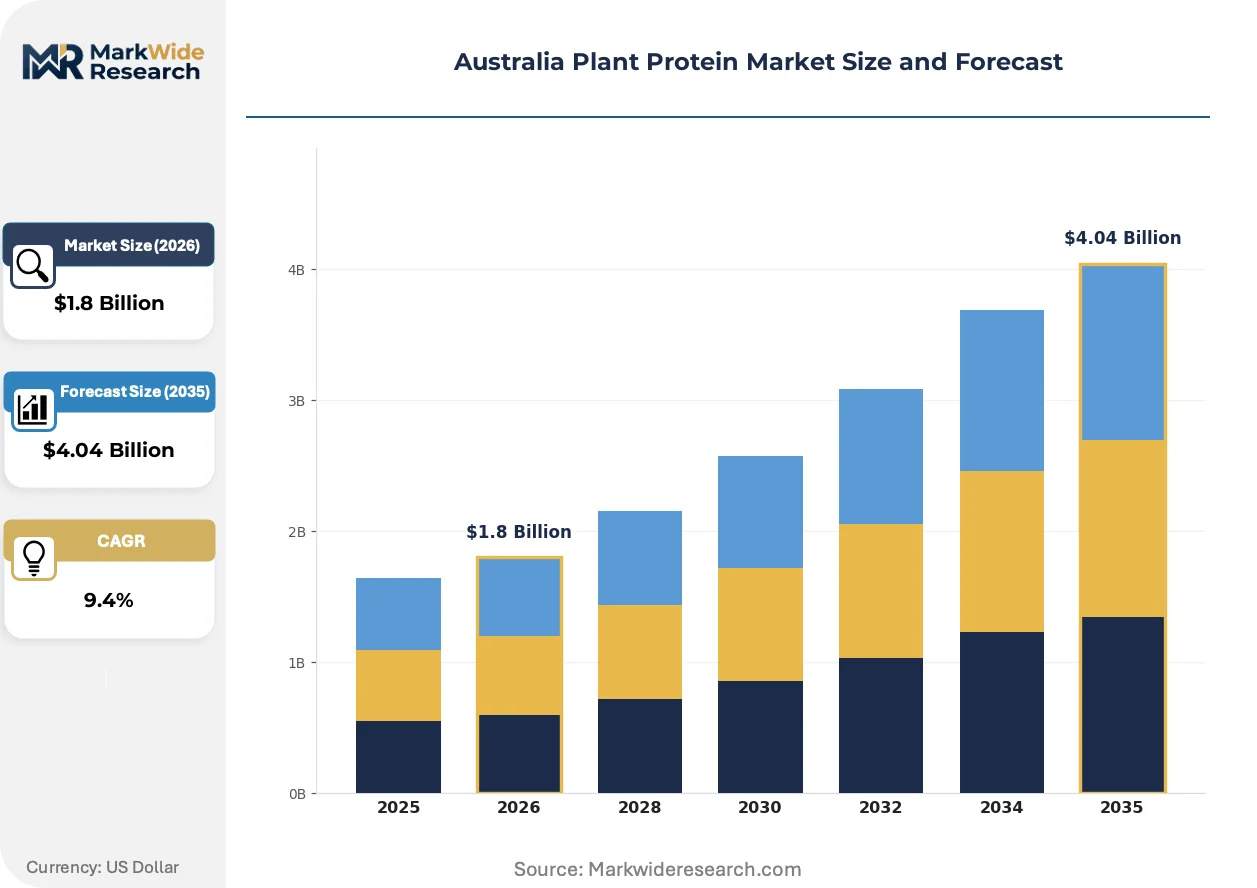
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein Application: Food & Beverages, Nutritional Supplements, Bakery Products, Snacks End User: Health-conscious Consumers, Fitness Enthusiasts, Vegans, Vegetarians Distribution Channel: Online Retail, Grocery Stores, Health Food Shops, Specialty Stores |
| Companies Covered | Kerry Group plc, Givaudan SA, Cargill Incorporated, Australian Plant Proteins Pty Ltd, Bunge Limited, Archer-Daniels-Midland Company, DSM-Firmenich AG, Manildra Group, International Flavors & Fragrances Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Plant Protein Market Strategic Shifts
Membrane filtration and enzyme-assisted extraction are displacing conventional isoelectric precipitation across Australian protein fractionation facilities, cutting water intensity and expanding functional property tunability for formulators.
High-pressure processing combined with dry-fractionation is automating protein concentration workflows that previously required batch-wise solvent extraction, enabling continuous operation at Australian Plant Proteins' Victorian facility and reducing labor input per kilogram of isolate output.
FSANZ guidance development on hybrid protein nomenclature is forcing ingredient suppliers to pre-position regulatory submissions ahead of formal classification rules, with New South Wales-based manufacturers accelerating novel food dossier preparation for precision-fermented whey analogues blended with pea protein.
Health food retailers in Melbourne and Sydney are consolidating shelf space around single-ingredient protein powders with transparent supply chain disclosure, compressing distribution margins for multi-component formulations and rewarding direct sourcing relationships between extraction facilities and specialty store networks.
Australia Plant Protein Market Segmentation
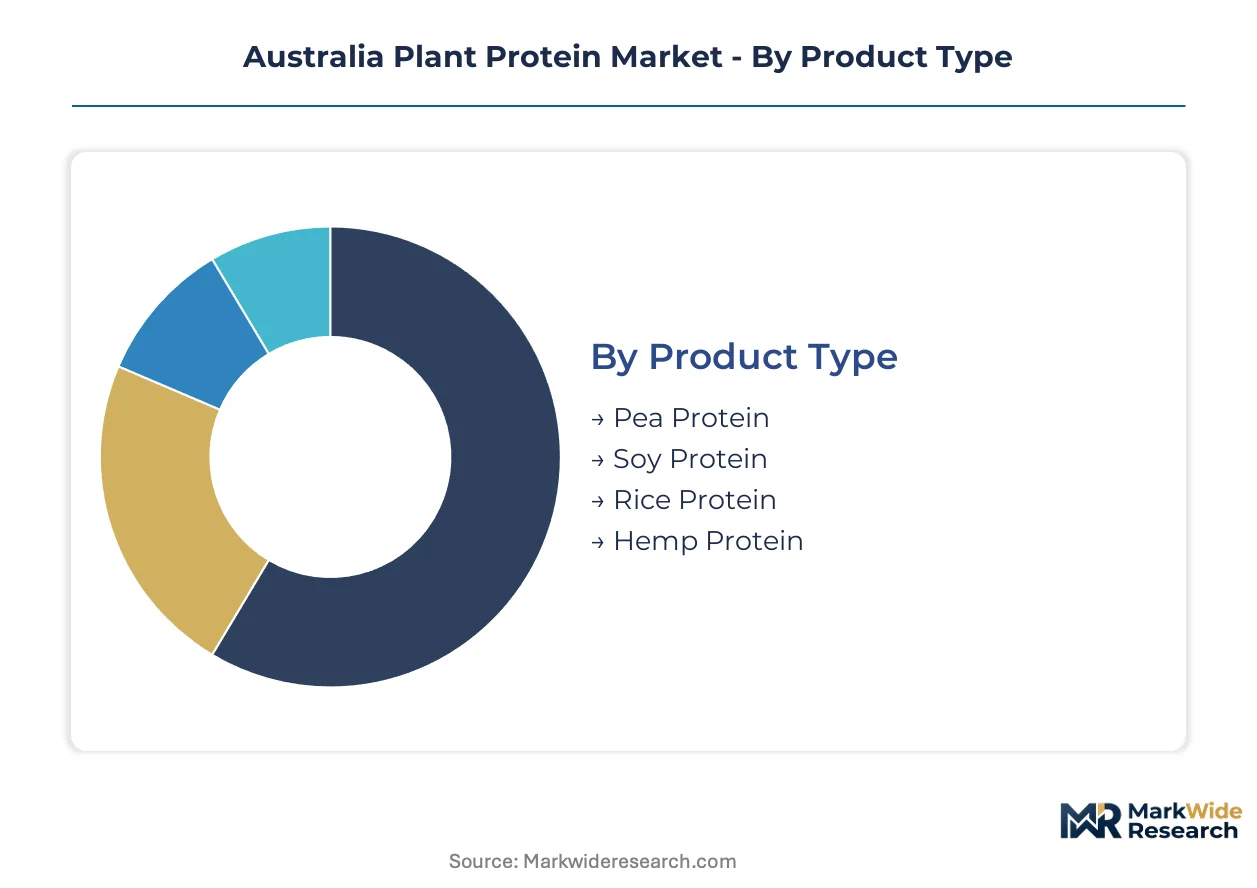
FSANZ novel food approvals and allergen labelling mandates reshape how Australian manufacturers select protein feedstocks and target consumer segments. Certification pathways and distribution economics vary sharply across product categories, creating divergent margin structures and time-to-market pressures.
Product Type:
FSANZ novel food status and allergen declaration requirements impose distinct compliance burdens across protein sources, with hemp and novel fractions facing extended dossier preparation while soy triggers mandatory labelling protocols.
- Pea Protein:Extracted legume fractions achieve 80-90% protein concentration through wet-milling and membrane filtration. Victorian extraction facilities at Australian Plant Proteins supply alt-meat formulators in Melbourne and Sydney with traceable non-GMO feedstock, though drought-sensitive pulse yields expose buyers to price volatility.
- Soy Protein:Mature processing infrastructure delivers cost-competitive isolates with established functional properties in emulsification and gelation. FSANZ allergen labelling mandates constrain formulation flexibility for infant nutrition applications, pushing some manufacturers toward hypoallergenic alternatives in premium positioning.
- Rice Protein:Hypoallergenic brown rice fractions command formulation priority in sports recovery and pediatric nutrition segments where digestibility scores outweigh cost premiums.
- Hemp Protein:Omega-3 positioning and allergen-free claims support premium pricing in health food shops, though off-note masking challenges limit high-concentration deployment.
Leading the category by volume: Pea Protein. Growing fastest: Hemp Protein.
Application:
End-use segments separate by margin capture potential, with nutritional supplements commanding direct-to-consumer premiums while food service channels prioritize cost-per-kilogram efficiency in bulk procurement.
- Food & Beverages:Alt-meat and dairy-analogue reformulations absorb the majority of Australian pea protein concentrate output, with Cargill Incorporated securing supply positions through global procurement networks. Clean-label processing investments concentrate in New South Wales manufacturing corridors where retail innovation hubs accelerate product pipeline velocity.
- Nutritional Supplements:Single-ingredient protein powders with transparent supply chain disclosure consolidate shelf space in Melbourne and Sydney health food retailers, compressing margins for multi-component formulations and rewarding direct sourcing relationships.
- Bakery Products:Functional texturizers and emulsifiers from rice and pea fractions enable gluten-free and high-protein positioning in commercial bakeries.
- Snacks:Extruded protein crisps and bars target fitness enthusiasts through convenience retail channels with portable format innovation.
Food & Beverages captures the largest revenue pool. Nutritional Supplements delivers the steepest expansion trajectory.
End User:
Consumer archetypes diverge by price sensitivity and information requirements, with vegans demanding ingredient transparency while fitness enthusiasts prioritize amino acid completeness.
- Health-conscious Consumers:Clean-label positioning and non-GMO certification drive purchasing decisions among suburban Australian households reformulating pantries around traceable plant ingredients.
- Fitness Enthusiasts:Leucine content and digestibility scores command formulation priority in sports nutrition applications, with rice protein competing for hypoallergenic positioning.
- Vegans:Ethical sourcing claims and single-ingredient transparency support premium pricing tolerance in specialty store channels.
- Vegetarians:Flexitarian transition products bridge familiar taste profiles with partial protein substitution in conventional retail formats.
Health-conscious Consumers dominate absolute spend. Vegans are climbing the fastest.
Distribution Channel:
Channel economics separate by working capital intensity and margin retention, with direct-to-manufacturer agreements bypassing traditional distributor markups for mid-scale alt-dairy producers.
- Online Retail:Subscription models and direct-to-consumer fulfillment enable margin capture for emerging Australian brands, though logistics costs erode competitiveness in bulk formats.
- Grocery Stores:Coles and Woolworths shelf space consolidation rewards national brands with scale economies, constraining regional extraction facility access to mass-market penetration.
- Health Food Shops:Melbourne and Sydney specialty networks consolidate around transparent supply chain disclosure, favoring direct relationships with Victorian extraction facilities over distributor intermediation.
- Specialty Stores:Independent retailers in Brisbane and Perth underpenetrated corridors present first-mover advantages for regional facility deployment.
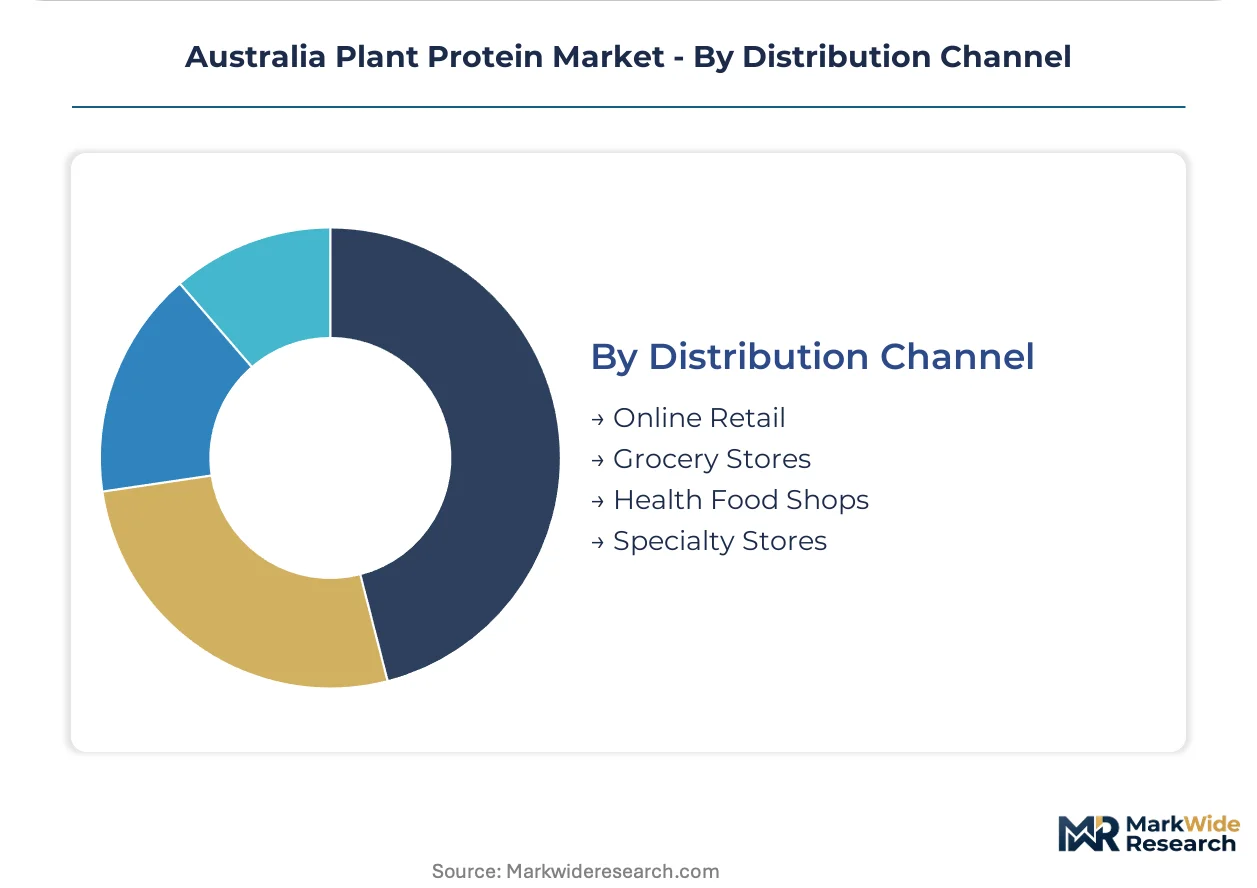
Grocery Stores lead by volume throughput. Health Food Shops are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Victoria's Regional Food and Fibre Growth Program is concentrating plant protein extraction capacity in Geelong and Melbourne's northern manufacturing corridor, with state-matched grants accelerating facility commissioning timelines.
New South Wales
Food and beverage manufacturers in Sydney's western suburbs are expanding reformulation pipelines around traceable non-GMO feedstocks. FSANZ novel food approval pathways are compressing time-to-market for precision-fermented ingredients. The Wollongong-Illawarra corridor hosts pilot-scale fractionation infrastructure serving alt-meat startups.
Victoria
Pea protein isolate output dominates Australian volume through Victorian extraction facilities supplying domestic alt-dairy formulators. The state's Food Innovation Network provides shared pilot plants reducing capital barriers for mid-scale entrants. Geelong's protein processing cluster anchors national supply for traceable legume feedstock.
Queensland
Northern Australian food manufacturing corridors lack dedicated plant protein extraction infrastructure, exposing formulators to interstate logistics costs. The Queensland Department of Agriculture and Fisheries is assessing pulse crop processing incentives for regional deployment. Brisbane-based distributors currently rely on Victorian supply chains with extended lead times.
Western Australia
Canola protein fractionation is emerging around Kwinana's existing oilseed crushing infrastructure, leveraging established supply chains for non-GMO feedstock. The state's Department of Primary Industries and Regional Development is mapping value-add opportunities for existing grain handlers. Perth health food retailers source specialty hemp proteins through direct relationships with eastern facilities.
Australia Plant Protein Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated taste-modulation providers capturing premium pricing in formulation-intensive applications while commodity processors compete on feedstock procurement scale. The market exhibits moderate concentration at the extraction tier, with Victorian facilities supplying national demand. Three archetypes dominate: global ingredient conglomerates with procurement networks, domestic extraction specialists with traceable supply chains, and integrated flavor houses masking off-notes in high-concentration formulations. Capacity expansion and direct-to-manufacturer supply agreements represent the dominant competitive vectors.
Among Irish-headquartered multinationals, Kerry Group plc and Givaudan SA exemplify the integrated taste-modulation archetype, occupying positions where flavor chemistry capabilities differentiate commodity protein offerings. Australian Plant Proteins Pty Ltd represents the domestic extraction specialist model, anchoring national supply security through Victorian manufacturing infrastructure. Cargill Incorporated and Bunge Limited sit within the global procurement tier, leveraging international origination networks to manage Australian input cost volatility.
| Leading Market Players |
|---|
| Kerry Group plc |
| Givaudan SA |
| Cargill Incorporated |
| Australian Plant Proteins Pty Ltd |
| Bunge Limited |
| Archer-Daniels-Midland Company |
| DSM-Firmenich AG |
| Manildra Group |
| International Flavors & Fragrances Inc. |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration and enzyme-assisted extraction are compressing production costs while simultaneously consolidating processing capacity in Victorian extraction facilities, creating a pricing dynamic where technology-advantaged suppliers capture margin from legacy isoelectric precipitation operators.
Pricing Analysis
Volume throughput concentrates in commodity pea protein concentrates while margin capture concentrates in premium hemp and rice protein isolates. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified isolates from conventional concentrates and bulk commodity fractions. Pricing pressure stems from drought-sensitive Australian pulse crop yields exposing formulators to feedstock cost volatility. Health-conscious consumers in suburban households show lowest price sensitivity, while food service bulk procurement channels exhibit highest cost-per-kilogram discipline.
Supply Chain Analysis
Domestic-content mandates under FSANZ novel food approval pathways are reshaping sourcing toward traceable Australian-grown feedstocks. Geographic supply concentration centers on Victorian extraction facilities, with secondary capacity emerging in New South Wales pilot plants and Western Australian canola processing infrastructure. Raw material dependencies include drought-sensitive field peas, non-GMO canola seed, and imported brown rice fractions. Single-source vulnerability concentrates in Victorian logistics corridors exposed to regional climate events. Distribution runs through direct-to-manufacturer agreements bypassing traditional ingredient distributors for mid-scale alt-dairy producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme-assisted extraction is displacing legacy isoelectric precipitation, compressing cost structures and rewarding early technology adopters with sustainable margin advantages.
For Market Incumbents: To counter precision-fermented protein entrants capturing premium positioning, anchor market share through captive supply agreements with Victorian extraction facilities and accelerate FSANZ novel food dossier preparation for hybrid protein classifications. Backward integration into non-GMO pulse crop origination secures feedstock cost stability against drought-driven volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer lowest competitive density for emerging Australian brands seeking bypass of Coles and Woolworths shelf space consolidation. Target Queensland's underpenetrated northern manufacturing corridors where interstate logistics costs currently disadvantage Victorian suppliers. Specialty health food shops in Brisbane and Perth reward transparent supply chain disclosure with premium positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global ingredient conglomerates seeking Australian extraction capacity for Asia-Pacific supply security. Long-term viability hinges on technology transition completion within the coming decade. Acquisition targets should demonstrate integrated taste-modulation capabilities or proprietary fractionation IP. The signal to watch is FSANZ finalization of hybrid protein nomenclature guidance, which will reclassify competitive positioning across precision-fermented and plant-extracted blends.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Deployment | Reduces water intensity at Victorian facilities while expanding functional property tunability for formulators. |
| FSANZ Novel Food Dossier Preparation | Accelerates regulatory approval timelines for precision-fermented whey analogues blended with pea protein. |
| Direct-to-Manufacturer Supply Agreements | Bypasses traditional distributor markups for mid-scale New South Wales alt-dairy producers. |
| Queensland Regional Facility Deployment | Captures first-mover advantages in northern corridors currently dependent on Victorian supply chains. |
| Integrated Taste-Modulation Capability Buildout | Masks off-notes in high-concentration hemp formulations for infant nutrition penetration. |
Study Parameters
FSANZ regulatory filings, Australian Bureau of Agricultural and Resource Economics trade data, and Victorian Department of Jobs, Skills, Industry and Regions grant disclosures formed the secondary backbone, cross-referenced with primary interviews involving extraction facility plant managers, alt-meat formulator R&D directors, health food retailer category buyers, and FSANZ regulatory affairs specialists. Bottom-up volume modeling from individual facility capacities reconciled against top-down expenditure flows from food and beverage manufacturer procurement disclosures.
Historical trendline analysis of Australian pulse crop yields and protein fractionation capacity utilization informed projection parameters across the analysis window. Segmentation dimensions modeled include protein source type, application category, end-user archetype, and distribution channel structure. CAGRs derived from slope analysis of normalized volume and value trajectories, adjusted for drought-frequency weighting in agricultural input assumptions and FSANZ approval velocity in regulatory timeline assumptions.
The model holds under stable FSANZ regulatory guidance and normalized rainfall patterns; deviation in extended drought cycles or accelerated precision-fermented protein approvals would shift capacity utilization and pricing trajectories. Forecasts reflect documented assumptions regarding technology adoption curves and feedstock cost pass-through elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Plant Based Breads Market