
 South America Soy Beverages Market | 2026-2036
South America Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Soy Beverages Market Analytics
Buyer concentration across South America's soy beverage landscape is broadening beyond traditional supermarket channels into specialty health food outlets and direct-to-consumer platforms. Danone SA leverages its dairy-alternative expertise to anchor shelf presence in Brazil's retail networks. Jussara SA dominates regional soy milk production with manufacturing scale advantages across São Paulo state. Kikkoman Corporation differentiates through fermentation technology leadership in flavored soy drink formulations.
Soy beverages comprise aqueous extracts of whole soybeans or soy protein isolates, typically processed through soaking, grinding, heat treatment, and homogenization to achieve suspension stability and nutritional bioavailability. The primary commercial purpose centers on delivering complete plant protein and isoflavone content to consumers seeking dairy alternatives or cholesterol-reduced diets. Soy milk occupies the mature volume position while soy protein beverages capture premium positioning among fitness enthusiasts. Online retail channels represent the fastest-growing distribution vector as logistics networks penetrate secondary Brazilian cities. Tetra pack formats sustain margin pools through extended ambient shelf life and reduced cold-chain dependency.
ANVISA governs ingredient disclosure and health claim substantiation for functional beverages across Brazil, while Mercosur technical regulations harmonize cross-border trade standards for Argentina, Paraguay, and Uruguay. These frameworks elevate compliance costs for imported formulations but simultaneously protect domestic manufacturers from unverified competitive positioning. Stakeholders must monitor evolving protein content thresholds and front-of-pack labeling mandates that will reshape formulation strategies and marketing communication across the continent.
Market Dynamics
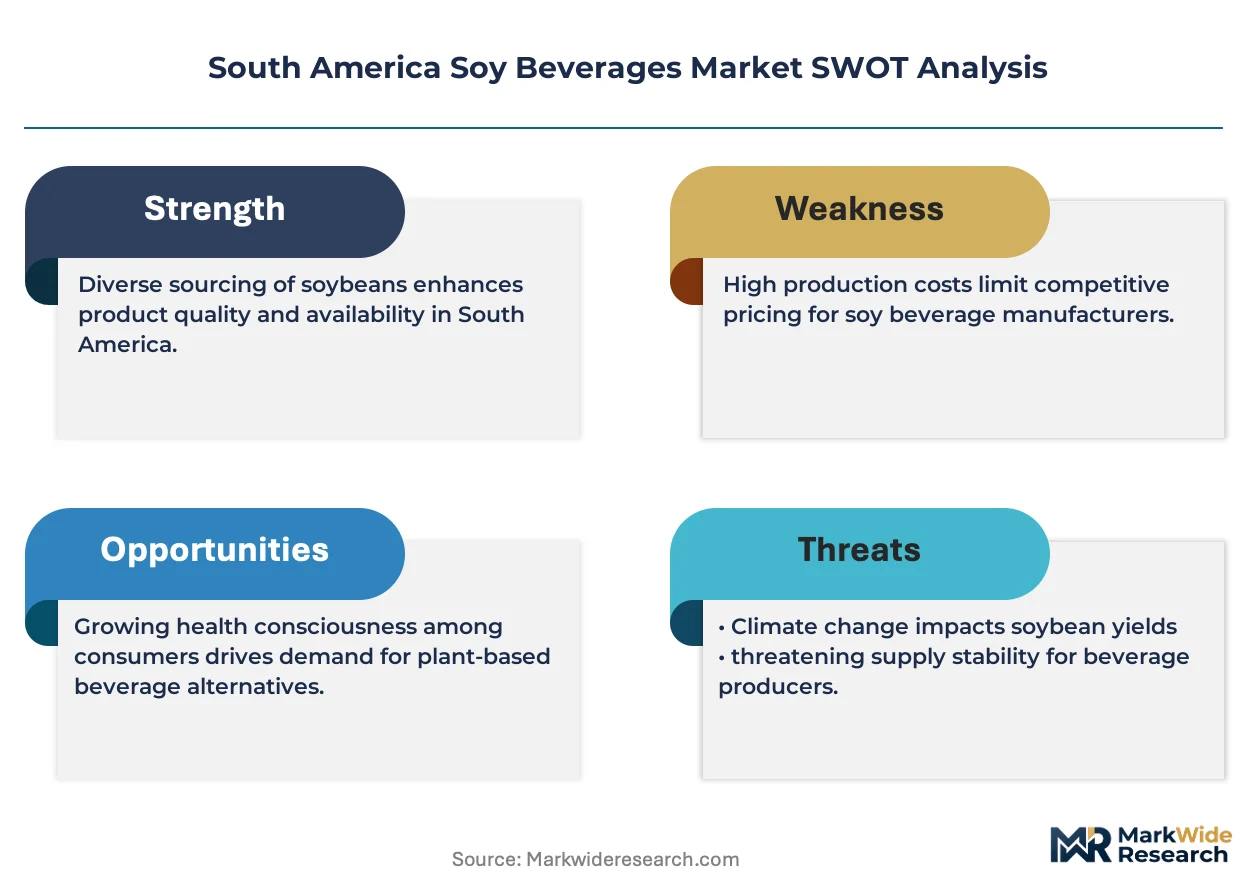
ANVISA's front-of-pack labeling mandates are compressing formulation timelines across Brazil's soy beverage sector, forcing manufacturers to reformulate for cleaner ingredient decks while maintaining protein bioavailability and shelf stability.
Growth Catalysts
- ANVISA Regulation 429:Mandatory nutrient warning labels on ultra-processed foods accelerate consumer migration toward plain soy milk variants with minimal additive content.
- Cross-border Mercosur harmonization:Unified technical standards for Argentina, Paraguay, and Uruguay reduce re-registration costs for Brazilian exporters seeking regional expansion.
- Metropolitan corridor clustering:São Paulo state's cold-chain density enables same-day delivery penetration into Rio de Janeiro and Belo Horizonte consumer bases.
Market Restraints
- Soybean input volatility:Argentine crushing margin compression transmits price instability to Brazilian soy protein isolate suppliers dependent on imported meal.
- Tetra Pak supply concentration:Aseptic carton substrate sourcing remains captive to European packaging conglomerates with limited South American production footprint.
- Behenic acid technical ceiling:Lipid fraction separation limitations constrain mouthfeel optimization in high-protein formulations targeting fitness segments.
Strategic Opportunities
- Paraguay retail whitespace:Asunción metropolitan zone lacks dedicated plant-based beverage distribution infrastructure, creating first-mover shelf allocation advantages.
- Direct-to-consumer subscription models:Recurring revenue platforms bypass traditional retail slotting fees while capturing consumer preference data for flavor innovation pipelines.
- Precision fermentation convergence:Bioreactor-produced isoflavone concentrates enable functional positioning beyond basic protein claims without agricultural commodity exposure.
Industry Challenges
- Food technologist scarcity:Brazilian universities produce insufficient formulation specialists trained in plant protein stabilization and enzymatic hydrolysis.
- Organic certification timelines:IBD and Ecocert audit backlogs extend product launch schedules by eight to fourteen months for premium positioning claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Soy Beverages Market |
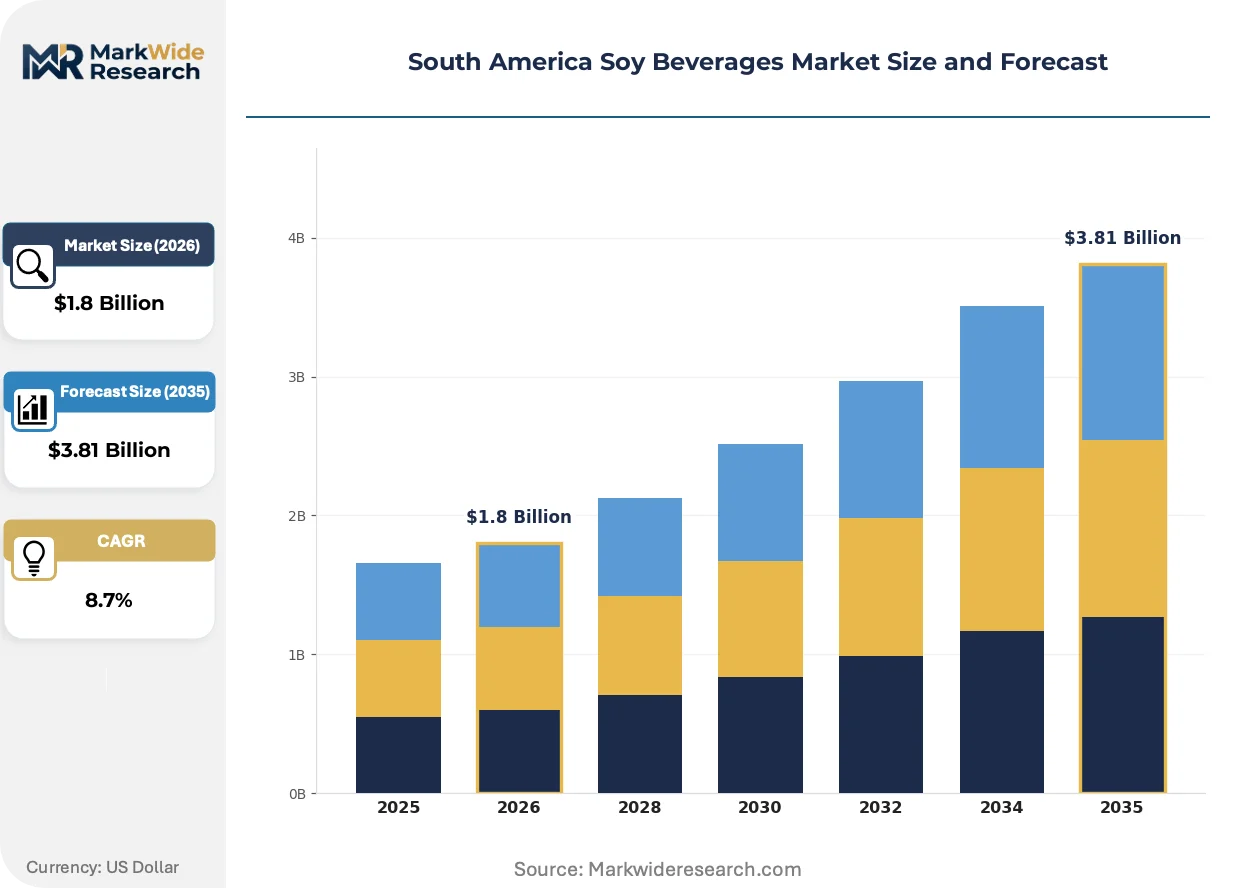
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Soy Yogurt, Soy Protein Beverages, Blended Soy Drinks End User: Health Conscious Consumers, Vegans, Lactose Intolerant Individuals, Fitness Enthusiasts Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores Packaging Type: Cartons, Bottles, Tetra Packs, Pouches |
| Companies Covered | The Hain Celestial Group, Danone SA, The Coca-Cola Company, Jussara SA, Lactalis, Kikkoman Corporation, Pacific Foods, Westsoy Soy Milk, Pureharvest, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Soy Beverages Market Evolving Landscape
Processing technology and distribution infrastructure are restructuring competitive advantage in South American soy beverages, with shelf-stable formats and digital channels displacing traditional refrigerated logistics and supermarket dependency.
High-pressure processing is converging with aseptic filling systems to extend ambient shelf life without thermal degradation of isoflavone content. Brazilian contract manufacturers in Minas Gerais are retrofitting existing UHT lines with HPP post-packaging tunnels to serve emerging direct-to-consumer brands. This dual-technology approach is compressing the capital barrier between artisanal production and national distribution scale.
Mercosur's updated Common Market Group Resolution on food additives is restricting synthetic emulsifier use in beverages marketed to children across Argentina, Brazil, and Uruguay. Manufacturers must reformulate with lecithin or gum arabic alternatives, elevating input costs but creating regulatory moats against informal imports. The preschool nutrition segment is responding with accelerated clean-label certification investments.
Fitness enthusiasts in São Paulo and Buenos Aires are consolidating purchasing through specialized e-commerce platforms that bundle soy protein beverages with personalized macronutrient coaching. Traditional pharmacy chains are losing traffic to these vertically integrated digital services. This channel rotation is most pronounced among consumers aged twenty-five to thirty-four with gym membership affiliations.
South America Soy Beverages Market Segmentation
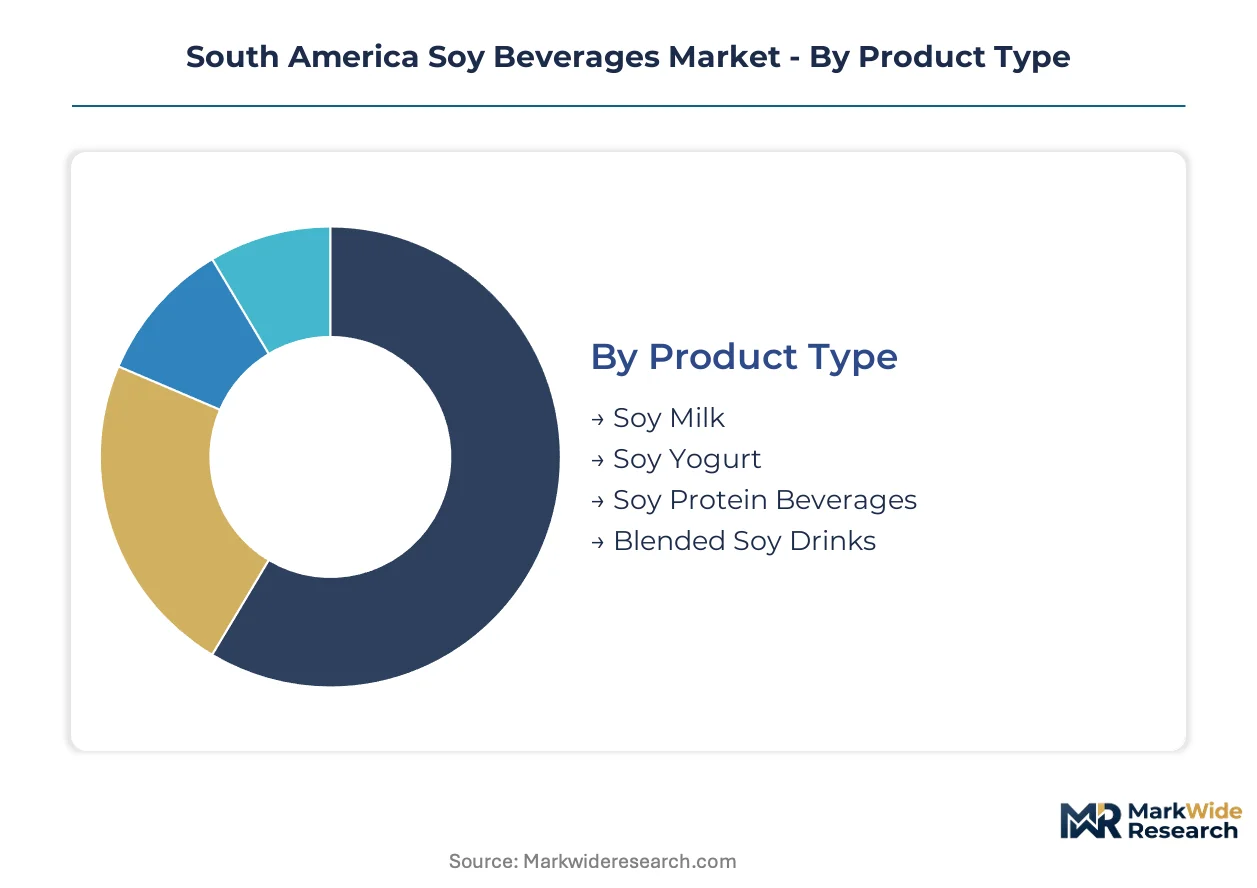
South America's soy beverage segmentation reveals divergent growth mechanics across consumption occasions and purchase pathways. Product formulation sophistication varies sharply between daily nutrition staples and performance-oriented functional drinks. Channel evolution is fragmenting traditional retail concentration while packaging innovation unlocks new distribution economics.
Product Type:
Reformulation cycles are accelerating as manufacturers respond to ANVISA's clean-label mandates and shifting protein bioavailability expectations across Brazilian and Argentine consumer bases.
- Soy Milk:Standardized aqueous extract of whole soybeans processed through soaking, grinding, and UHT stabilization delivers complete protein and isoflavone content. Demand concentrates in Brazil's southeastern metropolitan corridor from São Paulo to Rio de Janeiro, where supermarket penetration and cold-chain density support daily consumption rituals. ANVISA's front-of-pack warning labels are compressing additive content in flavored variants.
- Soy Protein Beverages:Isolated protein formulations with enhanced leucine content target post-workout recovery and muscle protein synthesis. Fitness enthusiasts in Buenos Aires and São Paulo's gym-dense neighborhoods drive premium positioning, with direct-to-consumer platforms capturing preference data for flavor pipeline development. Behenic acid separation limitations constrain mouthfeel optimization in high-concentration formats.
- Soy Yogurt:Fermented soy milk with live culture content serves dairy-alternative breakfast and snacking occasions. Argentine manufacturing clusters leverage Mercosur harmonization for cross-border distribution into Paraguay and Uruguay.
- Blended Soy Drinks:Composite formulations incorporating fruit, grain, or nut fractions for flavor differentiation and macronutrient diversification. Brazilian health food stores in Belo Horizonte and Curitiba experiment with localized ingredient sourcing.
Soy milk sits at the top of the volume ranking, with soy protein beverages climbing the fastest.
End User:
Customer archetypes are fragmenting around distinct nutritional missions, with each segment demanding tailored protein specifications and packaging formats.
- Health Conscious Consumers:Broad demographic seeking cholesterol reduction and cardiovascular protective effects through daily soy isoflavone intake. São Paulo's aging urban population drives shelf-stable carton demand for pantry stocking convenience.
- Fitness Enthusiasts:Gym-affiliated consumers aged twenty-five to thirty-four purchasing through specialized e-commerce platforms with bundled macronutrient coaching. Buenos Aires and São Paulo vertical integrations are displacing traditional pharmacy chain traffic.
- Vegans:Ethical and environmental motivation segments prioritizing organic certification and supply chain transparency. IBD and Ecocert audit backlogs extend product launch timelines by eight to fourteen months for this premium positioning.
- Lactose Intolerant Individuals:Medically-driven dairy avoidance seeking digestive comfort without nutritional compromise. Pediatric formulations face Mercosur restrictions on synthetic emulsifiers.
Health conscious consumers anchor volume demand, while fitness enthusiasts are expanding most quickly through digital channel migration.
Distribution Channel:
Logistics infrastructure investments are reconfiguring channel economics, with cold-chain penetration enabling same-day delivery beyond traditional supermarket catchments.
- Supermarkets:Multi-banner retail networks in Brazil's southeastern corridor maintain dominant shelf allocation through slotting fee structures and promotional calendar coordination. Danone SA leverages dairy-alternative expertise for anchor positioning.
- Online Retail:Fastest-expanding vector as logistics networks penetrate secondary Brazilian cities and subscription models bypass retail margin extraction. São Paulo-state contract manufacturers retrofit UHT lines with HPP post-packaging tunnels for direct-to-consumer brands.
- Health Food Stores:Curated assortment environments with trained staff consultation supporting premium and organic variant discovery. Asunción metropolitan zone represents first-mover whitespace opportunity.
- Specialty Stores:Pharmacy and gym-adjacent formats losing traffic to vertically integrated digital services among core fitness demographics.
Supermarkets retain volume leadership, with online retail gaining share fastest through subscription platform economics.
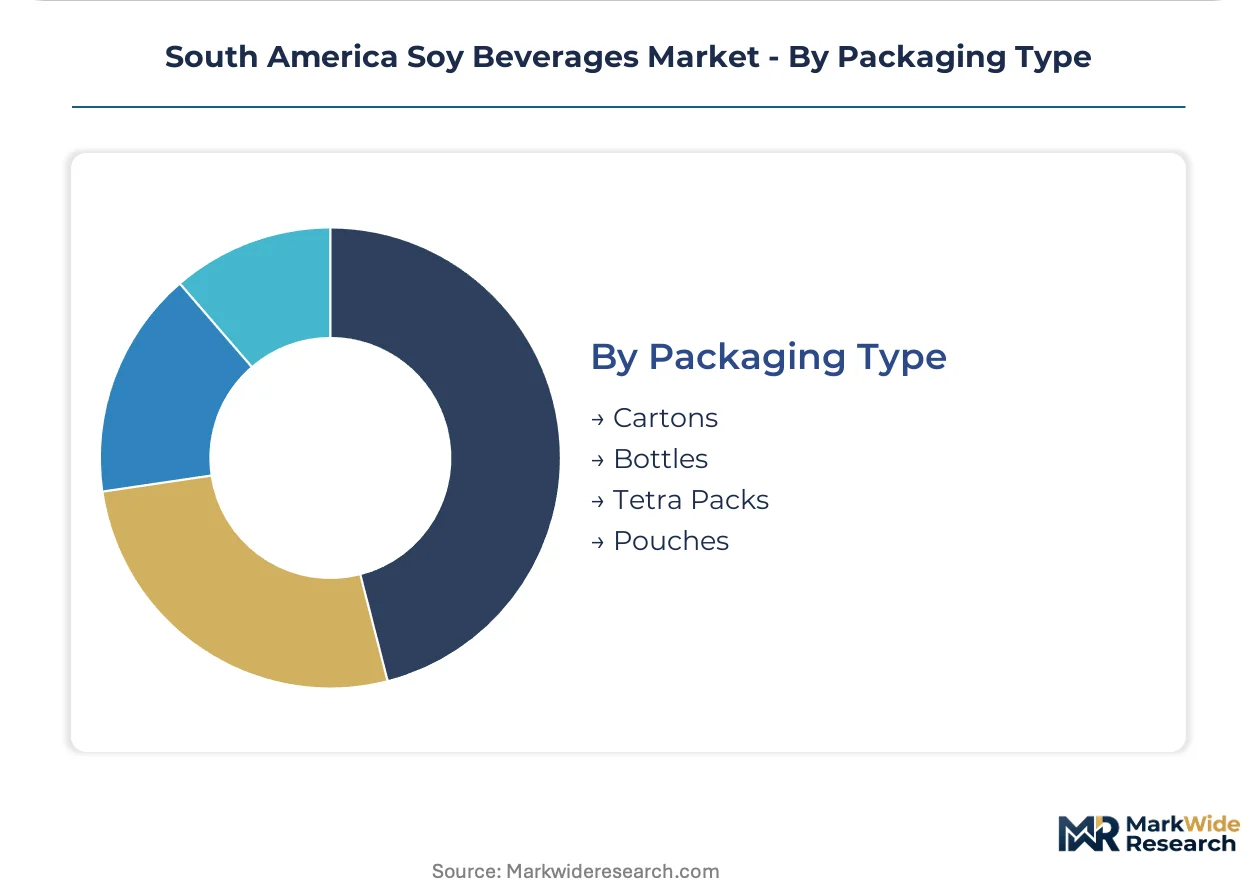
Packaging Type:
Material selection tradeoffs between shelf stability, cold-chain dependency, and sustainability credentials are reshaping procurement priorities across Brazilian manufacturing bases.
- Tetra Packs:Aseptic carton formats sustain margin pools through extended ambient shelf life and reduced refrigeration infrastructure requirements. European packaging conglomerates maintain substrate sourcing concentration with limited South American production footprint.
- Bottles:PET and HDPE formats for refrigerated premium positioning and visual transparency communicating product purity. Brazilian recycling infrastructure constraints limit post-consumer circularity claims.
- Cartons:Gable-top refrigerated formats for shorter shelf-life fresh products with regional distribution radius. São Paulo-state dairy-alternative specialists favor this for local market penetration.
- Pouches:Flexible film structures for single-serve portability and reduced material intensity. Emerging in Brazilian direct-to-consumer sampling and fitness channel bundles.
Tetra packs dominate volume rankings, with pouches expanding most quickly through portion-control and sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologist concentrations in São Paulo and Buenos Aires anchor South America's soy beverage innovation capacity, with university pipelines in Campinas and La Plata supplying formulation specialists to regional manufacturers.
Brazil
São Paulo state's metropolitan corridor generates the dominant consumption base, with health-conscious urban populations driving demand for clean-label soy milk variants. ANVISA's front-of-pack labeling mandates under Resolution 429 compress formulation timelines while elevating compliance costs for imported additives. Campinas-based contract manufacturers retrofit UHT lines with high-pressure processing tunnels to serve direct-to-consumer brands penetrating secondary cities.
Argentina
Buenos Aires gym-dense neighborhoods concentrate fitness-oriented soy protein beverage demand among twenty-five to thirty-four-year-old consumers. Mercosur technical regulations harmonize cross-border standards with Brazil, Paraguay, and Uruguay, reducing re-registration burdens for Argentine exporters. Rosario's crushing margin volatility transmits price instability to domestic soy protein isolate suppliers dependent on agricultural commodity flows.
Paraguay
Asunción's metropolitan zone presents first-mover whitespace for dedicated plant-based beverage distribution infrastructure, with supermarket penetration lagging regional peers. The national food regulator enforces Mercosur-aligned additive restrictions without domestic capacity for complex formulation oversight. Brazilian exporters leverage cross-border logistics networks to capture shelf allocation ahead of local manufacturing development.
Uruguay
Montevideo's aging urban population drives shelf-stable carton demand for cardiovascular-focused daily soy isoflavone intake. Mercosur membership ensures regulatory alignment with Argentine and Brazilian standards, though market scale limits dedicated manufacturing investment. Cross-border supply chains from Buenos Aires and São Paulo dominate product availability.
Chile
Santiago's health food store networks experiment with premium organic soy yogurt positioning, though IBD and Ecocert audit backlogs extend launch timelines. The national agricultural service maintains strict GMO labeling requirements that elevate sourcing costs for non-certified soybean inputs. Valparaíso's logistics infrastructure supports import-dependent supply chains from Argentine manufacturing clusters.
South America Soy Beverages Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South America's soy beverage sector, creating a tiered structure where scale advantages clash with agility in flavor innovation. Brazilian and Argentine manufacturing bases concentrate production gravity, with cross-border Mercosur trade flows enabling regional portfolio expansion without duplicate facility investment. Three archetypes dominate: dairy-alternative diversifiers leveraging existing cold-chain relationships, fermentation technology specialists commanding premium positioning, and contract manufacturers enabling private-label proliferation. Capacity expansion and clean-label reformulation represent the dominant competitive moves as ANVISA deadlines approach.
Within the dairy-alternative diversification tier, Danone SA and Lactalis exemplify multinational leverage of existing retail shelf relationships for soy beverage anchor positioning. Jussara SA represents Brazilian manufacturing scale concentration, while Kikkoman Corporation occupies the fermentation technology specialist archetype. These three companies illustrate how geographic origin and corporate structure shape competitive approach without requiring specific operational claims.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Danone SA |
| The Coca-Cola Company |
| Jussara SA |
| Lactalis |
| Kikkoman Corporation |
| Pacific Foods |
| Westsoy Soy Milk |
| Pureharvest |
| Others |
Value Network & Pricing Analysis
Backward integration into soybean crushing operations anchors pricing power for Brazilian soy beverage manufacturers, linking input cost control directly to margin sustainability across the São Paulo-to-Rio de Janeiro corridor. This structural choice determines competitive positioning as ANVISA's clean-label mandates elevate formulation expenses.
Pricing Analysis
Capacity additions in Minas Gerais are reshaping price floors for contract manufacturing services, compressing margins for established brands while enabling new entrants to access national-scale production. Pricing stratifies across premium organic, standard UHT-stabilized, and economy private-label tiers, with certification grade and cold-chain dependency as primary differentiation drivers. Cost compression in the standard tier is intensifying because Tetra Pak substrate sourcing remains captive to European suppliers. Fitness enthusiasts purchasing through subscription platforms exhibit the lowest price sensitivity, while mass-market supermarket shoppers drive volume through promotional responsiveness.
Supply Chain Analysis
Freight cost differentials between Brazilian southeastern manufacturing clusters and secondary cities determine distribution economics for ambient-stable formats. Soybean supply concentrates in Brazil, Argentina, and Paraguay, with crushing operations drawing from agricultural commodity flows through Rosario and Mato Grosso. Raw material dependencies include soy protein isolates, aseptic carton substrates, and enzymatic stabilizers. Single-source vulnerability in European packaging conglomerates elevates supply chain risk for national-scale brands. Distribution runs through supermarket slotting-fee networks, direct-to-consumer subscription platforms, and cross-border Mercosur logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in South American soy beverages rests on clean-label reformulation cost-down curves and fitness-segment premium-tier migration, with ANVISA compliance deadlines accelerating competitive sorting.
For Market Incumbents: Lock in shelf allocation through multi-year supermarket promotional calendar commitments before slotting-fee inflation accelerates. Secure backward integration into São Paulo-state soybean crushing to defend against Argentine meal price volatility. Prioritize HPP-UHT dual-technology retrofit investments at Campinas contract manufacturing partners to capture direct-to-consumer brand volumes. For New Entrants and Emerging Players: Enter via Paraguay's Asunción metropolitan whitespace, where dedicated plant-based beverage distribution infrastructure remains undeveloped. Target fitness enthusiasts through vertically integrated digital platforms bundling macronutrient coaching with subscription replenishment. Exploit IBD and Ecocert audit backlogs by partnering with certified Brazilian co-manufacturers rather than pursuing independent organic accreditation. For Investors and Strategic Acquirers: Roll-up economics work for regional contract manufacturers with HPP-capable UHT lines because ANVISA's formulation timelines compress in-house development feasibility for emerging brands. The five-to-ten-year viability window favors platforms consolidating São Paulo-state production gravity. Monitor precision fermentation technology maturation as the inflection signal for isoflavone concentrate sourcing disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | ANVISA Resolution 429 compliance protects shelf positioning against additive-heavy imports. |
| HPP-UHT Dual Technology Retrofit | Campinas contract manufacturers capture direct-to-consumer brand volumes with extended ambient shelf life. |
| Direct-to-Consumer Subscription Launch | São Paulo fitness enthusiasts generate recurring revenue and preference data for flavor pipelines. |
| Mercosur Cross-Border Expansion | Harmonized technical standards reduce re-registration burdens for Brazilian exporters entering Paraguay. |
| Precision Fermentation Partnership | Bioreactor-produced isoflavone concentrates enable functional positioning without agricultural commodity exposure. |
Research Methodology
Bottom-up end-use consumption modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with brand managers at Brazilian soy beverage manufacturers, category buyers at supermarket banners, formulation specialists at Campinas contract manufacturers, and logistics coordinators at cross-border distributors combined with secondary validation from ANVISA regulatory filings, Mercosur technical regulation databases, Nielsen retail audit data for Brazil's southeastern corridor, and customs records for soy protein isolate trade flows. Triangulation between demand-side consumption patterns and supply-side production volumes ensures statistical integrity.
Historical trendline analysis across the projection horizon established baseline growth trajectories for soy milk, soy protein beverages, soy yogurt, and blended formats. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and packaging format, with regional regulatory clusters and cold-chain penetration as cross-cutting variables. CAGRs were derived through regression analysis of volume and value outputs, incorporating ANVISA compliance cost curves and fitness-segment digital channel migration as industry-specific forecast inputs.
The model holds under stable Mercosur regulatory alignment and continued cold-chain infrastructure investment; deviation in Argentine soybean crushing margin volatility or European aseptic carton supply disruptions would shift trajectory assumptions. Stakeholders should weight assumptions against their own operating context and sourcing configurations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Tempeh Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
China Rice Protein Market