
 Construction TIC Market | 2026-2036
Construction TIC Market Size, Share, and Industry Trends Forecast 2026-2036
Construction TIC Market Outlook
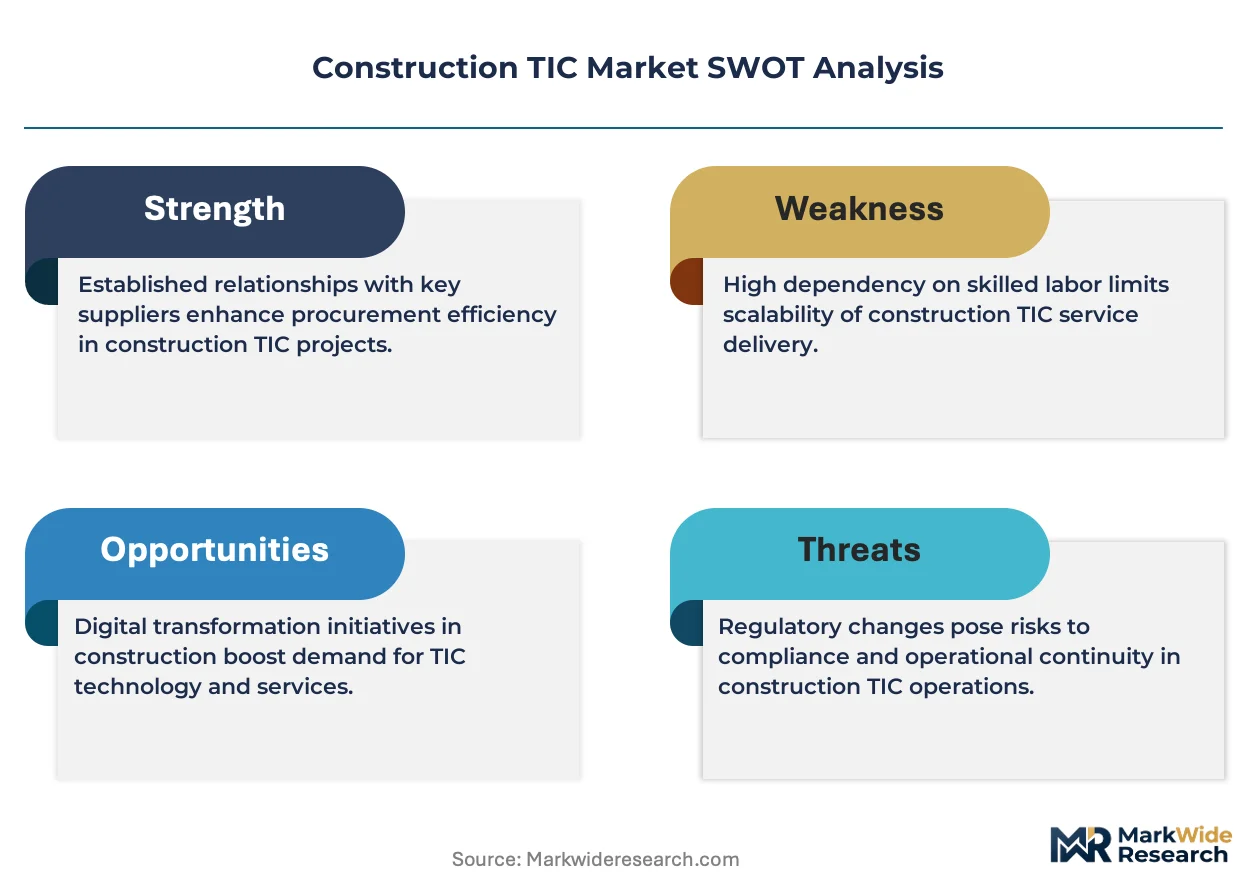
Private infrastructure funds and institutional asset managers are redrawing the Construction TIC competitive map as they mandate independent verification across portfolio assets. SGS leverages its global laboratory network to anchor large-scale civil engineering contracts across multiple continents. Bureau Veritas sustains dominance in marine and industrial construction certification, a niche where technical barriers protect margin pools. Intertek Group competes through aggressive geographic expansion in Middle Eastern megaproject corridors.
Construction TIC encompasses the independent testing, inspection, and certification of materials, processes, and completed structures against codified safety, quality, and environmental standards, typically involving concrete compression analysis, weld integrity radiography, and air permeability testing to verify structural performance and regulatory conformity. Its primary purpose is to transfer technical risk from project owners to qualified third parties while satisfying lender and insurer requirements. Quality control services command the deepest revenue pools due to recurring material batch testing, while regulatory compliance work is accelerating fastest as jurisdictions layer climate disclosure obligations onto traditional building codes. Building Information Modeling integration is reshaping project phase segmentation by embedding inspection checkpoints directly into digital twins before physical ground breaks.
EMA's construction product regulation under the EU CPR framework, alongside Germany's KBA-influenced infrastructure standards and France's ANSM-linked public health building codes, collectively raise the compliance threshold for market access across European project pipelines. The EPA and OSHA in the United States impose parallel demands through environmental impact and workplace safety mandates that TIC providers must navigate for cross-border contract eligibility. Stakeholders should monitor which regulatory bodies next mandate whole-life carbon auditing, as this single shift would restructure service mix priorities across all major Construction TIC providers.
Market Dynamics
The EU Green Deal's embodied carbon verification mandate is compressing project timelines and forcing inspection providers to embed environmental auditing into traditional quality control workflows.
Growth Catalysts
- EU Green Deal compliance mandates:France's ANSM-linked building codes and Germany's KBA-influenced infrastructure standards now require third-party carbon verification, expanding contract scopes for TIC providers.
- Commercial retrofit acceleration:Germany's commercial building sector is driving recurring inspection demand as energy efficiency upgrades trigger mandatory recertification cycles.
- Digital twin integration:Building Information Modeling is embedding inspection checkpoints into pre-construction phases, creating new service revenue streams before physical work begins.
Market Restraints
- Specialized equipment capex intensity:Radiographic weld testing and concrete compression analysis require capital-heavy laboratory infrastructure that limits provider scalability.
- Geographic supply concentration:Marine and industrial construction certification expertise clusters in specific coastal regions, creating bottlenecks for inland project access.
- Regulatory fragmentation:Divergent national implementations of EU CPR framework create compliance friction for cross-border contract execution.
Strategic Opportunities
- Middle Eastern megaproject corridors:Infrastructure investment in Gulf states is generating demand for independent verification services with limited incumbent provider presence.
- Whole-life carbon auditing:Anticipated regulatory expansion beyond embodied carbon into operational phase verification would restructure service mix priorities.
- Air permeability testing convergence:Integration of thermal imaging with traditional blower door protocols is opening premium certification tiers for high-performance building envelopes.
Industry Challenges
- Radiographic technician scarcity:Qualified weld integrity inspectors face supply constraints relative to pipeline construction velocity.
- Legacy system integration friction:Digital twin platforms must interface with established project management software, complicating technology adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction TIC Market |
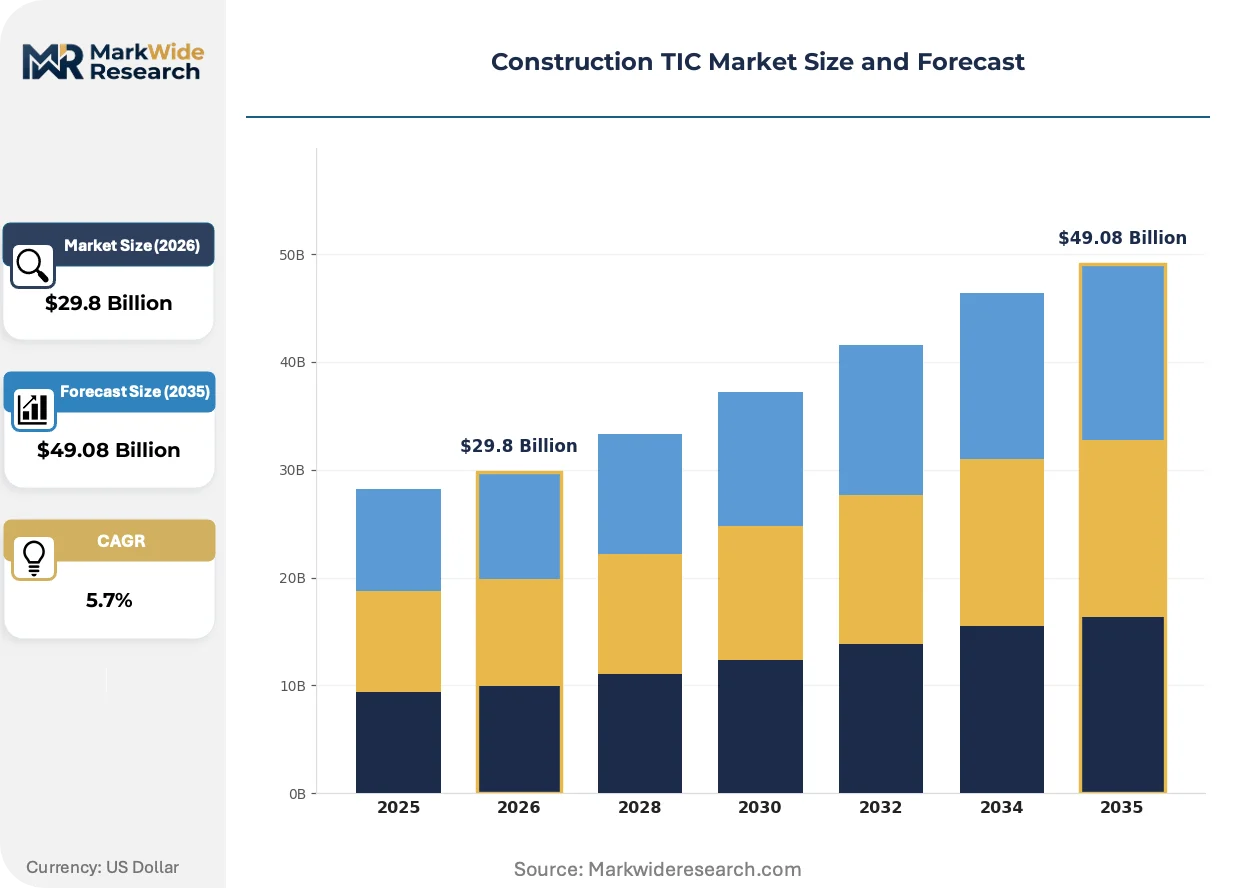
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $49.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Control, Safety Inspections, Regulatory Compliance, Risk Assessment Client Type: Contractors, Architects, Engineers, Developers Technology: Building Information Modeling, Drones, IoT, Virtual Reality Project Phase: Planning, Execution, Monitoring, Completion |
| Companies Covered | SGS, Bureau Veritas, Intertek Group, TÜV Rheinland, DEKRA, Applus+, UL Solutions, Element Materials Technology, TÜV SÜD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction TIC Market Strategic Shifts
Digital verification technologies are compressing traditional phase-gate inspection models while regulatory layering of climate disclosure onto safety codes is expanding required competency portfolios.
Drone-mounted thermal imaging is displacing manual facade inspection protocols for high-rise envelope verification. Institutional asset managers deploying capital across European commercial portfolios are mandating aerial thermographic surveys as a condition of loan covenant compliance. This displacement is compressing inspection timelines from weeks to days while elevating data resolution standards for air leakage detection.
The EU CSRD's scope expansion into built environment disclosure is forcing construction TIC providers to build carbon accounting capabilities alongside structural engineering competencies. France's regulatory implementation through ANSM-linked channels is most advanced, with German KBA-influenced infrastructure standards following closely. Commercial retrofit contractors in both jurisdictions are now bundling environmental verification into traditional quality control procurement packages.
Asset managers are consolidating vendor relationships across portfolio properties, replacing project-specific inspection contracts with multi-year framework agreements. This concentration is squeezing smaller regional providers while rewarding TIC firms with cross-border laboratory networks. The shift is most pronounced in Germany's commercial building sector, where fund-level procurement mandates now cover properties across multiple cities.
Construction TIC Market Segmentation
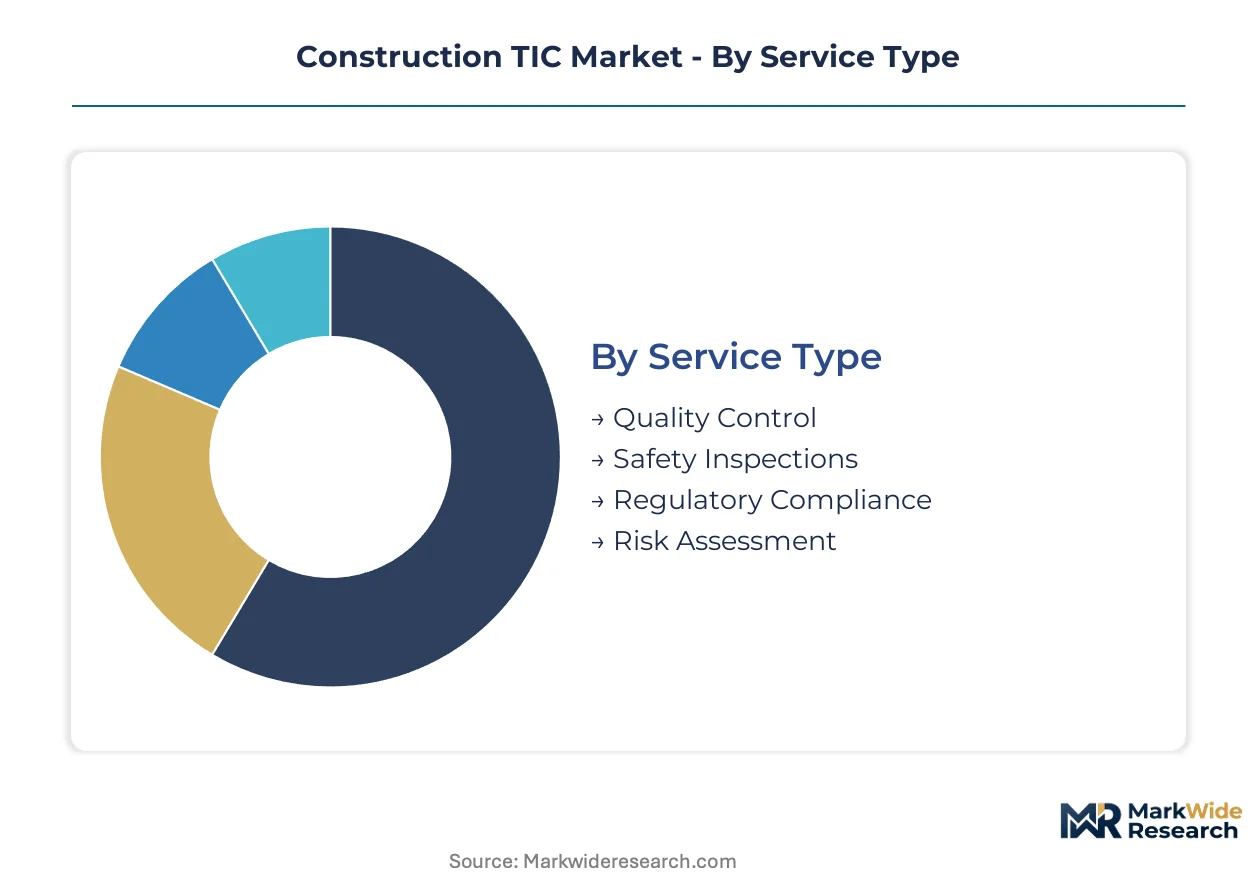
Construction TIC providers structure service delivery around distinct technical competencies, client relationships, and project lifecycle integration points. Channel economics vary sharply across these dimensions, with recurring quality control contracts generating fundamentally different margin profiles than one-off regulatory compliance engagements.
Service Type:
Quality control services flow through long-term framework agreements with institutional asset managers, while regulatory compliance work concentrates in project-specific procurement tied to permitting timelines.
- Quality Control:Recurring material batch testing for concrete compression, weld integrity, and soil compaction anchors provider cash flows. Germany's commercial retrofit sector drives concentrated demand as energy efficiency upgrades trigger mandatory recertification cycles under KBA-influenced standards.
- Safety Inspections:Workplace hazard assessment and fall protection verification occur across all project phases. OSHA mandates in the United States and parallel EU directives sustain baseline demand, though technician scarcity constrains expansion velocity.
- Regulatory Compliance:Third-party verification against codified building codes and environmental standards. EU Green Deal carbon disclosure obligations are expanding contract scopes beyond traditional safety parameters.
- Risk Assessment:Pre-construction liability evaluation and insurer-mandated technical due diligence. Institutional lenders increasingly require independent verification as a loan covenant condition.
By volume, Quality Control leads. By growth pace, Regulatory Compliance is expanding most quickly.
Client Type:
Developer procurement patterns concentrate vendor relationships at the portfolio level, while contractor engagement remains project-fragmented and price-sensitive.
- Developers:Portfolio-scale framework agreements spanning multiple properties and geographies. Private infrastructure funds in Germany now mandate multi-year TIC contracts covering commercial assets across Berlin, Munich, and Hamburg.
- Contractors:Project-specific procurement with compressed timelines and competitive bidding. Quality control batch testing represents the primary attach point for provider relationships.
- Architects:Design-phase integration through Building Information Modeling checkpoints. Digital twin embedding creates pre-construction revenue streams before physical ground breaks.
- Engineers:Technical specification validation and structural performance verification. Marine and industrial certification expertise clusters create geographic access constraints for inland projects.
Developers command the highest contract values per engagement. Contractors generate the greatest transaction frequency.
Technology:
Capital intensity stratifies provider capabilities, with drone and IoT infrastructure requiring upfront investment that rewards scaled operators.
- Building Information Modeling:Digital twin platforms embedding inspection checkpoints into pre-construction phases. Legacy system integration friction complicates adoption timelines for established project management software environments.
- Drones:Aerial thermographic surveys displacing manual facade inspection for high-rise envelope verification. Institutional asset managers in France mandate drone-mounted thermal imaging as a loan covenant compliance condition.
- IoT:Continuous structural health monitoring through embedded sensor networks. Real-time data streams are compressing traditional phase-gate inspection models.
- Virtual Reality:Immersive training environments for radiographic technicians and weld inspectors. Supply constraints for qualified personnel elevate simulation-based competency development.
Building Information Modeling captures the deepest integration into client workflows. Drone deployment is climbing the fastest as regulatory acceptance standardizes.
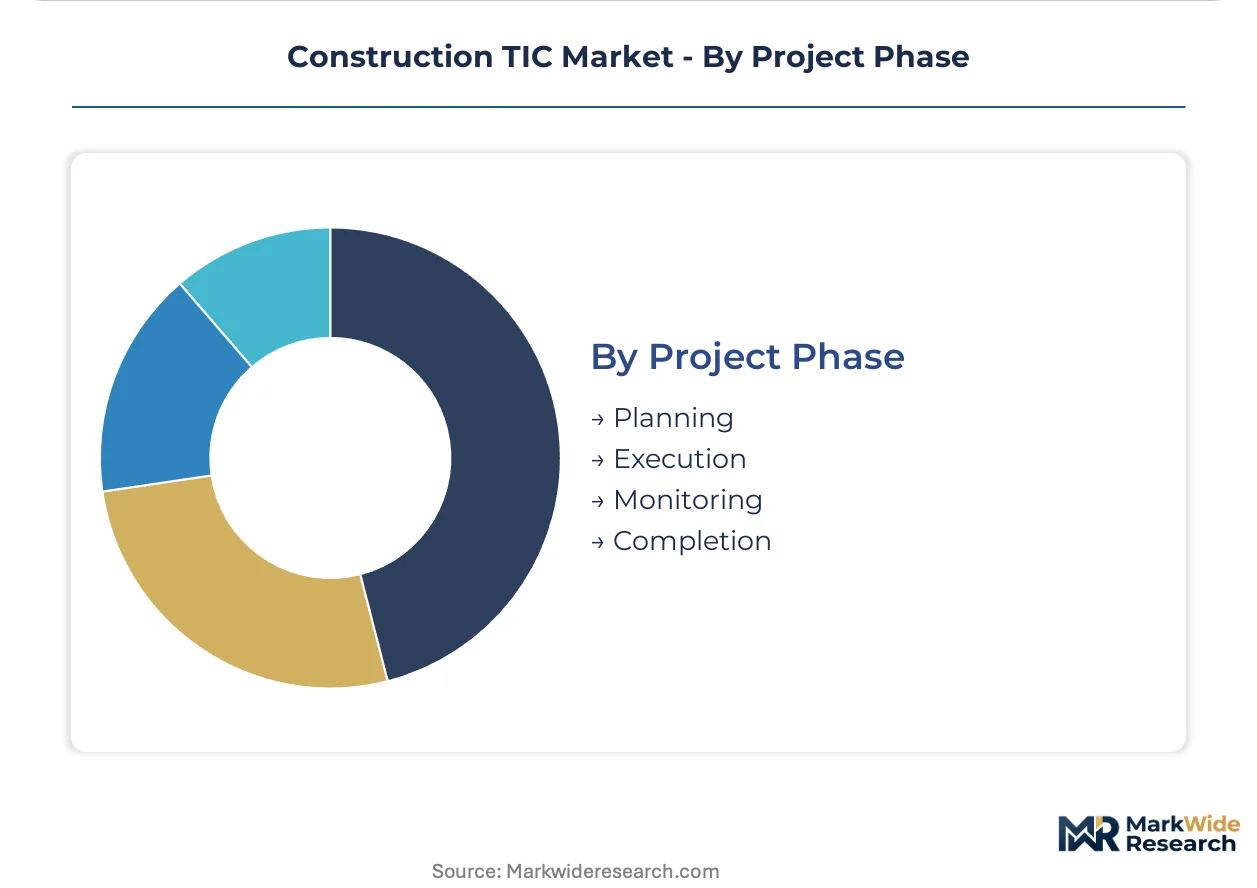
Project Phase:
Revenue recognition timing shifts dramatically across phases, with planning and completion work front-loaded and back-loaded respectively against long execution-phase testing programs.
- Planning:Pre-construction risk assessment and design validation through digital twin integration. EU CSRD scope expansion into built environment disclosure is forcing carbon accounting capabilities into early-phase service bundles.
- Execution:Material batch testing and in-progress weld radiography dominating provider labor deployment. Concrete compression analysis requires capital-heavy laboratory infrastructure that limits scalable provider entry.
- Monitoring:Continuous compliance verification against evolving regulatory thresholds. France's ANSM-linked building codes and Germany's infrastructure standards create jurisdiction-specific competency requirements.
- Completion:Final certification and air permeability testing for building envelope performance. Thermal imaging convergence with blower door protocols is opening premium certification tiers.
Execution absorbs the greatest labor hours. Planning is gaining share fastest as digital twin adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German TIC providers export verification services across Central European infrastructure corridors, while Middle Eastern capital flows draw inspection capacity into Gulf megaproject zones.
Germany
Commercial retrofit cycles and KBA-influenced infrastructure standards drive concentrated demand for embodied carbon verification. The EU Green Deal implementation through national building codes expands third-party inspection mandates. Berlin, Munich, and Hamburg anchor portfolio-scale framework agreements from institutional asset managers.
United States
OSHA workplace safety mandates and EPA environmental impact requirements sustain baseline inspection demand across civil engineering projects. Lender-mandated technical due diligence is tightening as a loan covenant condition. Texas and California infrastructure corridors absorb the greatest laboratory testing capacity for concrete compression and weld radiography.
France
ANSM-linked public health building codes accelerate air permeability testing for high-performance envelopes. The EU CSRD scope expansion into built environment disclosure forces carbon accounting capabilities into service bundles. The Paris metropolitan area concentrates drone-mounted thermal imaging adoption for facade verification.
United Arab Emirates
Gulf state infrastructure investment generates demand for independent verification with limited incumbent provider presence. MOHAP-linked building safety frameworks and municipal construction codes require third-party certification. Dubai and Abu Dhabi megaproject corridors attract TIC capacity from European and Asian providers.
China
Dual carbon goals and GB standards for green building certification expand mandatory inspection scopes. MIIT-influenced infrastructure quality frameworks elevate technical barriers for market access. The Yangtze River Delta and Pearl River Delta urban clusters concentrate demand for structural health monitoring and digital twin integration.
Construction TIC Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base stratifies into three tiers: global laboratory networks commanding portfolio-scale contracts, regional specialists dominating niche certifications, and emerging technology-focused entrants embedding digital verification tools. Scale-driven players pursue cross-border laboratory acquisitions. Technology-forward competitors prioritize Building Information Modeling integration partnerships.
Within the global network tier, SGS and Bureau Veritas exemplify archetypes of geographic breadth and technical specialization respectively. Intertek Group occupies a position emphasizing Middle Eastern corridor penetration. These three listed entities anchor competitive dynamics through divergent strategic postures rather than convergent imitation.
| Leading Market Players |
|---|
| SGS |
| Bureau Veritas |
| Intertek Group |
| TÜV Rheinland |
| DEKRA |
| Applus+ |
| UL Solutions |
| Element Materials Technology |
| TÜV SÜD |
| Others |
Value Chain & Pricing Dynamics
Multi-year framework agreements with institutional asset managers lock in both laboratory capacity access and cost predictability for German commercial retrofit portfolios. These contracts bundle embodied carbon verification with traditional quality control, embedding price visibility across recertification cycles triggered by KBA-influenced infrastructure standards.
Pricing Analysis
Manual inspection protocols versus drone-mounted thermal imaging versus AI-integrated digital twin platforms stratify service pricing across technology generations. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced predictive analytics from conventional radiographic weld testing from baseline material batch screening. Cost compression in standard-tier concrete compression analysis is intensifying because radiographic technician scarcity elevates labor premiums. Contractor procurement teams exhibit the highest price sensitivity, while private infrastructure funds accept premium pricing for portfolio-scale compliance bundling.
Supply Chain Analysis
Radiographic equipment manufacturing concentrates in Germany, the United States, and Japan, creating procurement bottlenecks for emerging market laboratory buildouts. Construction TIC providers draw from specialized sensor component suppliers, certified reference material producers, and drone hardware manufacturers. Single-source vulnerability in radiographic film and digital detector supply exposes providers to input cost volatility. Distribution runs through direct sales teams for developer framework agreements and regional agent networks for contractor project procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction TIC demand tracks infrastructure investment cycles, with commercial retrofit acceleration in Germany signaling recovery momentum from post-pandemic project delays.
For Market Incumbents: Secure radiographic technician pipelines through VR-based training partnerships to offset qualification scarcity constraining expansion velocity. Deepen backward integration into drone hardware maintenance capabilities to defend margin position against equipment rental cost escalation. Anchor certification investment in EU CSRD carbon accounting competencies before whole-life auditing mandates restructure service mix priorities. For New Entrants and Emerging Players: Anchor in Middle Eastern megaproject corridors where Gulf state infrastructure investment outruns incumbent laboratory network coverage. Target air permeability testing convergence as the most penetrable niche, bundling thermal imaging with blower door protocols for high-performance envelope certification. Pursue BIM integration partnerships as the primary go-to-market angle, embedding inspection checkpoints into architect workflows before physical ground breaks. For Investors and Strategic Acquirers: Regional specialists with marine and industrial certification expertise in coastal clusters offer consolidation targets as asset managers consolidate vendor relationships. Long-term viability hinges on carbon accounting capability buildout alongside structural engineering cores. Monitor which regulatory bodies next mandate whole-life carbon auditing as the inflection indicator for service mix restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Capability Buildout | EU CSRD scope expansion into built environment disclosure forces competency diversification beyond traditional safety parameters. |
| Drone Hardware Integration Partnership | Institutional asset managers in France mandate aerial thermographic surveys as loan covenant compliance conditions. |
| Radiographic Technician Training Program | Supply constraints for qualified weld inspectors elevate simulation-based competency development premiums. |
| BIM Platform Embedding | Digital twin integration creates pre-construction revenue streams before physical project phases commence. |
| Middle Eastern Laboratory Expansion | Gulf state megaproject corridors attract TIC capacity with limited incumbent provider presence. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with institutional asset managers, commercial retrofit contractors, radiographic technicians, and BIM platform engineers. Secondary validation drew from EU CPR regulatory filings, KBA infrastructure standards documentation, ANSM building code implementations, and SEC disclosures from listed TIC providers. Bottom-up project pipeline analysis and top-down regulatory mandate sizing were triangulated to establish market boundaries.
Across the projection horizon, the analytical framework modeled service type segmentation, client archetype procurement patterns, technology adoption curves, and project phase revenue timing. CAGRs were derived from regression analysis against infrastructure investment flows and regulatory compliance obligation layering. Carbon disclosure mandate expansion rates and commercial retrofit cycle frequencies served as industry-specific forecast inputs.
Material uncertainties — regulatory timeline delays, radiographic technician supply constraints, BIM platform interoperability failures — sit outside the modeled envelope. Forecasts reflect assumptions about EU Green Deal implementation velocity and national building code adoption patterns. Practitioners should keep alternative scenarios live as whole-life carbon auditing mandate announcements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Hardbanding Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Dust Suppression Control Market
Construction Services
Condenser Cleaners Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Train Contractor Market
Construction Services
MENA Architectural Services Market
Construction Services
Industrial Maintenance Products Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Excavating Contractor Market
Construction Services
Construction Project Management Services Market
Construction Services
Grease Trap Service Market