
 Forklift Repair and Maintenance Service Market | 2026-2036
Forklift Repair and Maintenance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Repair and Maintenance Service Market Insights
Third-party logistics providers are rotating toward predictive maintenance contracts as fleet uptime becomes a competitive metric. Equipment Depot leverages its authorized service center network to anchor regional coverage in the Midwest. Black Equipment competes through specialized electric forklift battery diagnostics and charging infrastructure repair. Alta Material Handling dominates direct service contracts with large manufacturing facilities requiring 24-hour response guarantees.
Forklift repair and maintenance service encompasses scheduled inspection, component replacement, hydraulic system refurbishment, and electronic control module calibration to sustain material handling equipment operational readiness. Preventive maintenance commands the largest share of service revenue due to mandatory compliance intervals, while predictive maintenance represents the fastest-expanding category as telematics-enabled condition monitoring reduces unplanned downtime. Electric forklift service generates premium pricing compared to internal combustion units because high-voltage battery management systems require certified technician labor and specialized diagnostic equipment.
OSHA mandates periodic operator training and equipment inspection standards that directly shape service scheduling frequency and documentation requirements for warehouse and manufacturing employers. The EPA regulates diesel emissions from forklift engines, pushing fleet operators toward electric conversions that demand different technician skill sets and service infrastructure. Stakeholders must monitor how battery recycling regulations and technician certification requirements will reshape service provider capabilities and pricing structures.
Market Dynamics
Electric forklift battery management systems are forcing a wholesale technician certification overhaul as high-voltage servicing requirements collide with shrinking qualified labor pools across warehouse automation hubs.
Growth Catalysts
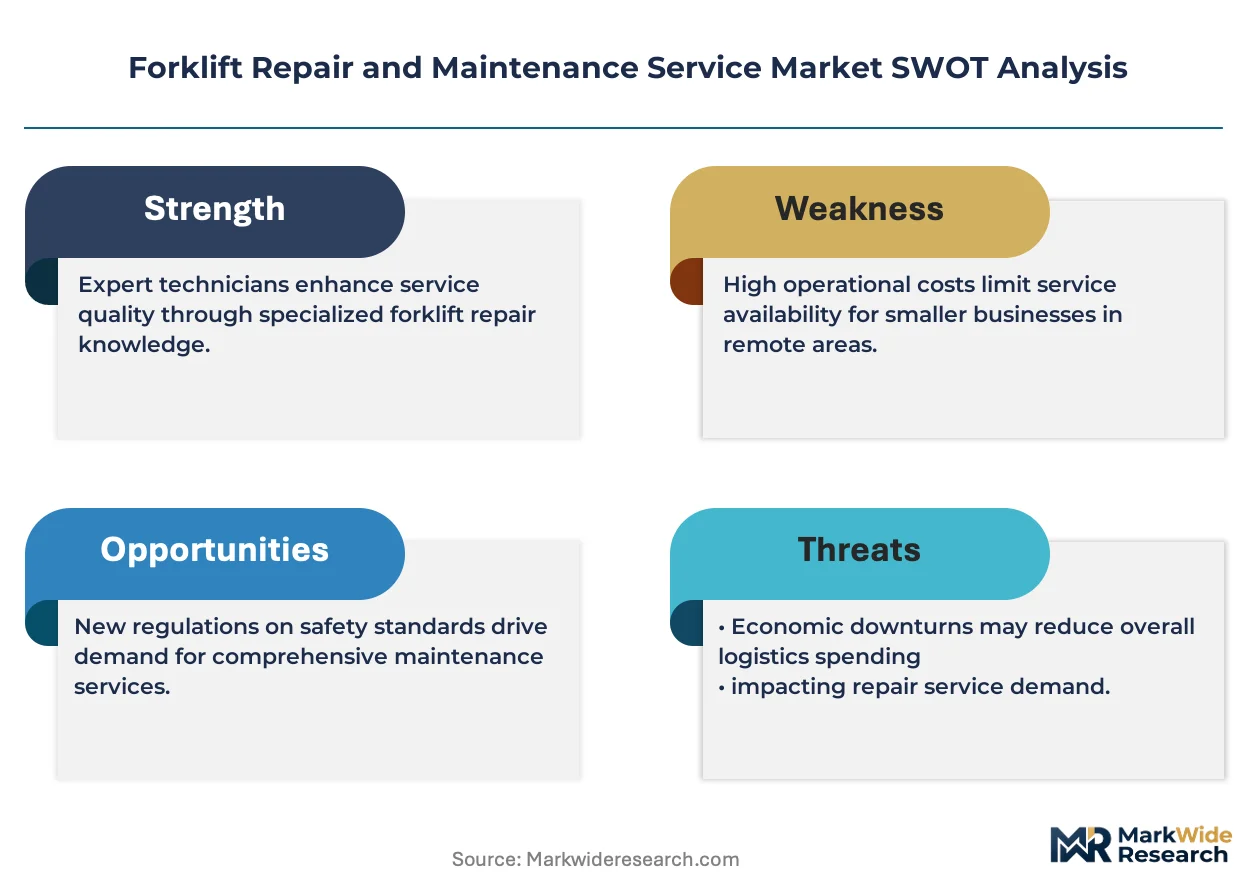
- OSHA workplace safety mandates:Mandatory inspection intervals and documentation standards compel warehouse operators to expand scheduled service contracts, directly lifting preventive maintenance revenue.
- E-commerce fulfillment centers:These facilities are accelerating fleet electrification timelines to meet corporate carbon targets, creating specialized demand for battery diagnostics and charging infrastructure repair.
- Telematics-enabled condition monitoring:Real-time equipment health data is enabling predictive maintenance adoption, reducing unplanned downtime and extending contract durations with third-party logistics providers.
Market Restraints
- Certified technician scarcity:High-voltage battery certification programs require 18-24 month completion timelines, constraining service provider expansion capacity in electric forklift segments.
- Specialized diagnostic equipment costs:Battery management system analyzers and charging station test rigs carry capital outlays that compress margins for independent repair shops.
- Diesel fleet residual value uncertainty:EPA emissions enforcement variability creates hesitation among operators regarding timing of internal combustion replacements, delaying maintenance contract upgrades.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for manufacturing and logistics infrastructure are driving forklift fleet growth where authorized service networks remain underdeveloped.
- Battery recycling regulation compliance:Emerging state-level hazardous waste rules for lithium-ion disposal create ancillary revenue streams for service providers with certified recycling partnerships.
- Telematics-AI convergence:Integration of machine learning with fleet management platforms enables outcome-based uptime guarantees, differentiating premium service tiers.
Industry Challenges
- Legacy system integration complexity:Retrofitting telematics hardware onto aging diesel fleets requires custom firmware solutions that strain technician training resources.
- Multi-brand certification burden:OEM-specific diagnostic protocols force independent service providers to maintain redundant training programs and proprietary tool inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Repair and Maintenance Service Market |
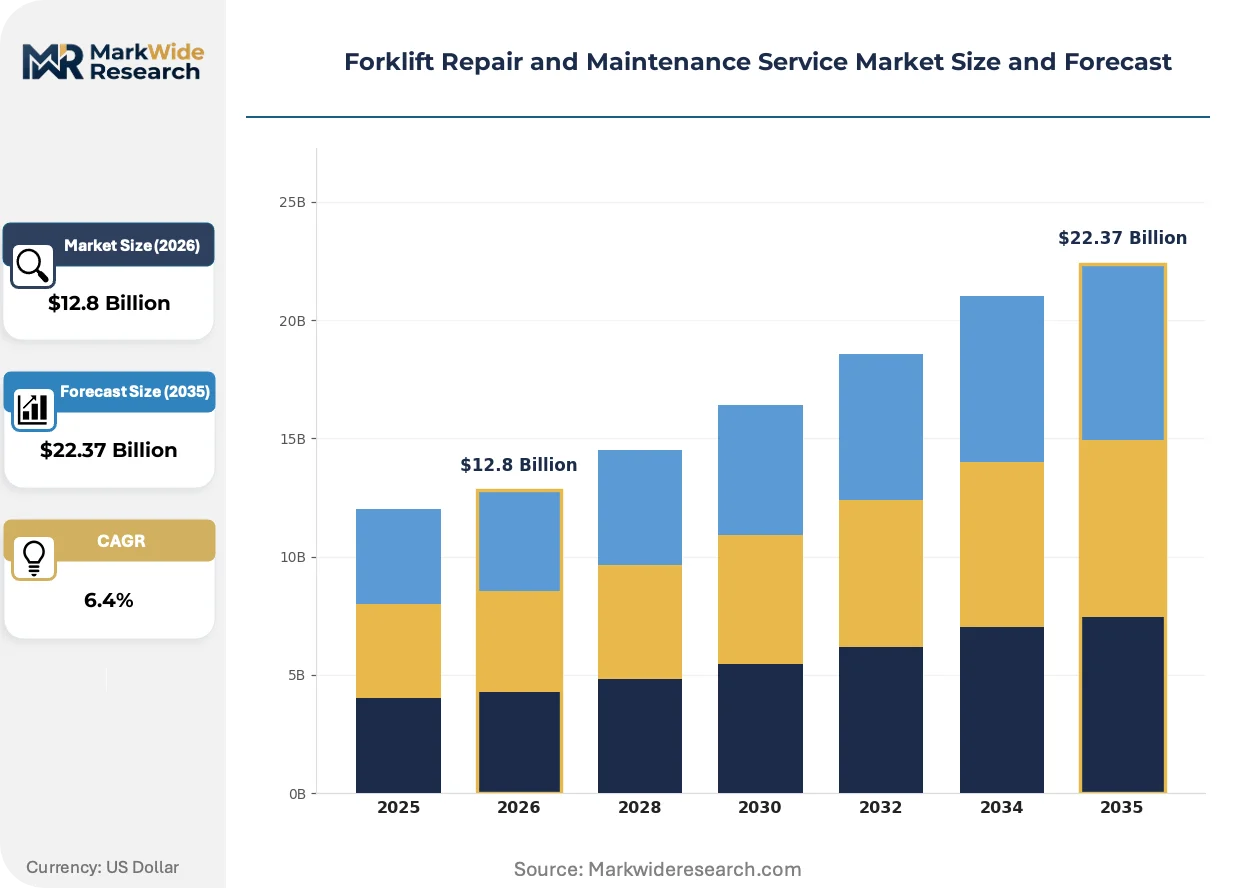
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Inspection, Emergency Repair, Preventive Maintenance, Predictive Maintenance, Overhaul Equipment Type: Electric Forklift, Diesel Forklift, LPG Forklift, Narrow Aisle Truck, Pallet Jack Customer Type: Warehouse Operators, Distribution Centers, Manufacturing Facilities, Logistics Providers, Construction Firms Distribution Channel: Direct Service Contracts, Authorized Service Centers, Third-party Repair Shops, On-site Maintenance, Remote Diagnostics |
| Companies Covered | Black Equipment, Alta Material Handling, Equipment Depot, Heubel Material Handling, Complete Forklift Repair, The Raymond Corporation, Cardinal Carryor, Cardinal Integrated Systems, Concentric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Repair and Maintenance Service Market Trends and Innovations
Service delivery models are compressing toward real-time responsiveness as fleet uptime metrics become contractual penalties rather than aspirational targets.
Telematics platforms are fragmenting the traditional break-fix service model by embedding continuous monitoring directly into forklift operating systems. Third-party logistics providers now demand sub-hour alert-to-technician dispatch protocols, compressing competitive differentiation around geographic density rather than technical breadth. Regional service networks are consolidating to meet these coverage requirements, squeezing independent operators without multi-state presence.
EPA diesel emissions enforcement is tightening compliance windows for fleet operators in California and the Northeast corridor. Manufacturing facilities with aging internal combustion fleets face accelerated replacement timelines or costly exhaust after-treatment retrofits. Electric conversion projects are concentrating in these jurisdictions, pulling technician training investment toward high-voltage battery competencies and away from engine rebuild specialization.
Outcome-based uptime contracts are displacing hourly labor billing across large manufacturing accounts. Facilities with 24-hour production schedules now specify equipment availability percentages rather than response-time guarantees, transferring operational risk to service providers. This shift is most pronounced in automotive and food processing verticals where line stoppage costs exceed preventive maintenance premiums by an order of magnitude.
Forklift Repair and Maintenance Service Market Segmentation
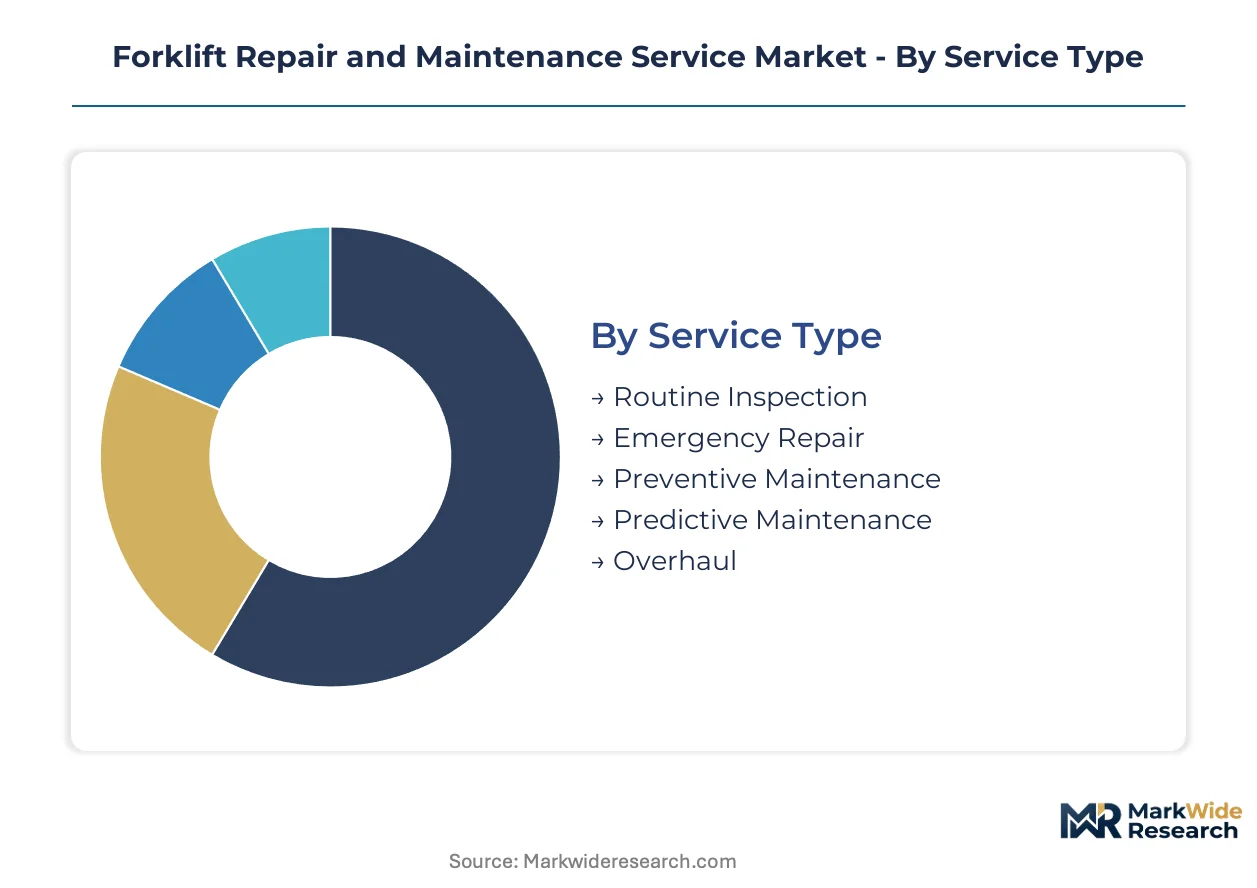
Service providers must align technician certifications and diagnostic capabilities with distinct operational demands across forklift fleet profiles. Each segmentation dimension reveals divergent margin structures and competitive intensity patterns.
Service Type:
Predictive maintenance platforms face the strongest substitution pressure as telematics vendors bundle software-as-a-service offerings that erode standalone diagnostic contracts.
- Routine Inspection:OSHA-mandated safety checks covering mast assemblies, braking systems, and load backrests. Warehouse operators in California and Texas concentrate compliance spending here due to state-level enforcement intensity.
- Emergency Repair:Unplanned breakdown response requiring 24-hour technician dispatch. Food processing facilities in the Midwest pay premium rates for guaranteed uptime restoration.
- Preventive Maintenance:Scheduled component replacement and fluid servicing. Distribution centers prioritize these contracts to avoid peak-season equipment failures.
- Predictive Maintenance:Condition-based intervention using vibration analysis and thermal imaging. Third-party logistics providers adopt this fastest to compress fleet downtime metrics.
- Overhaul:Complete drivetrain and hydraulic system rebuilds. Aging diesel fleets in manufacturing strongholds sustain residual demand despite electrification headwinds.
Preventive maintenance retains volume leadership; predictive maintenance holds the steepest expansion curve.
Equipment Type:
Cost tier stratification separates premium high-voltage service from commoditized internal combustion support.
- Electric Forklift:High-voltage battery management systems and charging infrastructure repair. E-commerce fulfillment centers in Georgia and Pennsylvania drive specialized technician demand.
- Diesel Forklift:Engine rebuild and exhaust after-treatment servicing. EPA enforcement corridors in the Northeast accelerate fleet replacement over repair decisions.
- LPG Forklift:Fuel system diagnostics and emissions compliance. Construction firms in Florida and Arizona maintain steady service volumes.
- Narrow Aisle Truck:Precision guidance system calibration for high-density storage. Cold storage warehouses require frequent mast and reach mechanism adjustment.
- Pallet Jack:Hydraulic pump and steer wheel replacement. Low-margin high-velocity segment dominated by parts-plus-labor retail models.
Electric forklift service commands premium pricing tiers; diesel forklift maintenance contracts face margin compression from regulatory uncertainty.
Customer Type:
Application-specific uptime requirements fragment service provider specialization across vertical workflows.
- Warehouse Operators:Multi-shift fleet management with seasonal volume spikes. Automated storage facilities in Illinois and Ohio demand integrated telematics support.
- Distribution Centers:Cross-dock intensity with sub-hour downtime tolerance. Same-day delivery networks prioritize geographic coverage density over technical breadth.
- Manufacturing Facilities:Line-integrated material handling with 24-hour production schedules. Automotive plants specify outcome-based availability guarantees.
- Logistics Providers:Asset-light fleet models relying on third-party maintenance networks. Regional consolidation pressures independent service shops.
- Construction Firms:Rough-terrain equipment exposure and mobile service requirements. Equipment rental companies intermediate service procurement.
Manufacturing facilities generate the highest contract values; logistics providers are expanding service outsourcing fastest.
Distribution Channel:
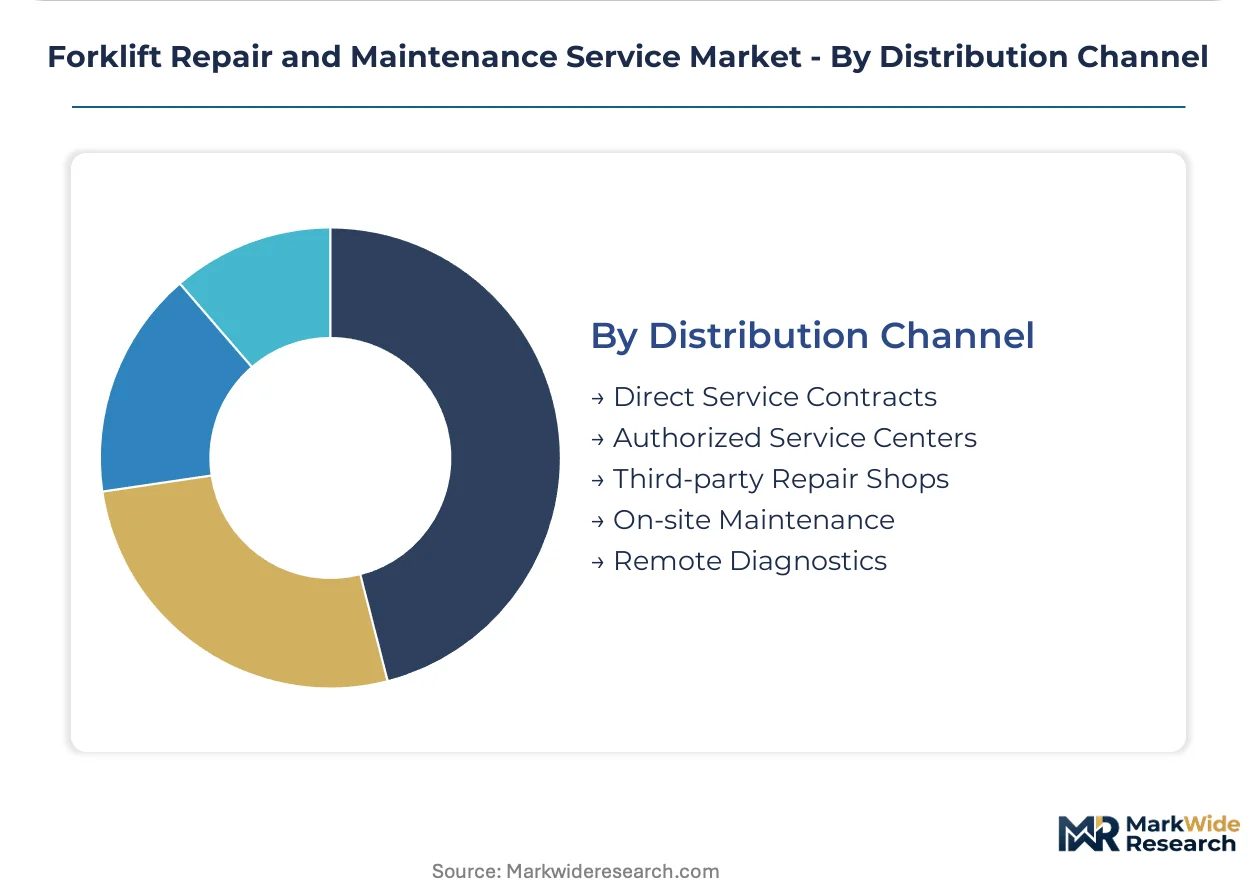
Customer type concentration shapes channel profitability as direct contracts capture enterprise accounts while fragmented channels serve smaller fleets.
- Direct Service Contracts:Bespoke agreements with dedicated technician assignment. Large manufacturing accounts in Michigan and Wisconsin anchor provider revenue stability.
- Authorized Service Centers:OEM-certified repair with genuine parts sourcing. Electric forklift battery warranty compliance mandates this channel for fleet operators.
- Third-party Repair Shops:Independent operators competing on labor rates. Diesel and LPG segments remain accessible without proprietary diagnostic tools.
- On-site Maintenance:Embedded technician programs for high-fleet-density locations. Multi-building campus operations in North Carolina adopt this model.
- Remote Diagnostics:Telematics-enabled fault code interpretation and parts pre-positioning. Predictive maintenance contracts increasingly bundle this capability.
Direct service contracts dominate revenue concentration; remote diagnostics capabilities are scaling fastest among channel investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites Europe's densest forklift service network, while the Union Pacific rail corridor anchors North American material handling density.
United States
Warehouse automation investments in Illinois and Ohio drive preventive maintenance contract expansion. OSHA mandates periodic equipment inspection standards that compel multi-shift facilities to expand scheduled service agreements. The Detroit automotive corridor specifies outcome-based uptime guarantees that transfer operational risk to service providers.
Germany
Industrial machinery clusters in Bavaria and Baden-Württemberg sustain premium overhaul demand for aging diesel fleets. The KBA enforces emissions compliance windows that accelerate electric conversion timelines. Stuttgart's automotive suppliers embed certified technicians on-site to meet 24-hour production schedules.
China
E-commerce fulfillment center construction in the Yangtze River Delta generates specialized battery management service demand. MIIT's dual carbon goals push fleet operators toward electric models requiring high-voltage technician certification. Shenzhen's robotics integrators bundle predictive maintenance with automated storage system deployments.
India
PLI scheme incentives for manufacturing infrastructure drive forklift fleet growth in Maharashtra and Gujarat. The country's national workplace safety regulator mandates operator training documentation that shapes service scheduling frequency. Bangalore's logistics parks remain underserved by authorized service networks.
Japan
Precision manufacturing facilities in the Chubu region demand narrow aisle truck calibration services. METI's industrial efficiency standards promote telematics-enabled condition monitoring adoption. Nagoya's automotive parts suppliers specify sub-hour technician dispatch protocols for line-integrated material handling.
Forklift Repair and Maintenance Service Market Competitive Landscape
Concentration sits with OEM-authorized service networks that leverage proprietary diagnostic protocols to anchor regional coverage. Independent operators compete on labor rates in diesel and LPG segments where specialized equipment requirements remain minimal. Two strategic archetypes dominate: multi-state networks pursuing geographic density for uptime guarantees, and battery specialists capturing premium pricing from electrification mandates. Consolidation pressures independent shops without multi-state presence, while vertical integration into charging infrastructure repair creates differentiation for electric-focused providers.
Among North American service networks, Equipment Depot anchors Midwest coverage through its authorized center footprint, while Alta Material Handling occupies a position serving large manufacturing accounts with dedicated technician assignment. Black Equipment exemplifies the battery specialization archetype, capturing premium segments as fleet electrification accelerates. These three represent distinct competitive vectors: geographic density, direct enterprise contracting, and technical specialization in high-voltage systems.
| Leading Market Players |
|---|
| Black Equipment |
| Alta Material Handling |
| Equipment Depot |
| Heubel Material Handling |
| Complete Forklift Repair |
| The Raymond Corporation |
| Cardinal Carryor |
| Cardinal Integrated Systems |
| Concentric |
| Others |
Pricing and Supply Chain Analysis
High-voltage battery management systems replacing legacy engine rebuild specialization are simultaneously redrawing technician labor geography toward OSHA-certified training hubs and compressing pricing premiums for diesel maintenance contracts. This substitution dynamic concentrates service provider investment in electric forklift capabilities while eroding margins for internal combustion expertise.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures. Premium tiers attach to 24-hour response guarantees and certified high-voltage battery diagnostics, while economy tiers cover routine OSHA-mandated inspections. Price differentiation hinges on technician certification grade and geographic coverage density. Cost compression in diesel maintenance is intensifying because EPA emissions uncertainty accelerates fleet replacement over repair decisions. Distribution centers with sub-hour downtime tolerance exhibit lowest price sensitivity; independent repair shops in fragmented LPG segments face highest sensitivity.
Supply Chain Analysis
Certified technician training capacity in the United States, Germany, and China constitutes the primary chokepoint constraining service network expansion. Battery management system analyzers and charging station test rigs draw from precision electronics manufacturing clusters in South Korea and Japan. Single-source vulnerability sits with proprietary OEM diagnostic software licenses that independent providers must maintain across multiple brands. Distribution runs through authorized service center networks for warranty-compliant electric forklift support, while third-party channels handle commoditized diesel and LPG segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a capital equipment replacement cycle as aging diesel fleets face accelerated EPA compliance deadlines. Warehouse automation investments and e-commerce fulfillment center expansion provide cyclical uplift.
For Market Incumbents: Shield core manufacturing account relationships by embedding certified technicians on-site for 24-hour production schedules. Deepen backward integration into charging infrastructure repair capabilities before battery specialists capture electrification premiums. Consolidate regional coverage density through multi-state network expansion to meet sub-hour dispatch protocols demanded by third-party logistics providers.
For New Entrants and Emerging Players: Anchor in India's underdeveloped authorized service networks where PLI scheme incentives drive forklift fleet growth without matching technician capacity. Target battery recycling compliance services as emerging state-level hazardous waste rules create ancillary revenue streams. Pursue telematics-AI convergence partnerships to differentiate predictive maintenance offerings against established break-fix incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional service networks lacking electric forklift certification infrastructure. Long-term viability favors providers with captive high-voltage technician training pipelines and multi-brand diagnostic tool inventories. Monitor OSHA workplace safety mandate enforcement intensity as the signal indicating preventive maintenance contract expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Certification Investment | OSHA-mandated battery servicing requirements create barrier against unqualified competitors. |
| Telematics Platform Integration | Real-time fleet monitoring enables outcome-based uptime guarantees for automotive manufacturers. |
| Charging Infrastructure Repair Capability | E-commerce fulfillment center electrification timelines demand specialized service bundling. |
| Geographic Network Consolidation | Multi-state coverage density satisfies third-party logistics provider dispatch protocols. |
| Battery Recycling Partnership Certification | State-level lithium-ion disposal regulations unlock ancillary compliance revenue streams. |
Research Methodology
A standing panel of maintenance directors, fleet operations managers, OEM aftermarket service heads, and third-party logistics procurement leads provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with facility engineers and channel partners against secondary validation through OSHA enforcement records, EPA emissions compliance databases, and customs data on diagnostic equipment imports. Bottom-up service contract analysis and top-down fleet penetration modeling were triangulated to cross-validate market sizing.
Consistency checks against external benchmarks verified projection outputs across the analysis window. The analytical framework modeled segmentation dimensions including service type, equipment propulsion architecture, customer vertical, and regional regulatory cluster. CAGRs were derived from technician capacity expansion rates, fleet electrification timelines, and contract renewal velocity. Industry-specific inputs incorporated OSHA inspection interval mandates, EPA enforcement corridor identification, and telematics adoption curves by warehouse automation tier.
Decision-makers should treat outputs as directional under assumptions of steady OSHA workplace safety mandate enforcement and continued EPA emissions compliance tightening; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding technician certification program completion timelines and electric forklift fleet conversion rates. Practitioners should keep alternative scenarios live as battery recycling regulation evolution and telematics-AI convergence maturity reshape service provider capability requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Industrial Maintenance Services Market
Construction Services
NDT and Inspection Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Train Contractor Market
Construction Services
Dust Suppression Control Market
Construction Services
Construction TIC Market
Construction Services
Excavating Contractor Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
MENA Architectural Services Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Testing, Inspection, and Certification for Construction Market