

Bathroom Remodeling Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Remodeling Market Insights
The EPA WaterSense certification program is realigning fixture procurement across the residential renovation channel. Kohler Co. leverages its vertically integrated casting and finishing operations to maintain specification rates in premium bathroom projects. Moen Incorporated anchors its position through channel control at big-box retailers and professional plumbing distributors. American Standard Brands differentiates via R&D intensity in touchless and smart faucet platforms.
Bathroom remodeling encompasses the structural alteration, fixture replacement, and finish upgrading of existing residential and commercial washroom spaces, typically involving plumbing rough-in modifications, waterproofing membrane installation, and surface material substitution with specifications such as 1/4-inch per foot shower pan slope for drainage compliance. Its primary commercial purpose centers on property value preservation, functional modernization, and energy or water efficiency compliance. Shower enclosures and vanities capture disproportionate margin pools as homeowners prioritize spa-like aesthetics and storage optimization. Faucets represent the fastest-growing product category as touchless and thermostatic technologies penetrate mid-market renovation budgets. Ceramic and porcelain materials dominate volume, though quartz surfaces are gaining specification share in vanity tops for durability and design flexibility.
EPA WaterSense, the U.S. Department of Energy appliance efficiency standards, and state-level plumbing codes collectively shape product eligibility and contractor compliance burdens across the American market. The DOE standards mandate maximum flow rates for showerheads and faucets, effectively filtering non-compliant imports from retail shelves. Contractors and distributors must monitor evolving federal efficiency timelines alongside patchwork state amendments to avoid specification conflicts and inventory obsolescence.
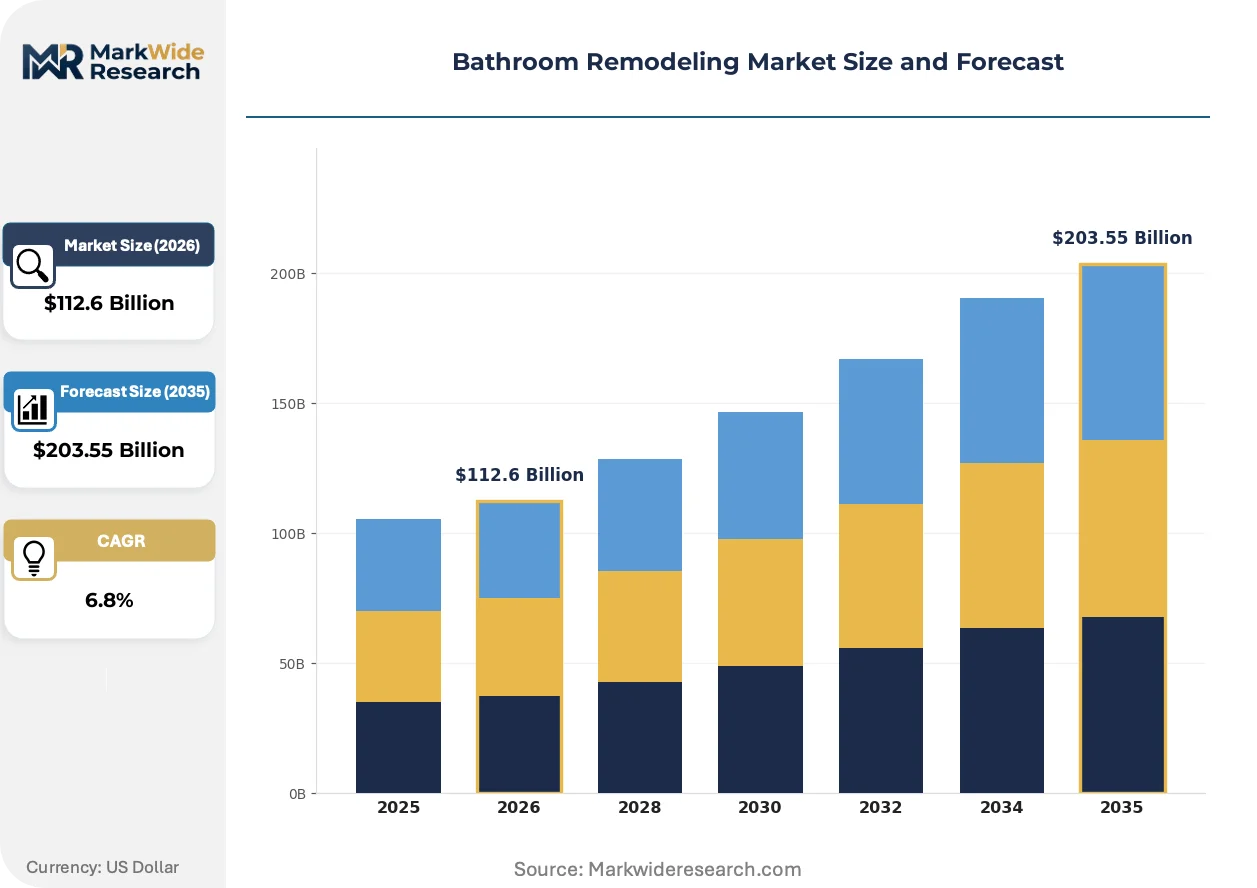
Market Dynamics
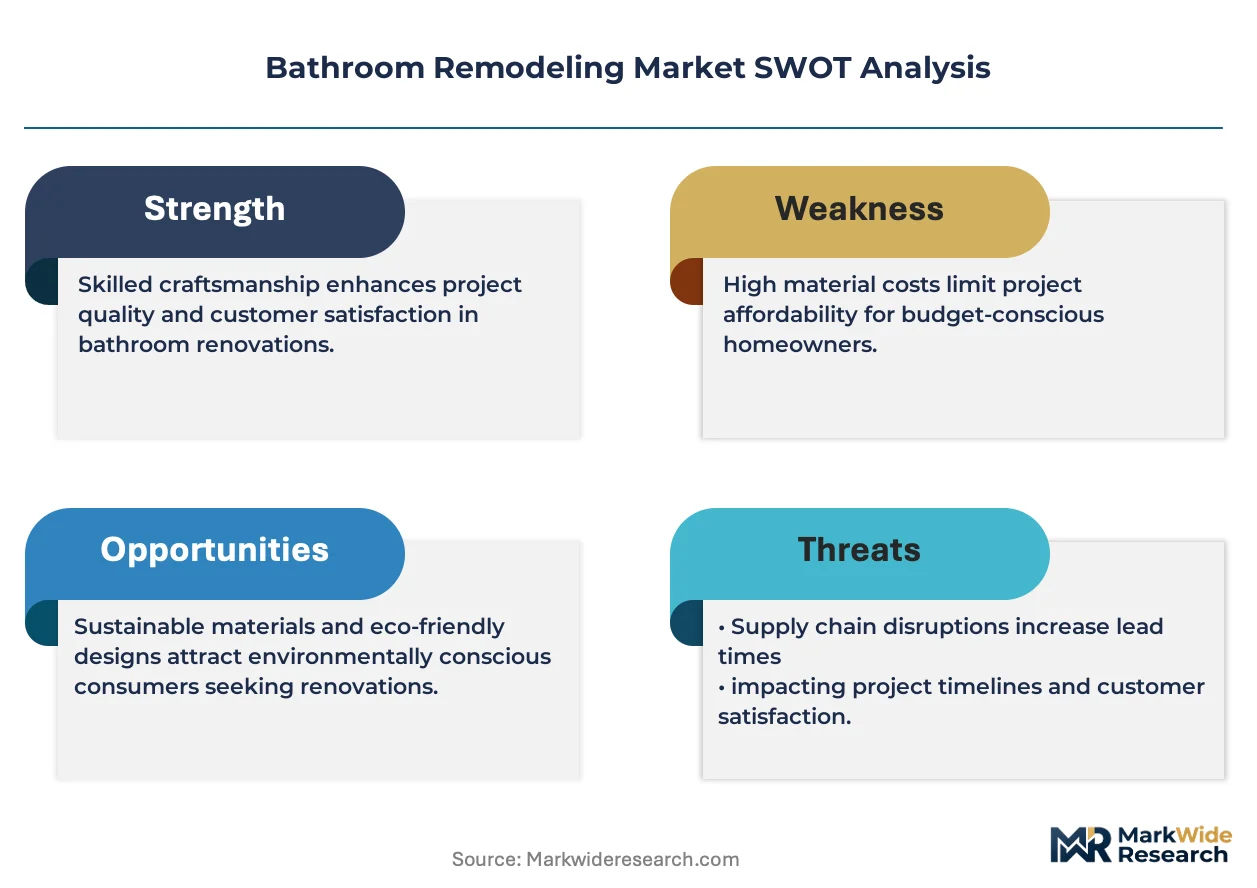
Water efficiency mandates are compressing product development cycles as manufacturers must certify fixtures against tightening EPA WaterSense and DOE flow-rate ceilings before legacy inventory clears distribution channels.
Growth Catalysts
- EPA WaterSense Certification:Federal procurement preferences and rebate programs in water-stressed municipalities accelerate specification of certified low-flow showerheads and faucets in renovation projects.
- Aging US Housing Stock:Over sixty million American homes built before 1990 require functional bathroom upgrades, creating replacement demand independent of discretionary spending cycles.
- Quartz Surface Technology:Engineered stone vanity tops deliver superior stain resistance and seam visibility versus natural marble, capturing specification share in mid-market and premium residential renovations.
Market Restraints
- Copper and Brass Input Volatility:Fixture manufacturers face margin pressure from London Metal Exchange price swings in copper alloy feedstocks used for faucet bodies and valve cartridges.
- Import Supply Concentration:Ceramic tile and vitreous china production clusters in specific coastal Chinese provinces expose distributors to ocean freight rate spikes and customs processing delays.
- Shower Pan Slope Technical Limitation:The 1/4-inch per foot drainage mandate in IPC and UPC codes restricts design flexibility in curbless wet-room conversions, limiting accessible aging-in-place retrofit penetration.
Strategic Opportunities
- Touchless Technology Convergence:Integration of infrared sensors with thermostatic mixing valves creates premium positioning in commercial and high-end residential specification channels.
- Online Design-to-Order Platforms:Direct-to-consumer vanity configurators bypass traditional showroom intermediaries, capturing margin and reducing specification friction for renovation homeowners.
- State-Level Water Rebate Programs:California Turf Replacement and similar municipal incentive schemes subsidize fixture upgrades, expanding addressable market in drought-affected western states.
Industry Challenges
- Licensed Plumber Talent Scarcity:Journeyman certification backlogs and vocational training pipeline gaps extend project timelines and inflate labor cost components in major metropolitan markets.
- WaterSense Certification Timeline:Third-party testing laboratory capacity constraints delay product launch windows, forcing manufacturers to commit inventory before final approval.
- Legacy Drain Rough-In Compatibility:Retrofit fixture installations encounter slab-on-grade concrete obstacles and obsolete cast-iron stack configurations, requiring costly demolition and structural remediation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Remodeling Market Trends and Innovations
Smart fixture integration and surface material substitution are redefining specification hierarchies as homeowners prioritize hygiene automation and maintenance reduction over traditional aesthetic markers.
Thermostatic digital shower systems is consolidating control interfaces into single-valve platforms with preset temperature memory and smartphone connectivity. High-end residential buyers and boutique hospitality developers specify these systems at accelerating rates. The technology is consolidating multiple mechanical components into sealed cartridge assemblies, compressing aftermarket repair revenue for traditional plumbing distributors.
DOE appliance efficiency standards are tightening maximum flow-rate thresholds for showerheads and faucets, effectively delisting non-compliant imports from retail shelves. Manufacturers must redesign aerator geometries and valve orifices to maintain perceived performance at reduced volumes. The regulatory pressure concentrates specification friction in the mid-market renovation segment where price sensitivity conflicts with compliance costs.
Homeowner specification behavior is fragmenting across channel types as design inspiration migrates to visual platforms while purchasing executes through divergent fulfillment modes. Big-box retailers capture volume transactions for standardized vanities and faucets, while specialty showrooms retain complex shower enclosure and custom surface specification. The behavioral split is most pronounced in coastal metropolitan markets with established design-build contractor networks and mature online fulfillment infrastructure.
Bathroom Remodeling Market Segmentation
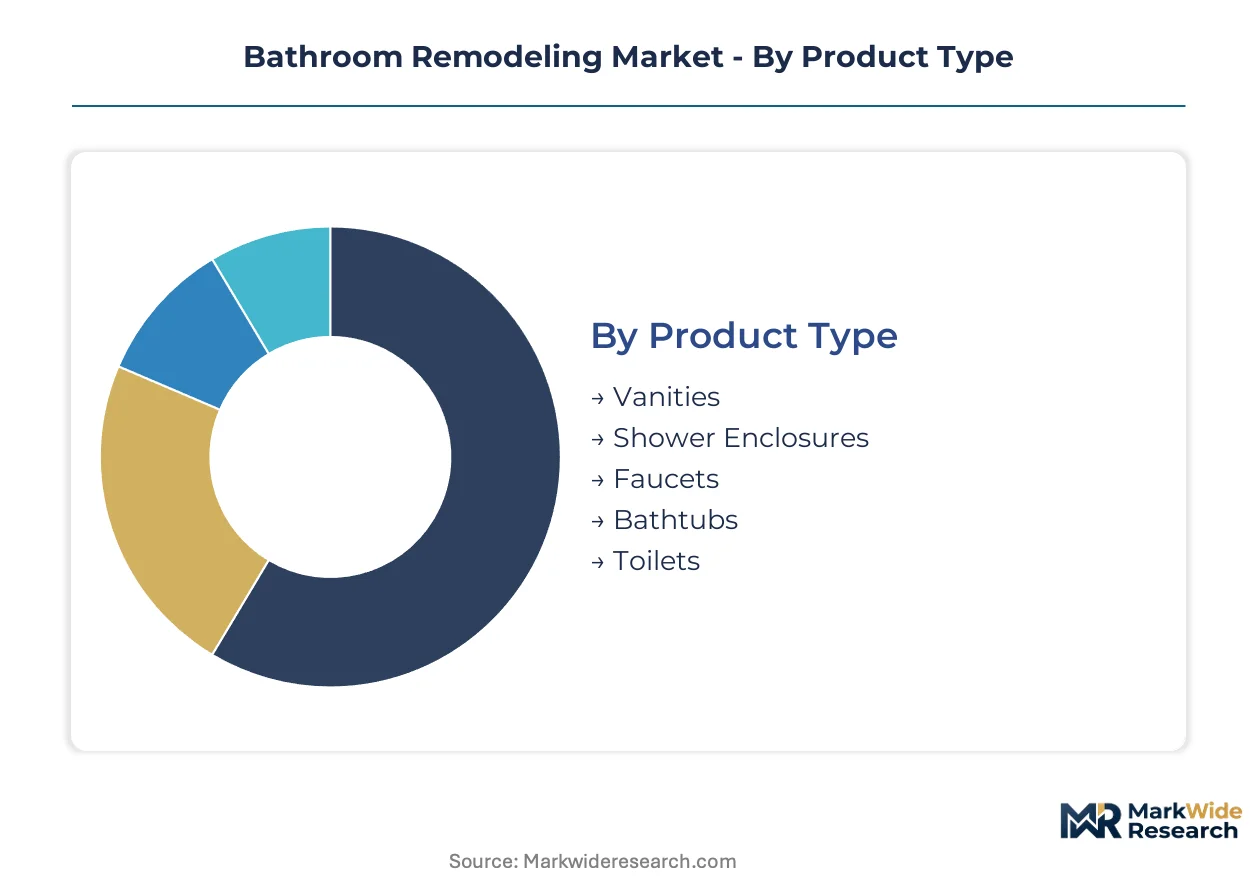
Bathroom remodeling procurement splits across four structural dimensions that determine specification authority, margin capture, and regulatory exposure. Product type dictates WaterSense certification requirements, while material selection governs supply chain risk and installation labor intensity.
Product Type:
EPA WaterSense certification burdens concentrate in water-delivery fixtures, while structural products face ICC/UPC code compliance and moisture-barrier standards.
- Faucets:Thermostatic and touchless valve platforms require WaterSense flow-rate certification and DOE appliance efficiency testing. Demand clusters in residential kitchen and bath renovations where rebate programs subsidize low-flow replacement. Leading the category by volume: Vanities. Growing fastest: Faucets.
- Shower Enclosures:Framed, semi-frameless, and frameless glass systems must satisfy tempered glass safety standards and 1/4-inch per foot slope drainage mandates. Hotels and boutique hospitality developers specify frameless systems for premium positioning.
- Vanities:Cabinet and countertop assemblies face CARB Phase 2 formaldehyde emissions standards for composite substrates.
- Bathtubs:Acrylic and cast-iron units require IAPMO/ANSI Z124 compliance for surface durability and structural load ratings.
- Toilets:Gravity-fed and pressure-assisted flush platforms must certify at 1.28 gallons per flush maximum under WaterSense protocols.
Specification gravity tilts toward fixtures with measurable efficiency credentials.
Material:
Cost tier stratification separates premium natural stone from engineered alternatives, with import exposure varying by extraction geography and fabrication cluster concentration.
- Quartz:Engineered stone surfaces combine crushed quartz with resin binders, delivering superior stain resistance and seam visibility versus natural marble. Mid-market residential renovations specify quartz for vanity tops where maintenance reduction outweighs natural stone prestige. Volume leadership: Ceramic. Steepest expansion trajectory: Quartz.
- Ceramic:Fired clay tile and vitreous china dominate volume through cost accessibility and established distribution at big-box retailers. Production clusters in specific coastal Chinese provinces expose distributors to ocean freight volatility.
- Porcelain:Higher-density ceramic with lower water absorption rates satisfies commercial wet-area specifications and freeze-thaw durability requirements.
- Granite:Natural stone extraction concentrates in Brazil and India, with slab fabrication adding lead time and freight cost to project timelines.
- Marble:Carrara and Calacatta varieties retain specification in ultra-premium residential and historic restoration projects despite porosity maintenance burdens.
- Glass:Tempered and laminated glass systems serve shower enclosure and decorative accent applications with strict ICC safety glazing requirements.
Material substitution accelerates where engineered surfaces close the aesthetic gap with natural stone.
Application:
Project type determines specification complexity, with commercial applications demanding ADA compliance and multi-unit phasing coordination.
- Residential Units:Single-family and multifamily owner-occupied renovations drive replacement demand independent of new construction cycles. Aging US housing stock built before 1990 requires functional bathroom upgrades. Dominant by project count: Residential Units. Expanding most quickly: Hotels.
- Hotels:Boutique and select-service properties specify spa-like shower systems and smart fixtures for guest experience differentiation.
- Offices:Commercial restroom modernization emphasizes touchless technology and water efficiency for LEED certification and operational cost reduction.
- Recreational Facilities:Gyms, spas, and athletic venues require moisture-resistant materials and high-traffic durability specifications.
- Educational Centers:K-12 and university renovations prioritize vandal-resistant fixtures and accessibility compliance under ADA Title II.
Commercial applications concentrate specification authority with facilities managers and design-build contractors.
Customer Type:
Procurement authority fragments across channel types, with direct-to-consumer platforms capturing share from traditional showroom intermediaries.
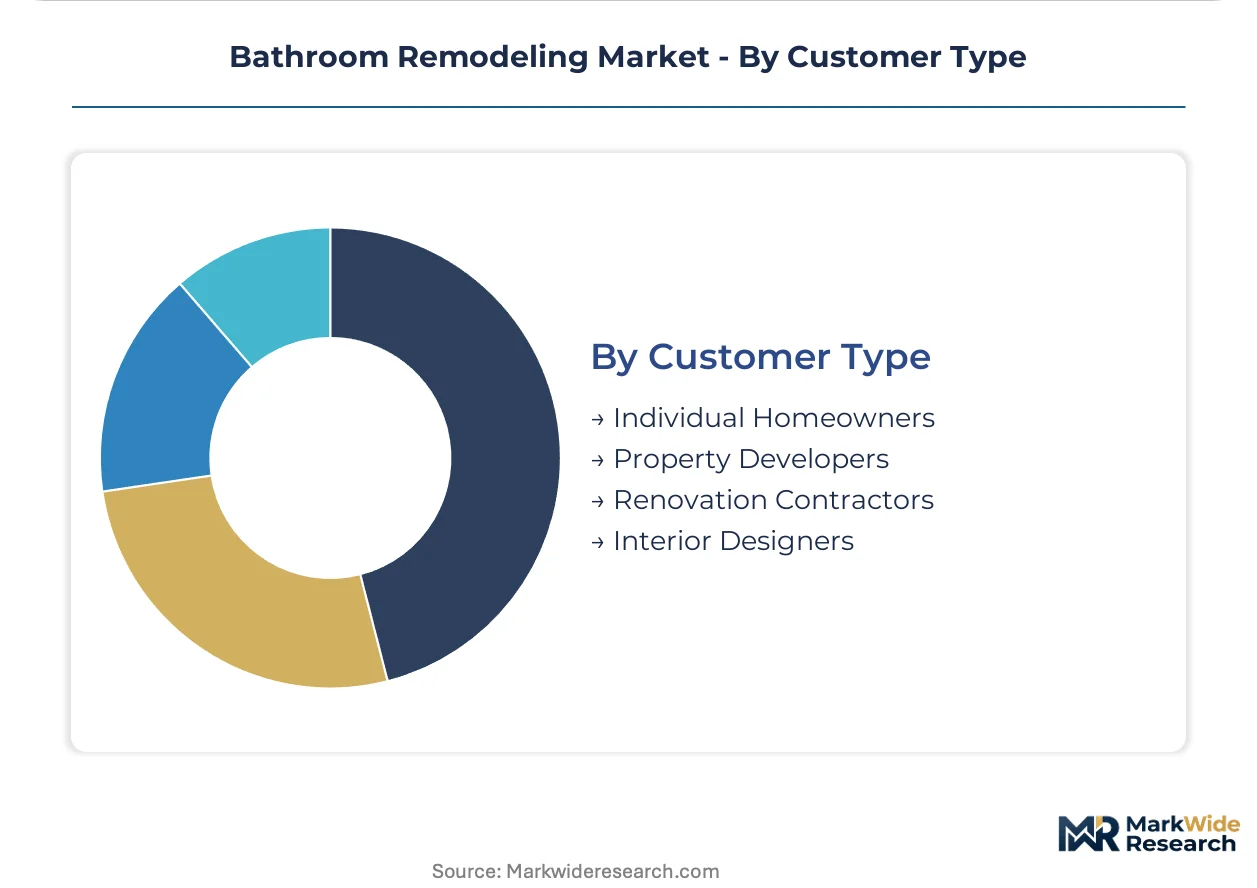
- Individual Homeowners:End-users research design inspiration through visual platforms while executing purchases through divergent fulfillment modes. Big-box retailers capture standardized vanity and faucet volume. Largest customer base: Individual Homeowners. Gaining share fastest: Renovation Contractors.
- Renovation Contractors:Licensed generalists and bathroom specialists control specification through trade pricing and installation bundling.
- Property Developers:Multifamily and hospitality developers negotiate volume pricing for fixture packages across project portfolios.
- Interior Designers:Design-build networks and independent practitioners specify custom shower enclosures and surface materials through specialty showrooms.
Channel control is consolidating with contractors who bundle design, procurement, and installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American bathroom remodeling demand through its aging suburban housing stock and persistent drought conditions that accelerate WaterSense fixture adoption.
United States
Over sixty million homes built before 1990 require functional bathroom upgrades, creating replacement demand independent of new construction cycles. EPA WaterSense certification mandates and DOE appliance efficiency standards filter non-compliant imports from retail channels. Dallas-Fort Worth concentrates contractor activity where journeyman plumber scarcity extends project timelines and inflates labor costs.
Germany
Energy-efficient building renovation subsidies under the federal BAFA program accelerate bathroom modernization in multifamily housing. REACH regulations and EU Green Deal sustainability targets reshape material specifications for surface coatings and composite substrates. The Rhine-Ruhr industrial corridor hosts fixture manufacturing clusters where producers adapt thermostatic valve platforms for continental flow-rate standards.
China
Rapid urbanization and rising disposable incomes in tier-two cities expand addressable market for mid-market vanity and shower enclosure upgrades. GB standards and MIIT water efficiency directives tighten fixture performance thresholds for domestic consumption. Foshan in Guangdong Province anchors ceramic tile and vitreous china production, exposing distributors to ocean freight volatility and customs processing delays.
Japan
Super-aging demographics and universal design mandates accelerate accessible bathroom retrofit penetration in owner-occupied housing. METI energy conservation standards and JIS certification protocols govern smart fixture integration and thermostatic control interfaces. The Kansai region around Osaka maintains concentration in precision valve cartridge manufacturing for regional export.
Australia
Water scarcity in southeastern states drives municipal rebate programs for low-flow showerhead and faucet replacement. WELS labeling requirements and state plumbing codes create compliance burdens for imported fixture specifications. Sydney and Melbourne metropolitan areas concentrate renovation contractor networks where design-build bundling captures specification authority from traditional showroom intermediaries.
Bathroom Remodeling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and channel control dimensions, with WaterSense credentialing and big-box retail access separating tier positions. The vendor base clusters around three strategic archetypes: vertically integrated casting specialists, sensor-technology platform developers, and direct-to-consumer vanity configurators. Capacity expansion and portfolio diversification dominate competitive moves as manufacturers compress development cycles to clear legacy inventory before tightening federal efficiency timelines.
Among North American fixture specialists, Kohler Co., Moen Incorporated, and American Standard Brands exemplify distinct positioning archetypes within the premium tier. Kohler anchors specification rates through captive foundry and finishing operations. Moen occupies a position defined by channel density at professional plumbing distributors and mass retail. American Standard represents the R&D-intensive vector in touchless and smart faucet platforms. These three entities collectively illustrate how competitive separation occurs through operational model differentiation rather than product overlap.
| Leading Market Players |
|---|
| Kohler Co. |
| Delta Faucet Company |
| Moen Incorporated |
| American Standard Brands |
| Jacuzzi |
| Masco Corporation |
| LIXIL Corporation |
| Roca Sanitario |
| TOTO |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in precision valve manufacturing anchor supply discipline through captive foundry operations, translating copper alloy input control into pricing power across thermostatic fixture tiers. Their ownership structure insulates procurement from quarterly earnings pressure, enabling long-term contracting with Guangdong ceramic producers while competitors chase spot-market savings.
Pricing Analysis
Value-based pricing anchored to WaterSense flow-rate performance and DOE efficiency certification separates premium thermostatic platforms from commodity aerator replacements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and installation bundling complexity. Cost compression in mid-market faucet tiers intensifies as non-compliant imports face delisting from big-box retail channels. Individual homeowners exhibit highest price sensitivity for standardized vanity transactions, while hospitality developers absorb premium positioning costs for frameless shower systems.
Supply Chain Analysis
EPA WaterSense and IAPMO certification gating filters supplier eligibility, concentrating compliant capacity among vertically integrated North American casting specialists and select German thermostatic valve producers. Ceramic tile and vitreous china production clusters in Guangdong Province, China, alongside quartz surfacing operations in India and Brazil, feed raw material dependencies. Ocean freight volatility and customs processing delays constitute the dominant structural risk. Distribution runs through professional plumbing distributors for specification-grade fixtures, with big-box retailers capturing standardized volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bathroom remodeling sector occupies a technology-transition phase where infrared sensor convergence and thermostatic digital controls displace legacy mechanical mixing valves. Smart fixture integration is reshaping specification hierarchies and compressing aftermarket repair revenue pools.
For Market Incumbents: Hedge specification erosion by deepening backward integration into copper alloy feedstock processing and accelerating WaterSense pre-certification timelines before DOE efficiency thresholds tighten. Threat concentration sits with direct-to-consumer vanity configurators bypassing traditional showroom intermediaries. Priority leverage rests with channel control at professional plumbing distributors where installation bundling captures procurement authority.
For New Entrants and Emerging Players: Sensor-technology platform development offers entry wedge into commercial touchless specification channels underserved by legacy mechanical specialists. White-space targets concentrate in drought-affected western states where California Turf Replacement and municipal rebate programs subsidize fixture upgrades. Most penetrable segment: mid-market residential renovations where price sensitivity conflicts with compliance costs. Go-to-market angle: online design-to-order configurators reducing specification friction for renovation homeowners.
For Investors and Strategic Acquirers: Distressed-cycle entries favor R&D-intensive faucet platform developers with captive WaterSense certification pipelines in the United States. Long-term viability frames around five-to-ten-year water efficiency mandate trajectories and smart fixture adoption curves. Acquisition target archetype: vertically integrated casting specialists with specification relationships in premium hospitality and healthcare channels. Signal to watch: journeyman plumber certification backlogs extending project timelines and inflating labor cost components in major metropolitan markets.
| Strategic Initiative | Industry Significance |
|---|---|
| WaterSense Pre-Certification Investment | EPA compliance timelines compress product launch windows and filter non-compliant competitors from retail shelves. |
| Direct-to-Consumer Vanity Configurator Launch | Online platforms bypass showroom intermediaries, capturing margin and reducing specification friction for renovation homeowners. |
| Copper Alloy Backward Integration | In-house foundry operations insulate margin from London Metal Exchange price volatility in faucet body feedstocks. |
| Touchless Technology Platform Development | Infrared sensor integration with thermostatic mixing valves creates premium positioning in commercial specification channels. |
| Regional Contractor Network Expansion | Licensed plumber scarcity in Dallas-Fort Worth and coastal metros extends timelines, favoring bundled design-procurement-installation offerings. |
Research Methodology
Multi-period observation of EPA WaterSense certification timelines, DOE efficiency standard trajectories, and copper alloy input pricing anchored the trend analysis, supplemented by interviews with fixture manufacturing executives, professional plumbing distributors, renovation contractor principals, and big-box retail category managers. Secondary validation drew from SEC 10-K filings of publicly traded building products companies, U.S. Census Bureau residential improvement spending data, IAPMO certification registries, and London Metal Exchange copper price series. Bottom-up project pipeline estimates triangulated against top-down housing stock age demographics.
Segment-weighting across product type, material specification, application, and customer channel dimensions structured the analytical framework across the projection horizon. Modeled dimensions included fixture category, surface material, residential versus commercial end-use, and procurement authority concentration. CAGRs derived from installed base replacement cycles, efficiency mandate compliance deadlines, and rebate program funding trajectories. Industry-specific forecast inputs encompassed journeyman plumber pipeline data and ocean freight rate indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated DOE efficiency timeline revisions or prolonged copper price volatility. Model outputs reflect assumptions regarding WaterSense laboratory capacity expansion and state-level plumbing code harmonization. A model refresh is warranted upon material change in federal appliance efficiency standards or municipal rebate program funding levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.