
 Austria Prefabricated Housing Market | 2026-2036
Austria Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Prefabricated Housing Market Outlook
The gap between premium architect-designed prefabricated homes and standardized commodity units is realigning competitive dynamics across Austria. Griffnerhaus GmbH leverages timber-frame specialization to dominate the premium segment with bespoke alpine designs. Hartl Haus Holzindustrie GmbH anchors its position through deep backward integration into cross-laminated timber production. ELK Fertighaus GmbH competes on volume scale across Austria's federal states with repeatable panelized configurations.
Prefabricated housing encompasses dwelling units manufactured in controlled factory conditions using standardized modules or pre-engineered panels, then transported to sites for final assembly with typical wall U-values below 0.15 W/m²K for Passivhaus compliance. Modular Homes command the largest share of current output as developers pursue faster project cycles, while Panelized Homes represent the fastest-expanding category due to flexibility in multi-story urban infill projects. Wood-based construction dominates material flows given Austria's domestic spruce and beech supply chains, though Steel framing gains share in commercial-hybrid developments around Linz and Graz.
Austria's federal building codes, the Klimafit subsidy framework administered by klimaaktiv, and EU-wide CE marking requirements for construction products collectively elevate thermal performance thresholds and restrict market access for non-compliant imports. The national Ministry of Climate Action enforces tightened EnEV standards that mandate renewable heating sources in new prefabricated units from 2026 onward. Stakeholders must monitor how pending EU taxonomy alignment rules for sustainable buildings reshape financing access and buyer qualification criteria across Austrian lending institutions.
Market Dynamics
Austria's prefabricated housing sector confronts a fundamental tension between factory-scale efficiency and site-specific customization demands, as Klimafit subsidy thresholds and Passivhaus thermal mandates force producers to re-engineer panel systems for alpine microclimates and urban infill simultaneously.
Growth Catalysts
- Klimafit Building Subsidy:The klimaaktiv-administered framework rewards developers achieving specific heating demand thresholds, channeling capital toward high-performance envelope systems in Vienna's peri-urban corridor.
- Cross-Laminated Timber Maturation:Domestic spruce supply chains now support industrial CLT output at competitive cost points, enabling multi-story residential configurations previously restricted to concrete.
- First-Time Buyer Cohorts:Young families priced out of conventional construction in Salzburg and Innsbruck are accepting modular delivery timelines in exchange for mortgage-accessible unit economics.
Market Restraints
- Cross-Laminated Timber Input Concentration:Three domestic producers control over 70% of structural-grade CLT supply, creating vulnerability to sawmill capacity constraints during peak construction seasons.
- Site Access Logistics:Narrow alpine road networks and crane clearance restrictions in Tyrolean valleys impose hard limits on module dimensions, fragmenting production runs.
- EnEV Thermal Standard Escalation:The 2026 renewable heating mandate forces immediate R&D expenditure on heat pump integration before cost curves flatten.
Strategic Opportunities
- Tourism-Adjacent Alpine Developments:Salzburg's secondary residence market remains undersupplied with low-maintenance prefabricated units meeting strict facade heritage codes.
- Building-Integrated Photovoltaics Convergence:Roof-integrated solar thermal collectors paired with CLT substrates create unified envelope-energy systems qualifying for enhanced Klimafit tiers.
- Direct-to-Consumer Digital Channels:Configurator platforms bypass traditional developer intermediaries, capturing margin and compressing sales cycles for standardized panelized configurations.
Industry Challenges
- Passivhaus Certifier Scarcity:Austria hosts fewer than 200 accredited building certifiers capable of validating factory-produced envelope assemblies, creating bottlenecks at project handover.
- Legacy Utility Integration:District heating networks in Vienna's outer districts require bespoke heat exchanger configurations incompatible with standardized plant room modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Prefabricated Housing Market |
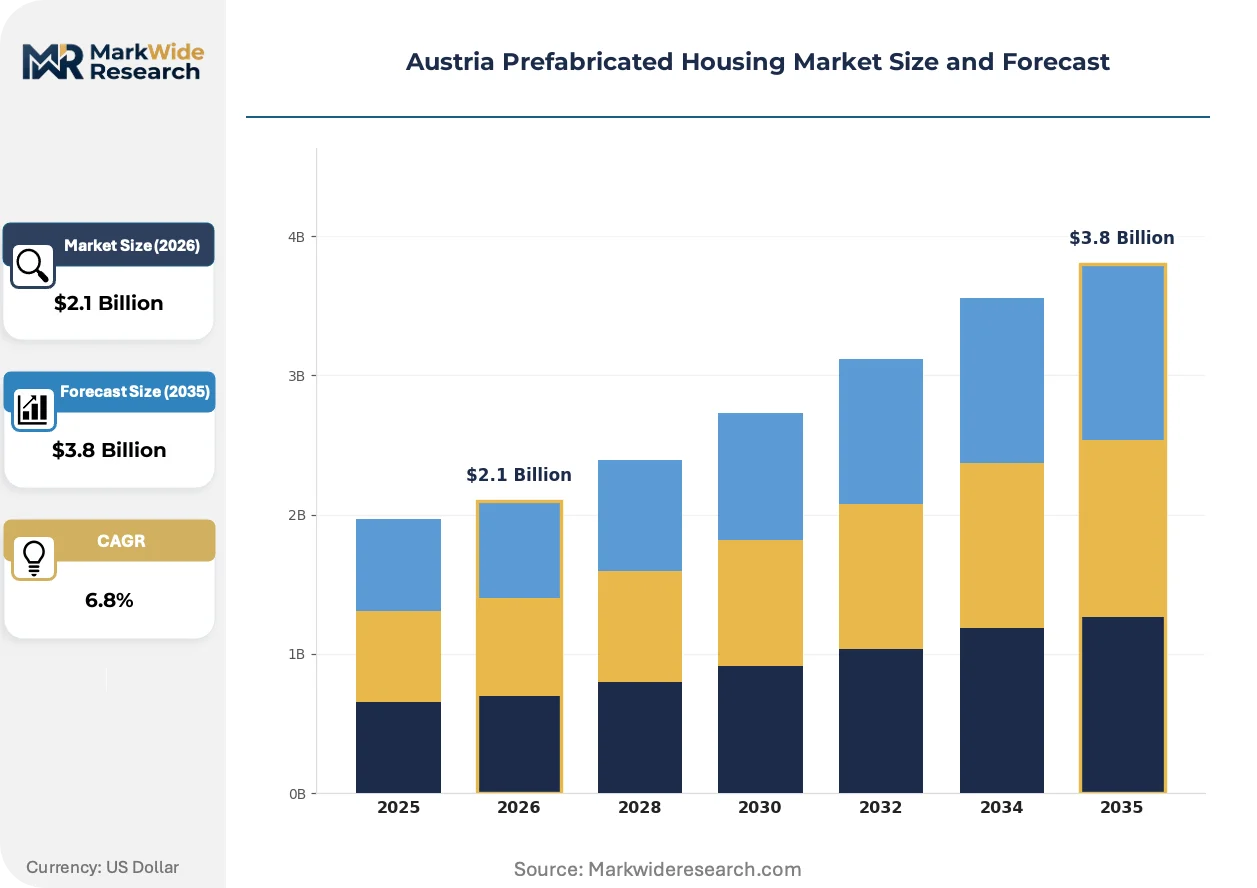
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cut Homes, Manufactured Homes End User: Individuals, Real Estate Developers, Contractors, Government Projects Material: Wood, Steel, Concrete, Composite Construction Method: Traditional Assembly, On-Site Assembly, Off-Site Fabrication, Hybrid Approach |
| Companies Covered | Kieninger Gesellschaft, Haas GmbH, Swietelsky AG, Hartl Haus Holzindustrie GmbH, Wolf Systembau Gesellschaft m.b.H., ELK Fertighaus GmbH, Georg Fessl GmbH, Griffnerhaus GmbH, Wimberger Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Prefabricated Housing Market Strategic Shifts
Factory automation and digital fabrication are collapsing the traditional trade-off between customization cost and production speed, enabling Austrian manufacturers to address fragmented demand without sacrificing margin.
Robotic timber milling is rewriting how structural panels achieve geometric complexity. Alpine resort developers now specify free-form roof geometries previously requiring on-site carpentry. Griffnerhaus and comparable specialists deploy seven-axis CNC routers to cut compound curves directly from CLT blanks. This capability is compressing the premium-custom segment against standardized volume production.
The Ministry of Climate Action's tightened EnEV standards are mandating renewable heating sources in all new prefabricated units from 2026 onward. Heat pump manufacturers must certify seasonal performance factors above 4.5 for alpine climate zones. Panelized home producers in Vorarlberg are responding by pre-integrating air-source units into mechanical core modules during factory assembly.
Young family buyers are abandoning traditional developer intermediaries in favor of direct configuration platforms. Online tools now visualize envelope performance, interior layouts, and Klimafit subsidy eligibility in unified interfaces. This channel shift is most visible in Vienna's peri-urban ring, where first-time buyers research options independently before contacting manufacturers for final specification lock.
Austria Prefabricated Housing Market Segmentation
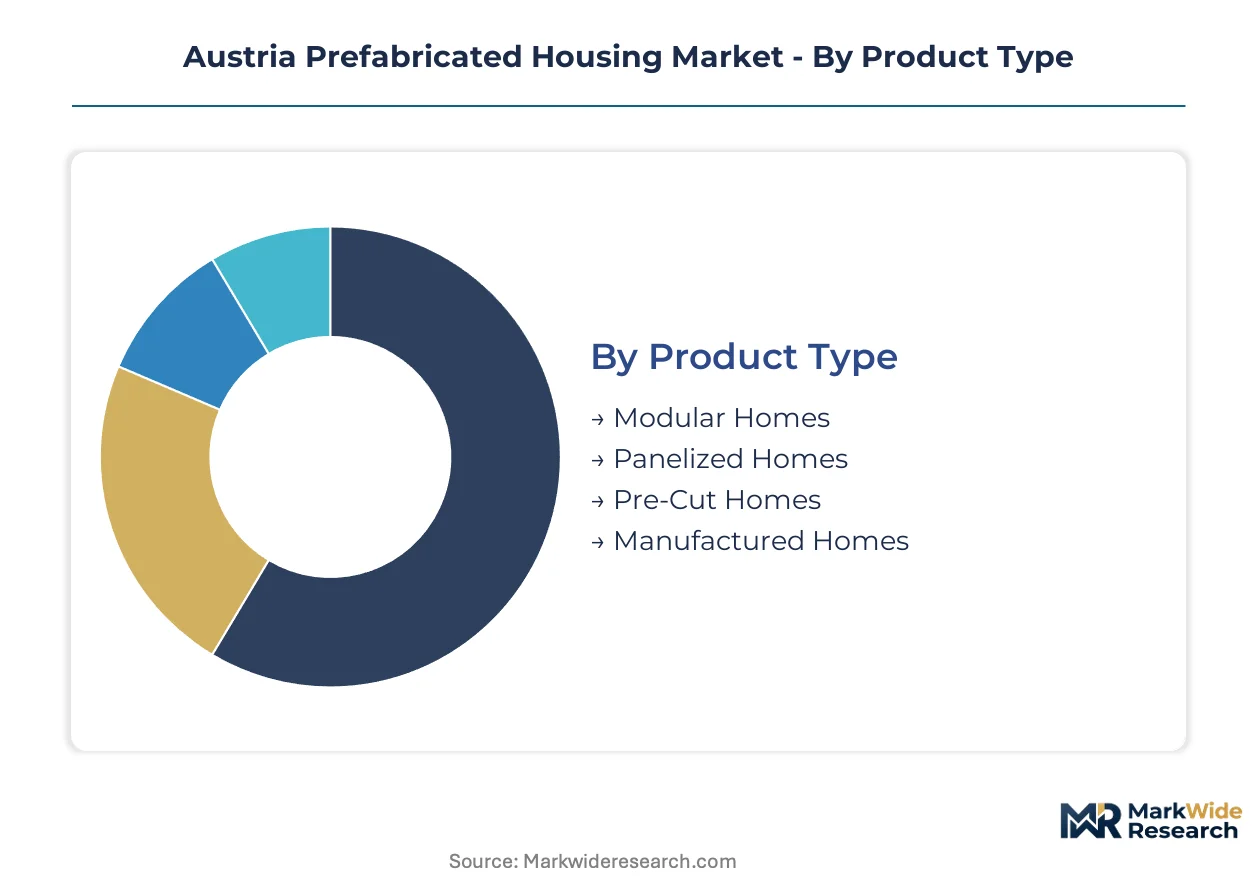
Segmentation in Austria's prefabricated housing market reveals how factory production capabilities align with distinct procurement channels and thermal performance requirements. Each dimension exposes different pressure points in matching standardized output to site-specific demands across Vienna's peri-urban corridor and alpine tourism zones.
Product Type:
Supply concentration among Austria's timber-frame specialists favors certain product architectures over others, with factory automation investments determining which formats achieve viable unit economics at scale.
- Modular Homes:Three-dimensional volumetric units complete with MEP rough-ins and interior finishes, shipped to site for crane-assisted placement. Demand clusters in Salzburg's secondary residence market where developers seek compressed construction windows. Klimafit subsidy tiers reward the thermal consistency these sealed factory environments deliver.
- Panelized Homes:Flat-pack wall, floor, and roof assemblies offering geometric flexibility for multi-story urban infill. Vienna's peri-urban ring drives procurement as first-time buyers customize configurations through direct-to-consumer platforms while maintaining Passivhaus envelope performance.
- Pre-Cut Homes:Precision-cut timber components requiring on-site assembly by specialized crews. Alpine heritage facade codes in Tyrol constrain adoption despite competitive material costs.
- Manufactured Homes:Transportable dwelling units built to mobile construction standards with chassis integration. Regulatory friction with Austria's federal building codes limits deployment outside designated exception zones.
Today's leader: Modular Homes. Tomorrow's challenger: Panelized Homes.
End User:
Procurement authority distributes unevenly across customer types, with volume concentration among developer intermediaries contrasting against the margin capture potential of direct manufacturer relationships.
- Individuals:First-time buyers and young families in Innsbruck and Graz leveraging online configurators to bypass traditional sales channels. Digital tools now visualize Klimafit eligibility alongside floor plans, compressing research-to-contract timelines.
- Real Estate Developers:Institutional purchasers driving repeat panelized configurations across multi-unit projects. Scale economies from standardized envelope systems offset premium pricing for Passivhaus certification support.
- Contractors:Regional construction firms assembling pre-cut or panelized systems on behalf of dispersed individual clients. Capacity constraints during peak alpine seasons create project scheduling volatility.
- Government Projects:Social housing authorities in Vienna and Linz specifying renewable heating integration ahead of EnEV mandates. Procurement frameworks prioritize lifecycle carbon metrics over first-cost minimization.
Developers command current volume. Individual buyers represent the steepest expansion trajectory through digital channel migration.
Material:
Domestic feedstock availability and CLT production maturity privilege certain substrates in Austria's federal subsidy calculations and thermal performance benchmarking.
- Wood:Spruce and beech supply chains from domestic forestry operations support cross-laminated timber output at industrial scale. Griffnerhaus and Hartl Haus anchor competitive positioning through captive or deeply integrated sawmill relationships.
- Steel:Light-gauge framing gains share in commercial-hybrid developments around Linz and Graz where fire resistance ratings exceed timber capabilities. Import dependency for galvanized sheet creates exchange rate exposure.
- Concrete:Precast concrete panels retain position in foundation and basement assemblies despite weight penalties for alpine transport logistics.
- Composite:Fiber-reinforced polymer and insulated metal panel systems emerging in high-performance envelope applications. Cost curves remain unfavorable for mainstream residential adoption.
Wood dominates present procurement. Steel frames the most credible material challenger for multi-story urban configurations.
Construction Method:
Factory-to-site workflow distribution determines quality consistency, thermal bridging risk, and crane logistics complexity across Austria's varied topography.
- Traditional Assembly:Stick-built construction with site-delivered dimensional lumber. Labor cost escalation and weather dependency push share erosion outside remote alpine valleys with restricted module access.
- On-Site Assembly:Pre-engineered components erected by manufacturer-certified crews. Passivhaus certifier scarcity creates validation bottlenecks at project handover for this intermediate approach.
- Off-Site Fabrication:Complete envelope and MEP integration within factory climate control. Klimafit heating demand thresholds are most reliably achieved through this method, concentrating investment in Vorarlberg and Upper Austria production facilities.
- Hybrid Approach:Factory-produced volumetric cores combined with site-built extensions or heritage-compliant facades. Salzburg tourism developers deploy this format to reconcile modern thermal performance with traditional alpine aesthetics.
Off-site fabrication leads on certification compliance. Hybrid approaches gain share fastest where heritage codes constrain pure factory solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austria's skilled timber-frame workforce clusters in Vorarlberg and Upper Austria, anchoring factory production capacity that supplies Vienna's peri-urban ring and alpine tourism corridors. Regional specialization reflects distinct topographic constraints and subsidy eligibility thresholds.
Vienna and Lower Austria
First-time buyers and young families drive demand in Vienna's peri-urban corridor, where Klimafit subsidy tiers reward heating demand below 15 kWh/m² annually. The klimaaktiv program channels capital toward high-performance envelope systems. Panelized configurations dominate procurement as digital configurators compress research-to-contract timelines.
Salzburg and Upper Austria
Tourism-adjacent secondary residence markets seek low-maintenance prefabricated units meeting strict facade heritage codes. The 2026 EnEV renewable heating mandate forces immediate heat pump integration into mechanical core modules. Production facilities in Upper Austria leverage cross-laminated timber supply chains for multi-story resort configurations.
Tyrol and Vorarlberg
Alpine topography imposes hard limits on module dimensions through narrow valley road networks and crane clearance restrictions. Vorarlberg's factory automation investments enable robotic timber milling for free-form roof geometries. Griffnerhaus anchors premium positioning through bespoke alpine designs manufactured in this cluster.
Styria and Carinthia
Steel-framed commercial-hybrid developments gain share around Graz as fire resistance requirements exceed timber capabilities. The federal Ministry of Climate Action enforces district heating integration in urban infill projects. Site access logistics favor panelized delivery over volumetric modules in Carinthia's lake tourism zones.
Linz and Upper Austria Industrial Belt
Social housing authorities in Linz specify renewable heating integration ahead of national mandates, prioritizing lifecycle carbon metrics over first-cost minimization. CLT production concentration creates sawmill capacity vulnerability during peak construction seasons. Hybrid factory-site workflows reconcile Passivhaus performance with heritage facade compliance.
Austria Prefabricated Housing Market Competitive Environment
Top-tier vendors anchor premium timber-frame specialization, while mid-scale fabricators compete on panelized volume across federal states. The vendor base splits between bespoke alpine designers and repeatable configuration producers. Three strategic archetypes dominate: timber-frame heritage specialists, CLT-integrated volume producers, and steel-framed commercial-hybrid developers. Competitive moves center on backward integration into sawmill operations and direct-to-consumer digital channel expansion.
Within the timber-frame specialization tier, Griffnerhaus GmbH and Hartl Haus Holzindustrie GmbH exemplify divergent positioning strategies. Griffnerhaus occupies a position representing bespoke alpine design capability, while Hartl Haus anchors CLT production integration. ELK Fertighaus GmbH sits within the scale-driven archetype, exemplifying repeatable panelized configurations across Austria's federal states. Haas GmbH and Wolf Systembau Gesellschaft m.b.H. represent mid-tier volume fabricators competing on standardized envelope systems. Kieninger Gesellschaft and Georg Fessl GmbH exemplify regional specialists with concentrated geographic footprints. Swietelsky AG and Wimberger Holding GmbH occupy positions spanning construction services and prefabricated manufacturing integration.
| Leading Market Players |
|---|
| Kieninger Gesellschaft |
| Haas GmbH |
| Swietelsky AG |
| Hartl Haus Holzindustrie GmbH |
| Wolf Systembau Gesellschaft m.b.H. |
| ELK Fertighaus GmbH |
| Georg Fessl GmbH |
| Griffnerhaus GmbH |
| Wimberger Holding GmbH |
| Others |
Value Chain & Pricing Dynamics
Robotic timber milling adoption across Vorarlberg production facilities is compressing customization premiums while concentrating supply leverage among CLT-integrated manufacturers. This factory automation wave simultaneously erodes cost barriers for free-form geometries and rewards producers with captive sawmill relationships, reshaping how Griffnerhaus and Hartl Haus extract margin from premium alpine configurations versus standardized panelized competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates turnkey Passivhaus certification packages from base envelope-only procurement. Three-tier pricing structure across premium, standard, and economy levels tracks thermal performance thresholds and Klimafit subsidy eligibility tiers. Cost compression in the standard tier intensifies as ELK Fertighaus and Wolf Systembau compete on repeatable panelized volumes. First-time buyers in Vienna's peri-urban ring exhibit highest price sensitivity, while Salzburg tourism developers absorb premiums for heritage-compliant facade integration.
Supply Chain Analysis
Passivhaus certifier scarcity gates supply access, with fewer than 200 accredited validators creating bottlenecks at project handover. Geographic supply concentration rests on Austria, Germany, and Czech Republic for cross-laminated timber feedstock and precision milling equipment. Raw material dependencies center on domestic spruce and beech supply chains, heat pump seasonal performance factor certification, and galvanized steel sheet for commercial-hybrid frames. Single-source vulnerability concentrates in CLT structural panel production where three domestic producers control majority share. Distribution runs through manufacturer-direct digital configurators and regional developer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's prefabricated housing market functions as a stable compounder, with Klimafit subsidy mechanics and EnEV thermal mandates embedding recurring upgrade cycles that sustain manufacturer revenue visibility.
For Market Incumbents: Deploy backward integration into cross-laminated timber production to defend margin against sawmill capacity constraints during peak alpine construction seasons. Lock Passivhaus certifier relationships through exclusive partnership structures before competitor accreditation expansion. This dual posture addresses the emerging threat of digital-native configurators eroding traditional developer channel control. For New Entrants and Emerging Players: Regional contractors in Tyrolean valleys represent the most penetrable channel partner type for pre-cut assembly services where module access logistics fragment incumbent delivery. Target Salzburg's secondary residence market with low-maintenance hybrid configurations that reconcile modern thermal performance with heritage facade codes. Pursue direct-to-consumer platform partnerships that bypass established developer intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale panelized fabricators lacking CLT integration but holding established Klimafit certification workflows. Long-term viability centers on producers capable of bridging renewable heating mandates with factory-scale envelope consistency. Watch Passivhaus certifier training program expansion as the signal indicating supply bottleneck alleviation and competitive pressure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CLT Production | Captive spruce supply from domestic forestry operations insulates margin from sawmill capacity volatility. |
| Passivhaus Certifier Partnership Lock | Exclusive validation relationships compress project handover timelines and deter competitor accreditation access. |
| Direct-to-Consumer Configurator Launch | Digital channel bypass of developer intermediaries captures margin and accelerates first-time buyer conversion. |
| Heat Pump Pre-Integration Investment | Factory assembly of mechanical core modules ahead of EnEV mandates secures Klimafit tier eligibility. |
| Heritage-Compliant Hybrid Development | Salzburg tourism corridor positioning reconciles modern envelope performance with traditional alpine aesthetic codes. |
Study Parameters
Coverage spans Vienna's peri-urban corridor, Salzburg's alpine tourism zones, and Upper Austria's production clusters, with primary inputs from each. The analysis combines structured interviews with prefabricated housing manufacturers, Passivhaus certifiers, klimaaktiv program administrators, and regional real estate developers with secondary validation. Secondary sources include klimaaktiv subsidy disbursement records, EnEV regulatory filings, Austrian Federal Ministry of Climate Action policy documents, and timber trade association production statistics. Bottom-up unit deployment estimates triangulate against top-down construction permit data.
Granularity-level framing applies product type, construction method, end user category, and material substrate dimensions at the federal state level across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by Klimafit subsidy tier eligibility and EnEV compliance phase-in schedules. Industry-specific forecast inputs incorporate cross-laminated timber production capacity expansion timelines and Passivhaus certifier pipeline graduation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sawmill capacity expansion delays and certifier training program throughput. Deviation in Klimafit subsidy renewal terms or EnEV thermal standard acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Global Manufactured Homes Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Residential Construction Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
US Residential Construction Market
Residential Construction
Residential Roofing Market
Residential Construction
Latin America Residential Construction Market