
 Canada Residential Construction Market | 2026-2036
Canada Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Residential Construction Market Outlook
Skilled trades shortages across Ontario and British Columbia is unwinding project timelines and inflating labor costs for builders nationwide. PCL Construction leverages its coast-to-coast apprenticeship pipelines to sustain workforce continuity on large-scale multi-family developments. EllisDon Corporation anchors its residential portfolio through integrated design-build delivery that compresses schedules for condominium towers in Toronto and Vancouver. Chandos Construction differentiates via employee-ownership culture that reduces turnover among project managers and site supervisors.
Canada residential construction encompasses the design, permitting, and physical assembly of detached houses, townhouses, condominiums, and multi-family rental structures using platform-framed wood, cast-in-place concrete, or prefabricated modular panels engineered to withstand seismic zones and extreme cold-weather cycles. Its primary purpose is creating habitable dwelling units that comply with national fire-safety, energy-efficiency, and structural-load standards while responding to household formation rates and mortgage-access conditions. Single-family homes retain the largest share of material volume but face margin compression from lot scarcity in urban cores, whereas multi-family units and condominiums concentrate profitability through density bonuses and accelerated municipal approvals in transit corridors. Modular components represent the fastest-expanding material category as developers seek to offset labor gaps with factory-built wall and floor assemblies that shorten on-site cycles.
Health Canada and the National Research Council jointly administer the National Building Code, which provinces adopt with jurisdiction-specific amendments governing seismic bracing, radon mitigation, and energy-step performance tiers. The Canada Mortgage and Housing Corporation shapes demand through mortgage-insurance eligibility rules and multi-unit rental financing programs that steer capital toward purpose-built rental stock. Provincial regulators including BC Housing and Ontario's Building Code Commission layer additional efficiency mandates that elevate window, insulation, and HVAC specifications. Stakeholders must monitor how municipal upzoning bylaws and federal housing-accelerator fund commitments reshape project feasibility across Canadian metropolitan areas.
Market Dynamics
Transit-oriented development policies in Ontario and British Columbia are compressing project timelines and forcing builders toward vertical formats as municipalities accelerate approvals for density near rapid-transit corridors. This structural shift toward intensification is reshaping material procurement, labor deployment, and capital structures across the residential value chain.
Growth Catalysts
- Federal Housing Accelerator Fund:Municipalities accessing this capital stream are upzoning arterial corridors, unlocking multi-family sites that were previously restricted to low-density formats.
- Prefabricated modular panels:Factory-built wall and floor assemblies are compressing on-site construction cycles and offsetting skilled trades shortages in Greater Toronto and Metro Vancouver.
- First-time homebuyer demand:Household formation in Ontario and British Columbia is concentrating order books for condominiums and townhouses as entry-level detached homes price out younger buyers.
Market Restraints
- Lumber and engineered wood products:Input cost volatility from British Columbia beetle-kill supply constraints and trade-duty uncertainty is compressing margins for platform-framed builders.
- Cast-in-place concrete supply:Concentration of ready-mix production in Metro Vancouver and Greater Toronto creates bottleneck risk when multiple high-rise projects phase simultaneously.
- National Building Code energy-step tiers:Provincial adoption timelines vary, creating compliance fragmentation that delays permit issuance in jurisdictions lagging on amendments.
Strategic Opportunities
- Alberta and Quebec secondary markets:Calgary, Edmonton, and Quebec City corridors offer underpenetrated demand for mid-rise rental stock as interprovincial migration accelerates.
- Passive House and net-zero-ready specifications:Municipal density bonuses for exceedance of National Building Code minimums are creating margin premiums for builders certifying to these standards.
- Integrated project delivery:Convergence of design software with modular manufacturing is enabling earlier trade contractor involvement and reducing field rework on complex multi-family sites.
Industry Challenges
- Red Seal carpentry and site supervision:Apprenticeship completion rates are trailing retirement outflows, forcing wage inflation and schedule extensions on active projects.
- Seismic bracing and radon mitigation:British Columbia's jurisdiction-specific amendments to the National Building Code are extending engineering review cycles and adding foundation-system complexity.
- Legacy HVAC integration:Heat-pump mandates in new construction are creating commissioning delays where mechanical contractors lack familiarity with cold-climate performance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Residential Construction Market |
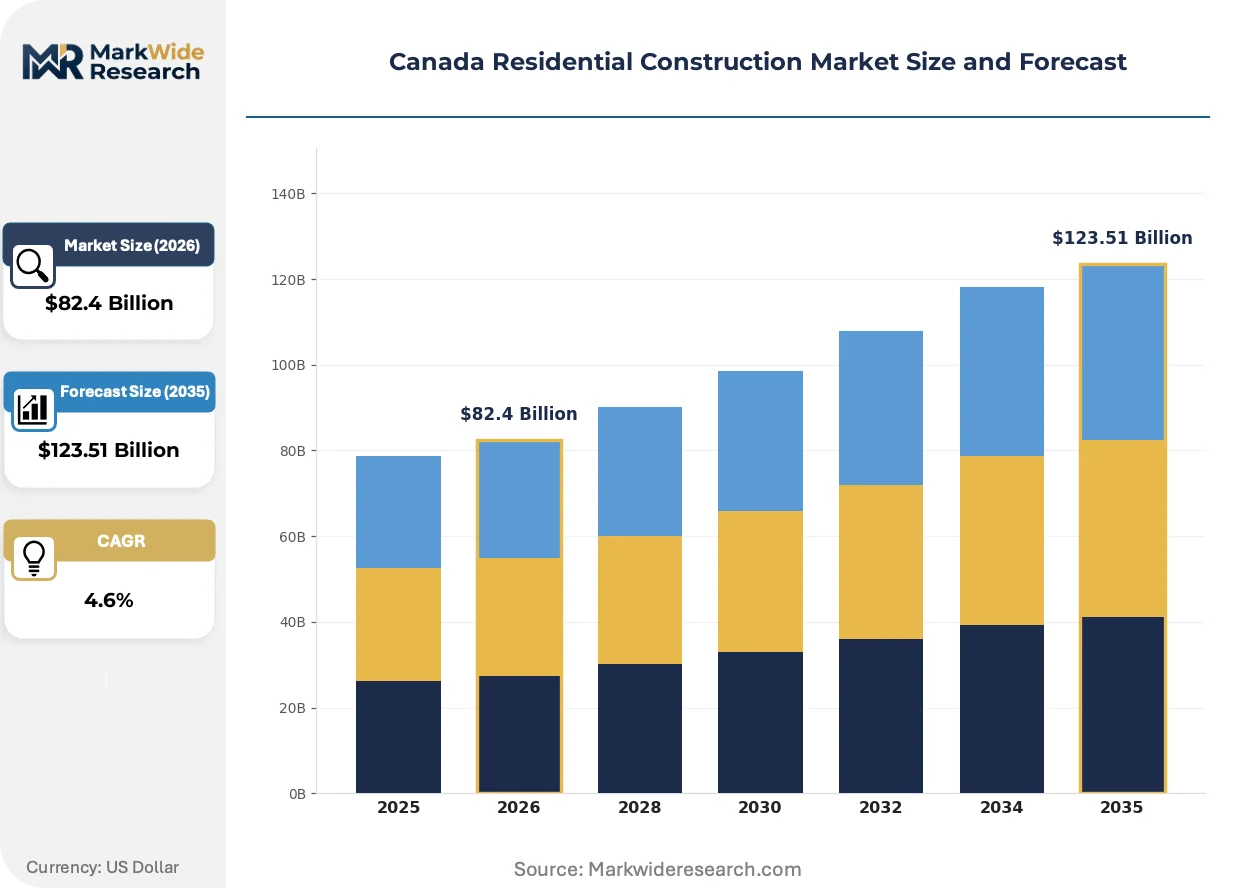
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $123.51 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Single-Family Homes, Multi-Family Units, Condominiums, Townhouses Material Type: Wood, Concrete, Steel, Modular Components Project Size: Small Scale, Medium Scale, Large Scale, Infrastructure Customer Type: Homeowners, Developers, Investors, Contractors |
| Companies Covered | Aecon Group Inc., Clark Builders, PCL Construction, Chandos Construction, Broccolini Construction Inc, Pomerleau, Ledcor Group of Companies, Concert Construction, EllisDon Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Residential Construction Market Strategic Shifts
Digital fabrication and advanced building envelopes are compressing traditional construction sequences while regulatory pressure on operational carbon is forcing material specification changes. These shifts are redistributing value capture from field labor to offsite manufacturing and specialized engineering.
Cross-laminated timber and mass timber structural systems are miniaturizing foundation footprints and enabling taller wood-frame construction under the National Building Code's alternate compliance paths. Developers in Vancouver and Toronto are adopting these systems to accelerate vertical phasing on constrained sites. The technology is miniaturizing the structural depth required for equivalent spans, freeing floor-area-ratio for additional sellable units.
British Columbia's Energy Step Code and Ontario's tiered efficiency mandates are tightening thermal-performance requirements for windows, insulation, and air-barrier continuity. Builders are responding with triple-glazed specifications and exterior insulation finish systems that exceed base-code minimums. Condominium towers in Metro Vancouver are most affected, with envelope consultants now engaged during schematic design rather than construction documents.
Institutional capital is consolidating rental-asset ownership and demanding standardized unit specifications across portfolios. Property managers are unbundling maintenance contracts and specifying durable-finish packages that reduce turnover costs. This procurement compression is most visible in Toronto's purpose-built rental pipeline, where REITs are pre-qualifying general contractors on past-performance databases rather than open tender.
Canada Residential Construction Market Segmentation
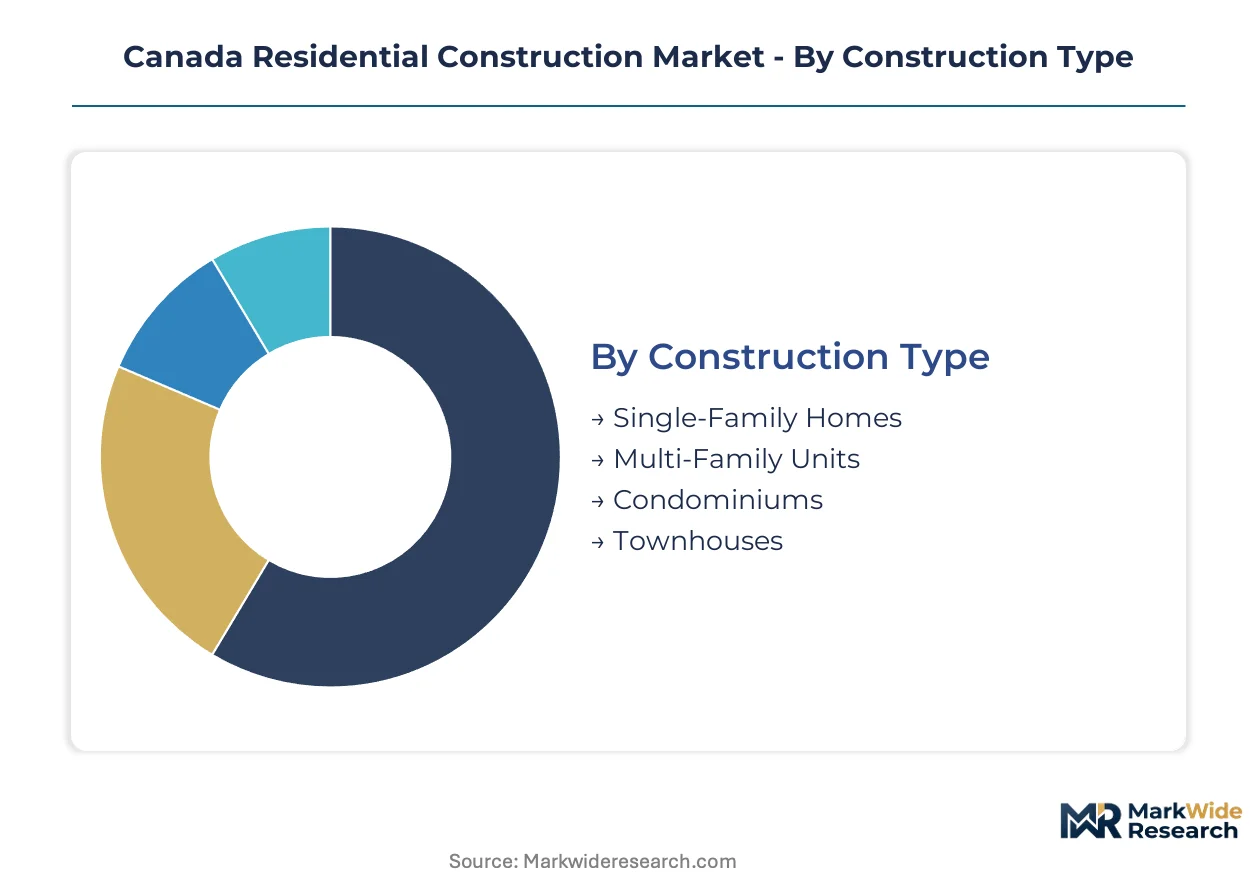
Segmentation in Canadian residential construction reveals how regulatory fragmentation, material procurement constraints, and customer capital structures reshape project economics. Builders must align format selection with National Building Code energy tiers and provincial adoption timelines to secure municipal approvals.
Construction Type:
The National Building Code's alternate compliance paths for combustible construction create divergent permitting timelines across format categories, with seismic zones and energy-step tiers forcing jurisdiction-specific design responses.
- Single-Family Homes:Platform-framed wood structures dominate material volume but face margin compression from lot scarcity in Greater Toronto and Metro Vancouver urban cores. Demand is retreating to exurban corridors where land costs permit entry-level pricing for household formation.
- Multi-Family Units:Purpose-built rental and stacked townhouses concentrate profitability through density bonuses near rapid-transit corridors. Ontario and British Columbia municipalities are accelerating approvals for these formats under federal housing accelerator commitments.
- Condominiums:Strata-title towers in Vancouver and Toronto face extended engineering review cycles from BC's seismic bracing amendments and Ontario's tiered efficiency mandates.
- Townhouses:Row housing formats bridge single-family preferences with multi-family density, attracting first-time buyers priced out of detached markets in Ontario and British Columbia.
Established volume favors single-family construction; emerging adoption favors multi-family units.
Material Type:
Cost tier differentiation separates premium engineered systems from commodity inputs, with factory-built assemblies commanding margin premiums over field-built alternatives.
- Wood:Platform-framed dimensional lumber and engineered wood products retain cost advantages for low-rise formats but face supply volatility from British Columbia beetle-kill constraints and trade-duty uncertainty.
- Concrete:Cast-in-place and precast systems enable high-rise structural capacity under National Building Code provisions. Concentration of ready-mix production in Metro Vancouver and Greater Toronto creates bottleneck risk during synchronized project phasing.
- Steel:Light-gauge framing and structural steel systems penetrate mid-rise commercial-residential hybrid projects where fire-rating requirements exceed wood-frame limits.
- Modular Components:Factory-built wall and floor assemblies compress on-site cycles and offset skilled trades shortages. This category is gaining share fastest as developers integrate digital fabrication with just-in-time site delivery.
Commodity inputs anchor project budgets; engineered systems capture efficiency premiums.
Project Size:
Application scale determines capital structure, with institutional financing availability tightening for formats below multi-unit thresholds.
- Small Scale:Custom infill and laneway housing projects navigate municipal variance processes and neighbor consultation requirements that extend timelines.
- Medium Scale:Mid-rise rental and condominium projects between four and twelve stories access standardized financing from Canada Mortgage and Housing Corporation multi-unit programs.
- Large Scale:Master-planned communities and high-rise towers require phased capital deployment across extended development horizons, exposing builders to interest rate and absorption risk.
- Infrastructure:Residential components of transit-oriented development and mixed-use precincts integrate with municipal infrastructure funding streams and density bonus negotiations.
Medium-scale projects dominate transaction velocity; large-scale developments concentrate capital deployment.
Customer Type:
Margin structure varies by buyer sophistication, with institutional purchasers extracting volume discounts unavailable to individual consumers.
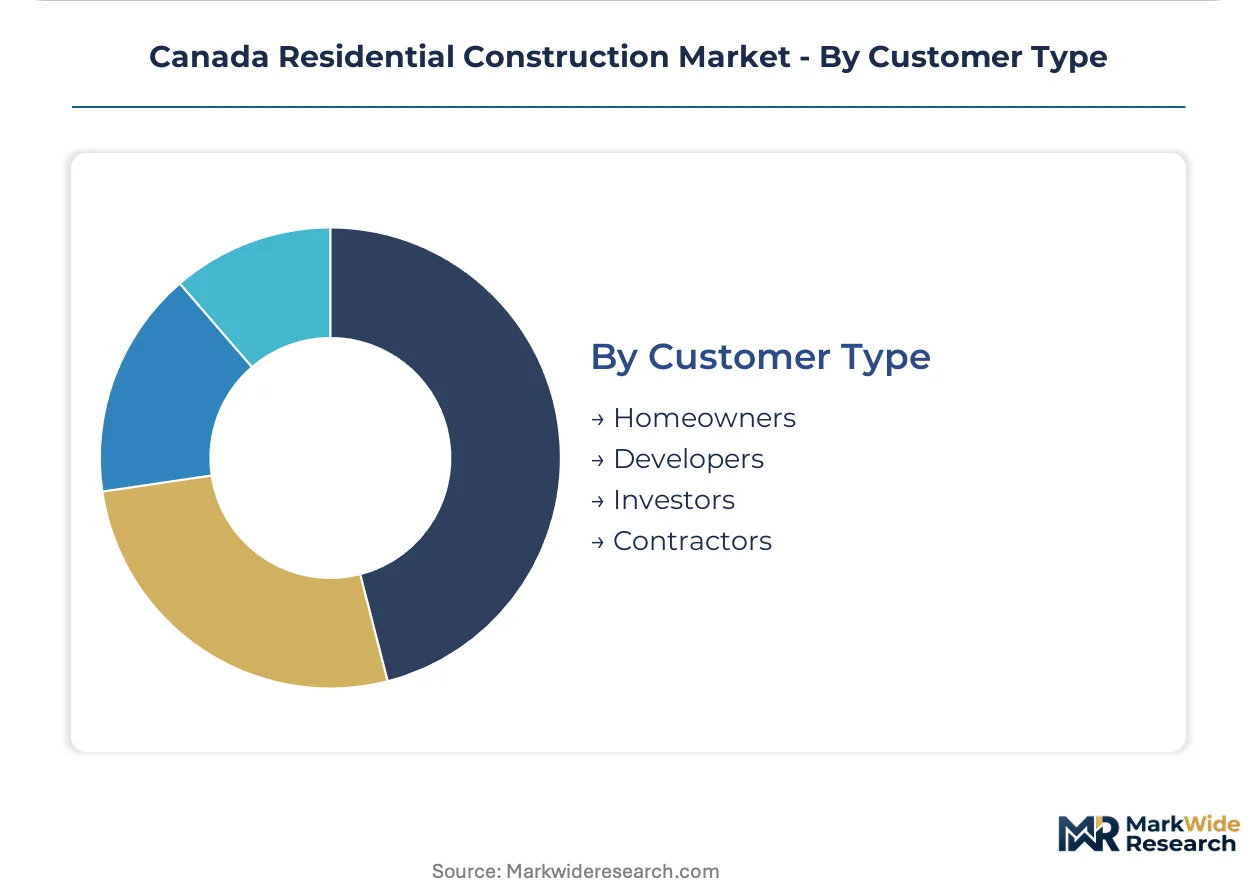
- Homeowners:Individual purchasers drive single-family and townhouse demand, with mortgage-insurance eligibility rules from Canada Mortgage and Housing Corporation shaping accessible price points.
- Developers:Merchant builders control land positions and secure phased construction financing, capturing value appreciation through entitlement acceleration in upzoned corridors.
- Investors:REITs and institutional capital are consolidating rental-asset ownership, demanding standardized specifications and pre-qualifying contractors on past-performance databases.
- Contractors:Design-build and construction-management firms assume risk-transfer positions on complex multi-family sites, with integrated project delivery compressing schedules for repeat developer clients.
Developer volume commands supply chain leverage; investor procurement is standardizing contractor selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada and the National Research Council jointly administer the National Building Code, which provinces adopt with jurisdiction-specific amendments governing seismic bracing, radon mitigation, and energy-step performance tiers.
Ontario
First-time homebuyer demand in the Greater Toronto Area is concentrating order books for condominiums and townhouses as entry-level detached homes price out younger buyers. Ontario's Building Code Commission layers additional efficiency mandates that elevate window, insulation, and HVAC specifications. Transit-oriented development policies in Toronto and Ottawa corridors are accelerating approvals for density near rapid-transit stations.
British Columbia
Metro Vancouver land scarcity and transit-oriented development policies are intensifying vertical residential formats. BC Housing and provincial regulators enforce jurisdiction-specific seismic bracing amendments that extend engineering review cycles. Vancouver and Victoria clusters concentrate mass timber adoption and passive house certifications as developers pursue density bonuses.
Alberta
Interprovincial migration is accelerating demand for mid-rise rental stock in Calgary and Edmonton corridors. The province maintains alignment with National Building Code base standards without tiered efficiency mandates that delay permitting elsewhere. Calgary's secondary market offers underpenetrated opportunities for purpose-built rental development at lower land costs than Ontario or British Columbia.
Quebec
Quebec City and Montreal corridors exhibit growing household formation driving multi-family construction. Provincial adoption of National Building Code energy tiers lags Ontario and British Columbia, creating compliance fragmentation. Montreal's transit-oriented development policies are beginning to mirror intensification strategies seen in Toronto and Vancouver.
Canada Residential Construction Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with coast-to-coast apprenticeship pipelines and design-build capabilities separating national-scale operators from regional contractors. The market structure reflects consolidation around firms with workforce continuity systems and integrated project delivery expertise. Strategic archetypes include integrated design-build firms, employee-ownership models, and coast-to-coast apprenticeship pipeline operators. Dominant competitive moves encompass geographic expansion through apprenticeship network scaling and portfolio diversification into modular fabrication partnerships.
Among national-scale integrated operators, PCL Construction, EllisDon Corporation, and Chandos Construction exemplify contrasting workforce and ownership architectures. PCL Construction anchors its position through coast-to-coast apprenticeship pipelines that sustain workforce continuity on large-scale multi-family developments. EllisDon Corporation occupies a position within the design-build tier through integrated delivery that compresses schedules for condominium towers in Toronto and Vancouver. Chandos Construction sits within the employee-ownership archetype, representing a model that reduces turnover among project managers and site supervisors through equity participation structures.
| Leading Market Players |
|---|
| Aecon Group Inc. |
| Clark Builders |
| PCL Construction |
| Chandos Construction |
| Broccolini Construction Inc |
| Pomerleau |
| Ledcor Group of Companies |
| Concert Construction |
| EllisDon Corporation |
| Others |
Value Chain & Pricing Dynamics
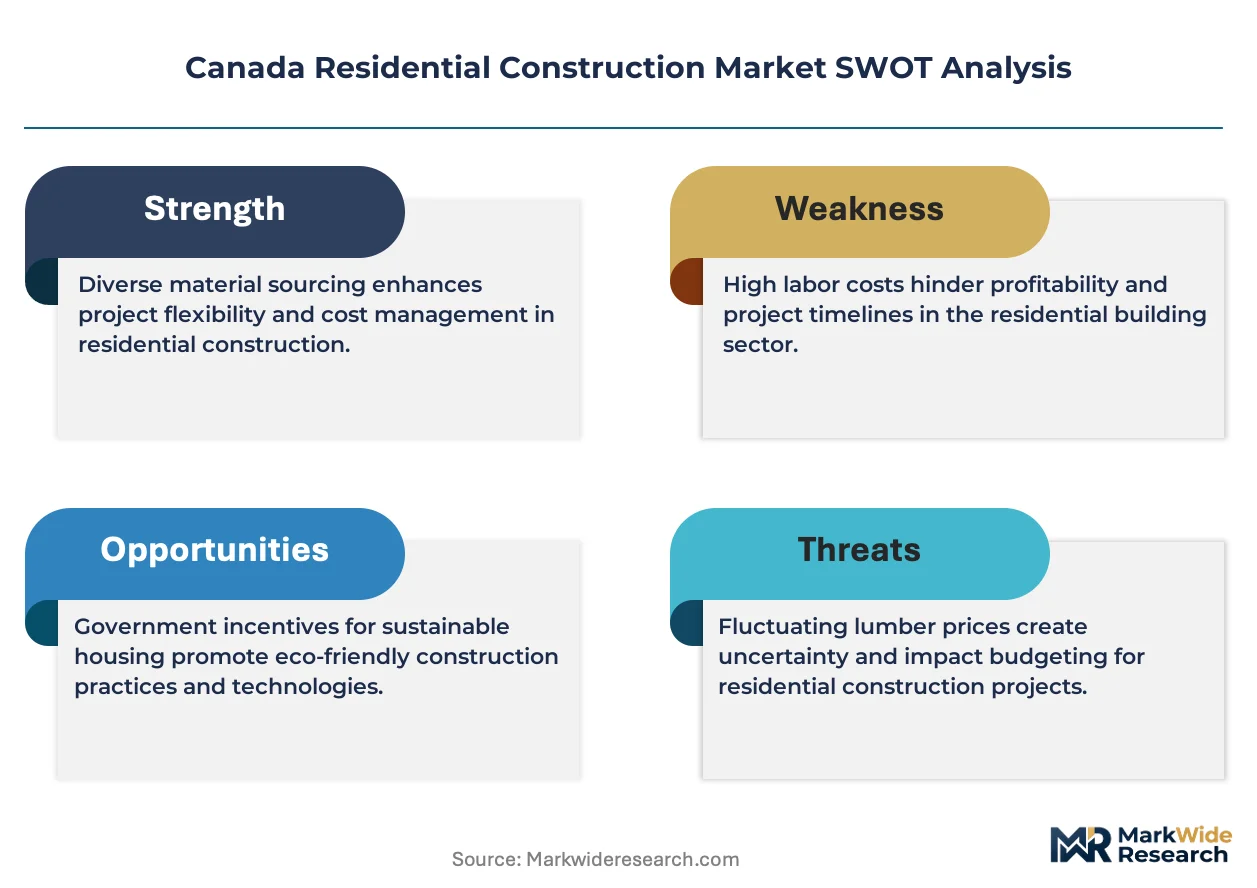
Ready-mix concrete batch-plant utilization rates in Metro Vancouver and Greater Toronto create regional price floors that compress margins for high-rise developers phasing multiple towers simultaneously. British Columbia's tiered energy-step mandates and Ontario's efficiency amendments add compliance premiums that stratify project costs across provincial boundaries.
Pricing Analysis
Geographic price spreads between Calgary-Edmonton corridors and Metro Vancouver-Greater Toronto clusters exceed thirty percent for equivalent mid-rise rental specifications. Project-based contract structures dominate, with price differentiation resting on energy-performance certification tiers and volume-scale procurement leverage. Cost compression in platform-framed wood segments is intensifying because British Columbia beetle-kill supply constraints and trade-duty uncertainty destabilize lumber input costs. First-time homebuyer segments exhibit highest price sensitivity, while REIT-led purpose-built rental developers absorb premiums for standardized, durable-finish packages that reduce long-term turnover expenditures.
Supply Chain Analysis
Inventory lead times for engineered wood products from British Columbia mills now extend beyond traditional seasonal patterns, forcing developers to pre-position materials ahead of spring construction windows. Supply concentration centers on British Columbia for dimensional lumber, Ontario for prefabricated modular assemblies, and Quebec for mass timber structural systems. Raw material dependencies span British Columbia coastal timber, Prairie region gypsum, and Asian-manufactured triple-glazed window units. Single-source vulnerability pervades ready-mix concrete in Metro Vancouver, where batch-plant capacity saturates during synchronized high-rise phasing. Distribution runs through integrated design-build contractors who coordinate just-in-time modular delivery with site crane schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional capital consolidation across Canadian rental-asset ownership has shifted procurement leverage toward REITs and pension-fund platforms, fragmenting contractor pricing power and standardizing specifications across multi-provincial portfolios.
For Market Incumbents: Shield margin positions by deepening captive supply of prefabricated wall assemblies through modular fabrication partnerships, insulating against Red Seal carpentry shortages that extend project timelines. Accelerate certification investment in Passive House and net-zero-ready standards to capture municipal density bonuses that offset land-cost inflation in Toronto and Vancouver corridors. For New Entrants and Emerging Players: Anchor in Alberta and Quebec secondary markets where mid-rise rental demand from interprovincial migration outpaces established contractor presence, and where National Building Code base standards avoid tiered efficiency delays. Pursue integrated project delivery contracts with municipal housing-accelerator fund recipients, leveraging digital fabrication capabilities to compress schedules for density-bonus-eligible sites. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors employee-ownership contractors with workforce continuity systems and coast-to-coast apprenticeship pipelines. Long-term viability across the projection horizon rests on firms controlling modular manufacturing capacity and design-build integration expertise. Monitor federal housing-accelerator fund disbursement velocity as the primary inflection signal for entitlement-acceleration opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Partnership | Factory-built assemblies offset skilled trades gaps in Greater Toronto and Metro Vancouver. |
| Passive House Certification Investment | Density bonuses from Vancouver and Toronto municipalities create margin premiums for certified projects. |
| Coast-to-Coast Apprenticeship Scaling | Workforce continuity systems reduce turnover among project managers and site supervisors. |
| Integrated Design-Build Delivery | Compressed schedules for condominium towers attract repeat developer clients in intensification corridors. |
| Secondary Market Geographic Expansion | Calgary and Edmonton corridors offer underpenetrated demand at lower land costs than Ontario or British Columbia. |
Study Parameters
The analysis maps single-family, multi-family, condominium, and townhouse construction segments, each validated through primary interviews with general contractor executives, municipal planning officers, prefabrication plant managers, and Canada Mortgage and Housing Corporation financing specialists. Secondary validation draws from National Building Code amendment filings, provincial energy-step code adoption timelines, municipal upzoning bylaws, and Canada Mortgage and Housing Corporation rental market reports. Bottom-up project pipeline enumeration triangulates against top-down construction spending benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass construction type, material category, project scale tier, and customer capital structure. CAGRs were derived from regression analysis of historical permit issuance patterns and forward projection of household formation rates. Industry-specific forecast inputs include interprovincial migration flows and federal housing-accelerator fund commitment schedules.
Material uncertainties — interest rate volatility, lumber trade-duty renegotiation, and provincial energy-tier adoption delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding mortgage-access conditions and municipal approval velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
US Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Residential Roofing Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Siding Market
Residential Construction
UK Residential Construction Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
North America Prefabricated Housing Market