
 Global Prefabricated Housing Market | 2026-2036
Global Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prefabricated Housing Market Foresight
Modular bundling of structural shells with pre-installed MEP systems is pivoting buyer choice toward turnkey configurations that slash field labor. Cavco Industries Inc. leverages factory-direct distribution to dominate price-sensitive segments across the American Southwest. Champion Home Builders Inc. anchors its position through vertical integration into chassis and appliance supply chains. Sekisui House Ltd. differentiates via precision-manufactured steel-frame modules engineered for seismic resilience in Japanese metropolitan corridors.
Prefabricated housing denotes dwelling units manufactured in controlled factory environments using standardized panel, module, or volumetric assembly methods, then transported and erected on permanent foundations; wall assemblies typically achieve R-values of 20-40 through integrated insulation layers, while floor cassettes span 8-16 feet to minimize field joints. Panelized homes currently occupy the largest production volume slot due to lower transport costs and flexible customization, yet 3D printed homes represent the fastest-expanding technology frontier as robotic extrusion of concrete and polymer composites compresses wall-formation cycles from days to hours. Steel and cross-laminated timber materials command premium positioning in multi-story and eco-certified projects, whereas wood-framed modules sustain margin pools in single-family and rural deployments.
FDA building-product oversight, EPA emissions standards for factory operations, and ISO 3834 welding quality protocols collectively shape material certification burdens and factory audit frequencies across manufacturing jurisdictions. REACH chemical restrictions in Europe and China's GB standards for structural steel further complicate cross-border component sourcing for multinational producers. Stakeholders must monitor evolving municipal zoning amendments that alternately restrict or incentivize factory-built density in transit-adjacent districts.
Market Dynamics
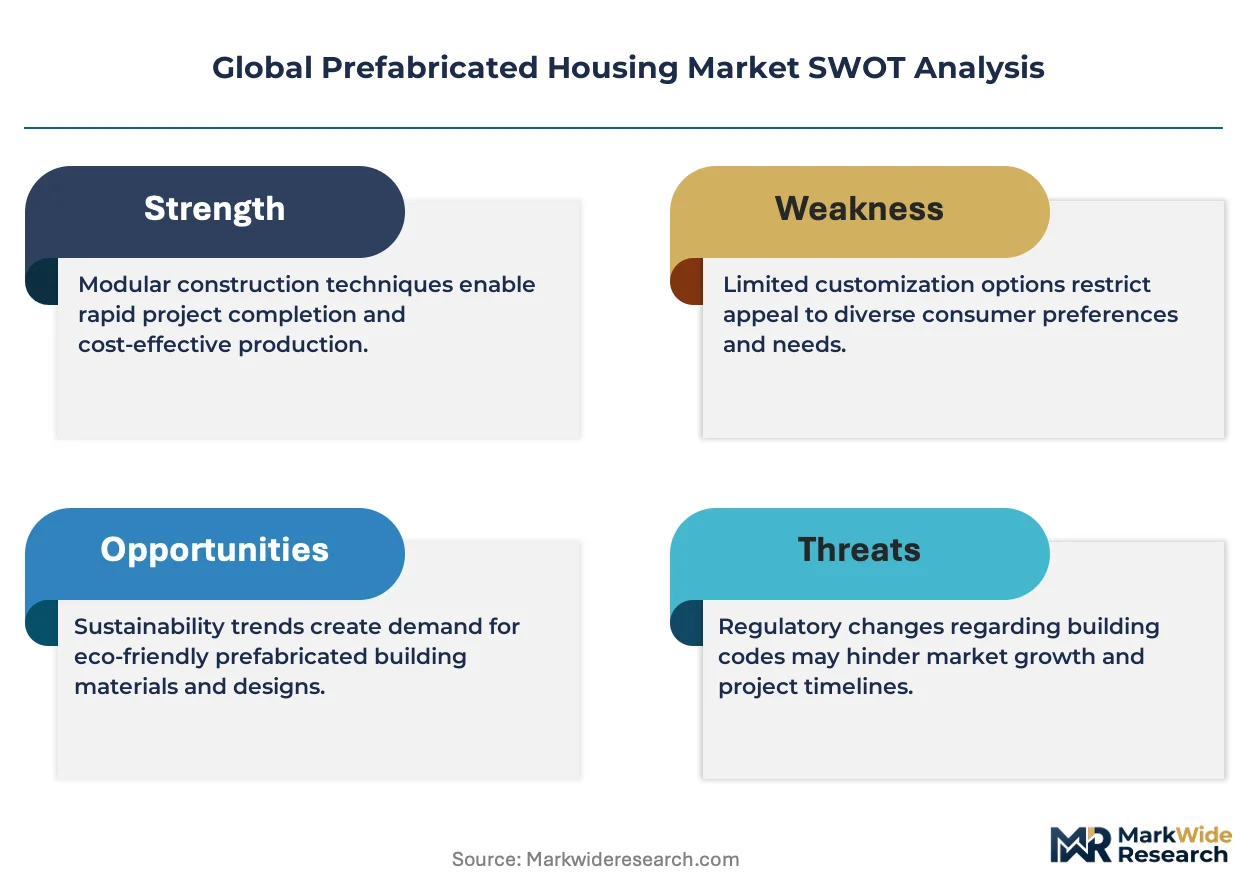
Factory automation of structural panel production is compressing fabrication cycles while cross-laminated timber engineering advances reduce material waste across multi-story residential deployments.
Growth Catalysts
- US Affordable Housing Initiatives:Federal and state housing agencies expand procurement quotas for modular residential units, accelerating factory-built solutions in urban corridors facing acute supply shortages.
- Cross-Laminated Timber Engineering:Advances in CLT fabrication reduce on-site assembly cycles and enable taller wood-frame construction, displacing conventional concrete in mid-rise residential projects.
- Urban Density Pressures:Metropolitan areas in China, Germany, and the United States favor volumetric modules that minimize field labor and accelerate project delivery timelines.
Market Restraints
- Transport Cost Structure:Volumetric module dimensions trigger oversized load permits and route restrictions, inflating logistics expenditure for projects beyond 500-mile radii from fabrication facilities.
- Steel Input Volatility:Fluctuations in global steel pricing compress margin pools for steel-frame module producers serving multi-story and seismic-resilient segments.
- REACH Chemical Restrictions:European ECHA compliance mandates for adhesive binders and surface treatments complicate cross-border component sourcing for multinational producers.
Strategic Opportunities
- India Affordable Housing Gap:Underpenetrated factory-built penetration in tier-2 and tier-3 cities creates white space for panelized systems meeting BIS structural standards and PMAY subsidy eligibility.
- 3D Concrete Printing Convergence:Integration of robotic extrusion with polymer composite reinforcement compresses wall-formation cycles, opening custom architectural geometries previously uneconomical with conventional forming.
- Japan Seismic Retrofit Mandates:METI building resilience guidelines accelerate replacement demand for precision-manufactured steel-frame modules engineered to JIS seismic performance tiers.
Industry Challenges
- Certification Timeline Compression:Factory audit frequencies under ISO 3834 welding protocols and EPA emissions standards extend product qualification cycles, delaying project mobilization.
- MEP Integration Complexity:Pre-installation of mechanical, electrical, and plumbing systems in controlled environments demands specialized technician pools scarce in traditional construction labor markets.
Report Scope
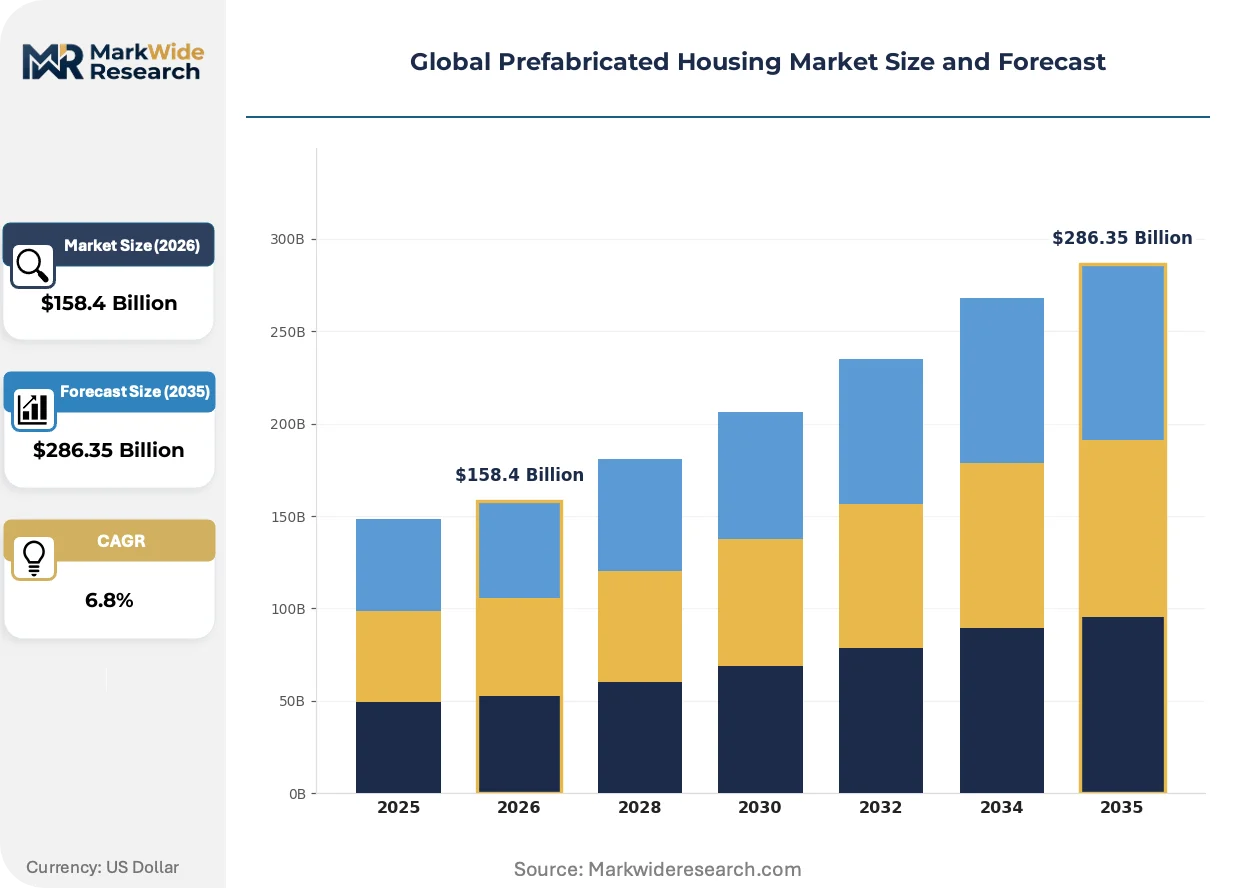
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prefabricated Housing Market |
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $286.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cut Homes, 3D Printed Homes Material: Wood, Steel, Concrete, Composite End User: Residential, Commercial, Industrial, Government Distribution Channel: Direct Sales, Retail, Online, Wholesaler |
| Companies Covered | Cavco Industries Inc., Champion Home Builders Inc., Daiwa House Industry Co. Ltd., Berkshire Hathaway Inc., Clayton Homes Inc., Sekisui House Ltd., Skyline Champion Corporation, Skanska AB, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prefabricated Housing Market Shifts & Advancements
Digital fabrication workflows and material science advances are compressing design-to-occupancy timelines while regulatory frameworks recalibrate around embodied carbon accounting.
Cross-laminated timber is integrating fire-rated encapsulation systems and moisture management layers to meet multi-story building codes previously reserved for concrete and steel. German and Austrian housing cooperatives are specifying CLT-core modules at accelerating rates. This material convergence is enabling timber structural systems to penetrate urban infill projects above six stories.
China's GB standards for structural steel and dual carbon goals are tightening factory emissions monitoring and material traceability requirements. Domestic producers face accelerated capital expenditure for emissions capture and renewable energy sourcing. Steel-frame module exports to European markets now require third-party verification against ECHA substance restrictions.
Buyer preference is consolidating around turnkey configurations bundling structural shells with pre-installed MEP systems, displacing traditional design-bid-build procurement. US multifamily developers and student housing operators are specifying factory-direct procurement models. This channel consolidation concentrates specification authority with national-scale producers capable of warranty-backed performance guarantees.
Global Prefabricated Housing Market Segmentation
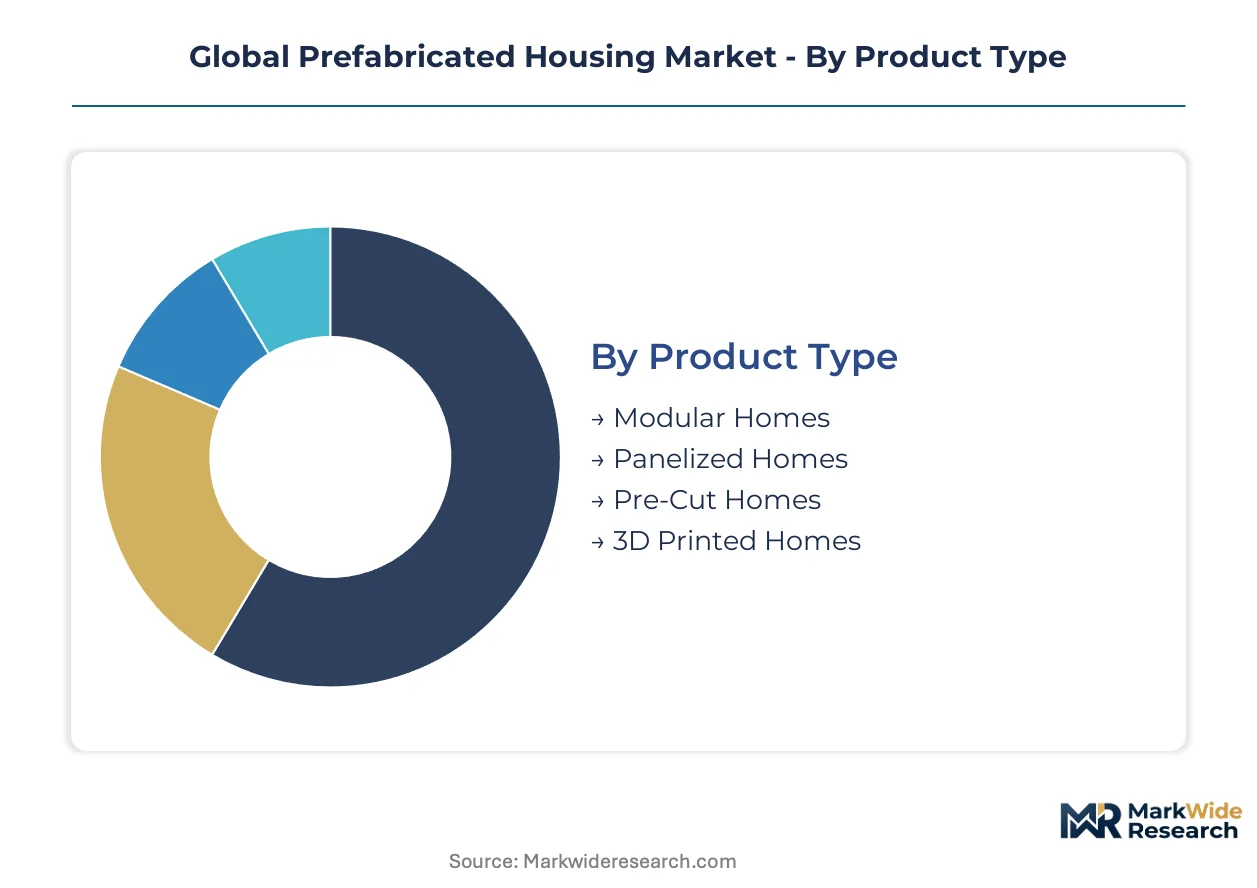
Segmentation in prefabricated housing reveals how factory automation, material science, and procurement channels reshape competitive positioning. Each dimension exposes distinct margin structures and capital intensity profiles that determine manufacturer viability across price-sensitive and premium deployment contexts.
Product Type:
Supply concentration tilts toward volumetric systems that capture economies of scale in controlled factory environments.
- Modular Homes:Complete volumetric units with pre-installed MEP systems manufactured to 90-95% completion before site delivery. Demand concentrates in United States urban corridors where labor shortages and federal affordable housing procurement accelerate adoption.
- Panelized Homes:Flat-packed wall, floor, and roof assemblies offering transport efficiency and field customization flexibility. Germany and Austria specify CLT-core panelized systems for multi-story residential infill above six stories.
- Pre-Cut Homes:Factory-cut framing components shipped as kit packages for on-site assembly by local crews.
- 3D Printed Homes:Robotic extrusion of concrete and polymer composites compressing wall-formation cycles from days to hours.
Panelized homes absorb the bulk of installed capacity; 3D printed homes are expanding most quickly.
Material:
Cost tier stratification separates premium structural systems from commodity framing inputs.
- Wood:Dimensional lumber and engineered wood products sustaining margin pools in single-family and rural deployments across North American markets.
- Steel:Cold-formed and structural steel framing commanding premium positioning in multi-story and seismic-resilient projects. Japan's METI building resilience guidelines accelerate replacement demand for precision-manufactured steel-frame modules engineered to JIS seismic performance tiers.
- Concrete:Precast and site-cast concrete systems dominating foundation and core structural elements in high-density urban deployments.
- Composite:Fiber-reinforced polymer and hybrid material systems enabling custom architectural geometries and enhanced thermal performance envelopes.
Wood commands the greatest production volume; steel claims the steepest expansion trajectory in multi-story residential.
End User:
Application maturity varies sharply between established residential procurement and emerging industrial deployment models.
- Residential:Single-family, multifamily, and student housing specifications driving factory-direct procurement consolidation. US multifamily developers and student housing operators are specifying factory-direct procurement models with warranty-backed performance guarantees.
- Commercial:Office, retail, and hospitality modules requiring accelerated project delivery timelines.
- Industrial:Worker accommodation, site offices, and temporary facilities for extractive and infrastructure projects.
- Government:Federal and state housing agency procurement quotas for modular residential units in urban corridors facing acute supply shortages.
Residential absorbs the bulk of installed capacity; government procurement is expanding most quickly through affordable housing mandates.
Distribution Channel:
Customer type determines channel power concentration between factory-direct relationships and intermediated retail networks.
- Direct Sales:Factory-direct relationships with national-scale developers and housing agencies enabling specification authority consolidation and warranty-backed performance guarantees.
- Retail:Dealer networks serving individual homebuyers with customization support and financing facilitation.
- Online:Digital configuration platforms and virtual showroom experiences emerging for standardized module selection.
- Wholesaler:Bulk procurement intermediaries supplying regional builders and construction aggregators with panelized and pre-cut systems.
Direct sales absorb the bulk of transaction value; online channels are expanding most quickly through configuration platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory capacity concentrates in China, the United States, and Germany while consumption spreads across urban corridors facing acute housing shortages. Japan and India represent emerging demand centers where regulatory tailwinds accelerate modular adoption. Cross-border module trade remains constrained by transport economics and divergent building codes.
United States
Federal affordable housing procurement quotas and HUD financing incentives drive modular residential deployment across California and Texas urban corridors. EPA emissions standards for factory operations and state-level building codes shape manufacturer compliance burdens. Factory-direct distribution clusters in the American Southwest where Cavco Industries Inc. leverages captive retail networks.
China
Dual carbon goals and GB standards for structural steel tighten factory emissions monitoring while accelerating steel-frame module production. MIIT industrial policy directs capital toward automated panel fabrication in the Yangtze River Delta. Shenzhen and Shanghai municipal governments incentivize volumetric modules for transit-adjacent density.
Germany
REACH chemical restrictions and the EU Green Deal recalibrate material sourcing for CLT-core panelized systems. ECHA compliance mandates for adhesive binders complicate cross-border component procurement. Bavarian and Austrian housing cooperatives specify engineered timber modules for multi-story residential infill above six stories.
Japan
METI building resilience guidelines and JIS seismic performance tiers accelerate replacement demand for precision-manufactured steel-frame modules. Tokyo and Osaka metropolitan corridors favor factory-built solutions to compress project delivery timelines. Sekisui House Ltd. anchors domestic supply through seismic-engineered volumetric systems.
India
PMAY subsidy eligibility and BIS structural standards create procurement pathways for panelized systems in tier-2 and tier-3 cities. CEA electrical safety codes and state-level urban development authorities shape factory certification requirements. Gujarat and Maharashtra industrial corridors attract capacity investment for affordable housing module fabrication.
Global Prefabricated Housing Market Competitive Landscape
The competitive structure tilts toward vertically integrated national-scale producers capable of warranty-backed performance guarantees. Factory-direct relationships with multifamily developers and housing agencies concentrate specification authority among three to five dominant players. Two strategic archetypes predominate: steel-frame specialists serving seismic-resilient multi-story segments and wood-framed volume producers targeting single-family affordability tiers. Competitive moves center on backward integration into chassis and appliance supply chains alongside geographic expansion through regional fabrication networks.
Among United States-based fabricators, Cavco Industries Inc., Champion Home Builders Inc., and Clayton Homes Inc. occupy positions within the wood-framed volume tier. Sekisui House Ltd. represents the steel-frame seismic specialist archetype. Daiwa House Industry Co. Ltd. and Skyline Champion Corporation exemplify scale-driven national operators. Berkshire Hathaway Inc. sits within the diversified industrial holding structure. Skanska AB anchors European construction-integrated module deployment. Asahi Kasei Corporation exemplifies materials-to-modules vertical integration.
| Leading Market Players |
|---|
| Cavco Industries Inc. |
| Champion Home Builders Inc. |
| Daiwa House Industry Co. Ltd. |
| Berkshire Hathaway Inc. |
| Clayton Homes Inc. |
| Sekisui House Ltd. |
| Skyline Champion Corporation |
| Skanska AB |
| Asahi Kasei Corporation |
| Others |
Supply & Pricing Matrix
Seismic-performance certification tiers bifurcate the prefabricated housing market into premium steel-frame modules and commodity wood-framed units, with each tier commanding distinct supply chain configurations and pricing power anchored in regulatory compliance burdens.
Pricing Analysis
Cost-down pressure on steel-frame modules accelerates because global steel input volatility compresses margin pools for producers serving multi-story and seismic-resilient segments. Project-based contract pricing dominates, with differentiation driven by JIS seismic certification grade and factory-direct volume scale. Wood-framed volume producers face acute price sensitivity from individual homebuyers, while steel-frame specialists command premium resilience from government housing agencies.
Supply Chain Analysis
Dual-sourcing requirements from US multifamily developers and Japanese METI procurement mandates force qualification of multiple CLT and steel suppliers across China, Germany, and Austria. Raw material dependencies center on cross-laminated timber adhesives, cold-formed steel coils, and concrete admixtures. Single-source vulnerability concentrates in oversized transport logistics for volumetric modules beyond 500-mile radii. Distribution runs through factory-direct relationships with national-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 3834 welding protocols and EPA emissions standards erect compliance moats that favor capitalized incumbents while screening out underfunded entrants across factory-built housing manufacturing.
For Market Incumbents: Deepen backward integration into chassis and appliance supply chains to defend margin position against steel input volatility. Expand automated panel fabrication capacity in the Yangtze River Delta to capture Chinese dual carbon procurement quotas. Prioritize MEP technician apprenticeship pipelines to address scarce specialized labor pools. For New Entrants and Emerging Players: Regional housing cooperatives in Bavaria and Austria offer channel access for CLT-core panelized systems targeting multi-story residential infill above six stories. White space exists in India's tier-2 and tier-3 cities where PMAY subsidy eligibility meets underpenetrated factory-built penetration. Pursue turnkey configuration partnerships with student housing operators seeking warranty-backed performance guarantees. For Investors and Strategic Acquirers: Re-rating potential sits with steel-frame seismic specialists given Japan's METI building resilience guidelines accelerating replacement demand. Long-term viability favors producers with captive supply of certified structural materials and established factory-direct government procurement relationships. Monitor municipal zoning amendments in transit-adjacent districts as inflection signal for volumetric module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chassis Manufacturing | Cavco Industries leverages captive chassis production to dominate price-sensitive Southwest markets. |
| Automated Panel Fabrication Scale-Up | MIIT industrial policy directs Chinese capital toward Yangtze River Delta factory automation. |
| Seismic Certification Investment | Sekisui House anchors Japanese supply through JIS-tier steel-frame engineering. |
| Factory-Direct Government Partnership | US affordable housing procurement quotas concentrate specification authority with national-scale producers. |
| CLT Fire-Rated Encapsulation Development | German and Austrian cooperatives specify engineered timber modules for six-plus-story urban infill. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this prefabricated housing analysis. Primary interviews with factory operations directors, multifamily developer procurement leads, municipal zoning officials, and CLT adhesive suppliers combined with bottom-up and top-down triangulation. Secondary sources encompassed EPA emissions compliance databases, ECHA REACH substance registries, BIS structural standard filings, and MIIT industrial policy directives.
Data-stream reconciliation across shipment volumes, factory capacity utilization, and procurement contract values informed the analytical framework. Segmentation dimensions modeled encompassed product type, material grade, end-use application, and distribution channel across the analysis window. CAGRs derived from regression analysis of historical factory output and forward-projected housing agency procurement quotas, with cross-laminated timber adoption curves and steel price elasticity as industry-specific inputs.
Caveats apply where steel commodity volatility or municipal zoning reversals could materially shift the outlook. Deviation in EPA emissions enforcement intensity or ECHA adhesive binder restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
UK Residential Construction Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Siding Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
Austria Prefabricated Housing Market