
 North America Popping Boba/Juice Balls Market | 2026-2036
North America Popping Boba/Juice Balls Market Size, Share, and Industry Trends Forecast 2026-2036
North America Popping Boba/Juice Balls Market Analytics
FDA food facility registration is collapsing as a meaningful barrier, with smaller importers now facing the same compliance burden as established operators. Bossen leverages its West Coast distribution network to dominate bulk supply into independent tea shops. Tea Zone sustains competitive positioning through specialized flavor development for foodservice accounts. Gong Cha anchors North American demand through captive consumption across its franchise network.
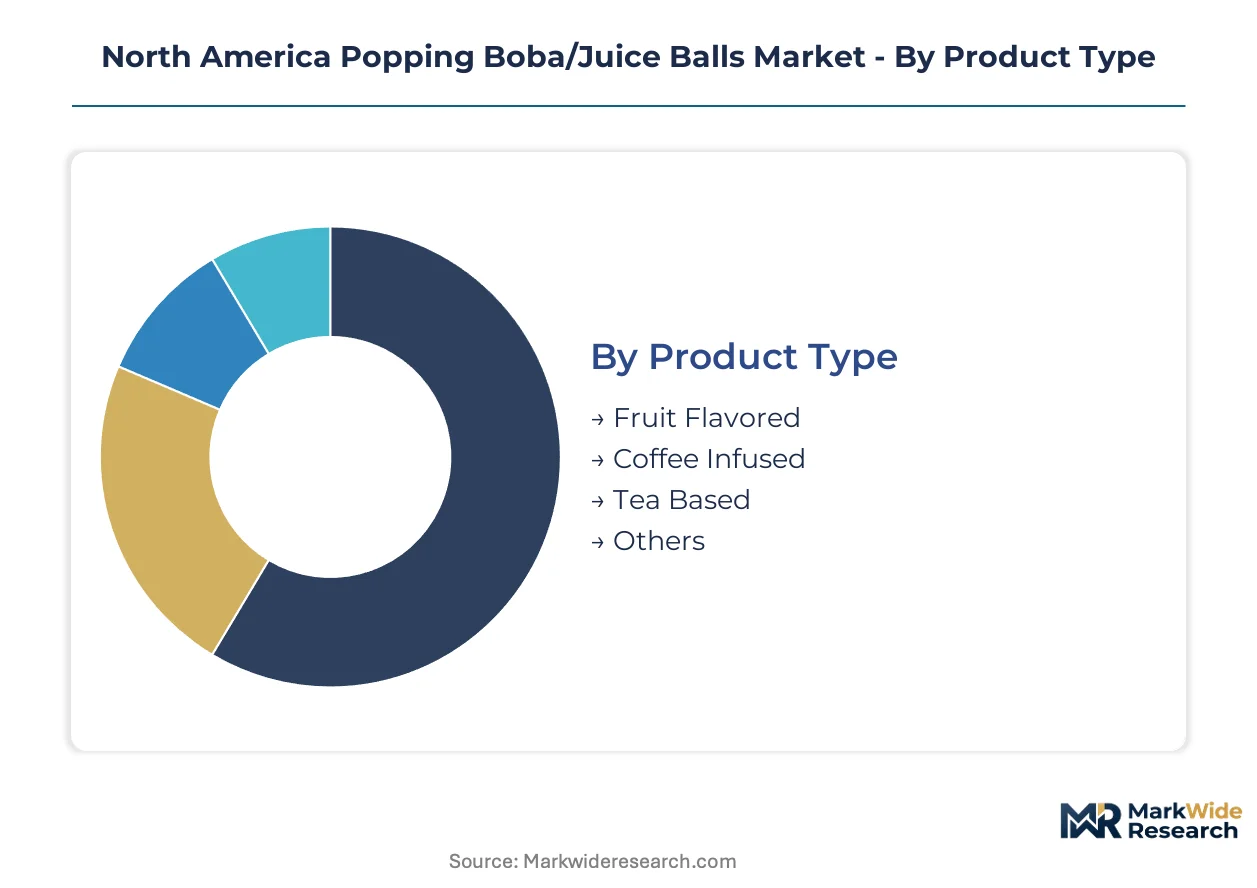
Popping boba consists of gel spheres formed via reverse spherification or extrusion-dripping into calcium baths, typically comprising sodium alginate, fruit juice or flavored syrup, and a thin calcium chloride skin that ruptures under pressure. The primary commercial purpose is to deliver burst-texture contrast in beverages, desserts, and frozen treats without diluting base formulations. Fruit flavored product types occupy the volume lead across retail and foodservice channels, while tea based variants capture premium positioning in specialty cafe menus. Bulk bags dominate procurement for high-throughput beverage manufacturers, whereas plastic cups and pouches concentrate in convenience retail and single-serve applications.
The FDA enforces ingredient safety and allergen labeling under FSMA, while CFIA administers parallel import inspection protocols for alginate and juice concentrate shipments entering Canada. These frameworks elevate compliance costs for new entrants but also standardize quality thresholds that benefit scaled suppliers with in-house laboratory capabilities. Stakeholders must monitor evolving state-level plastic packaging restrictions and sugar-content disclosure mandates that could reshape formulation and packaging decisions across the value chain.
Market Dynamics
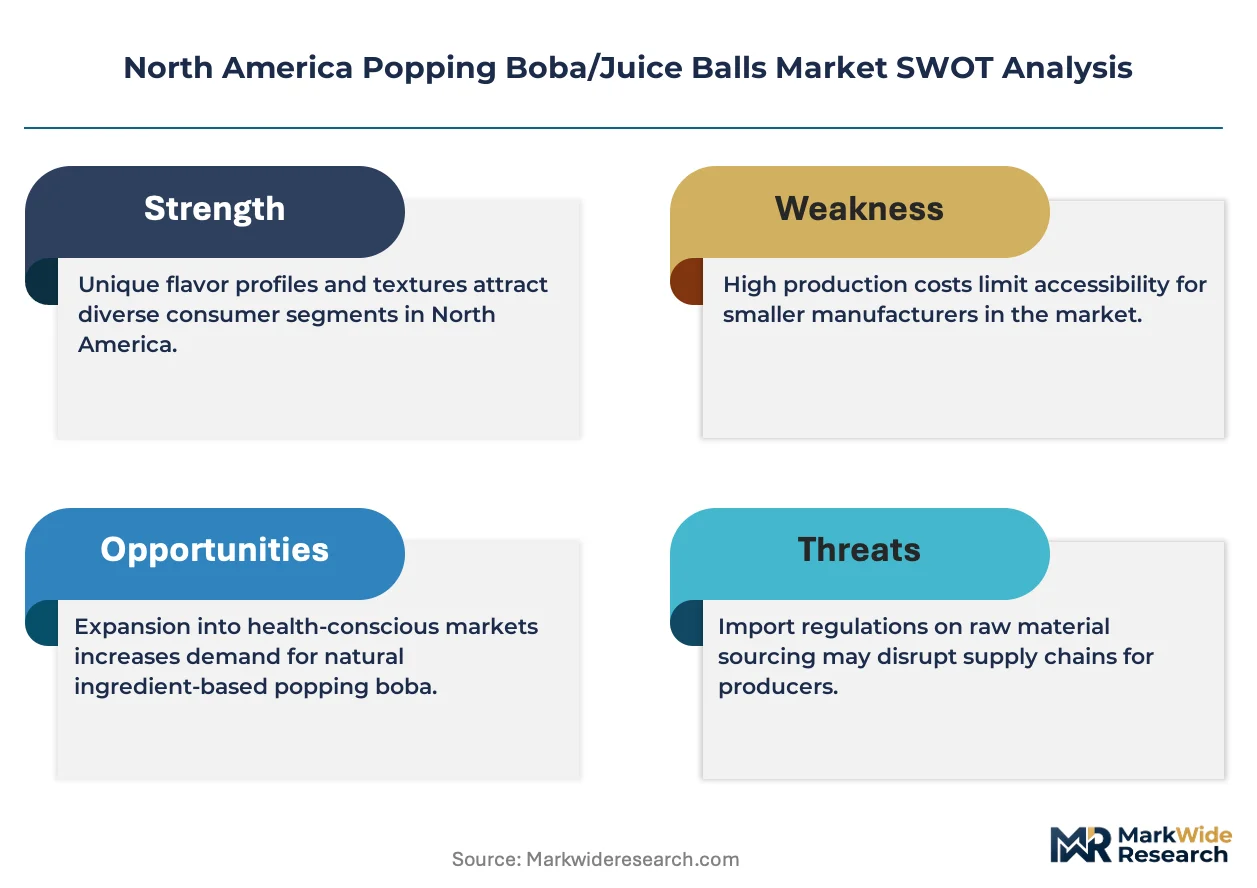
The North America Popping Boba/Juice Balls Market faces intensifying pressure from FSMA-mandated ingredient traceability, which forces alginate and juice concentrate importers to rebuild documentation systems and laboratory capabilities from the ground up.
Growth Catalysts
- Beverage chain SKU proliferation:Independent tea shops and franchise operators across California and Ontario are expanding textured drink menus, creating steady pull for bulk supply contracts.
- FDA facility registration standardization:The Food Safety Modernization Act's unified compliance burden erodes incumbent advantages, opening procurement to qualified new entrants with laboratory investments.
- Asian foodservice cluster density:The Greater Toronto Area's concentrated bubble tea corridor generates network effects that lower distribution costs for specialty flavor variants.
Market Restraints
- Input cost volatility:Sodium alginate prices fluctuate with kelp harvest yields and Chilean supply disruptions, compressing margin predictability for formulators.
- Single-source hydrocolloid dependency:North American manufacturers rely heavily on Asian alginate processors, exposing production schedules to trans-Pacific shipping congestion.
- Calcium chloride handling regulations:OSHA workplace exposure limits and EPA discharge standards elevate facility compliance costs for sphere-forming operations.
Strategic Opportunities
- Underpenetrated Canadian prairies:Calgary and Edmonton foodservice markets show rising bubble tea adoption with limited local boba supply infrastructure.
- Clean-label alginate alternatives:Pectin-based spherification technologies are converging with consumer preference for recognizable ingredient decks in premium channels.
- State-level sugar disclosure mandates:California and New York nutrition labeling expansions create first-mover advantage for low-sugar boba formulations that preempt compliance.
Industry Challenges
- Spherification technician scarcity:Food science programs produce few graduates trained in reverse spherification scale-up, forcing manufacturers to build in-house training pipelines.
- Legacy ERP integration friction:Lot-tracking software for FSMA compliance often conflicts with existing inventory systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Popping Boba/Juice Balls Market |
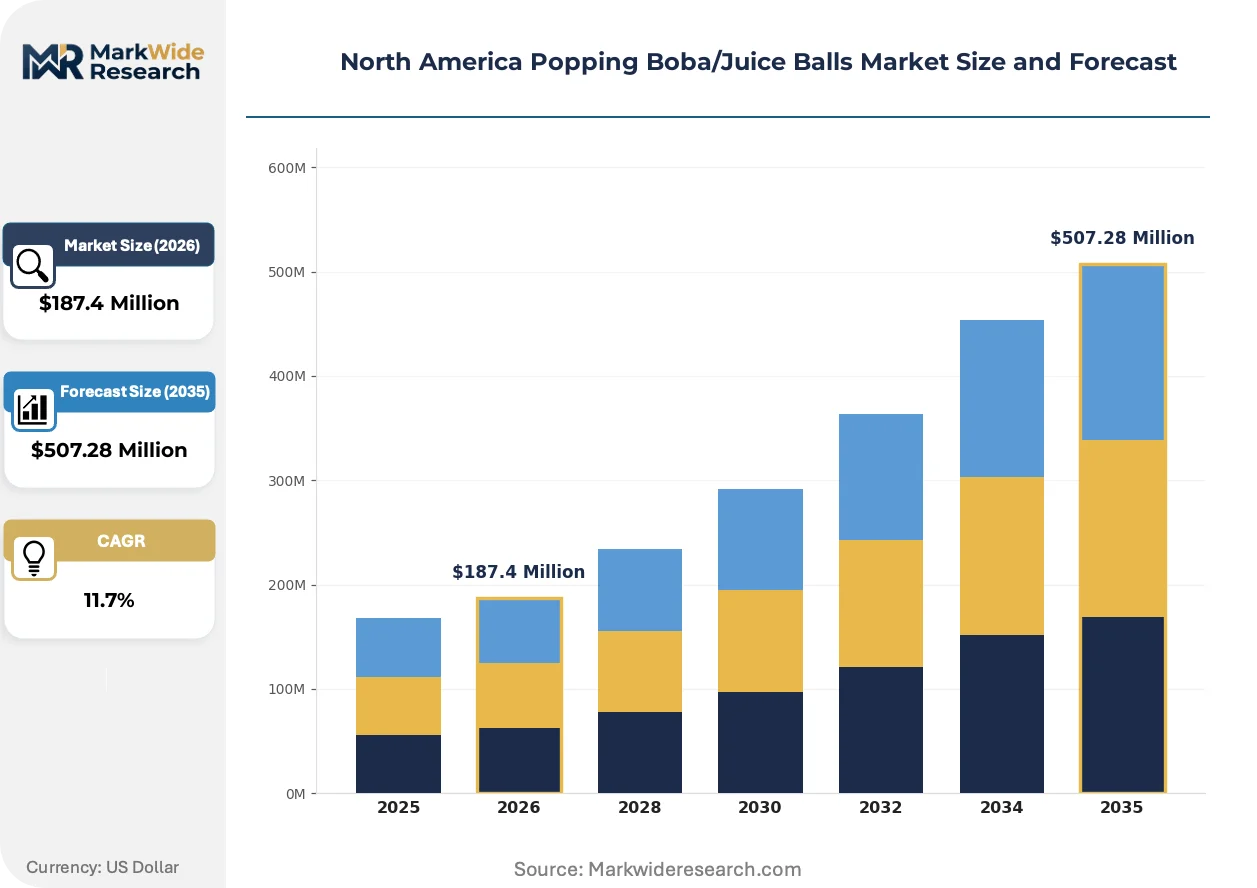
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavored, Coffee Infused, Tea Based, Others End User: Restaurants, Cafes, Beverage Manufacturers, Retailers Flavor Profile: Sweet, Sour, Mixed Fruit, Savory Packaging Type: Plastic Cups, Bulk Bags, Jarred, Pouches |
| Companies Covered | Zentis North America, Bossen, Tea Zone, Gong Cha, Kung Fu Tea, CoCo Fresh Tea and Juice, Boba Guys, Qbubble, Fusion Select, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Popping Boba/Juice Balls Market Evolving Landscape
Texture-driven beverage innovation is forcing rapid adaptation across formulation, equipment, and supply chain architecture. Three developments are compressing competitive timelines and reshaping procurement priorities.
Cold-set spherification using modified pectin gelling systems is decomposing the alginate monopoly in premium product tiers. Specialty cafe chains in Vancouver and Portland are piloting these alternatives to differentiate clean-label menus. The technology is decomposing traditional supplier relationships by enabling juice processors to bring sphere production in-house without calcium bath infrastructure.
FSMA's Foreign Supplier Verification Program is tightening documentary requirements for every alginate and concentrate shipment entering US ports. Small importers now face identical audit burdens to established distributors, accelerating consolidation toward scaled operators with captive laboratory resources. California's beverage manufacturers are responding by dual-sourcing hydrocolloids and pre-qualifying backup suppliers.
Direct procurement from Taiwanese and Thai equipment manufacturers is displacing traditional distributor intermediaries among mid-size tea shop chains. Buyers are configuring extrusion-dripping systems through video technical support rather than domestic resellers. This pattern concentrates most visibly in Texas and Florida markets where franchise growth outpaces local service infrastructure.
North America Popping Boba/Juice Balls Market Segmentation
Segmentation in the North America Popping Boba/Juice Balls Market reveals distinct procurement patterns between foodservice operators seeking bulk supply efficiency and retail channels prioritizing shelf-ready formats. Understanding these divides shapes formulation, packaging investment, and distribution strategy across the value chain.
Product Type:
Domestic formulation dominates fruit flavored and tea based variants through California and Ontario production clusters, while coffee infused lines rely heavily on imported concentrate from Southeast Asian processors.
- Fruit Flavored:Gel spheres incorporate apple, mango, or strawberry juice concentrates suspended in sodium alginate matrices. Demand concentrates in California's bubble tea corridor where independent shops prioritize vivid color stability and consistent burst texture for Instagram-visible beverages.
- Tea Based:Matcha, oolong, and jasmine infusions command premium positioning through specialized alginate encapsulation that preserves volatile aromatic compounds. Ontario's Greater Toronto Area foodservice cluster generates concentrated pull for these variants in specialty cafe menus.
- Coffee Infused:Cold brew and espresso concentrates require modified calcium bath concentrations to prevent bitterness migration. Thai and Vietnamese import channels supply most North American volume.
- Others:Includes yogurt-filled spheres and experimental savory prototypes from Vancouver pilot kitchens.
Fruit flavored holds the largest share; momentum sits with tea based.
End User:
Volume scale separates high-throughput beverage manufacturers from fragmented restaurant procurement, with margin structure inversely tracking order frequency.
- Beverage Manufacturers:Automated bottling lines demand calibrated sphere diameters within 0.5mm tolerances and extended shelf stability through modified atmosphere packaging. Texas and Florida franchise chains drive contract consolidation toward suppliers with FSMA-compliant laboratory infrastructure.
- Cafes:Independent bubble tea shops in Calgary and Edmonton prioritize flexible minimum order quantities and rapid flavor rotation over unit cost optimization.
- Restaurants:Asian fusion concepts across the Pacific Northwest incorporate popping boba into dessert applications with lower throughput requirements.
- Retailers:Convenience stores and grocery chains specify individual portion controls and bilingual labeling for cross-border distribution.
Beverage manufacturers capture the volume lead; cafes are expanding most quickly.
Flavor Profile:
Formulation complexity escalates from single-note sweet profiles to layered mixed fruit and savory experiments, with R&D investment tracking premium positioning.
- Sweet:Standard glucose-fructose syrup bases with artificial or natural colorants dominate commodity supply into quick-service beverage chains.
- Mixed Fruit:Layered flavor releases combining tropical and temperate fruit notes require precise osmotic pressure calibration during spherification.
- Sour:Citric acid incorporation demands modified alginate concentrations to prevent premature skin degradation; popular in Pacific Northwest specialty menus.
- Savory:Experimental cheese and herb infusions remain confined to high-end dessert applications in Vancouver and Portland test markets.
Sweet maintains dominant share; mixed fruit shows steepest expansion trajectory.
Packaging Type:
Supply chain configuration separates bulk foodservice logistics from retail-ready unit economics, with regulatory pressure on plastic formats reshaping procurement timelines.
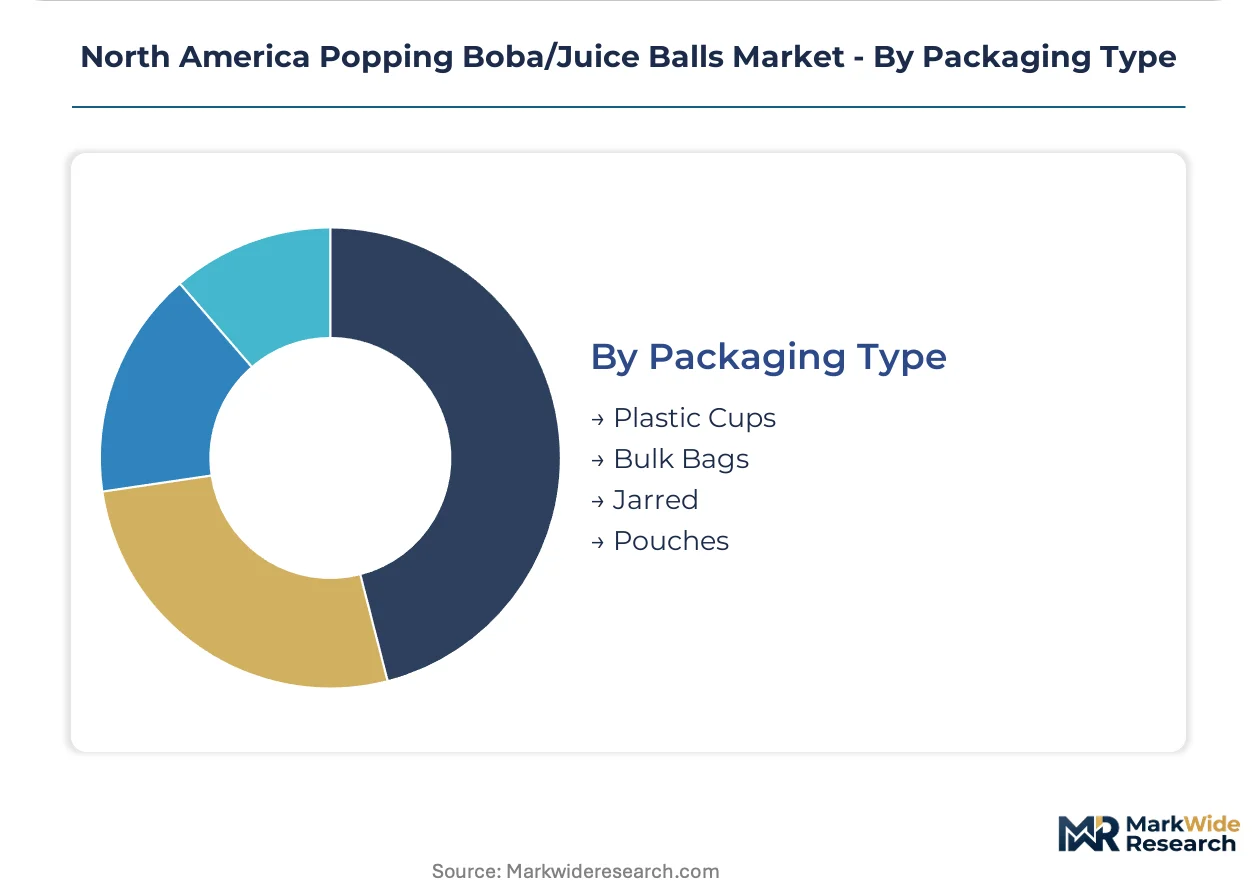
- Bulk Bags:Multi-kilogram polyethylene liners with nitrogen flushing serve high-throughput beverage manufacturers and franchise operators. California's state-level plastic restrictions are forcing migration toward recyclable film alternatives.
- Pouches:Single-serve flexible packaging concentrates in convenience retail and foodservice portion control applications.
- Plastic Cups:Pre-portioned retail formats with sealed lids dominate grab-and-go channels; facing regulatory headwinds in New York and California.
- Jarred:Glass containers with brine preservation occupy premium grocery positioning and gift market applications.
Bulk bags command the volume base; pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex processes the majority of sodium alginate and juice concentrate imports feeding North American spherification operations, while Canadian Pacific Railway intermodal links distribute hydrocolloids to Calgary and Edmonton foodservice hubs.
United States
California's bubble tea corridor drives concentrated demand for vivid fruit-flavored spheres, with independent Los Angeles and San Francisco shops prioritizing Instagram-visible color stability. FDA's Food Safety Modernization Act mandates laboratory-verified lot tracking for every alginate shipment entering West Coast ports. Texas and Florida franchise expansion outpaces local service infrastructure, forcing direct equipment procurement from Asian manufacturers.
Canada
The Greater Toronto Area's Asian foodservice cluster generates network effects that lower distribution costs for premium tea-based variants in specialty cafe menus. CFIA administers parallel import inspection protocols for alginate and juice concentrate shipments entering Vancouver and Montreal customs zones. Calgary and Edmonton markets show rising bubble tea adoption with limited local boba supply infrastructure, creating procurement bottlenecks for prairie operators.
Mexico
Mexico City Metro's emerging bubble tea scene sources popping boba through cross-border distributors operating Laredo-Nuevo Laredo logistics corridors. COFEPRIS food additive regulations require Spanish-language labeling and modified starch documentation for retail-format imports. Guadalajara's foodservice cluster experiments with tropical fruit sphere formulations using domestic mango and guava concentrates.
North America Popping Boba/Juice Balls Market Competitive Landscape
Listed leaders compete with private specialists across supply chain control and flavor development capabilities. The market structures around three tiers: scaled distributors with captive laboratory infrastructure, franchise networks with captive consumption, and independent formulators serving regional foodservice clusters. Strategic moves concentrate on backward integration into alginate sourcing and geographic expansion into underpenetrated prairie markets.
Within the distributor tier, Bossen leverages West Coast logistics networks to anchor bulk supply relationships with independent tea shops. Tea Zone occupies a specialist position through dedicated flavor development for foodservice accounts. Gong Cha exemplifies the franchise-integrated model, with captive consumption across company-operated and franchised locations driving predictable procurement volumes.
| Leading Market Players |
|---|
| Zentis North America |
| Bossen |
| Tea Zone |
| Gong Cha |
| Kung Fu Tea |
| CoCo Fresh Tea and Juice |
| Boba Guys |
| Qbubble |
| Fusion Select |
| Others |
Value Network & Pricing Analysis
FDA's Foreign Supplier Verification Program gates both supply qualification and price differentiation simultaneously, forcing alginate importers to absorb laboratory certification costs that stratify bulk procurement tiers while compressing margins for non-compliant operators.
Pricing Analysis
Volume-discount tiering structures separate FSMA-certified bulk suppliers from commodity-grade spot vendors, with beverage manufacturers capturing 15-20 point spreads over independent tea shops. Price differentiation rests on laboratory traceability documentation and captive West Coast distribution networks. Cost compression in standard-grade fruit-flavored spheres is intensifying because Thai and Vietnamese concentrate exporters are bypassing domestic distributors. Franchise beverage chains exhibit lowest price sensitivity; independent Calgary and Edmonton operators face acute margin pressure.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach elevates landed costs for Chilean kelp-derived sodium alginate and Taiwanese extrusion equipment, compressing procurement timelines for California formulation facilities. Supply concentrates in Thailand, Vietnam, and coastal China for juice concentrates and alginate processing. Raw material dependencies span kelp harvests, calcium chloride industrial grades, and modified starch stabilizers. Single-source vulnerability pervades trans-Pacific hydrocolloid lanes. Distribution runs through West Coast bulk distributors into Texas and Florida franchise corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as direct equipment procurement from Asian manufacturers displaces traditional distributor intermediaries, eroding geographic exclusivity and compressing service-margin pools across the value chain.
For Market Incumbents: Shield laboratory-verified supply relationships by accelerating backward integration into alginate sourcing and pre-qualifying backup Chilean kelp processors before FSMA audit windows tighten. Deepen captive distribution infrastructure in Calgary and Edmonton to preempt prairie-market entrants. Certification investment represents the priority defensive lever against clean-label pectin substitutes. For New Entrants and Emerging Players: Anchor in Alberta's underpenetrated bubble tea corridor where local supply infrastructure gaps create procurement bottlenecks for existing prairie operators. Target independent tea shops with flexible minimum-order quantities and rapid flavor rotation capabilities that scaled distributors cannot match. Direct technical support for extrusion-dripping equipment configuration offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FSMA-compliant laboratory infrastructure, favoring scaled operators with captive quality-assurance capabilities over fragmented formulators. Long-term viability over the coming decade hinges on backward integration into hydrocolloid sourcing and geographic diversification beyond California-Ontario production clusters. Watch alginate price volatility indices as the key inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alginate Sourcing | Captive kelp supply from Chilean processors insulates Bossen and Tea Zone from trans-Pacific shipping disruptions. |
| FSMA Laboratory Certification Investment | In-house lot-tracking capabilities open procurement channels to Texas and Florida franchise expansion. |
| Clean-Label Pectin Formulation Development | Vancouver and Portland specialty cafes pilot modified gelling systems to differentiate premium menus. |
| Prairie Distribution Network Buildout | Calgary and Edmonton infrastructure addresses rising bubble tea adoption with limited local supply. |
| Direct Equipment Procurement from Taiwan | Mid-size chains configure extrusion systems through video support, bypassing domestic reseller margins. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA import inspection records, CFIA border documentation, and trade flow databases covering alginate and juice concentrate shipments. Conversations with beverage manufacturing procurement directors, independent tea shop operators, foodservice distribution managers, and spherification equipment technicians informed demand-side validation. Secondary sources include customs manifests, FSMA compliance filings, and provincial health authority inspection reports. Bottom-up volume estimates from individual production facilities triangulate against top-down trade data.
Segmentation dimensions modeled span product type, end-user category, flavor profile, and packaging format across the analysis window. CAGRs derive from exponential trend fitting against historical trade volumes and projected franchise expansion patterns. Forecast inputs incorporate kelp harvest yield variability, California state-level plastic restriction timelines, and prairie-market penetration assumptions for Alberta and Saskatchewan foodservice clusters.
Material uncertainties — kelp supply disruptions, trans-Pacific shipping congestion, and state-level sugar disclosure mandate implementations — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and input cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Honey Market
Specialty Foods
Moringa Products Market
Specialty Foods
Sea Moss Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Algeria Couscous Market