
 Vegetarian Taquitos Market | 2026-2036
Vegetarian Taquitos Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetarian Taquitos Market Analytics
Single-source reliance on frozen-distribution networks is decoupling as brands diversify into fresh and direct-to-consumer channels. MorningStar Farms leverages its legacy freezer-aisle dominance to sustain volume leadership across mass retail. Gardein competes through aggressive foodservice placement, anchoring supply relationships with regional restaurant chains. Beyond Meat differentiates by extending its pea-protein platform into Mexican-format applications, navigating formulation challenges around texture and oil stability.
Vegetarian taquitos are rolled, filled corn tortillas containing plant-based proteins and vegetables, typically flash-fried or baked before freezing to achieve a crisp exterior and uniform internal moisture content; they serve as ready-to-heat appetizers or meal components for retail and foodservice buyers. Frozen product types dominate current shelf space and margin pools, though fresh-format offerings are registering the fastest velocity growth in premium grocery channels. Foodservice distribution channels occupy the highest per-unit value tier, while online retailers are reshaping repurchase patterns through subscription bundling.
The FDA governs ingredient disclosure and allergen labeling for prepared vegetarian foods, while USDA oversight applies to taquitos containing plant-based proteins marketed with meat-comparative claims. State-level cottage-food laws and California's Proposition 65 chemical warning requirements add compliance layers that influence packaging design and distribution geography decisions. Stakeholders must monitor how dual federal-state regulatory overlap affects cross-border product standardization and freezer-slot negotiation power with consolidated retail buyers.
Market Dynamics
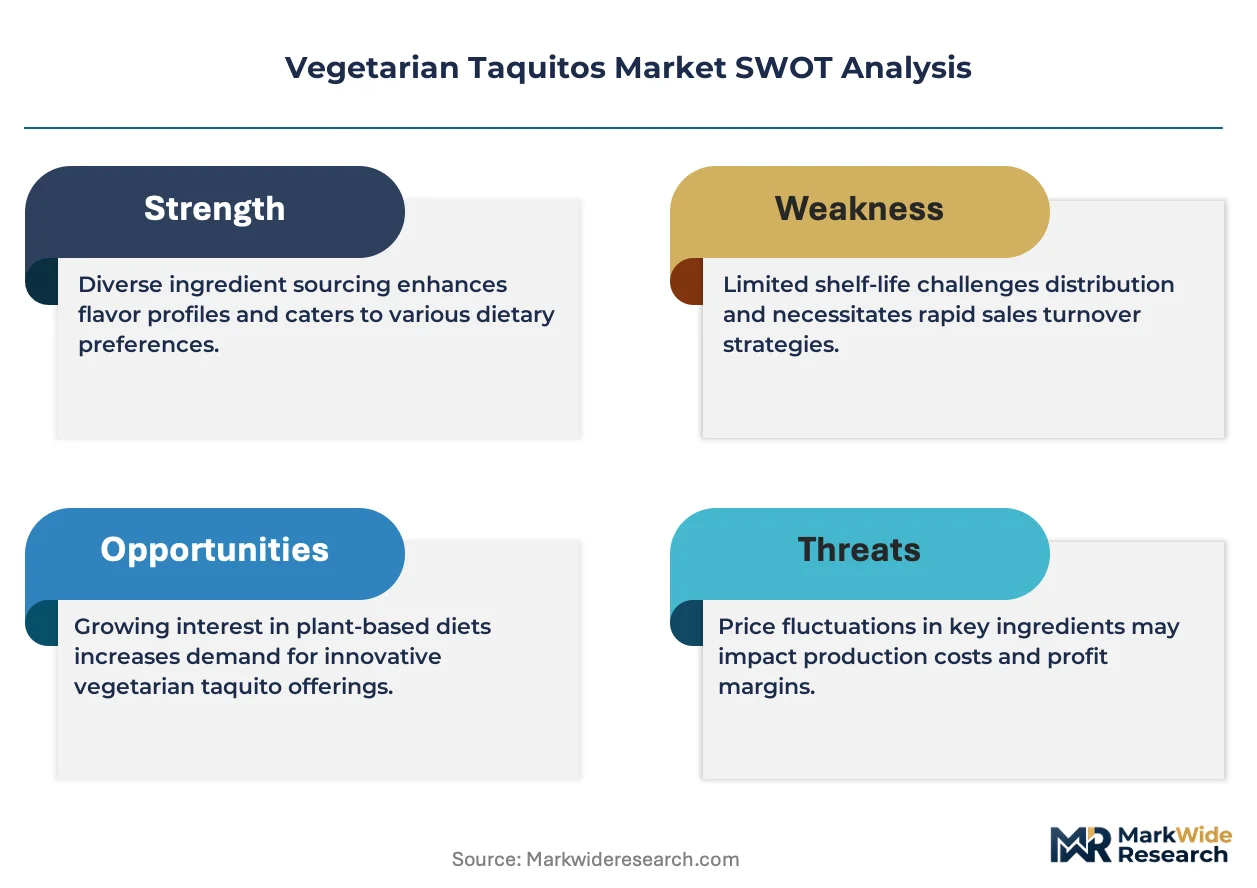
Frozen-distribution network consolidation is fragmenting as direct-to-consumer channels and fresh-format retail slots erode traditional freezer-aisle gatekeeper power, forcing reformulation investments around clean-label compliance and oil-stability engineering.
Growth Catalysts
- Clean-label mandates:FDA's updated Nutrition Facts labeling requirements for prepared foods are accelerating ingredient deck simplification across frozen appetizer portfolios.
- Foodservice program expansion:College and university dining contracts are incorporating plant-based frozen appetizers into procurement specifications.
- Pea-protein platform extension:Textured vegetable protein processing advances are resolving historical moisture-retention failures in rolled tortilla applications.
Market Restraints
- Input cost volatility:Corn tortilla and high-oleic sunflower oil prices fluctuate with commodity crop yields and biofuel diversion pressures.
- Supply concentration risk:Flash-freezing capacity clusters in the upper Midwest, creating geographic vulnerability to cold-chain disruption.
- Regulatory friction:California's Proposition 65 chemical warning requirements add packaging compliance costs that deter small-batch entrants.
Strategic Opportunities
- Subscription channel penetration:Online retailers are bundling frozen appetizers into recurring delivery models that reshape repurchase economics.
- Fresh-format velocity:Premium grocery channels are allocating refrigerated case space to short-shelf-life vegetarian taquito variants.
- Dual federal-state arbitrage:Cottage-food law variations across states create regulatory geography for pilot-scale production testing.
Industry Challenges
- Texture engineering talent scarcity:Food science PhDs with extrusion and emulsion expertise command premium compensation in competitive protein markets.
- Freezer-slot negotiation complexity:Consolidated retail buyers demand slotting allowances that strain working capital for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetarian Taquitos Market |
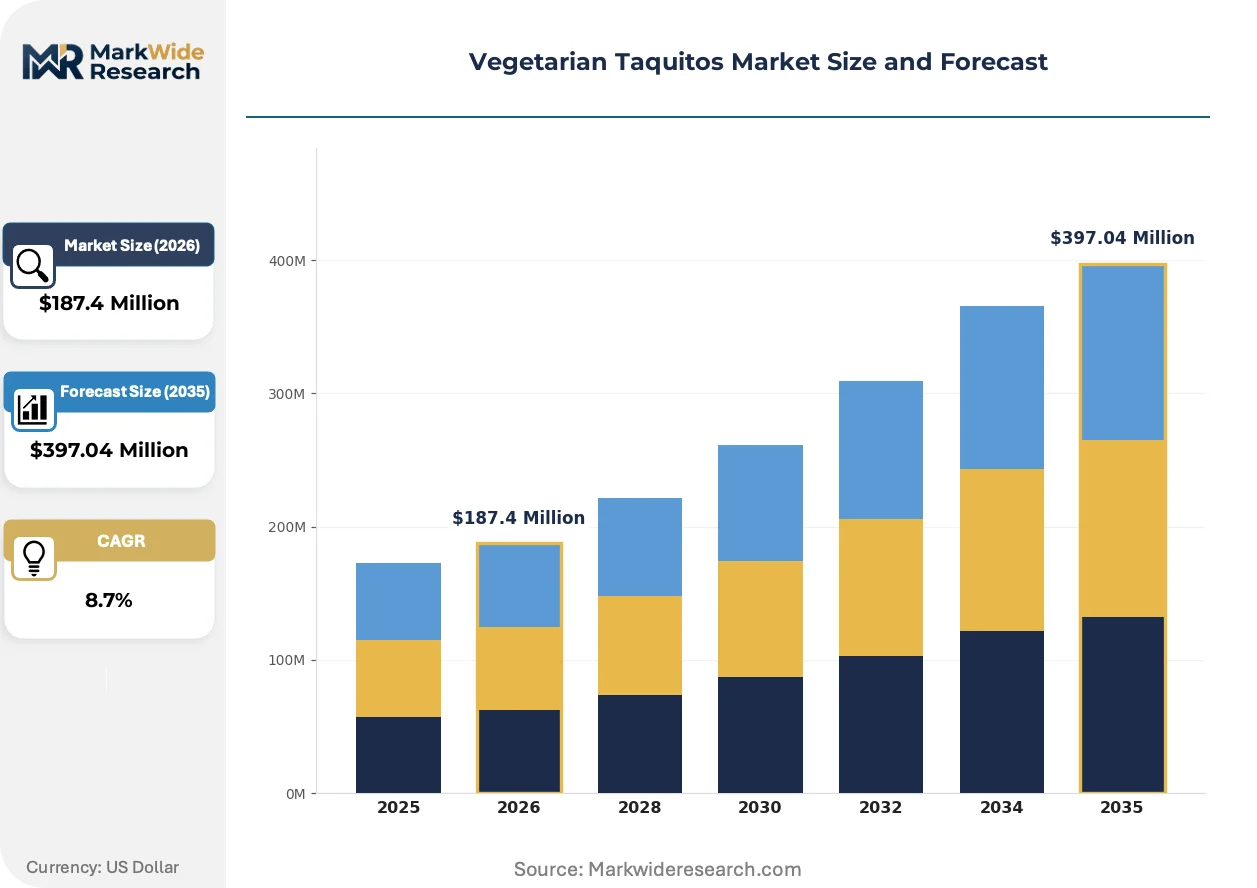
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Shelf-Stable, Ready-to-Eat Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Foodservice Ingredient Type: Vegetables, Beans, Grains, Spices Packaging Type: Plastic Wrap, Cardboard Box, Vacuum Sealed, Bulk Packaging |
| Companies Covered | MorningStar Farms, Gardein, Boca Foods, Daiya Foods, Planet Based Foods, Starlite Cuisine, Tacotarian, Beyond Meat, Tofurky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetarian Taquitos Market Evolving Landscape
Formulation science and channel architecture are converging to compress product development cycles while fragmenting how vegetarian taquitos reach end consumers.
High-moisture extrusion technology is modularizing plant-protein texturization for rolled tortilla applications. Regional restaurant chains are piloting this equipment for in-house vegetarian taquito production. The approach collapses traditional co-manufacturer dependencies and accelerates menu localization.
USDA oversight of meat-comparative claims is tightening substantiation requirements for plant-based protein marketing. Frozen appetizer brands must now maintain dual compliance frameworks alongside FDA ingredient disclosure rules. Foodservice distributors are demanding third-party certification documentation before adding SKUs to broadline catalogs.
College procurement offices are consolidating vegetarian appetizer sourcing through cooperative purchasing alliances. Regional foodservice management companies are displacing fragmented independent distributor relationships. This concentration is most visible in the Southwest, where university system contracts now specify minimum plant-based menu percentages.
Vegetarian Taquitos Market Segmentation
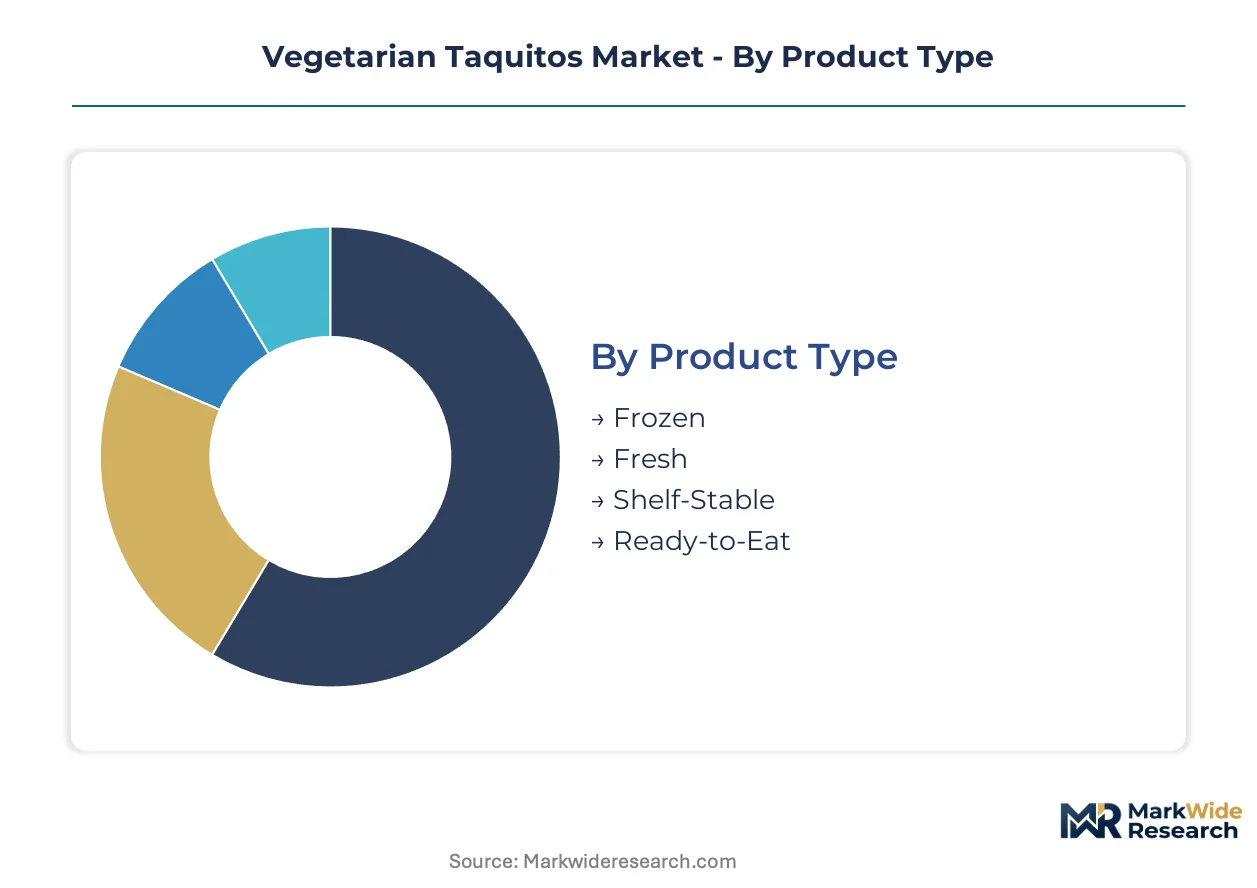
Segmentation in the vegetarian taquitos market reveals how formulation choices, channel access, and packaging economics fragment buyer priorities across retail and foodservice environments. Understanding these divides exposes where margin pools concentrate and where reformulation investments yield shelf-space returns.
Product Type:
Freezer-aisle placement commands the highest slotting allowances but delivers predictable velocity for mass-market penetration.
- Frozen:Flash-fried or baked before freezing to lock moisture and achieve crisp reheating; dominates current shelf allocation in US mass retail as buyers prioritize extended shelf life and bulk purchase economics.
- Fresh:Short-shelf-life variants with refrigerated distribution; gaining velocity fastest in premium US grocery channels where clean-label positioning justifies price premiums and subscription bundling.
- Shelf-Stable:Retort-pouched or aseptically packaged for ambient storage; occupies niche emergency-purchase and international export segments with limited domestic retail presence.
- Ready-to-Eat:Fully cooked, single-serve formats targeting grab-and-go convenience; expanding in US convenience store and college campus micro-market channels.
Volume sits with Frozen; growth tilts toward Fresh.
Distribution Channel:
Channel selection determines compliance burden, margin structure, and the scale of working capital tied to inventory holding.
- Supermarkets:Consolidated retail buyers negotiate multi-SKU planograms; freezer-slot competition intensifies as meat-alternative space expands in US chains.
- Online Retailers:Subscription bundling and direct-to-consumer logistics reshape repurchase patterns; temperature-controlled last-mile delivery remains the primary cost driver.
- Convenience Stores:Limited freezer capacity favors high-turnover, single-serve SKUs; ready-to-eat formats gain traction here.
- Foodservice:University dining contracts and regional restaurant chains specify plant-based appetizers; per-unit value exceeds retail but demands third-party certification documentation.
Margin concentrates in Foodservice; velocity expansion is climbing the fastest in Online Retailers.
Ingredient Type:
Formulation decisions cascade through labeling complexity, allergen management, and protein-content marketing claims.
- Vegetables:Peppers, onions, and corn dominate filling compositions; texture engineering focuses on moisture retention during flash-freezing.
- Beans:Black beans and pinto beans provide protein density and cost stability; FDA allergen labeling requires explicit disclosure for legume-sensitive consumers.
- Grains:Rice and quinoa extend filling volume; gluten-free positioning demands certified corn tortilla sourcing.
- Spices:Cumin, chili powder, and smoked paprika differentiate regional flavor profiles; California Proposition 65 compliance adds testing costs for certain spice sourcing.
Cost efficiency clusters with Beans; flavor differentiation is expanding most quickly through Spices.
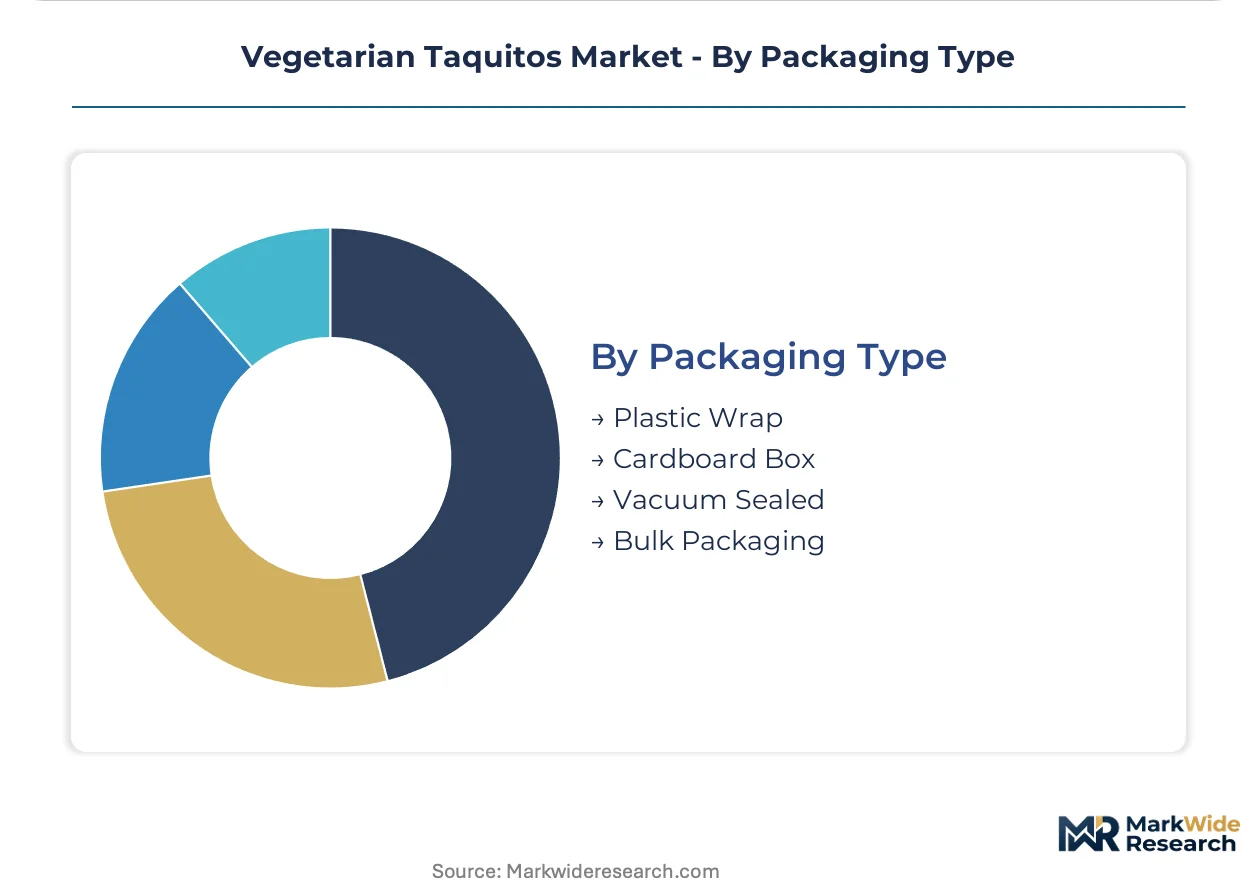
Packaging Type:
Packaging selection balances shelf-life extension, sustainability signaling, and logistics economics across frozen and fresh supply chains.
- Plastic Wrap:Low-cost barrier protection for frozen multi-packs; recycling code compliance varies by US state extended producer responsibility laws.
- Cardboard Box:Printable surface area supports brand storytelling and cooking instructions; susceptible to moisture damage in failed cold-chain scenarios.
- Vacuum Sealed:Oxygen exclusion extends fresh-format shelf life; premium positioning in refrigerated cases justifies higher unit economics.
- Bulk Packaging:Foodservice-focused cases reduce per-unit material cost; institutional buyers prioritize portion consistency over individual presentation.
Standardization favors Plastic Wrap; sustainability-driven switching is gaining share fastest in Vacuum Sealed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vegetarian taquitos concentrates most visibly in the United States, where retail freezer space allocation for meat alternatives continues expanding and foodservice procurement specifications increasingly mandate plant-based menu percentages.
United States
College and university dining contracts drive institutional procurement volumes, with cooperative purchasing alliances consolidating sourcing decisions across state university systems. The FDA's updated Nutrition Facts labeling requirements for prepared foods push manufacturers toward cleaner ingredient decks. Flash-freezing capacity clusters in the upper Midwest, creating geographic concentration of production infrastructure around Chicago and Minneapolis logistics hubs.
Canada
Health Canada oversees allergen labeling for plant-based frozen appetizers, maintaining alignment with FDA disclosure standards while adding bilingual packaging mandates. Retail consolidation in Ontario and Quebec favors established freezer-aisle brands with national distribution networks. Toronto and Vancouver serve as the primary entry points for US-manufactured products, with cross-border cold-chain logistics determining regional availability patterns.
Mexico
Domestic corn tortilla supply chains provide cost advantages for regional production, though flash-freezing infrastructure remains concentrated near Mexico City and Monterrey. The country's national food safety regulator enforces labeling standards for prepared foods containing plant-based proteins. Jalisco and Nuevo León host emerging co-manufacturing facilities serving both domestic consumption and export markets.
Germany
EFSA guidelines on novel protein sources influence formulation decisions for European market entry, with clean-label positioning commanding premium shelf placement. Berlin and Hamburg anchor distribution networks for frozen plant-based appetizers across Northern Europe. The EU Green Deal's packaging sustainability requirements accelerate transitions away from single-use plastics in multi-pack configurations.
United Kingdom
UK retailers allocate expanding chilled and frozen space to meat-alternative appetizers, with London-based buying offices influencing range decisions across national chains. The Food Standards Agency maintains distinct allergen labeling requirements that complicate pan-European product standardization. Midlands manufacturing clusters handle reformulation and repackaging for products entering the British market.
Vegetarian Taquitos Market Competitive Landscape
Portfolio diversification dominates the current landscape as legacy frozen-food conglomerates and plant-based specialists reposition around shifting channel economics. The vendor base spans three distinct tiers: established meat-alternative brands with freezer-aisle dominance, emerging fresh-format specialists, and private-label suppliers serving institutional foodservice. Two archetypes define competitive positioning: legacy brands leveraging distribution scale and insurgent players capturing velocity in premium refrigerated cases. Capacity expansion in high-moisture extrusion technology and strategic partnerships with regional restaurant chains represent the dominant competitive moves reshaping supply relationships.
Among legacy frozen-food specialists, MorningStar Farms and Gardein exemplify scale-driven archetypes anchored in mass retail distribution infrastructure. Beyond Meat occupies a distinct position as a platform-technology player extending pea-protein formulations into Mexican-format applications. These three companies represent contrasting strategic postures: established freezer-aisle incumbency, foodservice-focused supply relationships, and ingredient-platform expansion into prepared formats.
| Leading Market Players |
|---|
| MorningStar Farms |
| Gardein |
| Boca Foods |
| Daiya Foods |
| Planet Based Foods |
| Starlite Cuisine |
| Tacotarian |
| Beyond Meat |
| Tofurky |
| Others |
Value Network & Pricing Analysis
Fresh-format premium positioning against frozen commodity tiers splits margin capture and logistics investment across divergent cold-chain configurations. This bifurcation concentrates working capital in temperature-controlled distribution for short-shelf-life variants while mass-market frozen SKUs absorb slotting allowance pressure from consolidated retail buyers.
Pricing Analysis
Volume concentrates in frozen multi-packs where per-unit economics favor bulk purchase behavior, while margin pools in fresh-format refrigerated cases commanding subscription bundling premiums. Price differentiation rests on clean-label certification tiers and oil-stability engineering grades that signal formulation quality to foodservice procurement officers. Cost compression in commodity frozen tiers is intensifying because corn tortilla and high-oleic sunflower oil input volatility transfers directly to manufacturer margins. College dining contracts exhibit highest price sensitivity due to cooperative purchasing alliance leverage, whereas premium grocery channels absorb markups for vacuum-sealed fresh variants.
Supply Chain Analysis
Temperature-controlled freight costs dominate last-mile economics for direct-to-consumer channels and subscription bundling models. Production infrastructure clusters in the upper Midwest United States, with emerging co-manufacturing capacity expanding in Jalisco and Nuevo León, Mexico. Raw material dependencies center on corn tortilla supply chains, flash-freezing equipment, and high-oleic sunflower oil sourcing. Single-source vulnerability in upper Midwest flash-freezing capacity creates geographic exposure to cold-chain disruption. Distribution runs through consolidated retail buyers in mass-market channels, regional foodservice management companies for institutional contracts, and online retailer logistics networks for recurring delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around freezer-slot negotiation power and co-manufacturer access, with FDA labeling compliance costs and slotting allowance demands forcing sub-scale brands toward acquisition or exit.
For Market Incumbents: Hedge against fresh-format insurgents by securing refrigerated case space in premium grocery channels before velocity shifts permanently erode frozen-aisle dominance. Invest in high-moisture extrusion capacity in-house to reduce co-manufacturer dependency and accelerate menu localization for regional restaurant chain partnerships. Threat: emerging fresh-format specialists capturing subscription bundling economics. For New Entrants and Emerging Players: California's Proposition 65 chemical warning requirements in the United States open a window for clean-label positioning that justifies price premiums and deflects compliance cost burdens onto legacy reformulation laggards. Target college and university dining contracts in the Southwest where cooperative purchasing alliances specify minimum plant-based menu percentages. Go-to-market: pilot-scale production testing under cottage-food law variations before scaling to interstate distribution. For Investors and Strategic Acquirers: Re-rating potential sits with fresh-format specialists possessing vacuum-sealed packaging capabilities and direct-to-consumer logistics infrastructure given channel velocity migration toward subscription bundling. Long-term viability favors platforms with pea-protein texturization expertise and regional restaurant chain supply relationships. Signal to watch: foodservice distributor demands for third-party certification documentation before SKU addition to broadline catalogs.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | In-house texturization collapses co-manufacturer dependencies and accelerates menu localization for regional chains. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models reshape repurchase economics and capture customer data beyond retail gatekeeper control. |
| Clean-Label Certification Investment | FDA compliance documentation satisfies foodservice distributor requirements for broadline catalog inclusion. |
| Regional Restaurant Chain Partnership | Anchored supply relationships secure volume commitments ahead of freezer-slot competition intensification. |
| Fresh-Format Refrigerated Case Entry | Premium grocery channel allocation captures fastest velocity growth in short-shelf-life variants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with frozen food category buyers, foodservice procurement directors, co-manufacturing facility managers, and plant-based protein formulation scientists. Secondary sources included FDA ingredient disclosure databases, USDA meat-comparative claim filings, state-level cottage-food law registries, and Nielsen retail audit data for frozen appetizer velocity. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates from foodservice distributor transaction records.
Data-stream reconciliation across shipment volumes, retail scan data, and institutional procurement contracts informed the analytical framework throughout the forecast period. Segmentation dimensions modeled include product type, distribution channel, ingredient composition, and packaging format, with cross-cutting analysis of regional regulatory clusters and cold-chain infrastructure maturity. CAGRs were derived from trend extrapolation of historical velocity patterns adjusted for channel shift assumptions and clean-label compliance investment cycles. Forecast inputs incorporated flash-freezing capacity expansion timelines and college dining contract renewal schedules.
The model assumes a particular technology adoption path; alternative pathways for high-moisture extrusion modularization would alter the outlook if regional restaurant chains accelerate in-house production pilots. Forecasts reflect assumptions about FDA labeling rule enforcement consistency and cooperative purchasing alliance consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
White Fungus Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Halal Products Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Dong Quai Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Cultures Market
Specialty Foods
Zhacai Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Fruit Dessert Market