
 Middle East and Africa Hummus Market | 2026-2036
Middle East and Africa Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hummus Market Foresight
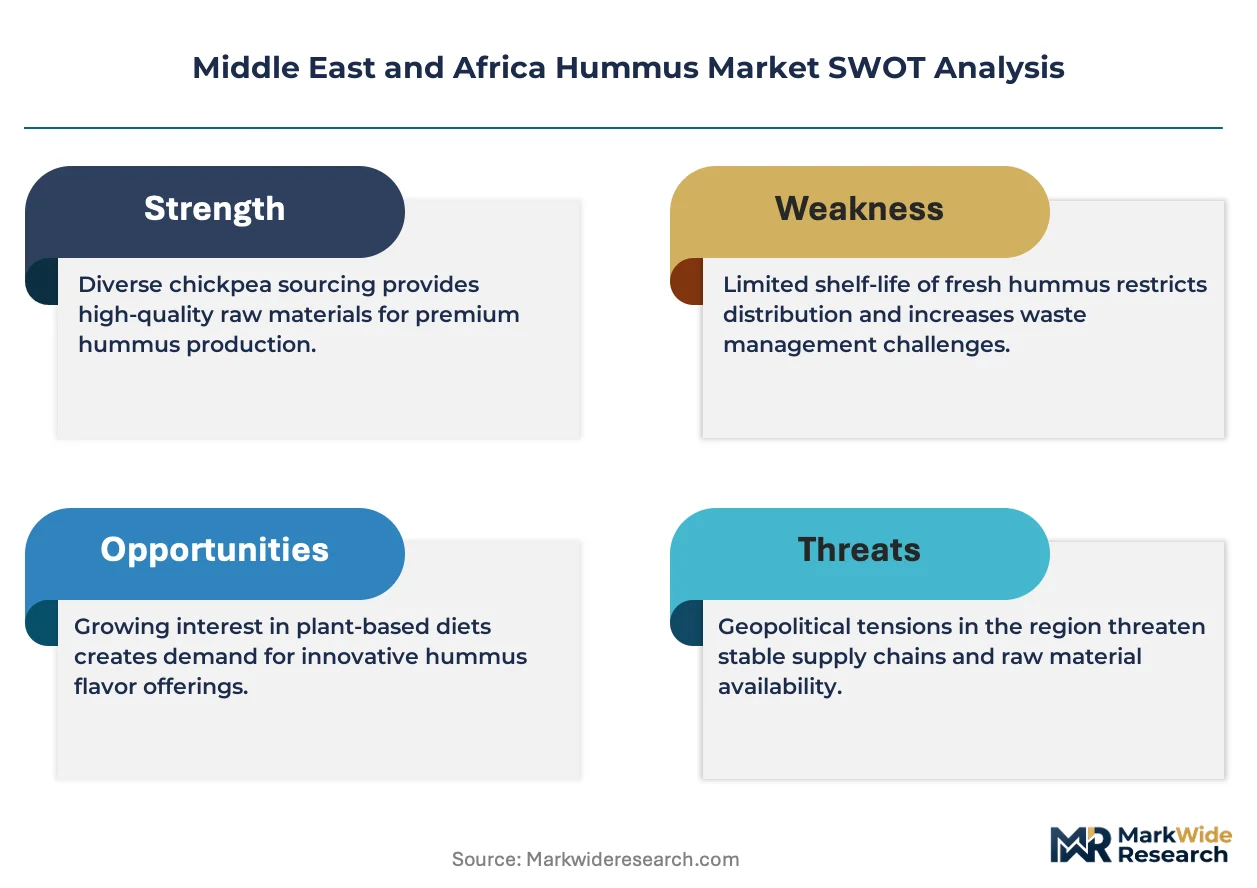
CE marking alignment for food-contact packaging is repositioning export eligibility for regional hummus manufacturers. Strauss Group Ltd. leverages its Israeli production base to supply private-label volumes across North African markets. Cedar's Mediterranean Foods Inc. anchors its competitiveness through specialization in organic tahini sourcing and clean-label formulations. Bakkavor Group Plc sustains chilled distribution networks that compete directly with ambient-stable imports from Levantine suppliers.
Hummus is a Levantine spread prepared from cooked, mashed chickpeas blended with tahini, lemon juice, garlic, and olive oil, typically achieving a shelf life of 21 to 45 days under refrigerated conditions and serving as both a dip and a sandwich component in foodservice and retail channels. Traditional Hummus dominates volume throughput in institutional catering across Saudi Arabia and Egypt, though Flavored Hummus variants command margin premiums in UAE supermarket chilled sections. Organic Hummus occupies a nascent but expanding niche as Gulf retailers introduce dedicated clean-label bays that reward certified suppliers with preferential placement fees.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce divergent additive thresholds and nutritional labeling protocols that fragment compliance costs for pan-regional brands. Israel's Ministry of Health maintains separate kosher certification requirements that condition access to institutional procurement channels. Stakeholders must monitor harmonization pressures between Gulf standardization bodies and North African import regimes as the African Continental Free Trade Area protocols mature.
Market Dynamics
Modern trade penetration across Gulf Cooperation Council secondary cities is reconfiguring distribution economics for packaged hummus, compressing traditional wholesale margins while expanding addressable retail households.
Growth Catalysts
- Airline catering standardization:Emirates and Etihad Airways now specify hummus as a mandatory mezze component in premium cabin service, creating contracted demand volumes that stabilize production planning for approved suppliers.
- SFDA shelf-life disclosure mandates:Saudi Food and Drug Authority tightening of prepared-food labeling requirements is accelerating industry consolidation by raising compliance costs for informal kitchen operators.
- Chickpea processing clusters:Concentrated milling capacity in Jordan's Irbid Governorate is reducing tahini-chickpea blend costs for Levantine exporters serving North African markets.
Market Restraints
- Tahini input volatility:Sesame seed prices fluctuate with Ethiopian and Sudanese harvest cycles, squeezing gross margins for producers lacking backward integration into seed crushing.
- Kosher certification fragmentation:Israel's Ministry of Health maintains separate institutional procurement standards that block pan-regional suppliers from accessing hospital and school catering contracts.
- Ambient import competition:Shelf-stable hummus from Lebanese manufacturers with lower cold-chain costs displaces chilled domestic production in Egyptian retail.
Strategic Opportunities
- Morocco modern trade expansion:Carrefour and Marjane hypermarket chains are opening locations in secondary cities without established hummus suppliers, creating first-mover placement advantages.
- Clean-label bay premiums:UAE retailers including Lulu and Union Coop now charge preferential slotting fees for organic-certified hummus positioned in dedicated natural food sections.
- AfCFTA protocol maturation:African Continental Free Trade Area harmonization of sanitary standards is reducing border delays for Egyptian producers exporting to Kenya and Nigeria.
Industry Challenges
- Cold-chain technician scarcity:Refrigerated logistics operations across the Gulf lack sufficient HVAC-certified maintenance staff to sustain 2-4°C distribution integrity during summer peak loads.
- Dual certification timelines:Manufacturers seeking both halal and kosher approvals face sequential audit queues that extend product launch schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hummus Market |
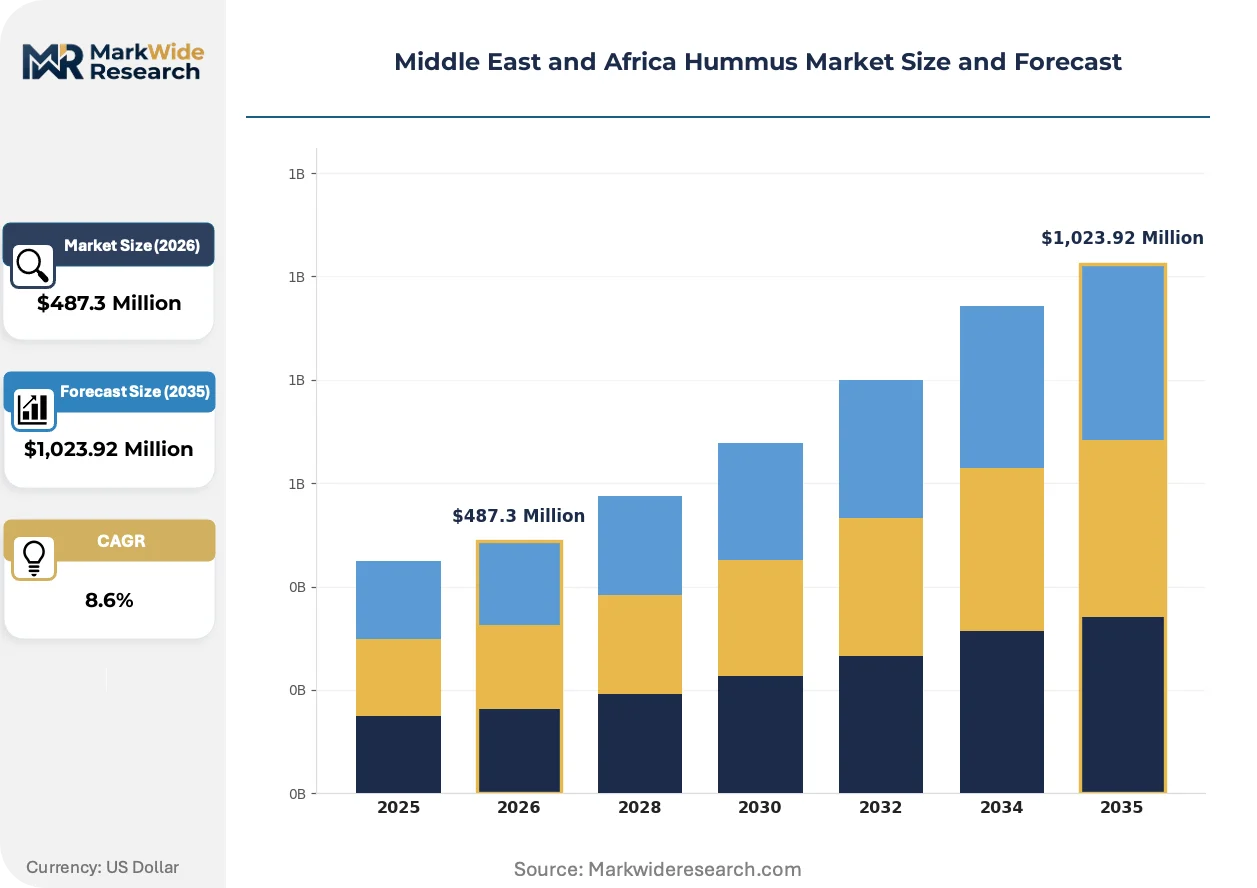
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Hummus, Flavored Hummus, Organic Hummus, Hummus Dip End User: Restaurants, Cafes, Supermarkets, Retail Consumers Packaging Type: Glass Jar, Plastic Tub, Pouch, Can Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Sabra Dipping Company, LLC, Strauss Group Ltd., Cedar's Mediterranean Foods Inc., Bakkavor Group Plc, Haliburton International Foods Inc., Hope Foods, LLC, Lantana Foods, Fontaine Santé, Roots Hummus, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hummus Market Shifts & Advancements
High-pressure processing technology is migrating from beverage applications into prepared spreads, enabling hummus producers to extend refrigerated shelf life without thermal degradation of texture or flavor compounds.
Pulse-based protein extraction is consolidating around wet-fractionation systems that recover starch and fiber streams alongside protein isolates. UAE food-tech ventures including those supplying hotel groups are adopting these systems to produce functional hummus bases with standardized viscosity. The technology is consolidating supplier power toward capital-intensive processors capable of multi-stream output.
Emirates Authority for Standardization and Metrology is enforcing additive threshold limits that diverge from Saudi SFDA standards, forcing manufacturers to maintain parallel formulation inventories. This regulatory fragmentation raises working capital requirements for pan-regional brands. Producers are responding by establishing country-specific production lines rather than centralized blending operations.
Foodservice procurement teams at Gulf hotel operators are consolidating supplier relationships around integrated mezze platter vendors rather than discrete hummus-only contracts. This bundling compresses standalone hummus margins while rewarding kitchen-ready portion control and customized packaging formats. The shift is most visible in Dubai's hospitality procurement, where Jumeirah Group and Emaar Hospitality have implemented unified sourcing platforms.
Middle East and Africa Hummus Market Segmentation
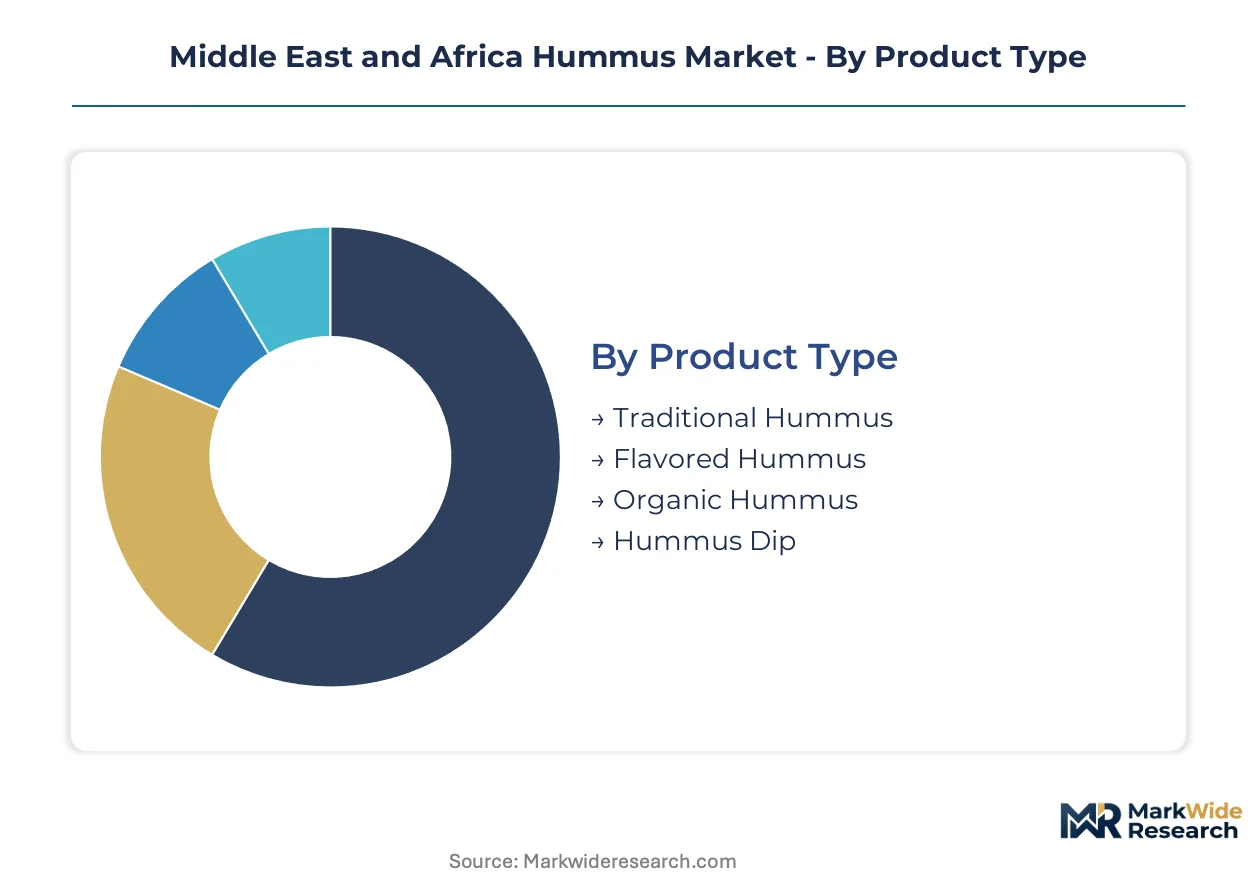
Product differentiation across the Middle East and Africa hummus market follows distinct demand curves shaped by cold-chain maturity, certification requirements, and channel-specific procurement standards. Each segmentation axis reveals divergent margin structures and compliance burdens that condition supplier positioning.
Product Type:
Formulation technology and shelf-life engineering define competitive positioning across product tiers, with thermal processing choices directly constraining channel access.
- Traditional Hummus:Classic tahini-chickpea blend without additive stabilizers, achieving 21-30 day refrigerated shelf life. Institutional catering across Saudi Arabia and Egypt concentrates procurement here, with SFDA labeling mandates compressing informal supplier margins.
- Flavored Hummus:Roasted red pepper, garlic-herb, and spicy harissa variants command placement premiums in UAE supermarket chilled sections. Emirates and Etihad Airways specify these for premium cabin mezze service, creating contracted demand pools that stabilize production planning.
- Organic Hummus:Certified clean-label formulations occupy dedicated bay placements at Lulu and Union Coop, attracting preferential slotting fees.
- Hummus Dip:Thickened viscosity formulations optimized for extended holding in foodservice warmers.
Traditional Hummus leads on scale; Flavored Hummus leads on momentum.
End User:
Procurement sophistication varies sharply across buyer categories, with formal tender processes replacing spot purchasing as contract values rise.
- Restaurants:Full-service establishments across Dubai and Riyadh drive volume through mezze platter bundling, with Jumeirah Group and Emaar Hospitality consolidating around integrated suppliers rather than discrete hummus-only contracts.
- Supermarkets:Modern trade penetration into GCC secondary cities is reconfiguring distribution economics, compressing traditional wholesale margins while expanding addressable retail households.
- Cafes:Grab-and-go breakfast channels in Cairo and Casablanca favor single-serve portion formats.
- Retail Consumers:Household purchasing concentrates in UAE and Saudi Arabia, with Carrefour and Marjane hypermarket expansion into Moroccan secondary cities creating first-mover placement opportunities.
Supermarkets dominate volume throughput; Restaurants are climbing the fastest on contract formalization.
Packaging Type:
Barrier properties and cold-chain compatibility determine geographic reach, with material choices constraining export eligibility under divergent Gulf standardization regimes.
- Plastic Tub:Polypropylene containers with modified atmosphere sealing dominate UAE retail, offering shatter resistance and lightweight logistics. Emirates Authority for Standardization and Metrology additive thresholds favor this format over glass for institutional channels.
- Glass Jar:Premium positioning in Lebanese exports to North African markets, though higher freight costs disadvantage chilled distribution.
- Pouch:Flexible formats gaining traction in airline catering for weight reduction.
- Can:Ambient-stable retort processing enables Lebanese manufacturers to displace chilled domestic production in Egyptian retail.
Plastic Tub leads on scale; Pouch leads on momentum.
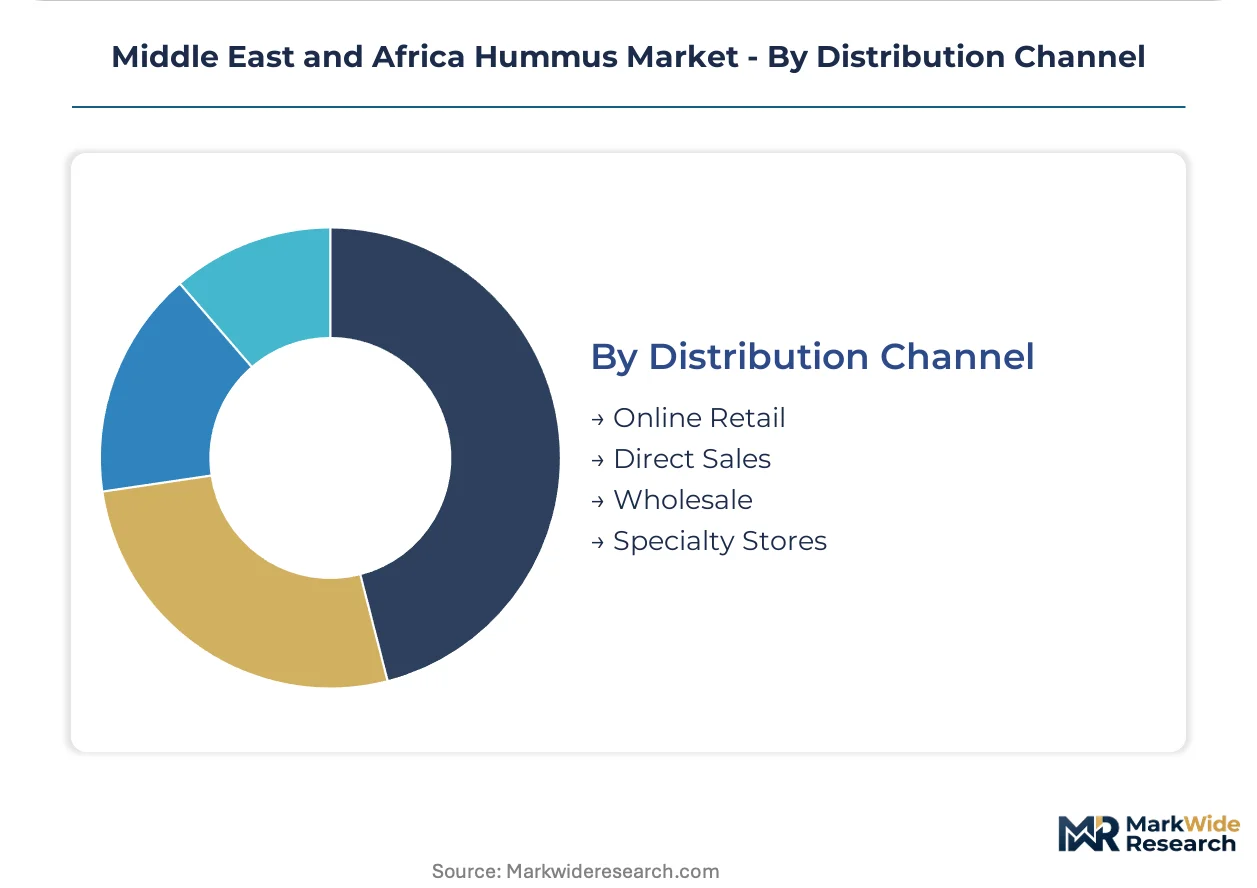
Distribution Channel:
Channel selection conditions working capital intensity and certification sequencing, with direct sales requiring dual halal-kosher approvals that extend launch timelines.
- Wholesale:Traditional cash-and-carry networks across Cairo and Amman remain volume-heavy but margin-thin, with cold-chain technician scarcity across the Gulf threatening 2-4°C distribution integrity during summer peaks.
- Online Retail:UAE food-tech ventures supplying hotel groups are consolidating procurement through unified sourcing platforms, bypassing traditional distributor markups.
- Direct Sales:Manufacturer-to-foodservice relationships reward kitchen-ready portion control and customized packaging formats.
- Specialty Stores:Organic-certified placement in dedicated natural food sections attracts clean-label premiums.
Wholesale leads on scale; Online Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hummus originated in the Levant, with modern commercial production scaling first through Israeli and Lebanese kitchen operations before spreading across Gulf markets via diaspora communities and airline catering contracts.
United Arab Emirates
Emirates and Etihad Airways now mandate hummus as a required mezze component in premium cabin service, creating contracted demand pools that stabilize production planning for approved suppliers. Emirates Authority for Standardization and Metrology enforces additive thresholds that diverge from Saudi standards, forcing parallel formulation inventories. Dubai's Jumeirah Group and Emaar Hospitality have implemented unified sourcing platforms that consolidate procurement around integrated mezze platter vendors.
Saudi Arabia
Retail consumers across secondary cities are expanding packaged hummus purchases as modern trade formats penetrate beyond Riyadh and Jeddah. Saudi Food and Drug Authority labeling requirements for prepared foods are tightening shelf-life disclosure standards, accelerating consolidation by raising compliance costs for informal kitchen operators. The Eastern Province's industrial food parks are attracting chilled distribution investments to serve the growing supermarket channel.
Israel
Strauss Group leverages its domestic production base to supply private-label volumes across North African markets, capitalizing on kosher certification requirements that condition access to institutional procurement channels. The Ministry of Health maintains separate standards that block pan-regional suppliers from hospital and school catering contracts. Tel Aviv's food-tech corridor is piloting high-pressure processing systems to extend refrigerated shelf life without thermal degradation.
Egypt
Ambient-stable hummus imports from Lebanese manufacturers with lower cold-chain costs are displacing chilled domestic production in Cairo retail channels. African Continental Free Trade Area harmonization of sanitary standards is reducing border delays for Egyptian producers exporting to Kenya and Nigeria. The Irbid Governorate milling cluster across the border in Jordan is reducing tahini-chickpea blend costs for Levantine exporters serving Egyptian distributors.
Morocco
Carrefour and Marjane hypermarket chains are opening locations in secondary cities without established hummus suppliers, creating first-mover placement advantages for entrants. Clean-label bay premiums at these retailers reward certified suppliers with preferential slotting fees. Casablanca's grab-and-go breakfast channels are driving single-serve portion format adoption among urban professionals.
Middle East and Africa Hummus Market Competitive Landscape
The competitive structure tilts toward vertically integrated Levantine producers with captive tahini supply and Gulf-based chilled distribution specialists. Market concentration remains moderate, with pan-regional brands competing against national kitchen operators and informal producers. Two strategic archetypes dominate: integrated foodservice suppliers bundling mezze components, and clean-label specialists commanding organic certification premiums. Capacity expansion and backward integration into sesame seed crushing represent the dominant competitive moves as producers seek margin protection against input volatility.
Within the integrated foodservice tier, Strauss Group Ltd. and Bakkavor Group Plc occupy positions that exemplify divergent geographic strategies—Israeli production leveraging North African export access versus British chilled distribution networks competing with ambient imports. Cedar's Mediterranean Foods Inc. anchors the clean-label specialist archetype through organic tahini sourcing discipline. Sabra Dipping Company, LLC represents the scale-driven multinational approach, though its operational footprint sits outside the immediate regional production cluster.
| Leading Market Players |
|---|
| Sabra Dipping Company, LLC |
| Strauss Group Ltd. |
| Cedar's Mediterranean Foods Inc. |
| Bakkavor Group Plc |
| Haliburton International Foods Inc. |
| Hope Foods, LLC |
| Lantana Foods |
| Fontaine Santé |
| Roots Hummus |
| Others |
Supply & Pricing Matrix
Sesame seed costs originating from Ethiopian and Sudanese harvest cycles flow through tahini crushing margins before stratifying into three distinct pricing tiers at the finished hummus level. Cold-chain logistics intensity then separates premium chilled products from ambient-stable alternatives, with Gulf distribution economics compressing margins on the former while Levantine exporters capture value on the latter.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the Middle East and Africa hummus market, with organic certification and airline catering contracts commanding the highest tier. Price differentiation hinges on halal-kosher dual certification status and backward integration into sesame seed crushing. Cost compression in the standard tier is intensifying because Lebanese ambient-stable imports undercut chilled domestic production on logistics. Foodservice procurement teams at Gulf hotel operators show the least price sensitivity, while Egyptian retail consumers demonstrate the highest.
Supply Chain Analysis
Tahini supply rests on sesame seed cultivation concentrated in Ethiopia, Sudan, and Turkey, with crushing capacity clustering in Jordan's Irbid Governorate. Raw material dependencies span sesame seeds, chickpea milling output, and high-barrier packaging resins. Single-source vulnerability in Ethiopian seed exports exposes producers to harvest cycle disruption. Distribution runs through chilled logistics networks across the Gulf Cooperation Council, competing with ambient-stable containerized shipments from Lebanese manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa hummus market represents a late-cycle quality story, with procurement teams at Emirates and Etihad Airways mandating premium mezze specifications that reward certified suppliers with contracted volume stability.
For Market Incumbents: Extend shelf-life engineering capabilities through high-pressure processing adoption, defending against ambient import competition from Lebanese manufacturers. Secure backward integration into Sudanese and Ethiopian sesame seed sourcing to neutralize tahini input volatility. Prioritize dual halal-kosher certification investment to maintain access to Gulf institutional procurement channels.
For New Entrants and Emerging Players: Airline catering procurement teams offer the most penetrable entry vector, with Emirates and Etihad Airways standardizing hummus as mandatory mezze components. Target Moroccan secondary cities where Carrefour and Marjane hypermarket expansion lacks established supplier relationships. Pursue clean-label certification to capture preferential slotting fees in UAE retailer dedicated natural food bays.
For Investors and Strategic Acquirers: Consolidation pressure builds where cold-chain technician scarcity across the Gulf threatens distribution integrity and raises operational barriers. Long-term viability favors vertically integrated producers with captive tahini supply and multi-country formulation capabilities. Watch African Continental Free Trade Area sanitary standard harmonization as the signal indicating Egyptian export competitiveness inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sesame Seed Crushing | Captive tahini supply neutralizes Ethiopian harvest price volatility for Levantine producers. |
| High-Pressure Processing Technology Adoption | Emirates Authority for Standardization and Metrology additive thresholds favor extended shelf-life formulations. |
| Dual Halal-Kosher Certification Investment | Israel's Ministry of Health standards condition access to hospital and school catering contracts. |
| Morocco Modern Trade Channel Expansion | Carrefour and Marjane secondary city openings create first-mover placement advantages. |
| Airline Catering Contract Consolidation | Emirates and Etihad Airways mandated mezze specifications stabilize production planning volumes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with category buyers at Lulu and Union Coop, procurement directors at Jumeirah Group and Emaar Hospitality, plant managers at Jordan's Irbid milling cluster, and regulatory affairs leads navigating SFDA and Emirates Authority for Standardization and Metrology protocols. Secondary validation drew from Saudi Food and Drug Authority labeling directives, airline catering procurement specifications, customs records of Lebanese ambient-stable exports, and trade data on Ethiopian sesame seed shipments. Bottom-up volume builds across product tiers and end-use channels were triangulated against top-down market sizing.
Segment-weighting approaches modeled traditional, flavored, organic, and dip formulations alongside restaurants, supermarkets, cafes, and retail consumers, with packaging format and distribution channel dimensions layered throughout the projection horizon. CAGRs were derived from trend extrapolation anchored in airline catering contract formalization and modern trade penetration trajectories. Forecast inputs incorporated high-pressure processing adoption curves and African Continental Free Trade Area protocol maturation effects on Egyptian export logistics.
Revisions become necessary when Ethiopian sesame harvest failures, Gulf cold-chain infrastructure bottlenecks, or regulatory divergence between Saudi and Emirates standardization bodies materialize. Forecasts reflect assumptions about continued airline catering specification tightening and modern trade format expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Sweet Spreads Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Halal Products Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Sofrito Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Hot Pot Market
Specialty Foods
Coconut Butter Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Natural Honey Market