
 Low Calorie Veggie Dip Market | 2026-2036
Low Calorie Veggie Dip Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Veggie Dip Market Analytics
Clean-label formulation technology is fragmenting traditional emulsifier and stabilizer supply chains as manufacturers replace modified starches with chickpea aquafaba, cashew bases, and cultured almond proteins. Bolthouse Farms leverages its captive carrot and vegetable processing infrastructure to control raw material quality from field to tub. Chobani LLC anchors its position through extensive fermentation expertise applied to non-dairy bases. Sabra Dipping Co. LLC competes by dominating hummus-specific distribution networks and refrigerated logistics partnerships.
Low calorie veggie dip comprises reduced-fat or plant-based emulsified sauces formulated with vegetable purees, legume bases, or cultured alternatives, typically containing fewer than 40 calories per 30-gram serving and designed for fresh vegetable accompaniment in retail and foodservice channels. Hummus leads volume through established production scale and shelf-stable distribution economics, while creamy dip variants built on cashew or oat bases represent the fastest-expanding margin pool as premium positioning commands higher unit economics. Tubs dominate packaging due to established cold-chain infrastructure, though pouches are gaining traction in convenience-oriented channels and single-serve foodservice applications.
The U.S. FDA governs nutrition labeling and health claims for reduced-calorie positioning, while the USDA oversees organic certification pathways that many brands pursue for premium differentiation. The EU's EFSA and REACH frameworks shape ingredient approval and additive restrictions for any European market entry, directly constraining emulsifier selection and clean-label formulation strategies. Stakeholders must monitor evolving front-of-package labeling mandates and added-sugar disclosure thresholds across multiple jurisdictions to anticipate reformulation requirements and maintain competitive shelf positioning.
Market Dynamics
Clean-label reformulation mandates from the U.S. FDA are forcing manufacturers to rebuild emulsifier supply chains around chickpea aquafaba, cashew bases, and cultured almond proteins, fragmenting traditional modified starch dependencies.
Growth Catalysts
- Gen Z Retail Demand:Health-conscious younger consumers in the refrigerated perimeter are accelerating purchases of plant-based dips, compressing conventional center-store shelf space allocation.
- USDA Organic Certification:Premium differentiation pathways through organic labeling are expanding margin pools for compliant manufacturers serving club channel expansion.
- REACH Framework Compliance:EU additive restrictions are accelerating clean-label ingredient innovation, creating export-ready formulation capabilities for domestic producers.
Market Restraints
- Raw Material Volatility:Cashew and almond base costs fluctuate with California water allocation policies and South Asian harvest cycles, compressing gross margins unpredictably.
- Cold-Chain Concentration:Refrigerated logistics partnerships concentrate in three national distributors, creating single-point-of-failure risk for tub-format distribution.
- Emulsifier Performance Gap:Aquafaba and plant-protein stabilizers currently deliver shorter shelf stability than modified starches, limiting conventional retail placement economics.
Strategic Opportunities
- Pouch Format Expansion:Single-serve flexible packaging for convenience channels remains underdeveloped relative to tub infrastructure, offering first-mover yield.
- Foodservice Penetration:Pre-portioned dip formats for corporate catering and airline channels represent whitespace beyond established retail grocery concentration.
- Dual Carbon Alignment:China's SAMR sustainability disclosure requirements and domestic ESG mandates are converging to reward low-carbon processing investments with preferential listing status.
Industry Challenges
- Fermentation Talent Scarcity:Cultured protein expertise sits concentrated in dairy and beverage sectors, requiring cross-industry recruitment or extended training timelines for non-dairy base development.
- Reformulation Capital Intensity:Clean-label line conversions demand simultaneous equipment replacement for allergen segregation, pasteurization retooling, and label compliance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Veggie Dip Market |
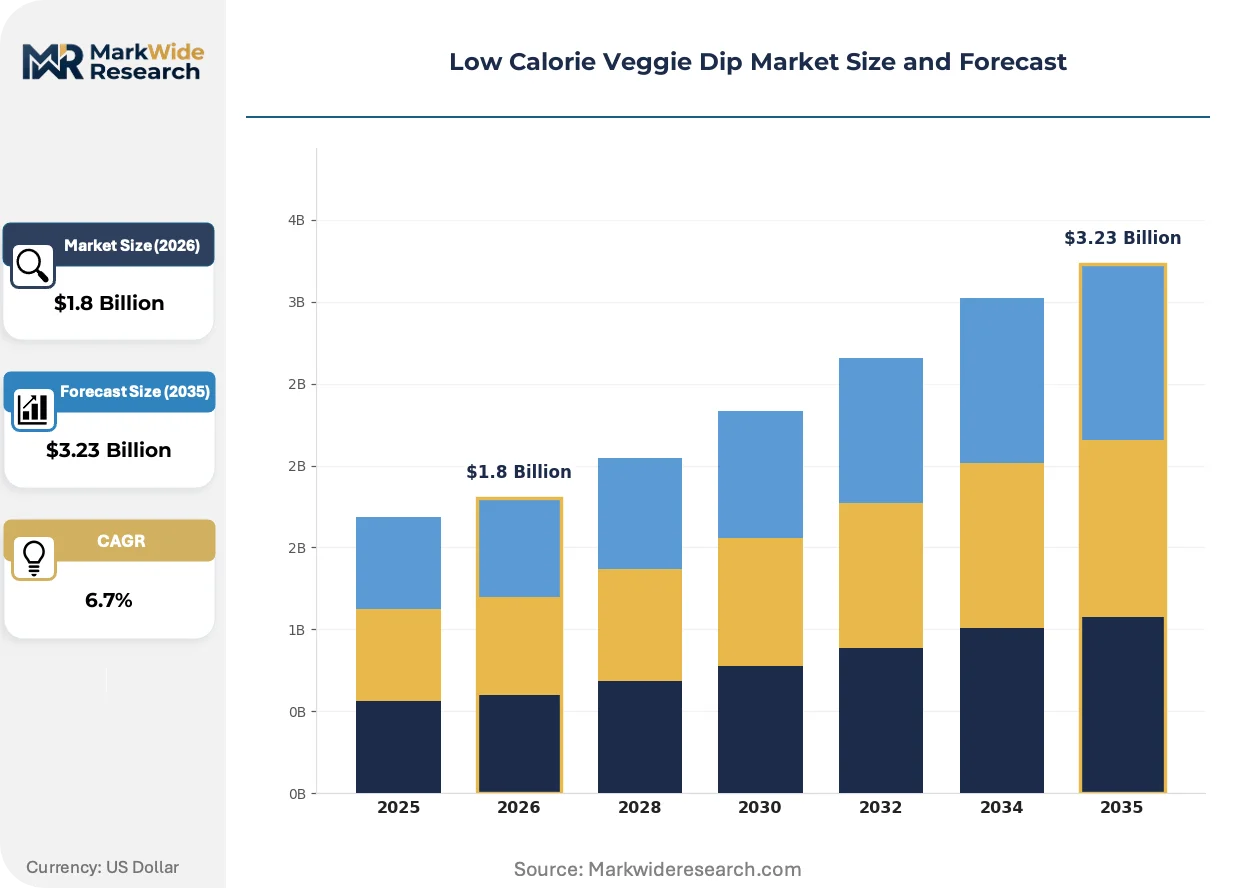
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hummus, Guacamole, Salsa, Creamy Dip Flavor: Garlic, Spicy, Herb, Onion Packaging Type: Bottles, Tubs, Pouches, Jars Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores |
| Companies Covered | Bolthouse Farms, Chobani LLC, Sabra Dipping Co. LLC, Conagra Brands, General Mills Inc., Nestle S.A., Frito-Lay Inc., Kite Hill, Good Foods Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Veggie Dip Market Evolving Landscape
Formulation science and packaging engineering are converging to redefine unit economics across refrigerated plant-based categories, with digital traceability and fermentation biotechnology emerging as the dominant capability differentiators.
Precision fermentation is digitizing protein production for non-dairy dip bases, enabling manufacturers to program specific functional properties into cultured almond and oat proteins. Mid-sized refrigerated brands are piloting these platforms to compress development cycles from eighteen months to under six. The technology is digitizing quality control protocols, replacing batch-based testing with real-time bioprocess monitoring that flags deviation before finished goods production.
REACH and EFSA additive restrictions are eliminating conventional emulsifiers from European-bound formulations, compelling manufacturers to validate chickpea aquafaba and lecithin alternatives through accelerated stability trials. U.S. exporters to the EU are restructuring ingredient sourcing to maintain dual-market production efficiency. The regulatory friction is compressing formulation flexibility, forcing advance commitment to clean-label architectures even for domestic-only product lines.
Club channel buyers are consolidating refrigerated dip assortment decisions around direct-store-delivery partners with dedicated cold-chain accountability, displacing traditional warehouse-distribution relationships. This procurement compression favors vertically integrated producers with captive processing infrastructure over contract-manufactured brands. The shift is most visible in United States fresh perimeter expansion, where Costco and Sam's Club placement now requires temperature-validated logistics guarantees from production facility to display case.
Low Calorie Veggie Dip Market Segmentation
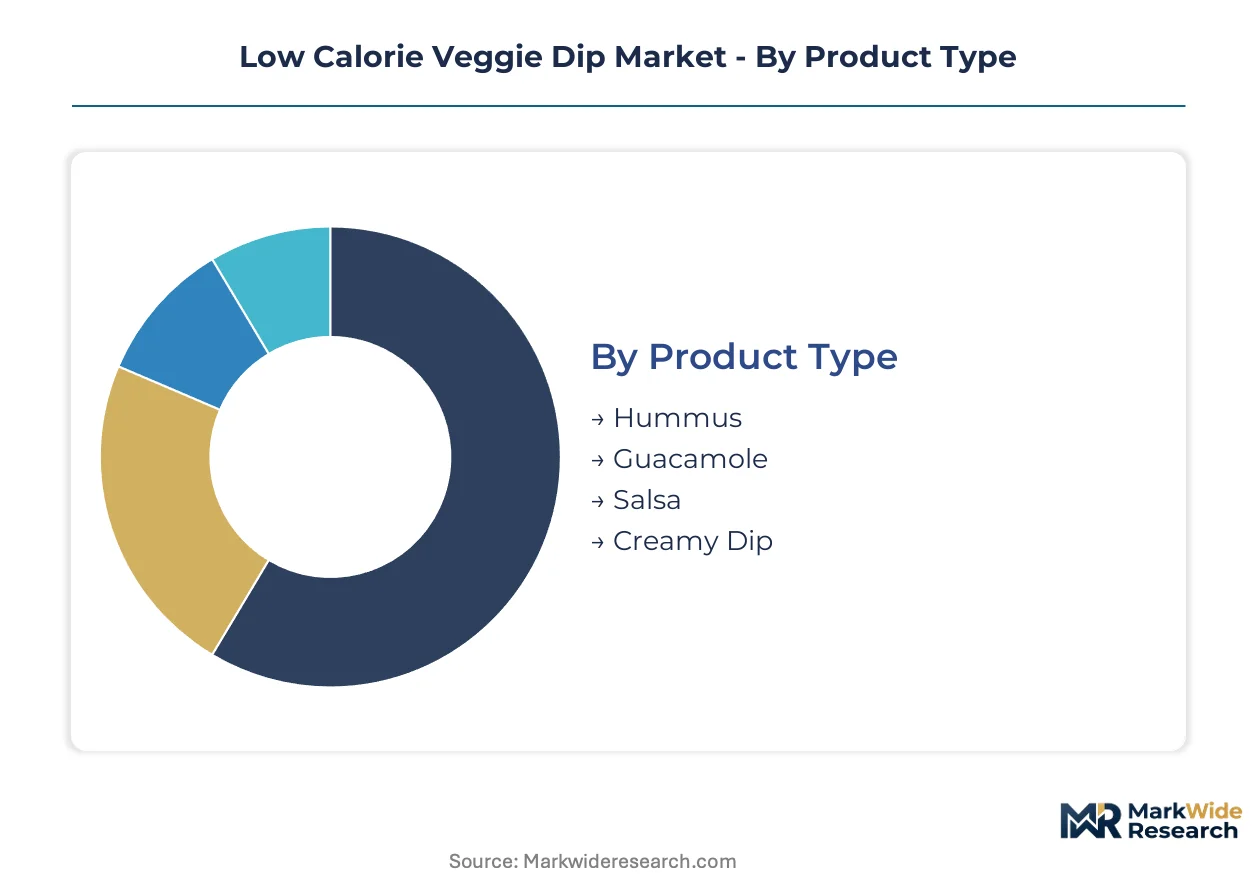
Segmentation in low calorie veggie dip markets reveals divergent velocity patterns across product lifecycles. Refrigerated formats turn inventory faster than shelf-stable alternatives, while plant-based variants compress innovation cycles compared to conventional formulations.
Product Type:
Hummus rotates shelf stock fastest due to established production scale and consumer familiarity, while creamy dip variants command longer development timelines for clean-label reformulation.
- Hummus:Chickpea-based emulsified spreads with tahini and lemon juice formulations dominate refrigerated perimeter placement. Demand concentrates in United States club channels where bulk tub formats drive volume throughput and repeat purchase frequency.
- Creamy Dip:Cashew, oat, and almond protein bases deliver sub-40 calorie positioning through precision fermentation. Expansion concentrates in coastal United States metro areas where premium plant-based positioning commands price elasticity and margin expansion.
- Guacamole:Avocado-based formulations with lime and cilantro profiles serve fresh produce pairing occasions.
- Salsa:Tomato and pepper-based chunky or smooth variants occupy hybrid shelf-stable and refrigerated positioning.
Hummus dominates installed base. Creamy dip is where expansion concentrates.
Flavor:
Flavor preference maps directly to application context and daypart targeting, with savory profiles anchoring meal occasions and bold variants capturing snack-centric consumption.
- Garlic:Roasted and raw garlic formulations provide umami depth in hummus and creamy dip bases. Demand concentrates in Mediterranean and Middle Eastern cuisine-adjacent United States markets where authenticity cues drive brand selection.
- Spicy:Jalapeño, habanero, and chili-infused variants deliver heat-seeker targeting across Gen Z and millennial demographics. Expansion concentrates in Texas, California, and Florida retail clusters where Latin flavor preference shapes assortment decisions.
- Herb:Dill, parsley, and cilantro profiles signal freshness and garden-origin positioning.
- Onion:Caramelized and fresh allium variants provide sweetness or pungency balance in creamy applications.
Garlic maintains broadest household penetration. Spicy is climbing the fastest as younger cohorts prioritize sensory intensity.
Packaging Type:
Packaging economics separate high-velocity retail formats from emerging convenience configurations, with cold-chain infrastructure dictating viable options.
- Tubs:Injection-molded polypropylene containers with tamper-evident lidding dominate refrigerated logistics networks. Demand concentrates in United States supermarket fresh perimeter where 8-16 ounce family sizes drive weekly basket attachment rates.
- Pouches:Flexible film stand-up or flat formats with spout or tear-notch closures enable single-serve and on-the-go positioning. Expansion concentrates in convenience store and airline catering channels where portion control and waste reduction command procurement preference.
- Bottles:PET or glass containers for pourable dressing-style applications in foodservice.
- Jars:Glass packaging for premium shelf-stable salsa and specialty positioning.
Tubs dominate installed base. Pouches represent the fastest-growing trajectory as convenience channels expand refrigerated grab-and-go assortment.
Distribution Channel:
Channel selection determines margin structure and brand control, with direct-store-delivery relationships displacing traditional wholesale in high-growth segments.
- Supermarkets:Fresh perimeter refrigerated cases and produce adjacency placements drive impulse attachment to vegetable purchases. Demand concentrates in Kroger, Albertsons, and Ahold Delhaize banners where local and regional brand slotting fees determine shelf presence.
- Online Retailers:E-commerce platforms enable subscription replenishment and discovery of niche clean-label entrants. Expansion concentrates in Amazon Fresh and Thrive Market ecosystems where search algorithm optimization and review velocity determine visibility.
- Health Food Stores:Whole Foods Market and Sprouts Farmers Market prioritize organic certification and non-GMO verification.
- Convenience Stores:7-Eleven and Circle K formats test refrigerated dip placement in produce-heavy remodels.
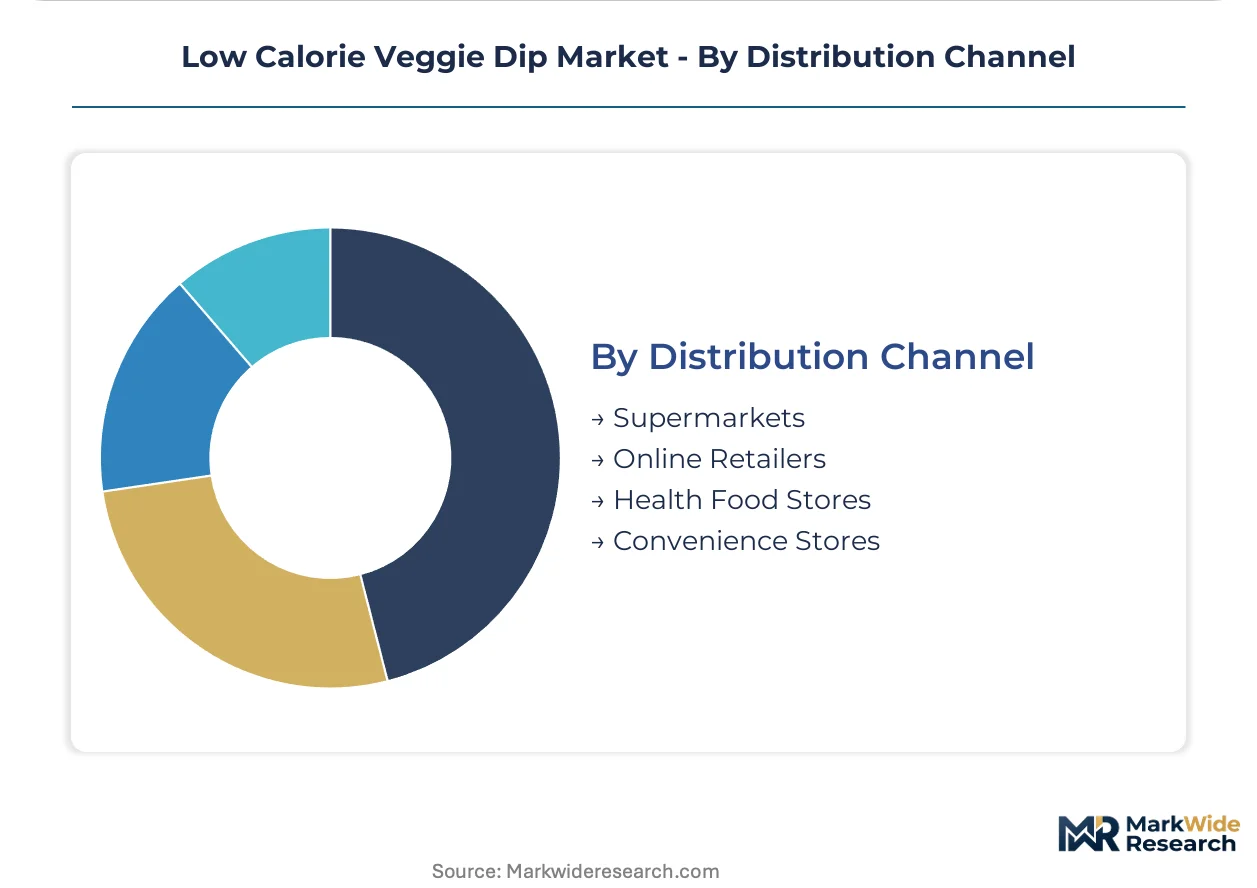
Supermarkets dominate installed base. Online retailers are gaining share fastest as cold-chain last-mile capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious millennials and Gen Z consumers concentrate in urban coastal markets, driving refrigerated plant-based dip velocity through fresh perimeter placements and club channel expansion.
United States
Demand clusters in Texas, California, and Florida retail networks where Latin flavor profiles and spicy variants capture younger demographics. The FDA's updated Nutrition Facts labeling requirements for added sugars are pushing manufacturers toward cleaner formulations with reduced sodium content. Los Angeles and New York metro areas anchor premium plant-based positioning where cashew and oat bases command price elasticity.
Germany
Organic certification pathways through the EU regulatory framework attract clean-label entrants seeking premium differentiation in Berlin and Munich supermarket fresh perimeters. EFSA and REACH additive restrictions are eliminating conventional emulsifiers from formulations, compelling validation of chickpea aquafaba alternatives through accelerated stability trials. The country's central European logistics position enables export-ready production for neighboring markets.
United Kingdom
London and Southeast England concentrate demand for hummus and Mediterranean flavor profiles through established distribution partnerships with major supermarket banners. The country's departure from EU regulatory alignment has created dual compliance requirements for manufacturers serving both domestic and continental European channels. Manchester and Birmingham retail clusters are testing expanded refrigerated dip assortments in convenience-oriented formats.
Canada
Toronto and Vancouver metropolitan areas drive plant-based innovation adoption through health food store networks and premium supermarket positioning. Health Canada oversees nutrition labeling harmonization with FDA frameworks, reducing reformulation friction for cross-border producers. The Prairie Provinces supply pulse crop raw materials that underpin regional hummus manufacturing scale.
Australia
Sydney and Melbourne anchor demand for clean-label refrigerated dips through independent grocers and supermarket fresh perimeter expansion. The Therapeutic Goods Administration and Food Standards Australia New Zealand govern additive approvals that shape emulsifier selection for domestic formulations. Queensland and Western Australia growing regions supply vegetable inputs for captive processing infrastructure.
Low Calorie Veggie Dip Market Competitive Landscape
Channel-controlling players compete with product-specialist players across refrigerated logistics networks and formulation technology capabilities. The market structure fragments between vertically integrated producers with captive agricultural processing and contract-manufactured brands dependent on third-party cold-chain partnerships. Two dominant archetypes emerge: field-to-tub integrators controlling raw material quality from agricultural sourcing through finished goods distribution, and fermentation-anchored innovators applying dairy-derived expertise to non-dairy base development. Competitive moves concentrate on direct-store-delivery relationship consolidation and clean-label line conversion capital deployment.
Within the integrated processing tier, Bolthouse Farms exemplifies field-to-tub vertical control through captive carrot and vegetable infrastructure, while Chobani LLC anchors fermentation expertise applied to non-dairy bases. Sabra Dipping Co. LLC occupies a position defined by hummus-specific distribution network concentration and refrigerated logistics partnerships.
| Leading Market Players |
|---|
| Bolthouse Farms |
| Chobani LLC |
| Sabra Dipping Co. LLC |
| Conagra Brands |
| General Mills Inc. |
| Nestle S.A. |
| Frito-Lay Inc. |
| Kite Hill |
| Good Foods Group LLC |
| Others |
Value Network & Pricing Analysis
Undercapacity in California almond processing facilities is compressing raw material availability for cashew and oat base formulations, forcing manufacturers to accept indexed pricing contracts that transfer harvest volatility risk downstream while constraining margin flexibility across premium and economy tiers.
Pricing Analysis
Cost-plus contracts indexed to California water allocation futures dominate raw material procurement for plant-based dip bases. Price differentiation hinges on USDA Organic certification tier and refrigerated logistics integration depth. Pricing pressure stems from aquafaba stabilizer performance gaps that shorten shelf stability and increase spoilage write-offs. Club channel buyers exhibit lowest price sensitivity due to volume commitments, while convenience store operators resist premium positioning without single-serve format justification.
Supply Chain Analysis
Upstream feedstock for chickpea aquafaba and cultured almond proteins concentrates in California, India, and Vietnam growing regions. Raw material flows draw from pulse crop processors, nut shelling cooperatives, and precision fermentation bioreactors. Tariff exposure on South Asian cashew imports creates margin volatility for creamy dip manufacturers. Distribution runs through direct-store-delivery partnerships with temperature-validated accountability from production facility to retail display case.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low calorie veggie dip markets sit in early-cycle expansion as refrigerated perimeter placements displace center-store shelf space and Gen Z adoption accelerates clean-label trial rates beyond historical category norms.
For Market Incumbents: Pre-empt pouch format encroachment by securing exclusive convenience channel partnerships before fermentation-specialist entrants achieve scale. Bolster captive vegetable processing infrastructure to defend against raw material cost spikes from California water policy shifts. Prioritize direct-store-delivery relationship consolidation in club channel expansion zones. For New Entrants and Emerging Players: Establish a beachhead in airline catering and corporate foodservice channels where pre-portioned formats face minimal incumbent saturation. Target Texas and Florida retail clusters with spicy flavor profiles tailored to Latin cuisine-adjacent demographics. Deploy precision fermentation partnerships to compress clean-label development timelines relative to conventional reformulation cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated producers with captive agricultural infrastructure and established refrigerated logistics networks. Long-term viability favors field-to-tub integrators over contract-manufactured brands dependent on third-party cold-chain partnerships. Monitor FDA added-sugar disclosure threshold revisions as inflection signals for reformulation capital deployment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Line Conversion | REACH-compliant emulsifier validation opens EU export pathways for domestic manufacturers. |
| Pouch Format Development | Single-serve flexible packaging captures convenience channel growth beyond tub infrastructure limits. |
| Precision Fermentation Partnership | Cultured protein platforms compress non-dairy base development from eighteen months to under six. |
| Direct-Store-Delivery Consolidation | Temperature-validated logistics guarantees secure Costco and Sam's Club placement requirements. |
| Organic Certification Investment | USDA pathways expand margin pools in club channel expansion and health food store networks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with category buyers at Kroger and Albertsons, supply planners at refrigerated logistics providers, fermentation R&D directors, and club channel procurement officers; and secondary validation through FDA labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and EU REACH additive restriction notices. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates.
Forecast inputs span product type segmentation across hummus, creamy dip, guacamole, and salsa variants; packaging format economics for tubs versus pouches; and distribution channel velocity through supermarkets, online retailers, and convenience stores. CAGRs were derived from regression analysis against refrigerated perimeter expansion rates and clean-label adoption curves. Industry-specific inputs include California water allocation policy scenarios and EU EFSA emulsifier approval timelines.
Stress conditions across almond and cashew harvest yields, cold-chain logistics disruption frequency, and FDA serving size revision implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Gen Z purchase velocity persistence and club channel slotting fee trajectories. Cross-checking against Circana refrigerated category growth benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Dill Juice Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Goldenseal Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Dong Quai Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Liquid Mushroom Market