
 Moringa Products Market | 2026-2036
Moringa Products Market Size, Share, and Industry Trends Forecast 2026-2036
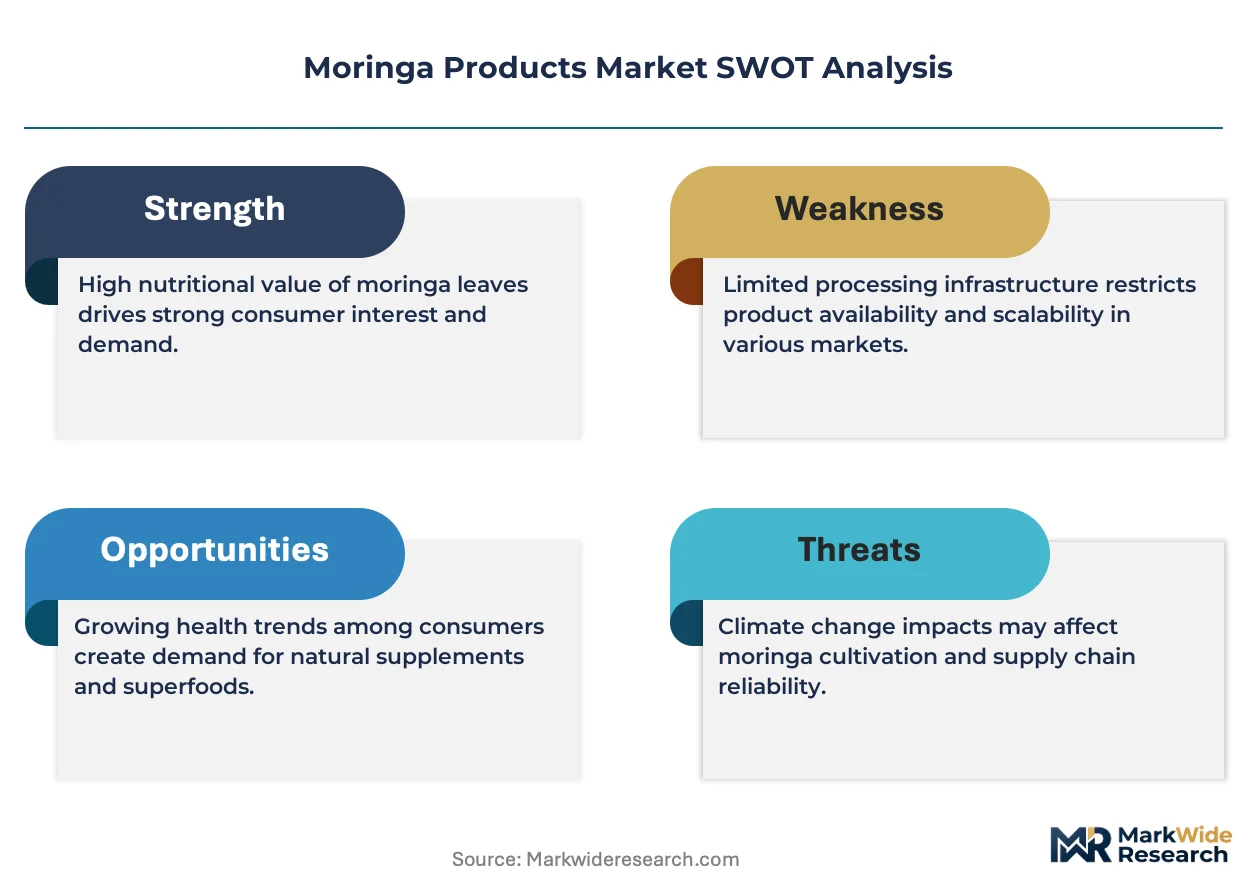
Moringa Products Market Analysis
Direct-to-consumer online retail is fragmenting as moringa brands bypass traditional health shop gatekeepers. Kuli Kuli, Inc. leverages its specialty store relationships to sustain premium positioning in North American markets. Organic India Pvt. Ltd. anchors bulk supply contracts with nutraceutical companies seeking certified organic leaf powder. Grenera Nutrients Pvt. competes on extraction technology leadership for high-potency moringa oleifera concentrates.
Moringa products encompass processed derivatives of Moringa oleifera, a drought-resistant tree whose leaves contain protein, vitamins A and C, calcium, potassium, and antioxidant compounds including quercetin and chlorogenic acid; primary industrial applications span functional food fortification, cosmetic active formulations, and dietary supplement manufacturing. Leaf powder dominates volume throughput due to its stability and versatility in food and beverage industry applications, while oil commands premium pricing from cosmetics manufacturers seeking cold-pressed ben oil for emollient formulations. Capsules represent the fastest-growing form segment as health conscious consumers prioritize standardized dosing and portability over bulk powder preparation.
The US FDA regulates moringa dietary supplements under DSHEA, requiring substantiation of structure-function claims without pre-market approval, while India's FSSAI mandates pesticide residue limits and heavy metal thresholds for herbal product exports. The EU EFSA novel food authorization pathway shapes market access for new moringa extract formats entering European nutraceutical channels. Stakeholders must monitor evolving organic certification harmonization between USDA NOP and India Organic standards to preempt supply chain disqualification risks.
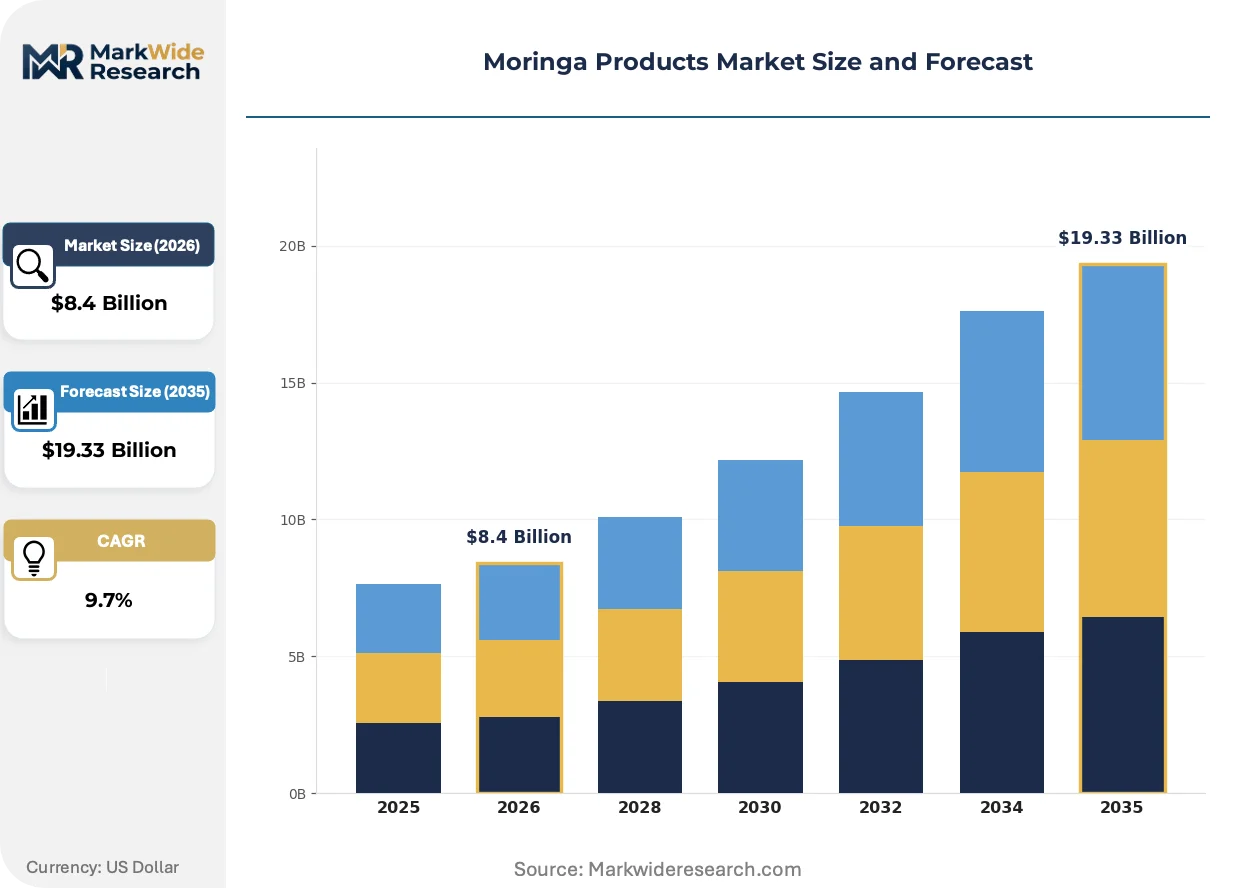
Market Dynamics
Smallholder cooperatives in Nigeria's northern states currently concentrate raw leaf supply, creating procurement bottlenecks that nutraceutical extractors must navigate through direct farm-gate contracting and backward integration into drying facilities.
Growth Catalysts
- India's PLI scheme for herbal manufacturing:Domestic processing capacity expansion is incentivizing investment in extraction infrastructure, reducing import dependence for international brands.
- Capsule format preference among health-conscious consumers:Standardized dosing and portability requirements are pulling demand away from bulk powder preparation in North American nutraceutical channels.
- Cold-pressed ben oil extraction:Cosmetics manufacturers seeking emollient formulations are commanding premium pricing for moringa oil, expanding cultivation acreage dedicated to seed production.
Market Restraints
- Input cost volatility in organic certification:USDA NOP and India Organic harmonization gaps create compliance overhead that disqualifies smallholder batches from export contracts.
- Supply concentration in Kano and Kaduna states:Weather shocks or political instability in these Nigerian corridors disrupt raw material flows to international extractors.
- Substitution threat from spirulina and chlorella:These established microalgae proteins compete for shelf space in functional food fortification applications with comparable nutritional profiles.
Strategic Opportunities
- Underpenetrated Brazilian nutraceutical market:ANVISA's evolving herbal product framework creates first-mover advantage for brands establishing local formulation partnerships.
- EU EFSA novel food authorization pathway:New moringa extract formats entering European channels benefit from regulatory clarity that pre-approves safety dossiers.
- Direct-to-consumer subscription models:Specialty e-commerce platforms are disintermediating traditional health shop gatekeepers, capturing margin previously lost to retail markup.
Industry Challenges
- Phytochemical standardization expertise gap:Analytical chemists capable of validating quercetin and chlorogenic acid potency claims remain scarce in emerging cultivation regions.
- Heavy metal compliance timelines:FSSAI-mandated testing for arsenic and lead extends export certification cycles, tying up working capital in inventory.
- Legacy drying infrastructure incompatibility:Solar dehydration units favored by sustainability certifications underperform during monsoon seasons, forcing costly fossil-fuel backup.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moringa Products Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leaf Powder, Oil, Capsules, Tea End User: Health Conscious Consumers, Food & Beverage Industry, Cosmetics Manufacturers, Nutraceutical Companies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Shops Form: Powder, Liquid, Capsule, Extract |
| Companies Covered | Earth Expo Company, Botanica Natural Products, Organic India Pvt. Ltd., Aayuritz Phytonutrients Pvt. Ltd., Green Virgin Products LLC, Kuli Kuli, Inc., Moringa Initiative Ltd., Ancient Greenfields Pvt. Ltd., Grenera Nutrients Pvt., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moringa Products Market Emerging Trajectories
Supercritical CO2 extraction technology is compressing processing timelines while preserving heat-sensitive bioactives, fundamentally altering how concentrate manufacturers compete on potency claims.
Supercritical CO2 extraction systems operate at low temperatures to isolate moringa oleifera's antioxidant compounds without thermal degradation. Nutraceutical formulators in Germany and Switzerland are adopting these units at accelerated replacement cycles. Traditional solvent-based extraction is rendering obsolete for premium-grade concentrate production.
REACH registration requirements for novel botanical extracts are tightening purity documentation standards across EU member states. Cosmetics manufacturers sourcing moringa oil must now submit full toxicological dossiers for ben oil emollient applications. German and French formulators are consolidating supplier bases to pre-qualified extraction partners with existing REACH master files.
Health practitioners are unbundling bulk powder recommendations from standardized capsule protocols, shifting patient compliance models. Functional medicine clinics in California and Texas are replacing loose-leaf prescriptions with pre-dosed blister packs. This behavioral pivot is most visible in integrative health networks where patient retention metrics now favor convenience formats.
Moringa Products Market Segmentation
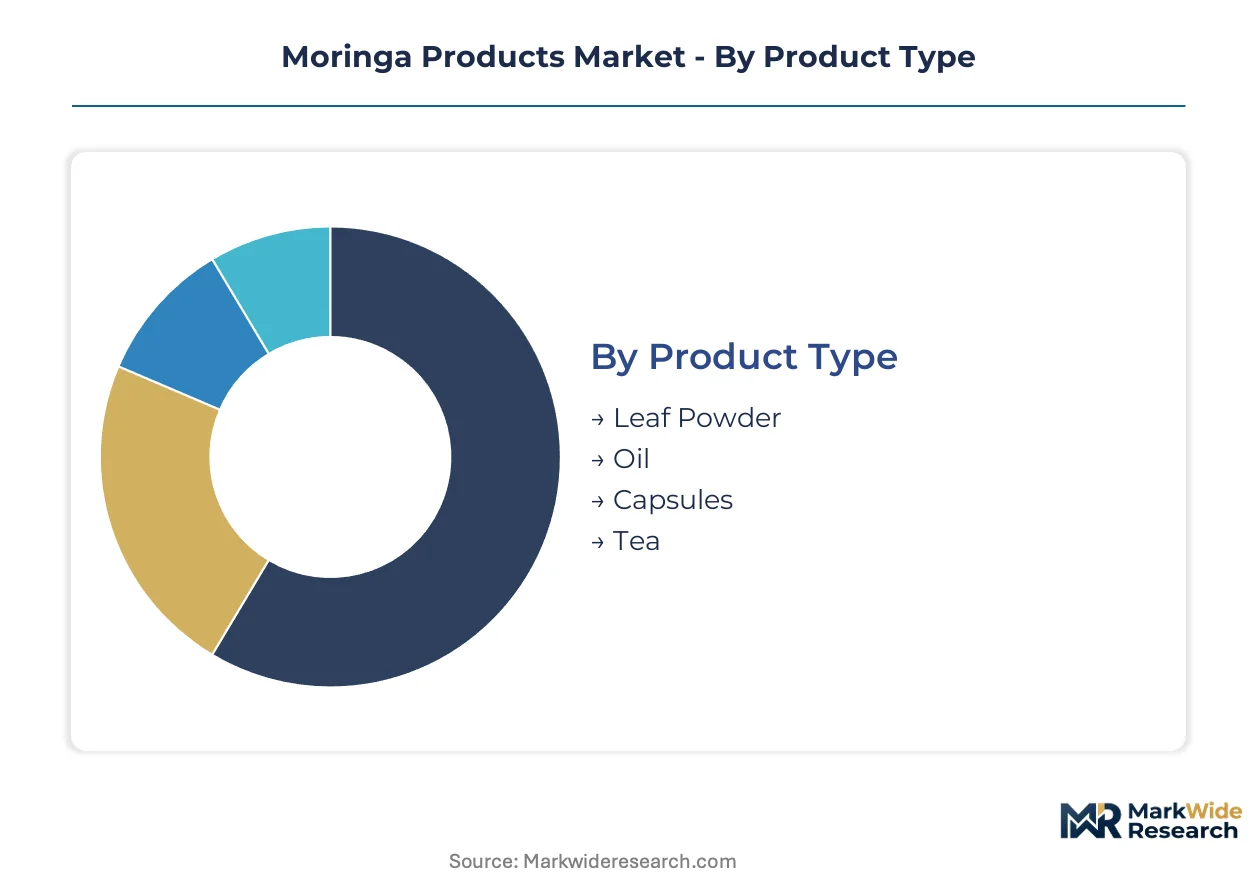
Moringa derivatives serve divergent value chains requiring distinct processing specifications and certification standards. Product format determines shelf stability, dosage precision, and margin capture across nutraceutical, cosmetic, and functional food applications.
Product Type:
The use-case spectrum spans bulk ingredient supply to finished consumer goods, with each format demanding specialized extraction or preservation protocols.
- Leaf Powder:Dehydrated and pulverized moringa oleifera leaves retain protein, vitamins A and C, calcium, and antioxidant compounds including quercetin. Food and beverage manufacturers in Germany and the United States source certified organic powder for functional fortification, constrained by FSSAI-mandated heavy metal testing timelines that extend export certification cycles.
- Capsules:Pre-dosed gelatin or vegetable cellulose shells deliver standardized moringa leaf powder or extract for dietary supplementation. Health-conscious consumers in North American nutraceutical channels prioritize portability and precise dosing, pulling demand away from bulk powder preparation and expanding most quickly among convenience-oriented formats.
- Oil:Cold-pressed ben oil from moringa seeds contains high oleic acid content and emollient properties for cosmetic formulations. Cosmetics manufacturers in France and Switzerland command premium pricing for REACH-registered emollient applications, consolidating supplier bases to pre-qualified extraction partners with existing toxicological dossiers.
- Tea:Whole or cut dried moringa leaves packaged for infusion deliver milder antioxidant concentration than extracts. Direct-to-consumer subscription platforms in California and Texas disintermediate traditional health shop gatekeepers for this format.
The dominant share belongs to Leaf Powder, while Capsules is closing the gap fastest.
End User:
Customer archetypes stratify by volume scale, certification requirements, and formulation expertise.
- Nutraceutical Companies:These formulators require standardized extracts with validated quercetin and chlorogenic acid potency claims for supplement manufacturing. India's PLI scheme for herbal manufacturing is incentivizing domestic processing capacity expansion to serve these buyers, reducing import dependence for international brands.
- Cosmetics Manufacturers:Formulators seek cold-pressed ben oil and antioxidant-rich extracts for emollient and active ingredient applications. REACH registration requirements across EU member states are tightening purity documentation standards, forcing consolidation toward pre-qualified extraction partners.
- Food & Beverage Industry:Processors incorporate moringa leaf powder into functional food fortification applications including energy bars, beverages, and baked goods. Substitution pressure from spirulina and chlorella constrains shelf space allocation for this segment.
- Health Conscious Consumers:Individual purchasers prioritize convenience formats and organic certification transparency. Specialty e-commerce platforms capture margin previously lost to retail markup through direct-to-consumer subscription models.
Nutraceutical Companies command the largest procurement volumes, though Cosmetics Manufacturers extract the highest per-kilogram pricing.
Distribution Channel:
Channel selection determines margin retention, brand control, and customer relationship depth.
- Online Retail:Direct-to-consumer platforms and third-party marketplaces enable brands to bypass traditional gatekeepers. Kuli Kuli leverages specialty store relationships alongside digital channels to sustain premium positioning in North American markets.
- Specialty Stores:Natural product retailers and co-ops curate certified organic and fair-trade moringa assortments for discerning shoppers. These outlets remain critical for brand discovery despite e-commerce encroachment.
- Supermarkets:Mass retail placement requires price-competitive positioning and conventional packaging formats. Organic India anchors bulk supply contracts through this channel for certified organic leaf powder distribution.
- Health Shops:Traditional brick-and-mortar wellness retailers face margin compression as brands disintermediate through subscription models and direct sales.
Online Retail captures share fastest from legacy channels, yet Specialty Stores maintain pricing power for premium-tier products.
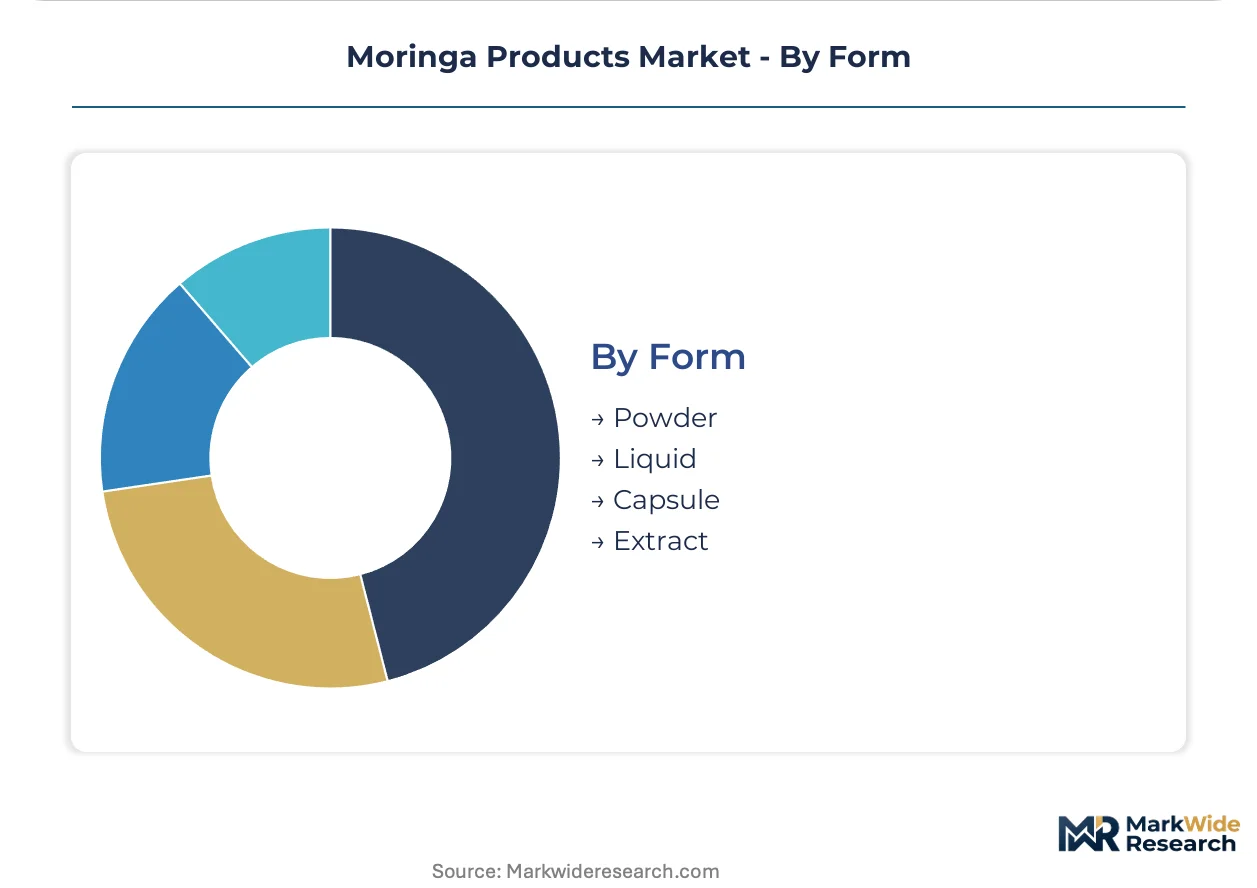
Form:
Physical state dictates extraction methodology, stability profile, and end-use flexibility.
- Powder:Spray-dried or freeze-dried particulate offers longest shelf stability and broadest formulation versatility. Solar dehydration units favored by sustainability certifications underperform during monsoon seasons, forcing costly fossil-fuel backup for powder production.
- Extract:Concentrated bioactive fractions including quercetin and chlorogenic acid isolates require supercritical CO2 or solvent-based processing. Grenera Nutrients competes on extraction technology leadership for high-potency concentrates targeting German and Swiss formulators.
- Liquid:Aqueous or oil-based suspensions enable beverage fortification and tincture applications. This format demands preservative systems or cold-chain logistics that constrain distribution economics.
- Capsule:Encapsulated powder or extract delivers precise dosing for supplement protocols. Functional medicine clinics in California and Texas are replacing loose-leaf prescriptions with pre-dosed blister packs to improve patient compliance metrics.
Powder retains volume leadership, while Extract commands the steepest expansion trajectory as supercritical CO2 technology compresses processing timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for herbal manufacturing is redirecting investment toward domestic extraction infrastructure, altering procurement patterns for international brands. Nigeria's northern corridor remains the dominant raw leaf source, though supply bottlenecks are forcing direct farm-gate contracting. Germany and Switzerland lead European concentrate demand through supercritical CO2 adoption.
India
Nutraceutical formulators in Bangalore and Hyderabad are expanding extraction capacity under FSSAI-mandated heavy metal compliance frameworks. The PLI scheme is incentivizing backward integration into drying facilities, reducing import dependence for leaf powder. Tamil Nadu and Karnataka clusters now host the majority of new supercritical CO2 installations serving export markets.
Nigeria
Smallholder cooperatives in Kano and Kaduna states concentrate raw leaf supply for international extractors seeking organic-certified biomass. Farm-gate contracting is displacing traditional aggregator networks as brands seek traceability documentation. Weather volatility in these northern corridors periodically disrupts material flows to European and North American processors.
Germany
REACH registration requirements for novel botanical extracts are consolidating supplier bases among pre-qualified extraction partners. EFSA novel food authorization pathways shape market access for new moringa extract formats entering nutraceutical channels. Frankfurt and Munich formulators command premium pricing for validated quercetin and chlorogenic acid concentrates.
United States
DSHEA framework governs dietary supplement claims without pre-market approval, enabling rapid product iteration for capsule and powder formats. Functional medicine clinics in California and Texas are replacing loose-leaf prescriptions with pre-dosed blister packs. Direct-to-consumer subscription platforms in these states capture margin previously lost to health shop retail markup.
Brazil
ANVISA's evolving herbal product framework creates first-mover positioning for brands establishing local formulation partnerships. São Paulo and Rio de Janeiro nutraceutical distributors are expanding moringa assortments as consumer awareness of functional foods accelerates. Import dependence for certified organic leaf powder persists pending domestic cultivation scale-up.
Moringa Products Market Vendor Landscape
On the supply side, the industry is bifurcated between integrated processors controlling extraction technology and fragmented raw material suppliers competing on certification compliance. Three archetypes dominate: vertically integrated specialists with captive cultivation, technology-led concentrate manufacturers, and brand-centric marketers disintermediating traditional retail. Competitive moves center on backward integration into drying infrastructure and supercritical CO2 capacity expansion.
Among India-based integrated specialists, Organic India Pvt. Ltd. and Grenera Nutrients Pvt. exemplify the captive supply archetype through controlled organic certification pipelines. Kuli Kuli, Inc. occupies a position within the brand-centric tier, representing direct-to-consumer distribution models that bypass legacy health shop channels. These three entities collectively illustrate the geographic and strategic segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Earth Expo Company |
| Botanica Natural Products |
| Organic India Pvt. Ltd. |
| Aayuritz Phytonutrients Pvt. Ltd. |
| Green Virgin Products LLC |
| Kuli Kuli, Inc. |
| Moringa Initiative Ltd. |
| Ancient Greenfields Pvt. Ltd. |
| Grenera Nutrients Pvt. |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoint exposure at the FSSAI heavy metal testing stage determines both premium-tier spreads and supply chain configuration, as certification delays in India compress margins for time-sensitive buyers while rewarding pre-qualified extraction partners with pricing power in European nutraceutical channels.
Pricing Analysis
Certification grade creates the primary spread between premium and standard tiers. USDA NOP and India Organic harmonization gaps force three-tier pricing structure across certified organic, transition-grade, and conventional leaf powder. Cost compression in the conventional tier intensifies because Nigerian smallholders face disqualification from export contracts. Nutraceutical companies show least price sensitivity for REACH-registered concentrates, while food and beverage manufacturers in mass retail channels exhibit highest sensitivity to per-kilogram leaf powder rates.
Supply Chain Analysis
Extended payment terms from European extractors to Nigerian cooperatives strain working capital at the farm-gate level. Raw leaf supply draws from Nigeria, India, and emerging cultivation zones in Brazil. Input dependencies center on organic-certified seed stock, solar dehydration equipment, and supercritical CO2 processing units. Single-source vulnerability concentrates in Kano and Kaduna states where weather shocks disrupt material flows. Distribution runs through direct farm-gate contracting, regional drying facilities, and consolidated export channels to German and Swiss formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as FSSAI compliance timelines and REACH registration requirements create switching costs that anchor long-term supplier relationships.
For Market Incumbents: Entrench position through backward integration into Nigerian drying facilities and captive organic certification pipelines. Supercritical CO2 capacity expansion in Tamil Nadu and Karnataka clusters counters substitution pressure from spirulina and chlorella. Pre-qualified REACH master files in Germany consolidate supplier selection criteria in your favor. For New Entrants and Emerging Players: Pursue white-space opportunity in Brazil's underpenetrated nutraceutical market before ANVISA framework maturation closes the window. Direct-to-consumer subscription models in California and Texas offer lowest barrier to brand establishment. Partner with established extraction technology providers rather than building in-house processing infrastructure. For Investors and Strategic Acquirers: EU EFSA novel food authorization reshapes the acquisition landscape toward dossier-ready extraction specialists. Five-to-ten-year viability favors integrated processors with captive cultivation and certified organic pipelines. Monitor ANVISA regulatory milestones as the signal for Brazilian market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | German and Swiss formulators prioritize low-temperature bioactive preservation for premium concentrate positioning. |
| Backward Integration into Drying Infrastructure | India's PLI scheme incentivizes farm-gate facility construction that reduces Nigerian supply bottlenecks. |
| REACH Master File Consolidation | French and German cosmetics manufacturers narrow supplier bases to pre-qualified extraction partners with existing dossiers. |
| Direct-to-Consumer Subscription Launch | California and Texas health-conscious consumers shift from health shop retail toward convenience-oriented capsule protocols. |
| Organic Certification Pipeline Investment | USDA NOP and India Organic harmonization gaps create disqualification risk that rewards certified-captive supply control. |
Methodological Framework
Operator-level perspectives from extraction technology specialists, FSSAI compliance officers, Nigerian cooperative managers, and German nutraceutical formulators anchored the qualitative base. Secondary validation drew from FSSAI export certification databases, REACH registration filings, EFSA novel food authorization records, and India PLI scheme disbursement disclosures. Bottom-up procurement volume estimates triangulated against top-down market size assessments.
Scenario-bracketing framed projections across the analysis window through sensitivity testing of regulatory timeline variables and organic certification adoption curves. Segmentation dimensions spanned product format, end-user archetype, distribution channel, and regional regulatory cluster. CAGRs derived from modeled volume-price interactions across leaf powder, capsule, oil, and extract categories. Supercritical CO2 installation capacity and Nigerian farm-gate contracting penetration served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in organic input commodity costs, euro-dollar exchange rates, or Nigerian agricultural policy would shift the trajectory. Forecasts reflect documented assumptions regarding PLI scheme continuity and EFSA authorization timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Triphala Powder Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Dong Quai Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Space Food Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Medicinal Herbs Market