
 Global Pine Pollen Market | 2026-2036
Global Pine Pollen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pine Pollen Market Outlook
Organic certification under USDA NOP and EU 2018/848 is reorganizing supplier eligibility, favoring operations with audited wild-harvesting protocols. Surthrival Premium Supplements leverages controlled sourcing from specific Pinus species to sustain premium positioning. Lost Empire Herbs anchors its portfolio around third-party tested extracts, while Hunan Nutramax dominates bulk ingredient supply to international formulators.
Pine pollen comprises the male microgametophyte of Pinus species, typically harvested during a brief spring dispersal window when cell-wall-broken processing unlocks bioavailable phytoandrogens, polysaccharides, and amino acid profiles for endocrine-support applications. Powder formats lead volume through direct-to-consumer blending flexibility, though extract segments command margin concentration due to standardized flavonoid content requirements. Online retail channels are accelerating fastest as subscription models reduce customer acquisition costs for specialized botanicals.
FDA cGMP enforcement for dietary supplements and EU Novel Food authorization pathways shape formulation investment cycles and cross-border shipment eligibility. China's NMPA traditional medicine standards and SAMR food safety labeling rules govern domestic processing scale and export certificate issuance. Stakeholders must monitor evolving adaptogen classification debates in multiple jurisdictions to anticipate reformulation obligations and channel restrictions.
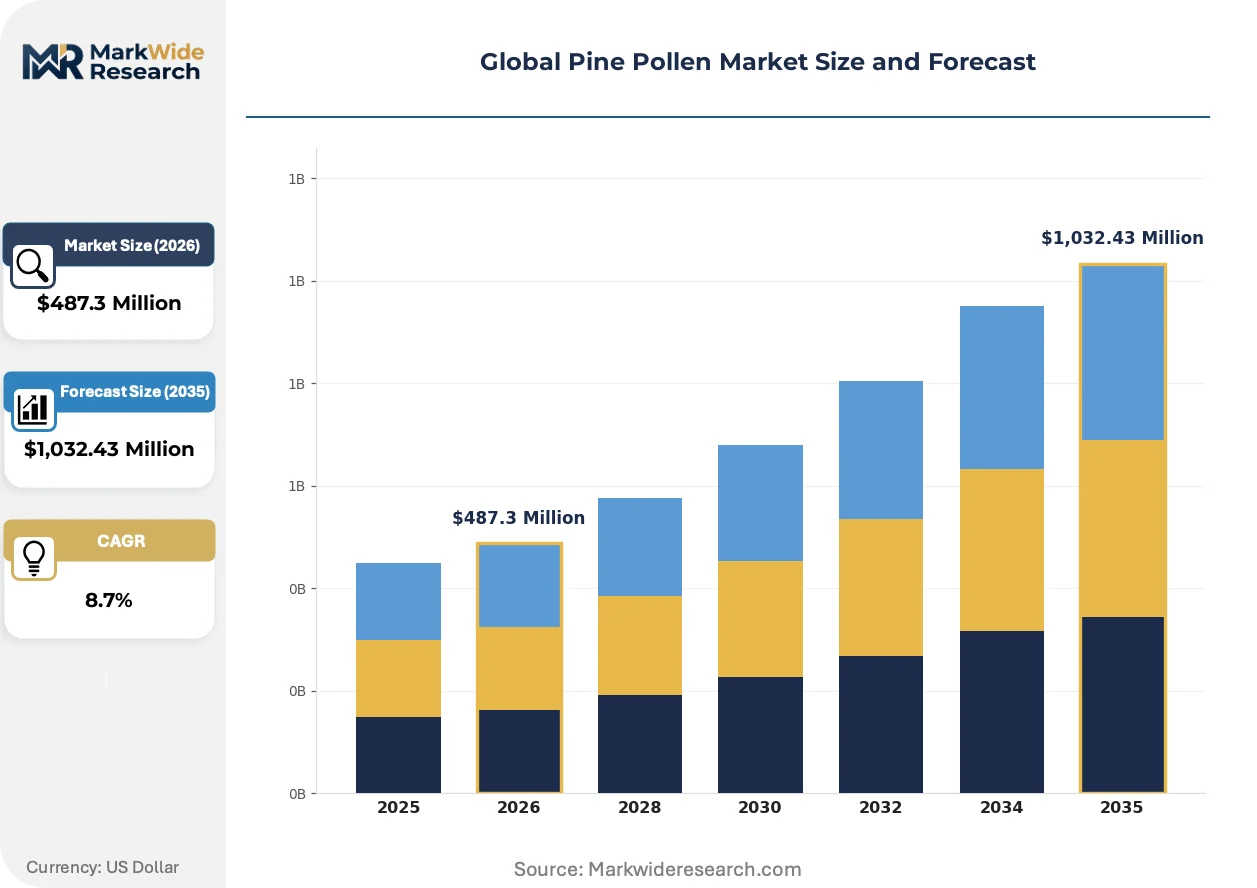
Market Dynamics
Cell-wall-breaking technology is compressing processing timelines while amplifying bioavailability claims, forcing mid-tier suppliers to upgrade equipment or exit as premium extractors capture margin concentration.
Growth Catalysts
- EU Novel Food authorization:Standardized flavonoid content requirements under EFSA guidelines are pulling investment toward certified extraction facilities in Germany and the Netherlands.
- China's traditional medicine modernization:NMPA streamlining of export certificate issuance is accelerating bulk ingredient flows to international formulators.
- Subscription commerce infrastructure:Direct-to-consumer platforms are reducing customer acquisition costs for specialized botanicals across North American wellness channels.
Market Restraints
- Wild-harvest input volatility:Pinus massoniana and Pinus sylvestris pollen yields fluctuate with spring temperature patterns, compressing the annual collection window to 7-14 days in key producing provinces.
- US FDA cGMP enforcement:Dietary supplement labeling rules are disqualifying smaller processors lacking audited batch documentation systems.
- Plant-based adaptogen substitution:Ashwagandha and rhodiola extracts compete for identical endocrine-support positioning at lower price points.
Strategic Opportunities
- South Korean functional food integration:MFDS health functional food codes are opening shelf-space expansion in Seoul and Busan retail channels for standardized pollen extracts.
- USDA Organic certification arbitrage:Wild-harvesting protocols meeting NOP standards command 40-60% price premiums in North American natural products retail.
- Cell-wall-breaking + spray-drying convergence:Integrated processing lines are enabling single-origin traceability claims that differentiate premium SKUs from commodity powders.
Industry Challenges
- Phytochemical assay standardization:Inconsistent testing methodologies across ISO 17025 laboratories create batch-to-batch variability disputes between suppliers and formulators.
- Dual-use botanical classification:Evolving adaptogen debates in multiple jurisdictions force reformulation investments as regulators reconsider pine pollen's food versus drug status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pine Pollen Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pine Pollen Powder, Pine Pollen Capsules, Pine Pollen Extract, Pine Pollen Tablets Application: Dietary Supplements, Health Food, Cosmetics, Herbal Remedies Distribution Channel: Online Retail, Health Stores, Pharmacies, Grocery Stores End User: Fitness Enthusiasts, Health Conscious Consumers, Athletes, General Public |
| Companies Covered | Surthrival Premium Supplements, Na'vi Organics, Pure Mountain Botanicals, Dragon Herbs, Woodland Essence, Lost Empire Herbs, Hybrid Herbs, Hunan Nutramax, RAW Forest Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pine Pollen Market Strategic Shifts
Processing technology and certification protocols are reconfiguring competitive advantage, separating capital-intensive extractors from commodity powder traders while regulatory clarity in major markets determines cross-border shipment eligibility.
Low-temperature cell-wall-breaking equipment is decomposing the traditional tradeoff between yield preservation and nutrient bioavailability. Premium supplement brands in California and Colorado are retrofitting production lines with nitrogen-protected milling systems. This technology is decomposing the market into two tiers: standardized extract suppliers commanding formulation partnerships versus undifferentiated bulk traders facing margin compression.
EU 2018/848 organic certification is tightening wild-harvesting documentation requirements for third-country suppliers. Operations lacking GPS-tracked collection zones and species verification protocols are losing access to German and French distribution networks. Bulk ingredient exporters in Hunan and Yunnan provinces are reorganizing supplier cooperatives to meet batch-level traceability mandates.
Chinese consumers are pivoting toward domestic-branded finished products over raw material exports. Tmall and JD.com data shows rising preference for NMPA-registered traditional medicine formats over unprocessed powders. This rotation is most visible in tier-one cities where younger demographics blend TCM consumption with fitness and skincare routines, forcing international formulators to localize brand positioning or cede premium positioning to domestic players.
Global Pine Pollen Market Segmentation
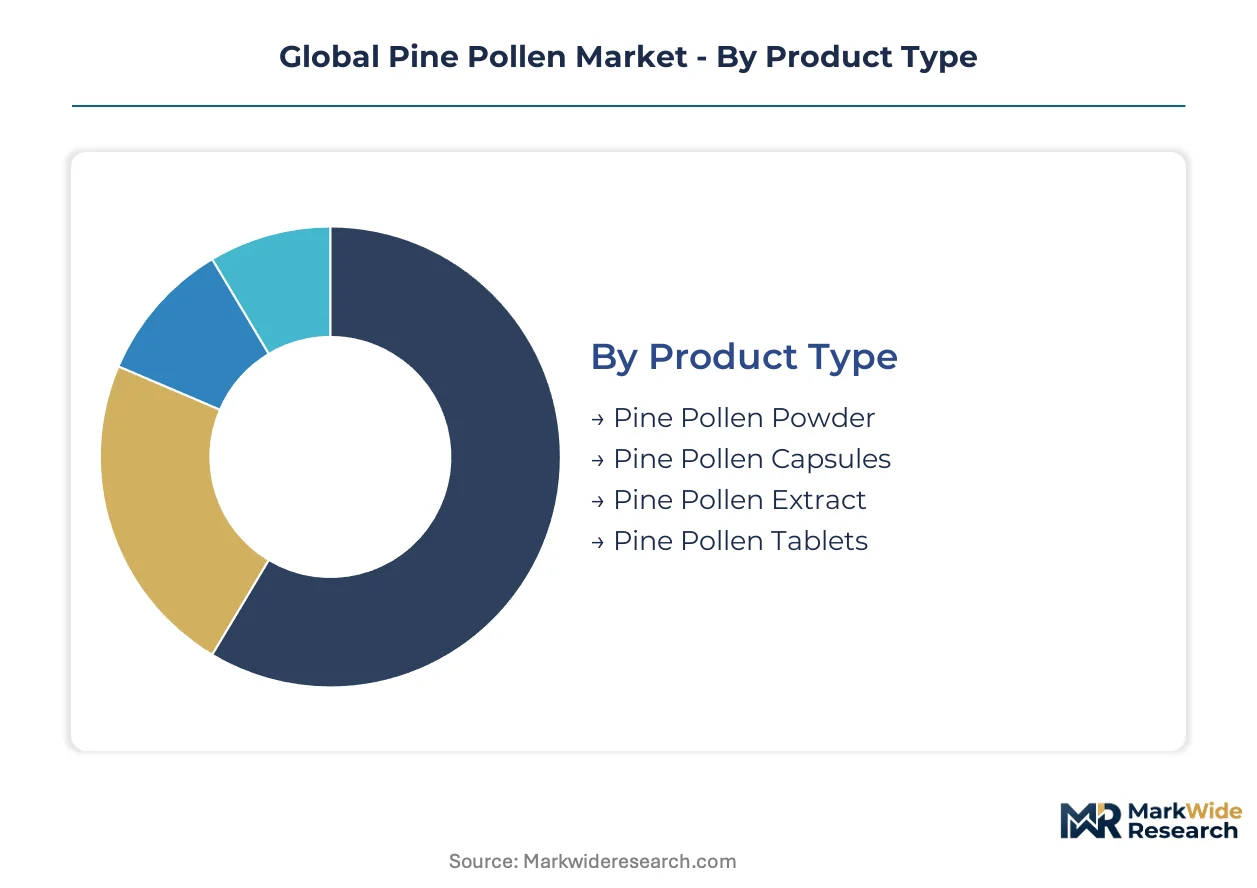
Pine pollen's bioactive complexity demands precise format matching to end-use requirements. Regulatory frameworks across FDA, EFSA, and NMPA jurisdictions enforce distinct specifications for each product category, channel, and consumer segment.
Product Type:
FDA cGMP labeling rules and EU Novel Food extract purity standards create divergent compliance burdens across formats, concentrating investment toward certified processing capabilities.
- Pine Pollen Powder:Cell-wall-broken powders deliver phytoandrogens and polysaccharides in unstandardized form. Direct-to-consumer blending in North American wellness channels drives volume, though batch variability limits pharmacy distribution.
- Pine Pollen Extract:Standardized flavonoid content meets EFSA Novel Food authorization thresholds. German and Dutch extraction facilities capture formulation partnerships as premium supplement brands seek certified inputs for EU market entry.
- Pine Pollen Capsules:Pre-measured dosing appeals to fitness enthusiasts seeking convenience. Capsule manufacturing requires additional encapsulation equipment investment that filters smaller suppliers.
- Pine Pollen Tablets:Compressed formats suit TCM traditional medicine channels in China. NMPA registration requirements favor domestic processors with established export certificate protocols.
Established volume favors Pine Pollen Powder; emerging adoption favors Pine Pollen Extract.
Application:
End-use specifications range from bulk ingredient supply to finished branded goods, with margin concentration shifting toward formats commanding regulatory clearance.
- Dietary Supplements:Cell-wall-breaking technology unlocks bioavailable phytoandrogens for endocrine-support positioning. Subscription commerce infrastructure in California and Colorado reduces customer acquisition costs for specialized botanicals.
- Cosmetics:Polysaccharide content drives skincare formulations targeting anti-aging claims. South Korean MFDS functional food codes and topical regulations create dual-pathway market access.
- Health Food:Functional food integration requires ingredient stability through processing. EU 2018/848 organic certification mandates GPS-tracked wild-harvesting documentation for third-country suppliers.
- Herbal Remedies:TCM modernization in China concentrates demand through NMPA-registered formats. Younger demographics in tier-one cities blend traditional consumption with fitness routines.
Ingredient supply concentrates in Dietary Supplements; finished goods expansion centers on Cosmetics.
Distribution Channel:
Channel selection determines regulatory exposure and margin capture, with digital infrastructure enabling traceability claims that differentiate premium positioning.
- Online Retail:Subscription models reduce customer acquisition costs for specialized botanicals. Single-origin traceability claims propagate most effectively through direct-to-consumer platforms.
- Health Stores:USDA Organic certification commands 40-60% price premiums in North American natural products retail. Staff education requirements favor standardized extract formats with clear dosing protocols.
- Pharmacies:NMPA registration and FDA cGMP compliance create qualification barriers. Batch documentation systems disqualify smaller processors lacking audited quality management.
- Grocery Stores:Mass-market placement demands price-competitive positioning. Ashwagandha and rhodiola substitutes compete for identical endocrine-support shelf space at lower price points.
Margin concentration follows Online Retail; regulatory qualification favors Pharmacies.
End User:
Consumer sophistication varies across fitness-optimization, preventive wellness, and traditional medicine orientations, shaping format preferences and price elasticity.
- Fitness Enthusiasts:Seek phytoandrogen content for performance positioning. Pre-workout and recovery formulations in US and Australian markets favor extract standardization.
- Health Conscious Consumers:Prioritize organic certification and wild-harvesting protocols. EU 2018/848 compliance enables access to German and French distribution networks.
- Athletes:Demand batch-tested inputs for anti-doping compliance. Third-party certification requirements concentrate procurement toward ISO 17025-documented suppliers.
- General Public:Price-sensitive segment favoring powder formats for home blending. Tmall and JD.com data shows Chinese younger demographics pivoting toward domestic-branded finished products.
Premium positioning targets Fitness Enthusiasts; volume scaling centers on General Public.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Novel Food authorization pathways and China's NMPA export certificate streamlining are redirecting investment toward certified extraction facilities in Germany, the Netherlands, and Hunan province. These regulatory frameworks determine cross-border shipment eligibility for phytoandrogen-standardized products.
United States
FDA cGMP enforcement for dietary supplements disqualifies processors lacking audited batch documentation systems. California and Colorado host the largest concentration of subscription-commerce botanical brands retrofitting production lines with nitrogen-protected milling systems. Lost Empire Herbs anchors third-party tested extract supply to these channels.
China
NMPA traditional medicine standardization and SAMR food safety labeling rules govern domestic processing scale in Hunan and Yunnan provinces. Younger demographics in Shanghai and Beijing pivot toward domestic-branded finished products on Tmall and JD.com. Hunan Nutramax dominates bulk ingredient flows to international formulators.
Germany
EFSA Novel Food extract purity requirements under EU 2018/848 organic certification pull investment toward certified extraction facilities. GPS-tracked wild-harvesting documentation mandates filter third-country suppliers lacking batch-level traceability. Operations in Bavaria and Baden-Württemberg capture formulation partnerships for EU market entry.
South Korea
MFDS health functional food codes open shelf-space expansion in Seoul and Busan retail channels for standardized pollen extracts. Polysaccharide content drives skincare formulations targeting anti-aging claims through dual-pathway market access. Domestic processors integrate cell-wall-breaking technology for functional food applications.
Australia
TGA complementary medicine regulations enforce batch-tested input requirements for anti-doping compliance in sports nutrition channels. Fitness enthusiasts in Sydney and Melbourne seek phytoandrogen content for pre-workout and recovery formulations. Third-party certification requirements concentrate procurement toward ISO 17025-documented suppliers.
Global Pine Pollen Market Competitive Environment
Player mix skews toward specialized botanical suppliers with organic certification capabilities and bulk ingredient exporters serving international formulators. Mid-tier processors face margin compression as cell-wall-breaking technology investments separate standardized extract suppliers from commodity powder traders. Two strategic archetypes dominate: premium supplement brands leveraging controlled sourcing protocols, and bulk ingredient suppliers organizing supplier cooperatives for traceability compliance. Competitive moves concentrate on USDA Organic certification arbitrage and integrated processing lines enabling single-origin traceability claims.
Within the premium supplement tier, Surthrival Premium Supplements and Lost Empire Herbs exemplify brands leveraging third-party testing and controlled sourcing from specific Pinus species to sustain positioning. Hunan Nutramax occupies a position among bulk ingredient exporters reorganizing supplier cooperatives in Hunan and Yunnan provinces to meet EU 2018/848 batch-level traceability mandates. These three anchors illustrate the market's bifurcation between finished goods differentiation and raw material supply consolidation.
| Leading Market Players |
|---|
| Surthrival Premium Supplements |
| Na'vi Organics |
| Pure Mountain Botanicals |
| Dragon Herbs |
| Woodland Essence |
| Lost Empire Herbs |
| Hybrid Herbs |
| Hunan Nutramax |
| RAW Forest Foods |
| Others |
Value Chain & Pricing Dynamics
EU 2018/848 organic certification gates both supplier qualification and price differentiation, mandating GPS-tracked wild-harvesting documentation that separates premium extractors from commodity traders while enabling 40-60% price premiums in certified channels.
Pricing Analysis
Cost-plus contracts with pollen yield indexation dominate bulk ingredient supply to international formulators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale. Pricing pressure stems from ashwagandha and rhodiola substitution in endocrine-support positioning. General Public buyers exhibit highest price sensitivity; Fitness Enthusiasts accept premium positioning for batch-tested inputs.
Supply Chain Analysis
Container availability constraints on Shanghai-Rotterdam and Shenzhen-Hamburg lanes compress spring collection-to-delivery windows. Wild-harvest pollen supply concentrates in China, with secondary sourcing from Russia and Mongolia. Processing draws from cell-wall-breaking equipment, nitrogen-protected milling systems, and spray-drying lines. Single-source vulnerability in Pinus massoniana collection zones threatens input security. Distribution runs through certified extraction facilities in Germany and the Netherlands for EU market entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pine Pollen Market sits in early-cycle expansion as subscription commerce infrastructure penetrates specialized botanical channels and NMPA export certificate streamlining accelerates bulk ingredient flows.
For Market Incumbents: Shield premium positioning by deepening backward integration into GPS-tracked wild-harvesting cooperatives in Hunan and Yunnan provinces. Invest in nitrogen-protected milling systems to defend against mid-tier equipment upgrades. Cell-wall-breaking technology investments separate standardized extract suppliers from margin-compressed commodity traders.
For New Entrants and Emerging Players: Lead with USDA Organic certification arbitrage in North American natural products retail, where audited protocols command substantial price premiums. Target South Korean functional food integration under MFDS health functional food codes as the most penetrable regulatory pathway. Deploy direct-to-consumer subscription models to reduce customer acquisition costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified botanical holdings seeking to monetize non-core pine pollen extraction capabilities. Long-term viability hinges on regulatory clarity in adaptogen classification debates across multiple jurisdictions. Monitor EFSA Novel Food authorization timelines as the critical inflection signal for EU market entry eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Wall-Breaking Technology Deployment | Nitrogen-protected milling systems unlock bioavailability claims that differentiate premium SKUs from commodity powders. |
| USDA Organic Certification Investment | Audited wild-harvesting protocols under NOP standards enable 40-60% price premiums in North American natural products retail. |
| EU Novel Food Authorization Pursuit | EFSA standardized flavonoid content requirements pull investment toward certified extraction facilities in Germany and the Netherlands. |
| Subscription Commerce Infrastructure Buildout | Direct-to-consumer platforms reduce customer acquisition costs for specialized botanicals across California and Colorado wellness channels. |
| Supplier Cooperative Reorganization | GPS-tracked collection zones and species verification protocols meet EU 2018/848 batch-level traceability mandates for third-country access. |
Study Parameters
The analysis maps cell-wall-broken powders, standardized extracts, capsules, and tablets, each validated through extraction facility operators, wild-harvest cooperative coordinators, dietary supplement formulators, and third-party certification auditors. Primary interviews combined with secondary sources including FDA cGMP inspection records, EFSA Novel Food submission databases, NMPA export certificate registries, and Tmall/JD.com category sales data. Bottom-up pollen yield modeling and top-down wellness channel sizing triangulate volume estimates.
Consistency checks validated outputs against customs trade flows for pine pollen HS codes and subscription commerce platform disclosed SKU counts across the analysis window. Segmentation dimensions modeled include product format, application end-use, distribution channel, and consumer sophistication tier. CAGRs derived from pollen yield elasticity to spring temperature patterns and channel penetration curves for specialized botanicals. Industry-specific inputs encompass cell-wall-breaking equipment deployment rates and organic certification audit completion timelines.
Forecasts assume regulatory continuity in FDA cGMP enforcement, EFSA Novel Food pathways, and NMPA traditional medicine standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as adaptogen classification debates and wild-harvest input volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Dill Juice Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Free-From Food Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Space Food Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Chamomile Market
Specialty Foods
Hot Pot Market
Specialty Foods
Edible Mushroom Market