
 Algeria Couscous Market | 2026-2036
Algeria Couscous Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Couscous Market Intelligence
Semolina milling expertise is rotating toward automated production lines as traditional artisan methods face labor shortages in Algeria's northern agricultural belt. Groupe METIDJI leverages vertical integration from wheat procurement to retail packaging, sustaining cost advantages across its distribution network. Groupe LABELLE dominates branded couscous segments in urban supermarkets, while Moulins Industriels Du Sebaou (MIS) anchors supply for institutional buyers through bulk channel control.
Couscous comprises steamed granules of crushed durum wheat semolina, traditionally processed through gradual hydration and rolling before sun-drying or mechanical dehydration to achieve uniform particle size. Traditional couscous commands premium positioning in ceremonial and export channels, whereas instant couscous captures volume growth among younger urban households seeking reduced preparation time. Whole wheat variants attract health-conscious segments despite higher raw material costs, with flavored couscous occupying niche positioning in supermarket aisles.
Algeria's national food safety regulator enforces durum wheat purity standards and packaging labeling requirements that filter informal producers from formal retail channels. The country's central bank and trade ministry coordinate import substitution policies affecting semolina pricing and local wheat procurement obligations. Stakeholders must monitor evolving domestic wheat harvest quality and regulatory enforcement intensity to calibrate sourcing strategies and capacity investments.
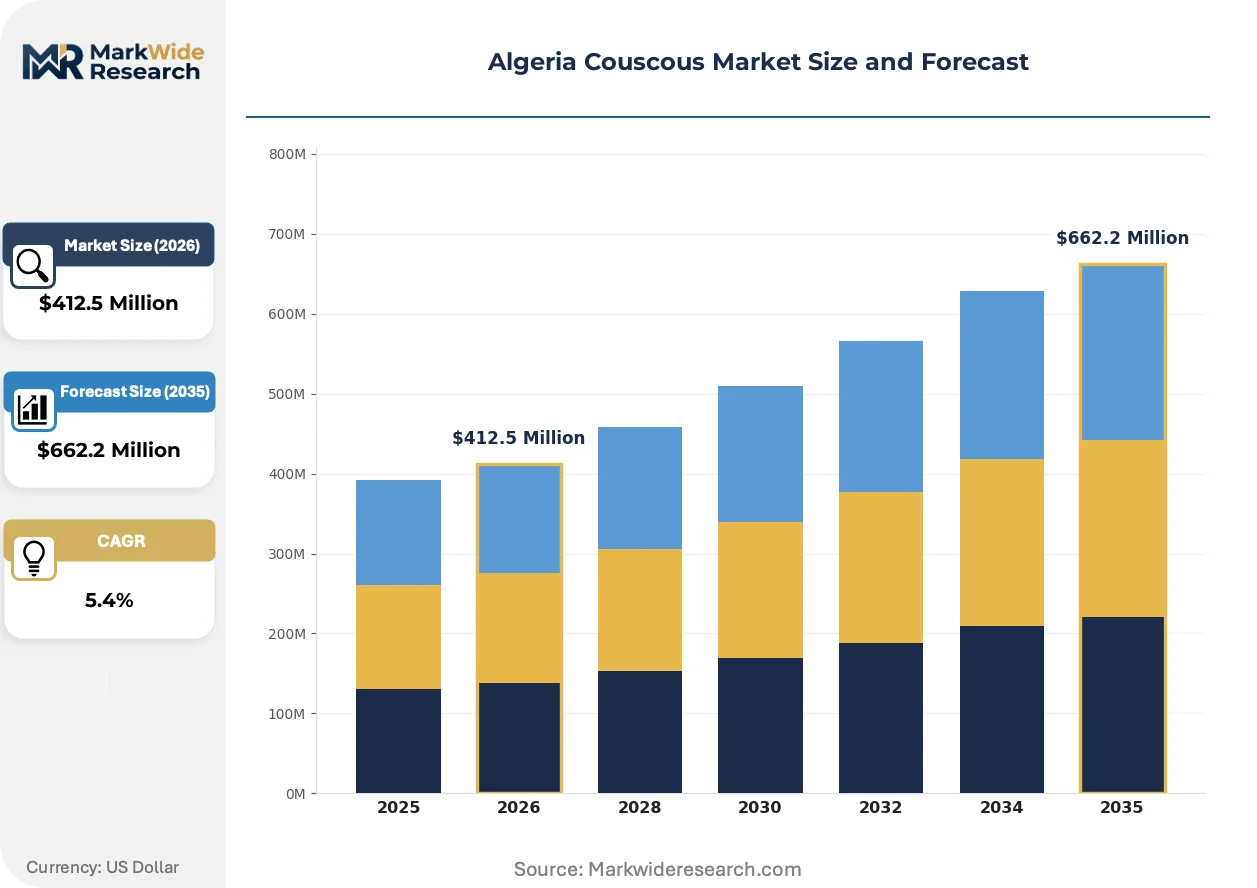
Market Dynamics
Algeria's durum wheat procurement obligations and semolina purity enforcement are compressing informal production capacity while accelerating automated milling investments across the northern agricultural belt. These structural pressures are redrawing competitive boundaries between artisan and industrial processors.
Growth Catalysts
- Durum wheat sourcing mandates:The national food safety authority's purity standards are filtering informal producers from formal retail channels, consolidating volume toward compliant industrial mills.
- Urban household convenience demand:Younger demographics in Algiers and Oran are driving instant couscous adoption, creating volume pull for mechanized dehydration lines.
- Oran industrial corridor concentration:Processing infrastructure clustering in this western hub reduces logistics costs for packaged goods distribution to coastal supermarkets.
Market Restraints
- Durum wheat import dependency:Domestic harvest quality variability forces reliance on foreign grain, exposing margins to currency fluctuation and trade ministry quota adjustments.
- Artisan labor scarcity:Traditional hand-rolling expertise is contracting in the northern belt as younger workers migrate to urban service employment.
- Whole wheat cost premium:Health-conscious segments face price resistance due to higher raw material costs and lower milling yields for bran-inclusive semolina.
Strategic Opportunities
- Constantine regional expansion:This eastern urban corridor shows underpenetrated branded couscous presence relative to Algiers and Oran supermarket saturation.
- Export ceremonial channel development:Traditional couscous commands premium positioning in diaspora markets, rewarding quality certification investments.
- Flavored product innovation:Spice-infused variants occupy niche supermarket positioning with minimal direct competition from commodity instant formats.
Industry Challenges
- Automated line integration complexity:Traditional mills face technical debt when retrofitting gradual hydration systems with continuous process controls.
- Food safety compliance timelines:Packaging labeling requirements demand laboratory verification cycles that delay product launches for smaller processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Couscous Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Couscous, Whole Wheat Couscous, Instant Couscous, Flavored Couscous Packaging Type: Bags, Boxes, Bulk, Cups Distribution Channel: Supermarkets, Online Retail, Local Markets, Wholesale Distributors End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Groupe LABELLE, Groupe METIDJI, Groupe Benamor, MEXICALI SARL, Societe Des Pates Industrielles (SOPI), Groupe SIM, Moulins Industriels Du Sebaou (MIS), Societe De Semoulerie Minoterie L'etoile (SOSEMIE), Les Moulins GERBIOR Benhamadi Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Couscous Market Strategic Shifts & Innovations
Mechanical dehydration and continuous milling systems are actively displacing batch artisan methods across Algeria's semolina processing base. These equipment transitions are compressing production cycles while reshaping workforce composition and capital requirements.
Continuous steam-injection dehydration is supplanting traditional sun-drying and batch oven methods in urban-focused mills. Medium-scale processors in Mitidja plain are adopting these lines to serve supermarket private-label contracts. The technology is supplanting seasonal production constraints and enabling year-round supply consistency for branded packagers.
The national food safety authority's labeling enforcement is tightening traceability requirements for durum wheat origin declarations. Industrial mills must now maintain batch documentation linking retail packages to specific procurement lots. Bulk channel suppliers serving institutional buyers face the steepest compliance cost increases as documentation systems replace informal verbal sourcing arrangements.
Younger urban households are compressing preparation time tolerance from traditional steaming cycles toward boil-and-serve convenience. Supermarket chains in Algiers are expanding shelf space for pre-portioned instant formats while reducing bulk traditional couscous facings. This behavioral pivot is most visible in coastal metropolitan zones where dual-income employment patterns limit weekday cooking duration.
Algeria Couscous Market Segmentation
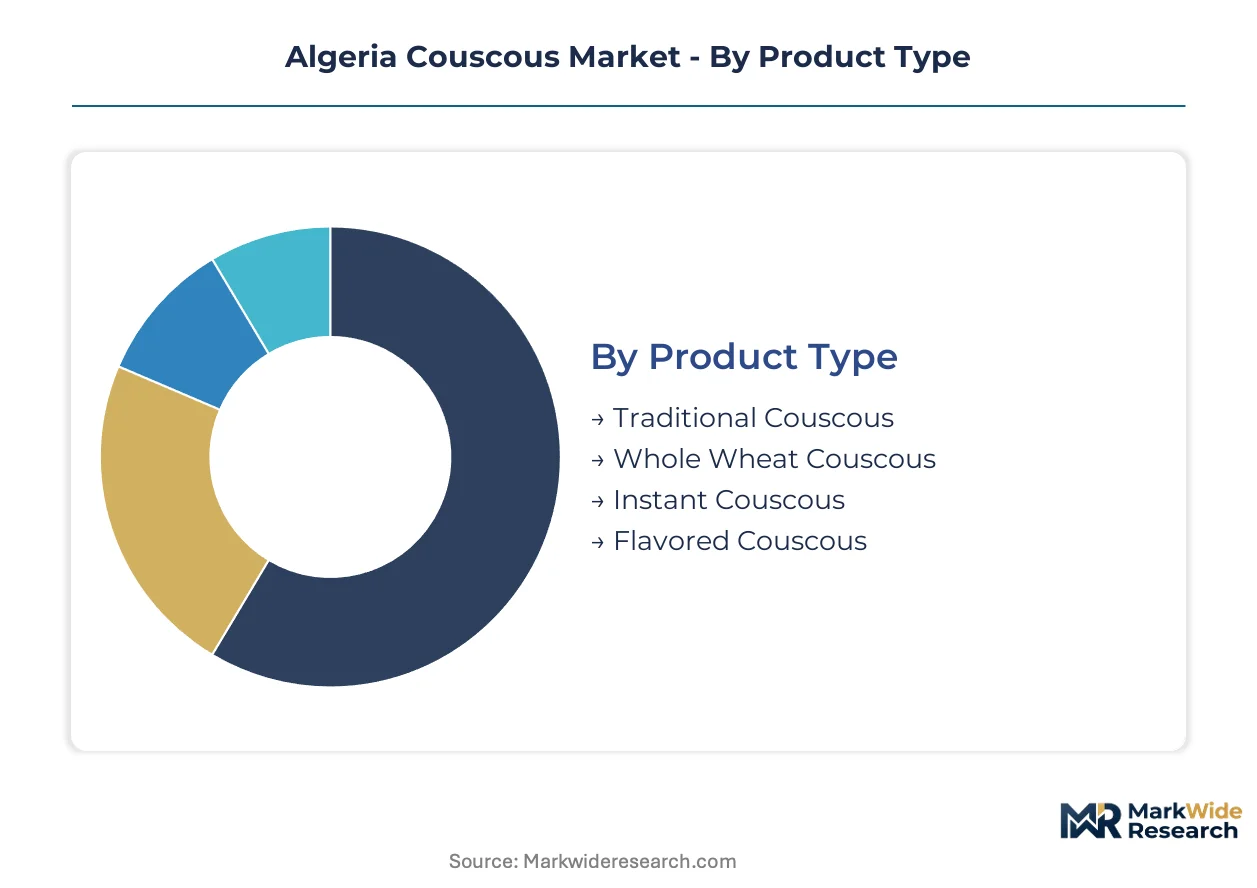
Algeria's couscous market segments reflect a dual-channel structure where ceremonial consumption flows through traditional formats while urban convenience demand reshapes product innovation. Understanding these segment boundaries clarifies where industrial scale competes against artisan heritage.
Product Type:
Channel-mix dynamics split sharply: traditional and whole wheat variants dominate ceremonial and health-focused retail, while instant and flavored formats capture supermarket shelf space targeting time-constrained households.
- Traditional Couscous:Steamed granules of crushed durum wheat semolina processed through gradual hydration and rolling before sun-drying or mechanical dehydration. Demand concentrates in northern urban corridors including Algiers and Oran for ceremonial occasions and export channels, supported by premium positioning in diaspora markets.
- Instant Couscous:Pre-cooked and mechanically dehydrated granules enabling boil-and-serve preparation without traditional steaming cycles. Younger demographics in Algiers and Oran are driving adoption, creating volume pull for mechanized dehydration lines serving supermarket chains.
- Whole Wheat Couscous:Bran-inclusive semolina variant with higher fiber content but elevated raw material costs and lower milling yields. Health-conscious segments in urban supermarkets face price resistance despite nutritional positioning.
- Flavored Couscous:Spice-infused variants occupying niche supermarket positioning with minimal direct competition from commodity instant formats.
By volume, Instant Couscous leads. By growth pace, Flavored Couscous is expanding most quickly.
Packaging Type:
Cost tier stratification separates premium boxed formats for branded retail from economy bulk channels serving institutional buyers, with bag and cup formats occupying mid-tier convenience positioning.
- Bags:Flexible polyethylene or polypropylene packaging dominating mid-volume household purchases across supermarket and local market channels. Northern urban corridors including Constantine show rising bag-format penetration as branded packagers expand distribution.
- Boxes:Rigid cardboard packaging commanding premium shelf positioning in Algiers and Oran supermarkets. Groupe LABELLE's branded couscous segments rely on box formats for visual differentiation and stacking efficiency.
- Bulk:Unpackaged or large-volume sack distribution serving institutional buyers and traditional local markets. Moulins Industriels Du Sebaou anchors supply through bulk channel control, though documentation requirements are replacing informal verbal sourcing arrangements.
- Cups:Single-serve rigid containers targeting convenience-oriented urban households and foodservice grab-and-go applications.
By volume, Bulk leads. By margin capture, Boxes command the highest unit economics.
Distribution Channel:
Geographic concentration patterns concentrate supermarket growth in coastal metropolitan zones while local markets retain dominance in interior regions and traditional consumption occasions.
- Supermarkets:Branded retail channels in Algiers, Oran, and Constantine expanding shelf space for pre-portioned instant formats while reducing bulk traditional couscous facings. Dual-income employment patterns in coastal metropolitan zones limit weekday cooking duration.
- Local Markets:Traditional souk and neighborhood vendor networks preserving artisan couscous access for ceremonial preparation and price-sensitive households. Northern agricultural belt producers maintain direct relationships with these channels.
- Wholesale Distributors:Bulk channel intermediaries serving restaurants, catering services, and food manufacturers with sack-format semolina.
- Online Retail:Emerging direct-to-consumer platform for branded packagers reaching diaspora demand and convenience-oriented urban households.
By transaction volume, Local Markets lead. By value growth rate, Supermarkets are climbing the fastest.
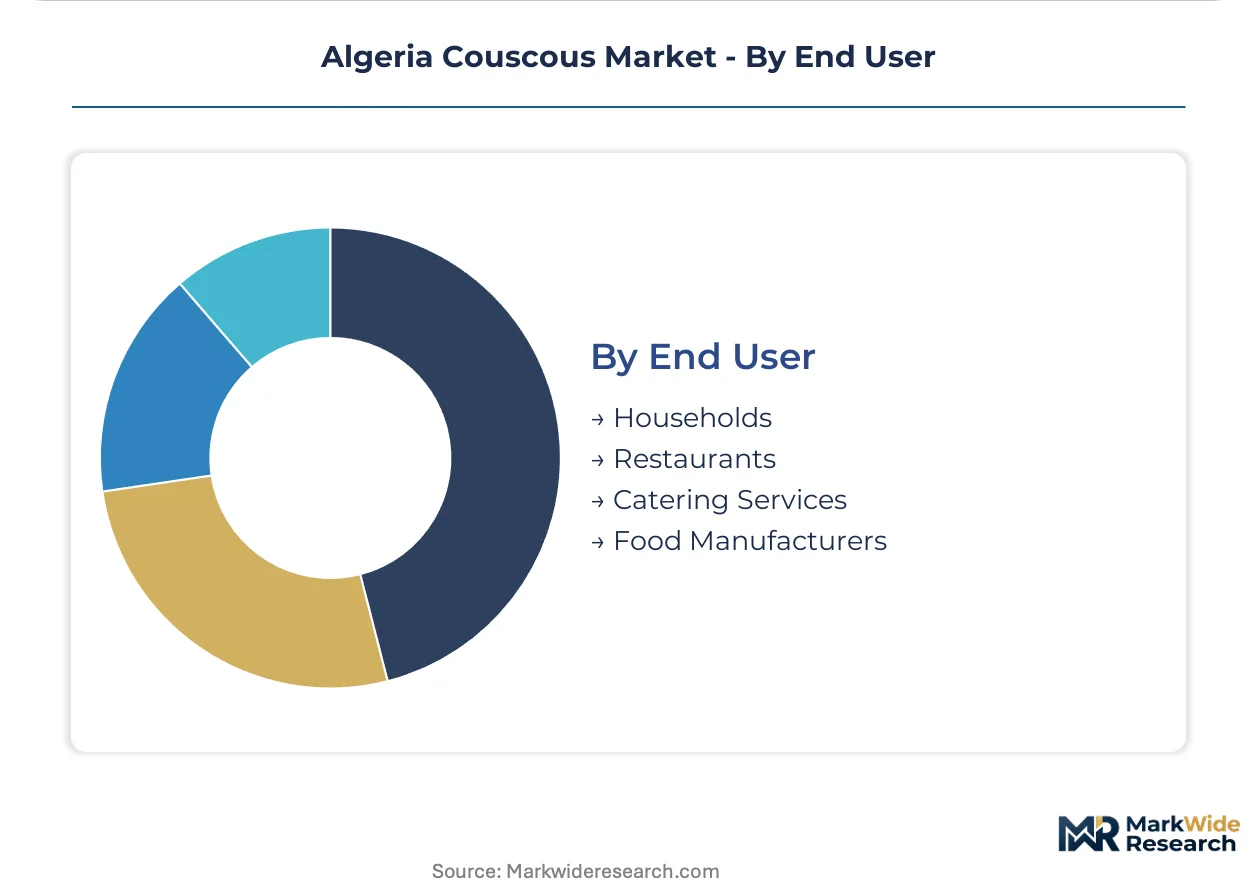
End User:
Application maturity separates household consumption as the established demand pillar from institutional segments where formalization and compliance investments are reshaping supplier relationships.
- Households:Core demand pillar spanning traditional ceremonial preparation and everyday convenience consumption. Younger urban households in Algiers and Oran are compressing preparation time tolerance toward boil-and-serve formats.
- Restaurants:Foodservice operators sourcing bulk traditional couscous for authentic preparation or instant formats for operational efficiency.
- Catering Services:Event and institutional food providers balancing cost control with volume consistency requirements.
- Food Manufacturers:Industrial buyers incorporating couscous as ingredient input for prepared meals and packaged food production.
By volume, Households dominate. By formalization pressure, Food Manufacturers face the steepest compliance cost increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Algiers exceeds that in Constantine by roughly one-third, reflecting supermarket density gaps and branded-product penetration differentials across Algeria's northern urban corridor. Coastal metropolitan zones concentrate value capture while interior regions trade on volume and ceremonial consumption patterns. The national food safety authority's durum wheat purity standards apply uniformly, yet enforcement intensity varies by provincial inspectorate capacity.
Algiers
Dual-income households and supermarket chain expansion drive instant couscous adoption in the capital. The national food safety authority maintains its headquarters here, accelerating labeling enforcement timelines for packagers. Industrial mills in the Mitidja plain supply branded products to coastal retail networks.
Oran
Western Algeria's industrial hub hosts mechanized dehydration lines serving private-label supermarket contracts. The central bank's trade finance facilities concentrate here, easing import substitution procurement for semolina processors. Processing infrastructure clustering reduces logistics costs for packaged goods distribution.
Constantine
Eastern urban corridor shows underpenetrated branded couscous presence relative to Algiers saturation. Local market vendors retain dominance for ceremonial traditional couscous preparation. Regional mills face documentation compliance costs as traceability requirements replace informal sourcing arrangements.
Mitidja Plain
Northern agricultural belt semolina processors confront artisan labor scarcity as younger workers migrate to urban service employment. Durum wheat procurement obligations from the trade ministry shape local milling economics. Medium-scale automated lines here serve bulk institutional channels and emerging branded retail.
Tizi Ouzou
Kabylie region maintains traditional hand-rolling expertise for ceremonial export channels commanding diaspora premiums. Mountain geography limits large-scale industrial infrastructure investment. Small-batch producers here face steepest food safety compliance cost increases relative to revenue scale.
Algeria Couscous Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Algeria's couscous market. Automated milling specialists capture supermarket shelf space through consistency and traceability compliance, while vertically integrated wheat processors defend margin positions through procurement control. The competitive terrain splits between heritage artisan brands and industrial scale operators. Capacity expansion and backward integration into durum wheat sourcing represent the dominant competitive moves reshaping supplier relationships.
Among industrial-scale packagers, Groupe LABELLE and Groupe METIDJI exemplify divergent strategic positions. Groupe LABELLE occupies branded retail archetype space through supermarket channel dominance. Groupe METIDJI represents vertical integration archetype with wheat-to-shelf control. Moulins Industriels Du Sebaou anchors the bulk supply tier serving institutional buyers. These three patterns—branded retail, vertical integration, bulk institutional—capture the competitive structure without exhaustively mapping the field.
| Leading Market Players |
|---|
| Groupe LABELLE |
| Groupe METIDJI |
| Groupe Benamor |
| MEXICALI SARL |
| Societe Des Pates Industrielles (SOPI) |
| Groupe SIM |
| Moulins Industriels Du Sebaou (MIS) |
| Societe De Semoulerie Minoterie L'etoile (SOSEMIE) |
| Les Moulins GERBIOR Benhamadi Group |
| Others |
Cost & Logistics Intelligence
Ninety-day durum wheat inventory cycles in Algeria's northern milling belt concentrate procurement leverage among vertically integrated processors while compressing margin buffers for smaller operators dependent on spot semolina markets. This lead-time structure binds pricing power to upstream grain control, rewarding players with trade ministry quota allocations and penalizing informal processors exposed to currency-adjusted import costs.
Pricing Analysis
The customization-premium spread between ceremonial traditional couscous and commodity instant formats spans roughly one-third in Algiers supermarkets versus Constantine local markets. Three-tier pricing structure across premium boxed, standard bagged, and economy bulk levels dominates, with differentiation driven by certification grade for food safety compliance and brand heritage positioning. Cost compression in the bulk institutional tier is intensifying because documentation requirements are replacing informal verbal sourcing arrangements. Household consumers in coastal metropolitan zones show lowest price sensitivity for ceremonial occasions, while interior region local market buyers face acute resistance to whole wheat premiums.
Supply Chain Analysis
Inventory concentration in the Mitidja plain and Oran industrial corridor feeds from French and Canadian durum wheat imports alongside variable domestic harvest quality. The supply chain draws from semolina milling equipment sourced from Italian and Turkish manufacturers, polyethylene packaging resins, and spice inputs from regional Mediterranean suppliers. Single-source vulnerability sits with the trade ministry's centralized quota allocation system for foreign grain procurement. Distribution runs through supermarket chains in Algiers and Oran, wholesale distributors serving institutional buyers, and traditional souk networks penetrating interior ceremonial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as younger urban households split from ceremonial consumption patterns, creating distinct product-positioning niches between convenience-oriented instant formats and heritage traditional channels.
For Market Incumbents: Compound channel control in Constantine and Mitidja plain distribution networks before automated competitors consolidate these corridors. Invest in continuous steam-injection dehydration lines to capture supermarket private-label contracts displacing batch artisan supply. The national food safety authority's tightening traceability requirements threaten smaller processors unable to fund laboratory verification cycles, creating acquisition targets for compliant operators. For New Entrants and Emerging Players: Post-purchase traceability documentation represents a service-layer gap where incumbents under-serve diaspora export channels demanding origin-certified traditional couscous. Target Kabylie region small-batch producers for quality certification partnerships enabling ceremonial channel premiums. Penetrate flavored couscous innovation with spice-infused variants occupying minimal supermarket competition against commodity instant formats. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with under-optimized couscous divisions lacking automated milling investment. Five-to-ten year viability hinges on backward integration into durum wheat sourcing and compliance infrastructure rather than brand equity alone. Monitor trade ministry import quota expansion announcements as inflection signal for margin compression timing among non-integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Durum Wheat Procurement | Trade ministry quota allocations from the central bank defend margin positions against currency-adjusted import volatility. |
| Continuous Steam-Injection Dehydration Deployment | Oran industrial corridor clustering reduces logistics costs for packaged goods distribution to coastal supermarket chains. |
| Food Safety Certification Investment | National food safety authority batch documentation requirements filter informal competitors from formal retail channel access. |
| Flavored Product Line Extension | Spice-infused variants capture niche supermarket positioning with minimal direct competition from commodity instant formats. |
| Constantine Regional Distribution Expansion | Eastern urban corridor underpenetration relative to Algiers saturation offers branded volume growth before competitor consolidation. |
Research Approach
Desk research of customs trade records, central bank procurement policy circulars, and food safety regulatory filings preceded structured interviews with semolina mill operations directors, supermarket category buyers in Algiers and Oran, trade ministry grain allocation officers, and packaging procurement managers at industrial processors. Primary fieldwork with artisan cooperative representatives in Tizi Ouzou and Mitidja plain automated line supervisors validated secondary data on production capacity transitions. Bottom-up volume estimates from facility-level capacity utilization triangulated against top-down consumption surveys from urban household panels.
Variance decomposition across product type, packaging format, distribution channel, and regional urban corridor dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier mix and regional penetration differentials. Modeled inputs incorporated durum wheat harvest quality variability, trade ministry quota adjustment frequency, and food safety enforcement intensity by provincial inspectorate capacity.
Material uncertainties — domestic wheat harvest failure, currency devaluation triggering import cost spikes, and regulatory enforcement acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about trade policy continuity and urbanization pace rather than point-estimate precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Aloe Butter Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Global Truffle Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
United States Tofu Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
White Fungus Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Brahmi Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Acacia Honey Market