
 Sea Moss Market | 2026-2036
Sea Moss Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Moss Market Analytics
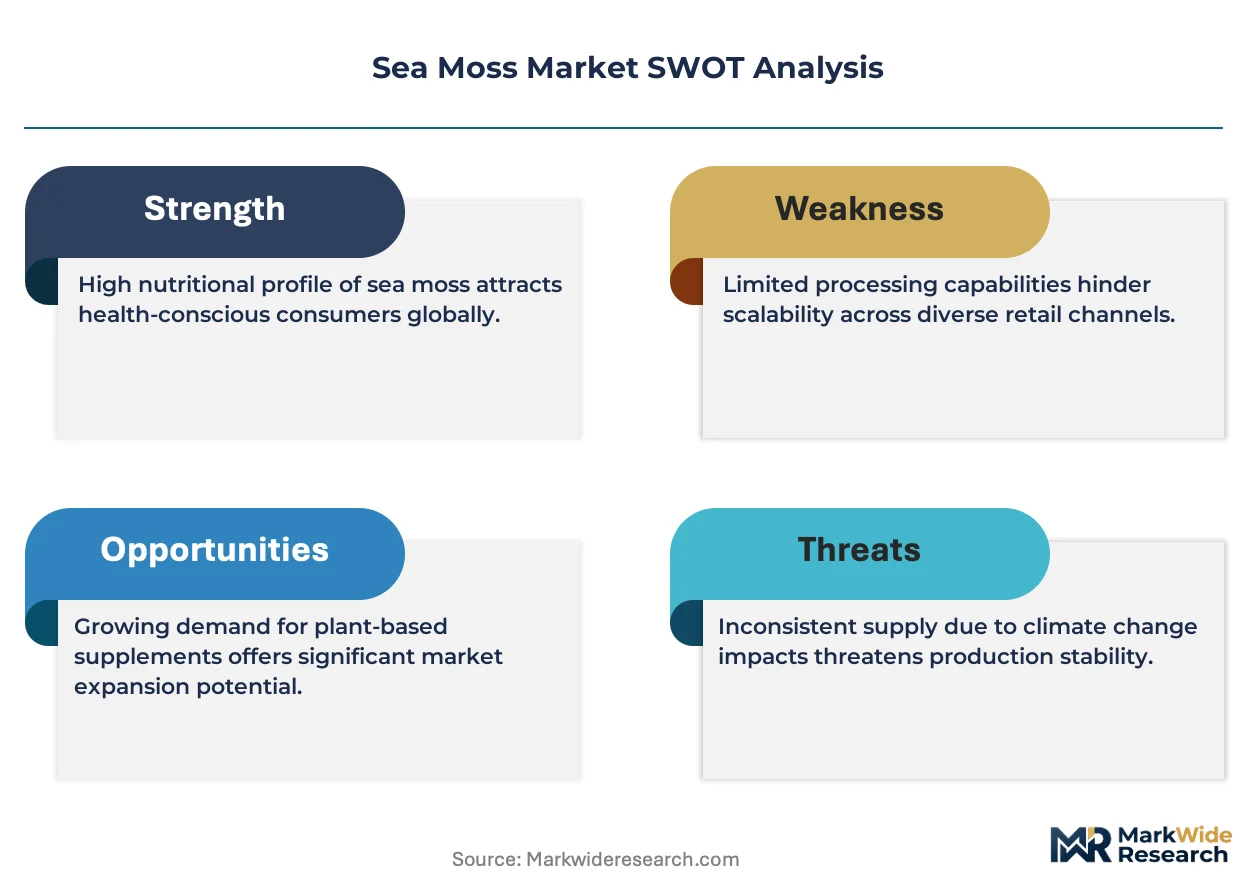
Wildcrafting labor shortages across Caribbean harvesting zones is unwinding raw material availability for processors. TrueSeaMoss leverages direct relationships with St. Lucian harvesters to secure first-pass supply. GlassWing Organics anchors its position through organic certification and cold-chain logistics from farm to gel. Starwest Botanicals competes by dominating bulk powder distribution to North American health stores and formulators.
Sea moss comprises dried marine red algae, primarily Chondrus crispus and Gracilaria species, containing carrageenan polysaccharides that function as gelling agents, emulsifiers, and prebiotic fiber sources. Industrial applications exploit its viscosity profile and mineral density for food stabilization and topical delivery systems. Gel and powder formats lead volume owing to ease of incorporation into beverages and skincare bases, while capsules capture premium margin pools through dosing precision and shelf stability. Dietary supplements represents the fastest-growing application as consumers prioritize iodine, potassium, and collagen-supporting mineral intake.
FDA oversight of dietary supplement Good Manufacturing Practices shapes product quality thresholds for domestic sellers, while EFSA novel food assessments govern European import authorization for non-traditional sea moss species. The USDA National Organic Program and EU Organic Regulation create bifurcated certification demands that filter supplier eligibility. Stakeholders must monitor evolving heavy-metal testing protocols and origin traceability mandates to sustain market access across jurisdictions.
Market Dynamics
Wildcrafting labor shortages across Caribbean harvesting zones are compressing raw material availability, forcing processors to secure direct relationships with coastal communities or absorb volatile spot-market pricing for Gracilaria and Chondrus crispus biomass.
Growth Catalysts
- EFSA Novel Food Assessments:Clearance pathways for non-traditional sea moss species are unlocking European import channels previously blocked by regulatory ambiguity, expanding addressable demand for Caribbean and Atlantic suppliers.
- Direct-to-Consumer Wellness Brands:Functional beverage and skincare formulators are accelerating procurement of raw and processed sea moss as mineral-rich positioning claims attract premium pricing power in crowded supplement aisles.
- Cold-Chain Logistics Infrastructure:Temperature-controlled ocean freight and last-mile gel distribution networks are reducing spoilage rates for fresh-format products, enabling farm-to-gel traceability narratives that command buyer loyalty.
Market Restraints
- Wildcrafting Labor Concentration:Harvesting capacity clusters in St. Lucia, Jamaica, and Grenada, creating geographic single-point-of-failure exposure when tropical weather systems disrupt coastal access.
- FDA Dietary Supplement GMP Compliance:Domestic sellers face escalating quality threshold costs for heavy-metal testing, identity verification, and batch record documentation that squeeze margin structures for smaller importers.
- Carrageenan Substitution:Synthetic hydrocolloids and plant-based alternatives from guar and locust bean gum compete on price stability and supply predictability in food stabilization applications.
Strategic Opportunities
- Australian TGA Pathways:Therapeutic Goods Administration listing procedures for iodine and mineral supplements present underexploited authorization routes for compliant Caribbean exporters seeking Asia-Pacific diversification.
- Biotechnology Cultivation:Land-based tank farming of Gracilaria species is emerging as a controlled-environment alternative that decouples supply from seasonal wild harvest cycles and weather volatility.
- USDA Organic Certification:National Organic Program compliance creates pricing stratification that filters commoditized suppliers and rewards harvesters with documented sustainable practices.
Industry Challenges
- Origin Traceability Systems:Implementing blockchain or DNA barcoding documentation across fragmented coastal harvester networks demands capital investment and technical coordination that many mid-tier processors lack.
- Heavy-Metal Testing Protocols:Evolving FDA and state-level requirements for arsenic, lead, and cadmium screening are extending batch release timelines and increasing laboratory certification costs for gel and powder formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Moss Market |
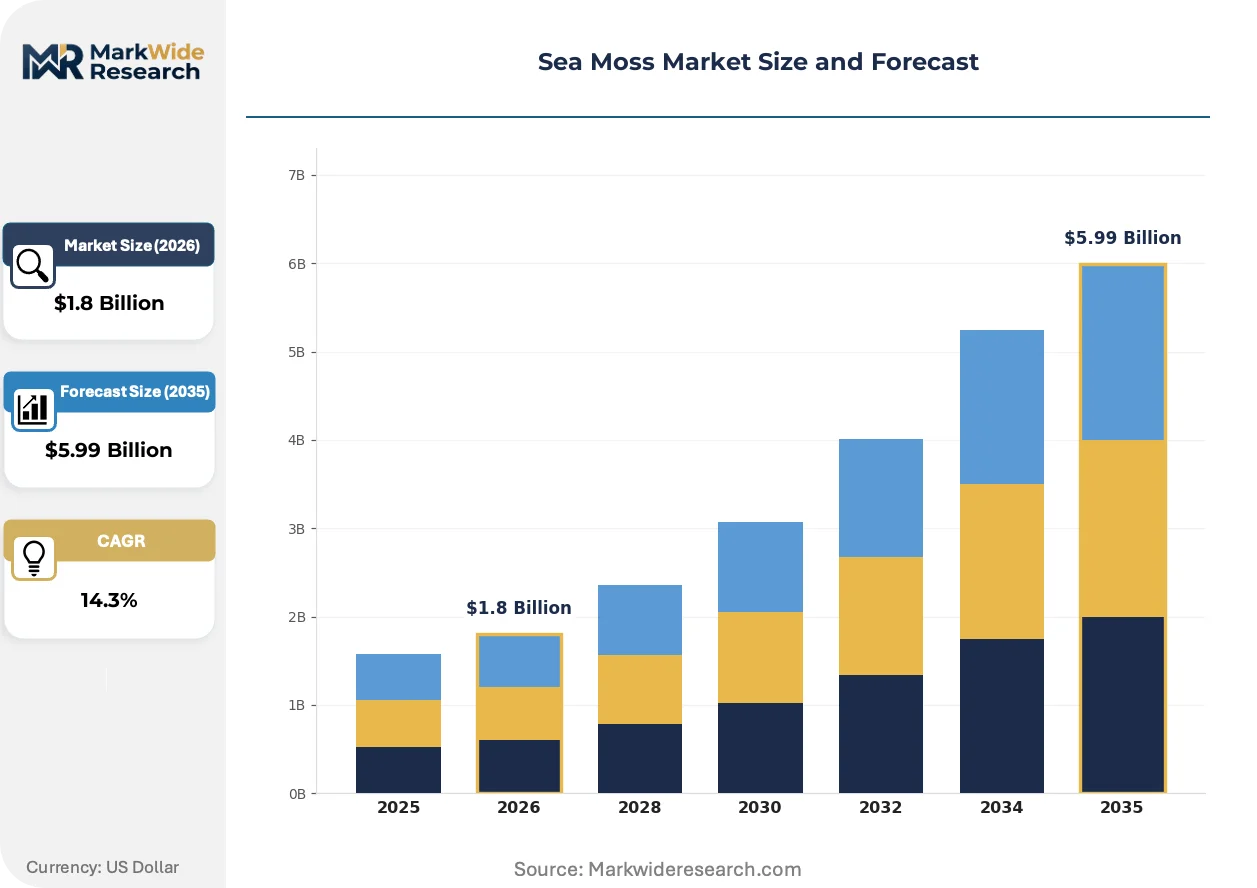
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Powder, Capsules, Gel Application: Food & Beverage, Cosmetics, Pharmaceuticals, Dietary Supplements End User: Households, Food Manufacturers, Cosmetic Companies, Health Stores Distribution Channel: Online Retail, Supermarkets, Natural Food Stores, Pharmacies |
| Companies Covered | Nutriflair, GlassWing Organics, TrueSeaMoss, Starwest Botanicals, Transformation Factory, Bloom Health, Atlantic Gold Sea Moss, Veganlifemoss, Power By Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Moss Market Evolving Landscape
Processing technology and regulatory clarity are converging to reshape competitive positioning across the sea moss value chain, with format innovation and compliance automation emerging as primary differentiation vectors.
Spray-dried microencapsulation technology is supplanting traditional sun-drying and oven-dehydration methods for powder production. Functional beverage formulators in the United States are adopting microencapsulated sea moss at accelerating pace for its solubility and flavor-masking properties. This processing shift is compressing the addressable market for commodity-grade bulk powder while expanding premium tier boundaries for bioavailable ingredient positioning.
EFSA's evolving novel food safety claim scrutiny is tightening import authorization requirements for non-traditional red algae species entering European markets. Industrial consequence includes mandatory pre-market safety assessments and toxicological dossiers that extend time-to-revenue for new suppliers. Caribbean and Atlantic exporters targeting Germany, France, and the Netherlands are responding by consolidating species portfolios around historically consumed varieties with established consumption evidence.
Wellness brands are compressing their supplier bases toward vertically integrated harvesters with captive organic certification and cold-chain assets. The direct-to-consumer channel is displacing wholesale bulk purchasing as the dominant procurement model, with subscription-based gel delivery services capturing recurring revenue pools. This concentration pattern is most visible in United States coastal metropolitan markets where traceability narratives drive purchase decisions.
Sea Moss Market Segmentation
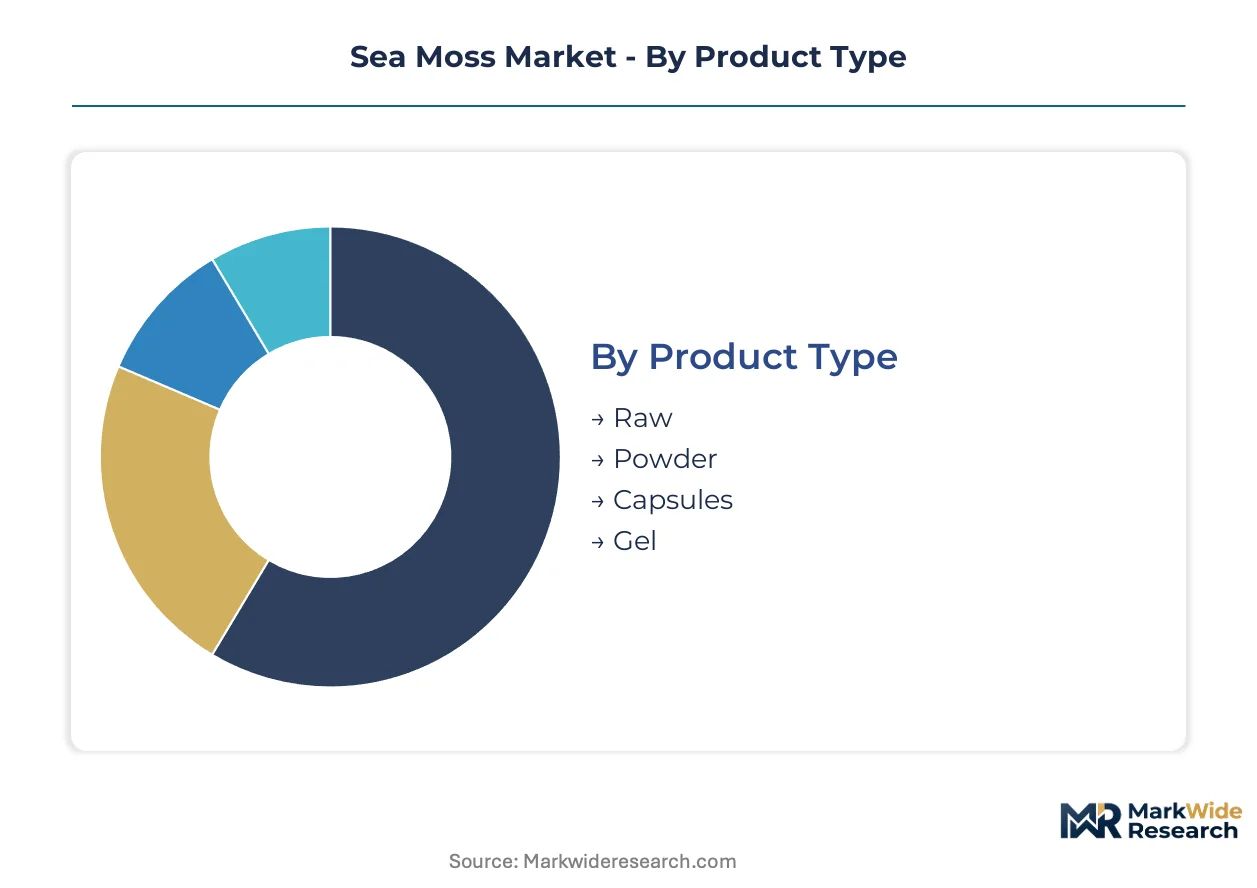
Sea moss segmentation reveals concentrated margin pools in value-added formats and premium channels, with processing intensity and regulatory compliance costs creating tiered profitability structures across product categories.
Product Type:
Margin pools concentrate in processed formats where cold-chain logistics and organic certification create pricing power, while raw biomass remains commoditized by harvest volatility.
- Gel:Fresh-preserved format requiring refrigerated ocean freight and last-mile cold distribution. Direct-to-consumer wellness brands in United States coastal metros absorb premium positioning costs for farm-to-gel traceability narratives that command subscription loyalty.
- Powder:Spray-dried microencapsulation technology delivers solubility and flavor-masking for functional beverage formulators. FDA dietary supplement GMP compliance and heavy-metal testing protocols extend batch release timelines, filtering smaller processors from premium tier access.
- Capsules:Dosing precision and shelf stability capture premium margin pools through convenience positioning in health store channels.
- Raw:Dried marine algae biomass sold to processors and formulators, exposed to St. Lucian and Jamaican wildcrafting labor shortages and tropical weather disruption.
Gel holds installed capacity. Powder is rotating up the share rankings.
Application:
Application mix reflects divergent regulatory exposure, with pharmaceutical and supplement channels facing escalating compliance costs while food stabilization competes on price.
- Dietary Supplements:Iodine, potassium, and collagen-supporting mineral claims attract premium pricing in crowded supplement aisles. EFSA novel food assessments and FDA GMP scrutiny tighten quality thresholds, extending time-to-revenue for new Caribbean suppliers seeking European and United States market entry.
- Food & Beverage:Carrageenan polysaccharides function as gelling agents and emulsifiers. Synthetic hydrocolloids and plant-based alternatives from guar and locust bean gum compete on supply predictability, compressing margin structures for commodity-grade sea moss stabilization.
- Cosmetics:Topical delivery systems exploit mineral density and viscosity profiles for skincare bases.
- Pharmaceuticals:Therapeutic positioning requires TGA, FDA, or EMA pathway compliance with toxicological dossier demands.
Dietary Supplements is climbing the fastest. Food & Beverage maintains volume dominance.
End User:
Customer concentration patterns show direct-to-consumer displacement of wholesale bulk purchasing, with traceability requirements reshaping procurement relationships.
- Households:Subscription-based gel delivery services capture recurring revenue through traceability-driven purchase decisions in United States coastal metropolitan markets.
- Health Stores:Independent retailers and natural product chains stock powder and capsule formats, prioritizing USDA National Organic Program certification and batch documentation.
- Food Manufacturers:Industrial buyers source bulk powder for beverage stabilization, exposed to carrageenan substitution risk from synthetic alternatives.
- Cosmetic Companies:Formulators demand consistent viscosity profiles and heavy-metal screening documentation for topical product lines.
Households is expanding most quickly. Health Stores defend established shelf positions.
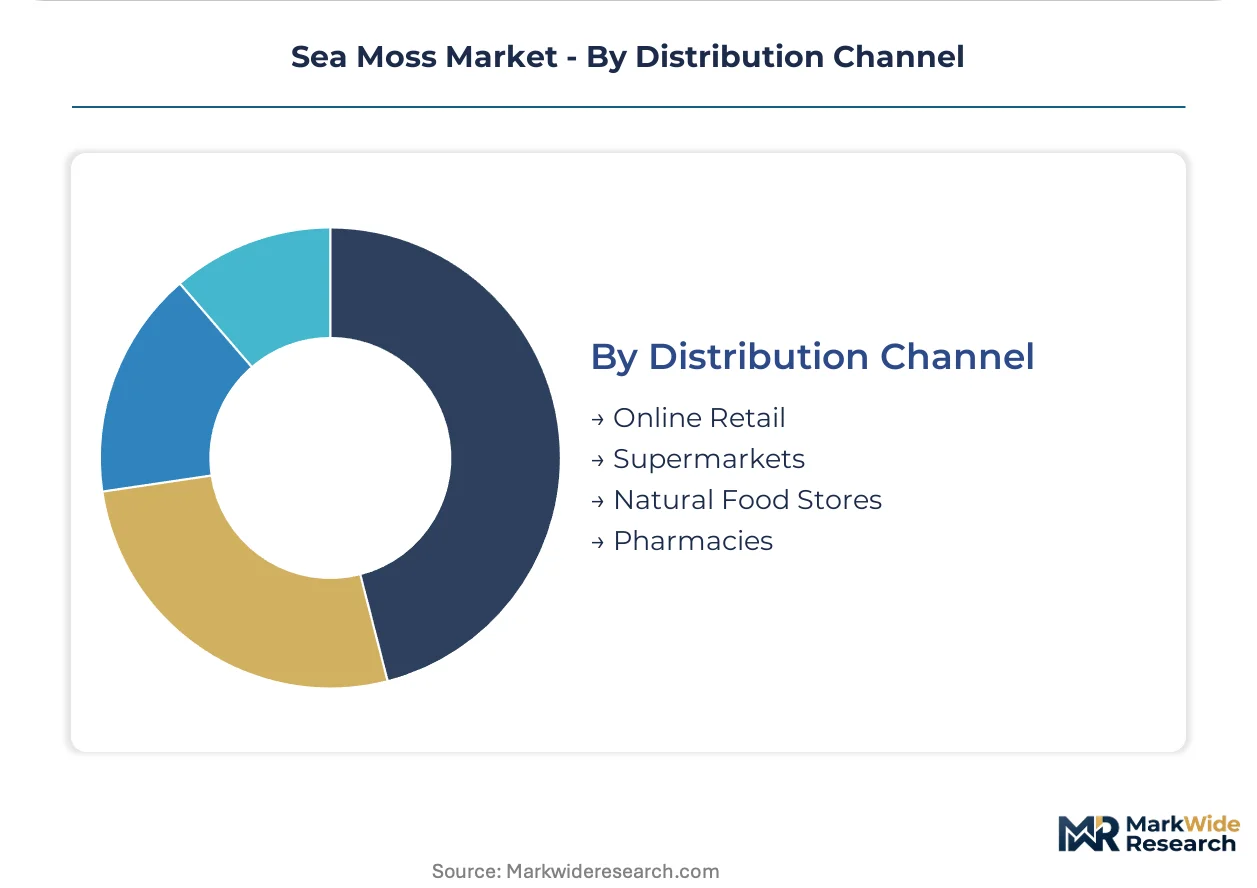
Distribution Channel:
Channel economics favor vertically integrated harvesters with captive cold-chain assets, compressing traditional wholesale intermediaries.
- Online Retail:Direct-to-consumer wellness brands leverage subscription mechanics and traceability narratives, displacing bulk wholesale as the dominant procurement model.
- Natural Food Stores:Independent retailers filter suppliers through organic certification and origin documentation requirements, rewarding harvesters with sustainable practice verification.
- Supermarkets:Mass retail penetration remains limited by refrigerated distribution costs and short shelf-life constraints for gel formats.
- Pharmacies:Therapeutic supplement positioning requires regulatory pathway completion, constraining SKU breadth for Caribbean exporters.
Online Retail is gaining share fastest. Natural Food Stores hold established regional density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dietary supplement GMP compliance anchors the United States as the dominant geography, with EFSA novel food assessments shaping European import authorization and TGA pathways opening Asia-Pacific diversification for Caribbean exporters.
United States
Direct-to-consumer wellness brands in coastal metropolitan markets drive gel format demand through subscription mechanics and traceability narratives. FDA heavy-metal testing protocols and batch documentation requirements filter smaller importers from premium tier access. Miami and Los Angeles anchor cold-chain distribution networks for Caribbean-sourced fresh product.
Germany
Functional beverage formulators prioritize spray-dried microencapsulated powder for solubility and flavor-masking applications. EFSA novel food safety assessments mandate toxicological dossiers for non-traditional red algae species, extending authorization timelines. Hamburg and Rotterdam serve as consolidation points for Atlantic-sourced biomass entering continental distribution.
United Kingdom
Health store channels filter suppliers through organic certification and origin documentation requirements. The UK Food Standards Agency enforces evolving heavy-metal screening protocols for iodine-rich supplement positioning. London's direct-to-consumer wellness startup cluster compresses procurement toward vertically integrated Caribbean harvesters.
Canada
Natural product retailers prioritize USDA National Organic Program equivalency and cold-chain integrity for gel format shelf placement. Health Canada supplement regulations govern therapeutic mineral claims and iodine dosage thresholds. Toronto and Vancouver anchor subscription-based delivery service expansion for traceability-driven household demand.
Australia
TGA listing procedures for iodine and mineral supplements present underexploited authorization routes for compliant Caribbean exporters. Therapeutic positioning requirements constrain SKU breadth but reward dossier-complete suppliers with pharmacy channel access. Sydney and Melbourne concentrate wellness brand procurement offices seeking Asia-Pacific diversification.
Sea Moss Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into St. Lucian and Jamaican harvesting networks separating premium-positioned gel suppliers from commodity bulk powder distributors. Three archetypes dominate: vertically integrated harvester-processors with captive organic certification, specialist bulk distributors serving health store and formulator channels, and direct-to-consumer wellness brands with subscription mechanics. Competitive moves concentrate on cold-chain asset acquisition and organic certification consolidation.
Within the integrated harvester-processor tier, TrueSeaMoss exemplifies direct coastal community relationships securing first-pass supply, while GlassWing Organics occupies a position anchored through organic certification and temperature-controlled logistics. Starwest Botanicals represents the bulk distribution archetype, sitting within North American health store and formulator supply chains. These three company structures illustrate the bifurcation between traceability-premium gel formats and commoditized powder distribution.
| Leading Market Players |
|---|
| Nutriflair |
| GlassWing Organics |
| TrueSeaMoss |
| Starwest Botanicals |
| Transformation Factory |
| Bloom Health |
| Atlantic Gold Sea Moss |
| Veganlifemoss |
| Power By Naturals |
| Others |
Value Network & Pricing Analysis
Harvesting capacity utilization across St. Lucian and Jamaican coastal zones shapes both supply concentration and price floors for Caribbean-sourced biomass. Scale economies in cold-chain logistics and organic certification create tiered pricing power that filters commoditized suppliers from premium-positioned gel producers.
Pricing Analysis
Caribbean-to-United States price spreads for raw Gracilaria biomass widen during tropical storm seasons when coastal access disruptions compress spot-market availability. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic-certified gel from conventional powder and unprocessed dried algae. Pricing pressure stems from synthetic hydrocolloid substitution in food stabilization applications, eroding commodity-grade sea moss margins. Food manufacturers exhibit highest price sensitivity due to carrageenan alternative availability, while direct-to-consumer wellness brands absorb premium positioning costs for traceability narratives.
Supply Chain Analysis
St. Lucian port infrastructure and Miami cold-chain terminals constitute critical chokepoints for fresh-format gel distribution into United States coastal metropolitan markets. Supply concentrates in St. Lucia, Jamaica, and Grenada for wildcrafted Chondrus crispus and Gracilaria species, drawing from seasonal labor pools and weather-dependent harvesting cycles. Single-source vulnerability runs through concentrated Caribbean wildcrafting zones exposed to hurricane disruption. Distribution runs through vertically integrated harvester-processors with captive organic certification and temperature-controlled logistics, compressing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-pass supply relationships with St. Lucian harvesting communities represent scarce, non-replicable assets that separate premium gel suppliers from commodity distributors. Cold-chain infrastructure ownership and EFSA dossier completion capabilities constitute additional capability gaps that shape competitive outcomes.
For Market Incumbents: Consolidate direct coastal community relationships before tropical weather disruptions accelerate spot-market price volatility. Acquire refrigerated ocean freight capacity to secure farm-to-gel traceability narratives that command subscription loyalty. Invest in EFSA toxicological dossier completion to unlock European import channels previously blocked by novel food regulatory ambiguity. For New Entrants and Emerging Players: Lead with biotechnology cultivation of Gracilaria species in land-based tank systems to decouple supply from seasonal wild harvest cycles and geographic concentration risk. Target Australian TGA listing pathways for iodine and mineral supplements as underexploited authorization routes with limited incumbent competition. Deploy direct-to-consumer subscription mechanics with traceability storytelling to bypass wholesale channel barriers. For Investors and Strategic Acquirers: Caribbean harvester-processors with captive USDA Organic certification and verified St. Lucian coastal relationships represent priority acquisition targets. Long-term viability hinges on supply decoupling from wildcrafting labor shortages through controlled-environment cultivation or backward integration into tank farming operations. Watch EFSA novel food assessment clearance velocity as inflection indicator for European market expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Acquisition | Temperature-controlled logistics from St. Lucian ports to United States coastal metros reduces spoilage and enables subscription gel delivery. |
| USDA Organic Certification Investment | National Organic Program compliance filters commoditized suppliers and commands pricing premiums in health store channels. |
| EFSA Dossier Completion | Novel food safety assessments unlock German, French, and Dutch import authorization for historically consumed red algae species. |
| Biotechnology Cultivation Scale-Up | Land-based tank farming of Gracilaria decouples supply from Caribbean wildcrafting labor shortages and weather volatility. |
| TGA Listing Pathway Execution | Therapeutic Goods Administration authorization for iodine supplements opens pharmacy channel access in Sydney and Melbourne markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Caribbean harvesting cooperative leaders, United States direct-to-consumer wellness brand procurement executives, cold-chain logistics providers, and EFSA regulatory consultants. Secondary validation drew from FDA dietary supplement GMP guidance documents, EFSA novel food assessment registers, USDA National Organic Program certification databases, and Caribbean export customs records. Bottom-up volume modeling triangulated against top-down addressable market sizing across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by product format, application channel, end-user archetype, and distribution pathway, with additional granularity on organic certification status and cold-chain requirement intensity. CAGRs were derived from trend extrapolation of procurement velocity patterns and regulatory authorization timelines. Forecast inputs incorporated wildcrafting labor availability indices, tropical storm frequency assumptions, and EFSA assessment queue velocity.
Forecasts assume regulatory continuity in FDA dietary supplement oversight and EFSA novel food regimes; material policy shifts in heavy-metal testing protocols or novel species authorization would require re-modeling. Practitioners should keep alternative scenarios live as biotechnology cultivation cost curves and synthetic hydrocolloid substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Halal Products Market
Specialty Foods
Brahmi Market
Specialty Foods
Curculin Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Natural Honey Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Aloe Butter Market