
 Low Calorie Oatmeal Market | 2026-2036
Low Calorie Oatmeal Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Oatmeal Market Analytics
The low calorie oatmeal category is restructuring around a widening split between premium functional formulations and commodity rolled oats. The Quaker Oats Company leverages its milling infrastructure to sustain volume leadership in conventional retail channels. Bob's Red Mill Natural Foods, Inc. differentiates through organic certification and heritage grain sourcing that commands price premiums in natural grocery. Purely Elizabeth anchors the superfood-infused tier with probiotic and collagen-enhanced SKUs that target wellness-oriented millennials.
Low calorie oatmeal denotes oat-based breakfast products formulated to deliver fewer than 150 calories per standard serving, typically achieved through controlled portion sizing, reduced added sweeteners, and modified starch profiles that preserve mouthfeel without caloric density. Manufacturers employ steam-flaking or extrusion processes to modify beta-glucan solubility, which governs glycemic response and satiety signaling. Instant oatmeal dominates volume throughput due to microwave-ready convenience, though steel-cut oats capture disproportionate margin pools through perceived authenticity and slower digestion kinetics. Health-Conscious Consumers represent the most penetrated end-user cohort, while Fitness Enthusiasts drive fastest growth through demand for macro-balanced, high-protein variants.
The FDA governs calorie claim substantiation and fiber quantification methodology under Nutrition Labeling and Education Act provisions, while USDA Organic certification shapes ingredient sourcing requirements for premium positioning. FSSAI in India and EFSA in Europe enforce parallel standards on health claim validation and contaminant thresholds that determine export eligibility for North American suppliers. Stakeholders must monitor evolving definitions of dietary fiber across jurisdictions, as regulatory reclassification of isolated fibers could force reformulation of products currently marketed as high-fiber, low-calorie alternatives.
Market Dynamics
Protein fortification is reconfiguring competitive positioning in low calorie oatmeal, as Fitness Enthusiasts pull manufacturers toward macro-balanced formulations that command shelf space away from legacy instant varieties. This demand rotation is compressing margins on conventional SKUs while rewarding R&D investment in functional ingredients.
Growth Catalysts
- FDA Nutrition Facts Revisions:Updated labeling requirements for added sugars and fiber claims are accelerating product reformulation among U.S. manufacturers seeking clean-label positioning.
- Overnight Oats Format Expansion:Ready-to-eat refrigerated formats are capturing premium placement in health food retail channels, particularly in United States urban markets.
- Beta-Glucan Solubility Engineering:Steam-flaking and extrusion process advances are improving glycemic response profiles, enabling satiety claims that resonate with Health-Conscious Consumers.
Market Restraints
- Oat Input Cost Volatility:Weather-driven supply fluctuations in North American grain belts create margin pressure for processors dependent on contracted milling volumes.
- Heritage Grain Supply Concentration:Limited organic certified acreage constrains expansion plans for premium tier manufacturers sourcing heritage cultivars.
- Isolated Fiber Regulatory Reclassification:Evolving FDA definitions of dietary fiber threaten reformulation costs for products currently marketed as high-fiber alternatives.
Strategic Opportunities
- Collagen and Probiotic Convergence:Superfood-infused SKUs targeting wellness-oriented millennials represent underexploited white space in functional breakfast categories.
- Steel-Cut Margin Premium Capture:Slower digestion kinetics and perceived authenticity support disproportionate pricing power in specialty retail channels.
- EFSA Health Claim Pathways:European regulatory frameworks for beta-glucan cholesterol claims offer export expansion avenues for North American suppliers meeting contaminant thresholds.
Industry Challenges
- Extrusion Technician Scarcity:Specialized knowledge in steam-flaking parameter optimization limits production scale-up for emerging manufacturers.
- USDA Organic Certification Timelines:Multi-year conversion requirements for heritage grain sourcing constrain speed-to-market for premium positioning.
- Legacy Equipment Retrofit Costs:Microwave-ready format lines require capital-intensive reconfiguration to accommodate probiotic-sensitive processing conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Oatmeal Market |
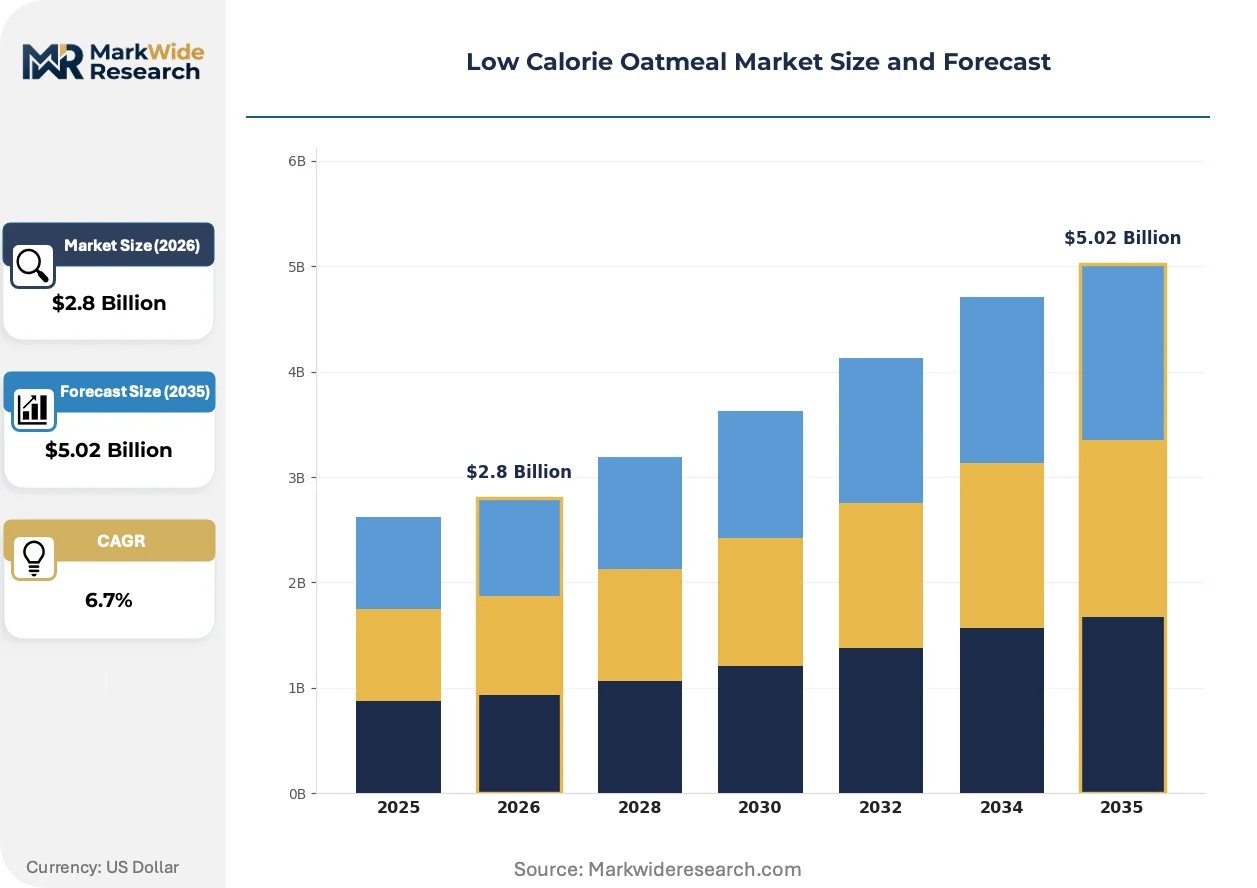
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oatmeal, Steel-Cut Oats, Rolled Oats, Flavored Oatmeal End User: Health-Conscious Consumers, Fitness Enthusiasts, Weight Watchers, Families Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Packaging Type: Single-Serve Packets, Bulk Packaging, Boxed, Pouches |
| Companies Covered | The Quaker Oats Company, Nestlé S.A., Kellogg Company, General Mills, Inc., Bob’s Red Mill Natural Foods, Inc., Nature’s Path Foods, Inc., Purely Elizabeth, Kodiak Cakes, Mush, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Oatmeal Market Evolving Landscape
Functional ingredient integration is compressing the boundary between food and nutraceuticals in low calorie oatmeal, as manufacturers engineer products that deliver measurable physiological outcomes beyond basic nutrition.
Protein fortification technology is unifying macronutrient optimization with convenience formats. Fitness Enthusiasts are adopting high-protein instant varieties at accelerating rates. This convergence is enabling premium pricing tiers that compress commodity oatmeal margins in conventional retail.
EFSA beta-glucan health claim validation standards are reshaping European export requirements for North American suppliers. Manufacturers must demonstrate soluble fiber quantification methodology compliance to access continental shelf space. Steel-cut and overnight oat categories face the steepest compliance adaptation costs due to processing variability.
Health food retail channel consolidation is displacing traditional grocery as the primary discovery environment for premium oatmeal. Wellness-oriented millennials are sourcing superfood-infused SKUs through natural grocery formats that emphasize ingredient storytelling. United States coastal metropolitan markets exhibit the most pronounced channel migration, with refrigerated ready-to-eat formats commanding disproportionate placement investment.
Low Calorie Oatmeal Market Segmentation
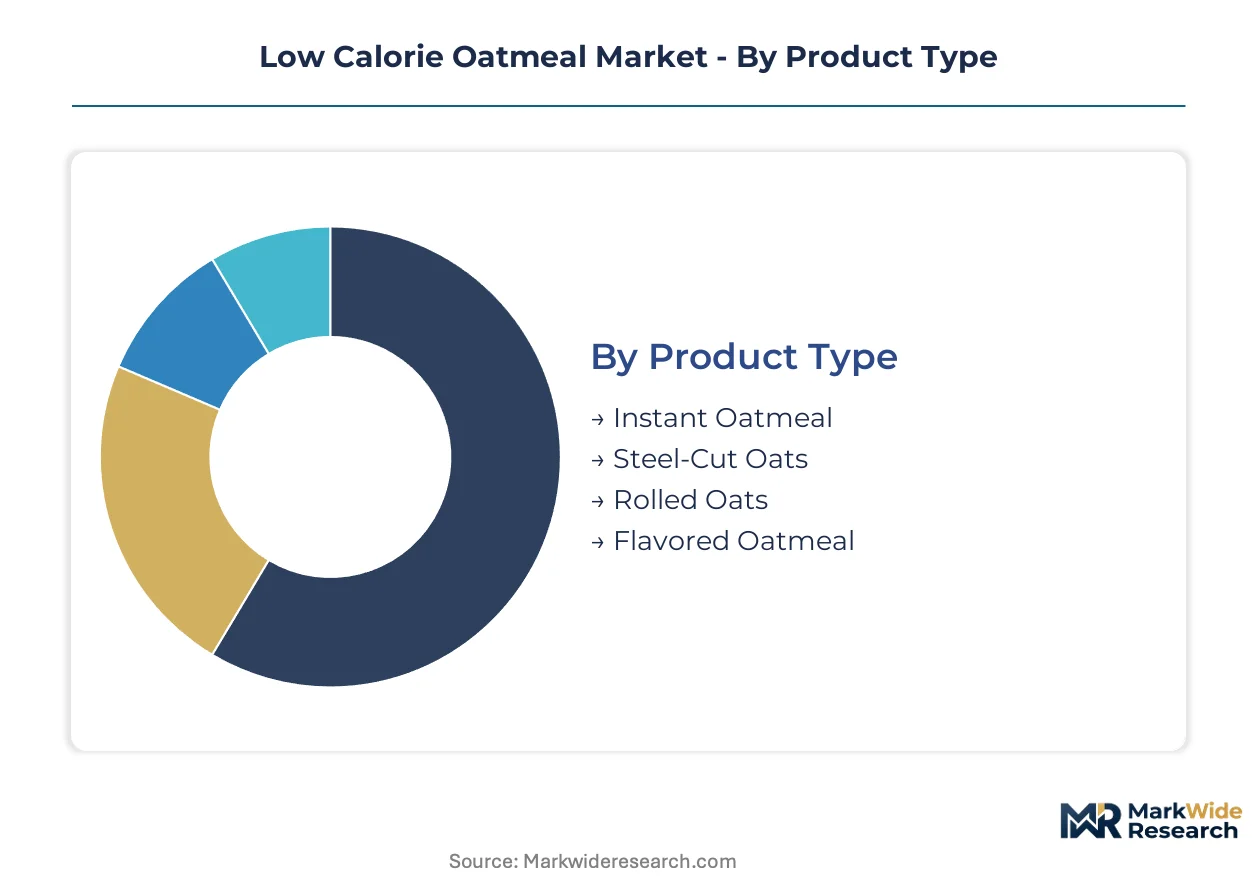
Low calorie oatmeal manufacturers calibrate portfolio depth across four distinct segmentation axes. Product format determines processing capital requirements and margin architecture. End-user targeting shapes functional ingredient investments and channel placement strategies.
Product Type:
Steam-flaking and extrusion integration depth separates microwave-ready formats from minimally processed alternatives requiring extended preparation.
- Instant Oatmeal:Pre-cooked and dried flakes rehydrate in under two minutes via microwave or boiling water. Health-Conscious Consumers in United States urban markets pull this segment through convenience-driven repeat purchase patterns.
- Steel-Cut Oats:Groats chopped into pieces rather than rolled preserve intact beta-glucan structure and slower digestion kinetics. Specialty retail channels in coastal metropolitan areas command premium pricing for perceived authenticity and extended satiety signaling.
- Rolled Oats:Steam-softened groats flattened between rollers offer intermediate preparation time and versatile application across hot cereal and overnight oat formats.
- Flavored Oatmeal:Pre-sweetened and fruit-infused varieties incorporate controlled-calorie sweetener systems and natural flavor masking for palatability without caloric density escalation.
Volume placements concentrate in Instant Oatmeal; the faster expansion belongs to Steel-Cut Oats.
End User:
Macro-balancing requirements and ingredient transparency expectations diverge sharply across wellness-motivated cohorts versus household efficiency seekers.
- Health-Conscious Consumers:This penetrated cohort prioritizes clean-label positioning and organic certification in purchase decisions. FDA fiber claim substantiation and added sugar disclosure transparency govern brand switching behavior.
- Fitness Enthusiasts:Protein-fortified formulations with 10-15g protein per serving attract this expanding segment through macro-tracking alignment and post-workout recovery positioning.
- Weight Watchers:Calorie-controlled portion sizing and satiety-engineered starch profiles support adherence to structured dietary protocols.
- Families:Multi-serve packaging efficiency and child-palatable flavor systems drive purchase concentration in conventional retail channels.
Health-Conscious Consumers anchor current volume; Fitness Enthusiasts are climbing the fastest.
Distribution Channel:
Channel selection determines margin capture versus volume throughput tradeoffs, with refrigerated format compatibility constraining placement options.
- Supermarkets:Conventional grocery dominates total unit movement through promotional velocity and household stock-up behavior.
- Online Retailers:Subscription models and bulk purchasing patterns concentrate in this channel for pantry-stocking efficiency.
- Health Food Stores:Natural grocery formats command disproportionate placement investment for superfood-infused SKUs targeting wellness-oriented millennials.
- Convenience Stores:Single-serve packet formats align with grab-and-go consumption occasions in transit-oriented locations.
Supermarkets retain volume leadership; Health Food Stores show the steepest expansion trajectory.
Packaging Type:
Packaging configuration directly determines portion control precision, shelf stability engineering, and sustainability credentialing.
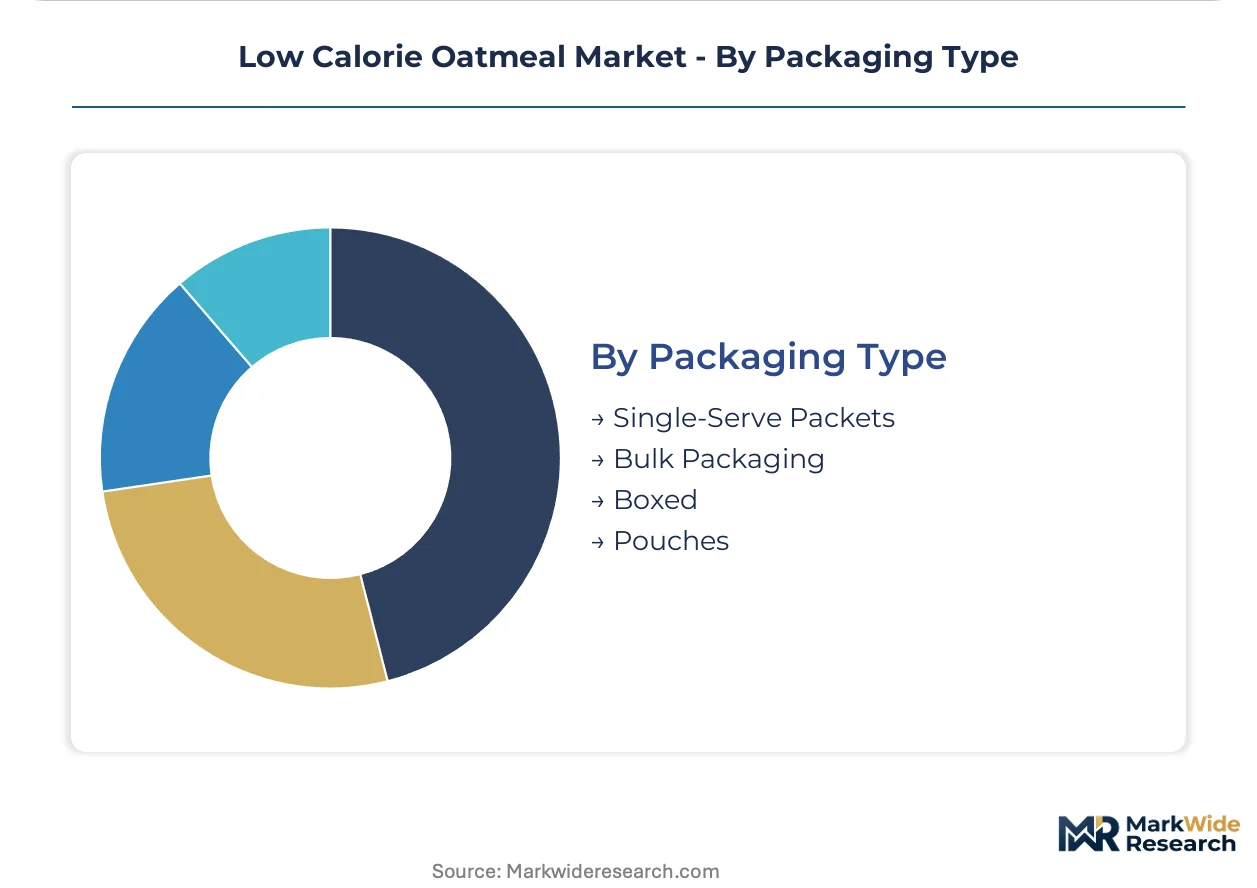
- Single-Serve Packets:Pre-portioned sachets eliminate measuring error and support calorie claim precision for Weight Watchers adherence.
- Bulk Packaging:Food-service and high-volume household applications favor this format for unit economics and waste reduction.
- Boxed:Multi-pouch retail presentations dominate conventional shelf placement with stackable logistics efficiency.
- Pouches:Flexible film formats reduce material weight and support resealability for overnight oat preparation.
Boxed configurations hold volume concentration; Pouches are gaining share fastest through sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American oatmeal processing capacity through its rail-linked grain handling infrastructure and refrigerated distribution corridors serving overnight oat brands. The metropolitan area's food manufacturing density supports rapid format innovation from legacy milling operations to ready-to-eat startups.
United States
Fitness Enthusiasts in coastal metropolitan markets pull protein-fortified SKUs through health food retail channels. FDA updated Nutrition Facts labeling requirements for added sugars and fiber claims are accelerating reformulation timelines among domestic manufacturers. The Pacific Northwest corridor from Seattle to Portland concentrates organic certified milling capacity for heritage grain sourcing.
Germany
EFSA beta-glucan cholesterol reduction health claims are reshaping product positioning for export-oriented suppliers seeking continental shelf access. The country's national food safety regulator enforces strict contaminant thresholds on oat imports from non-EU origins. Bavaria's food technology clusters around Munich drive extrusion process optimization for glycemic response engineering.
United Kingdom
Overnight oats format adoption concentrates in London and Southeast England urban corridors where refrigerated ready-to-eat placement commands premium velocity. The Food Standards Agency governs fiber quantification methodology parallel to evolving EU frameworks. Scotland's oat cultivation belt supplies heritage cultivar inputs for organic certified product lines.
India
FSSAI enforcement of health claim validation and contaminant thresholds determines import eligibility for North American suppliers targeting urban wellness consumers. The regulator's evolving dietary fiber definitions mirror FDA trajectory with jurisdiction-specific timing. Maharashtra's Mumbai-Pune industrial corridor hosts domestic oatmeal processing scale-up for instant format localization.
Canada
Health Canada and PMRA joint oversight of novel food ingredients and pesticide residue limits shapes cross-border supply chain compliance for U.S. exporters. The Prairie Provinces oat cultivation concentration provides raw material proximity for integrated milling operations. Toronto's food manufacturing density supports overnight oat format innovation targeting U.S. export markets.
Low Calorie Oatmeal Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the low calorie oatmeal category, with integrated millers owning steam-flaking infrastructure while specialty brands outsource manufacturing to co-packers. The vendor base stratifies into three tiers: multinational CPG conglomerates with diversified breakfast portfolios, mid-scale natural food specialists with organic certification depth, and emerging functional food startups with superfood-infused positioning. Consolidation pressure intensifies as protein fortification R&D costs favor scaled players, while private label expansion compresses margin pools in conventional retail channels.
Within the heritage grain specialist tier, Bob's Red Mill Natural Foods, Inc. exemplifies organic certification and heritage sourcing archetypes that command price premiums in natural grocery formats. Purely Elizabeth anchors the superfood-infused vector through probiotic and collagen-enhanced SKUs targeting wellness-oriented millennials. The Quaker Oats Company occupies the scale-driven position leveraging milling infrastructure for volume leadership in conventional retail channels.
| Leading Market Players |
|---|
| The Quaker Oats Company |
| Nestlé S.A. |
| Kellogg Company |
| General Mills, Inc. |
| Bob's Red Mill Natural Foods, Inc. |
| Nature's Path Foods, Inc. |
| Purely Elizabeth |
| Kodiak Cakes |
| Mush |
| Others |
Value Network & Pricing Analysis
USDA Organic certification timelines for heritage grain sourcing gate both qualified supply and premium-tier pricing access, compressing margin pools for manufacturers unable to secure certified acreage while rewarding integrated millers with captive organic supply chains.
Pricing Analysis
Satiety-engineered starch profiles anchor value-based pricing tiers, with beta-glucan solubility metrics commanding premiums from Health-Conscious Consumers. Three-tier pricing structure across premium, standard, and economy levels separates collagen-infused superfood SKUs from conventional instant varieties and private-label commodity oats. Pricing pressure stems from protein fortification R&D costs favoring scaled players over emerging entrants. Fitness Enthusiasts exhibit lowest price sensitivity due to macro-tracking alignment, while Families in conventional retail show highest sensitivity to promotional velocity.
Supply Chain Analysis
Extrusion technician scarcity in Chicago and Minneapolis-St. Paul manufacturing corridors constrains production scale-up for steam-flaking parameter optimization. North American oat cultivation concentrates in the Prairie Provinces of Canada and the northern United States grain belt, with heritage cultivar sourcing drawing from limited organic certified acreage. Single-source vulnerability in heritage grain supply threatens reformulation timelines for premium tier manufacturers. Distribution runs through rail-linked grain handling infrastructure anchored in Chicago, with refrigerated corridors serving overnight oat brands in coastal metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around protein fortification R&D cost barriers that force sub-scale natural food specialists toward acquisition or private-label servitude.
For Market Incumbents: Anchor milling infrastructure advantages through backward integration into heritage grain sourcing, securing multi-year organic certification timelines before competitor lock-up. Acquire extrusion process optimization capabilities to defend against functional food startups encroaching on superfood-infused positioning. Channel control in health food retail formats remains critical as wellness-oriented millennials displace traditional grocery discovery. For New Entrants and Emerging Players: Weight Watchers adherence protocols represent an underserved buyer archetype with unmet demand for calorie-precision portion engineering beyond generic single-serve packets. Target steel-cut overnight oat preparation kits through subscription models emphasizing satiety signaling transparency. Go-to-market through natural grocery formats that reward ingredient storytelling over promotional velocity. For Investors and Strategic Acquirers: EFSA beta-glucan health claim validation announcements are the leading indicator that European export pathways have opened for North American suppliers meeting contaminant thresholds. Five-to-ten year viability favors vertically integrated millers with organic certification depth over asset-light brand designers dependent on co-packer capacity. Watch for FDA isolated fiber reclassification proposals as the signal forcing portfolio-wide reformulation investment.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Supply Agreement | Multi-year organic certified acreage contracts secure premium-tier raw material access against competitor lock-up. |
| EFSA Health Claim Compliance Investment | Beta-glucan cholesterol reduction validation unlocks continental European shelf space for export-oriented suppliers. |
| Extrusion Process Optimization Center | Steam-flaking parameter expertise concentrates production scale-up capability in scarce technical talent pools. |
| Direct-to-Consumer Subscription Launch | Overnight oat preparation kits bypass retail margin compression through recurring revenue relationships. |
| Collagen-Probiotic SKU Extension | Superfood-infused positioning captures wellness-oriented millennials migrating to health food retail channels. |
Research Methodology
USDA organic certification databases, FDA Nutrition Facts labeling guidance documents, and EFSA health claim submission records formed the secondary backbone for regulatory pathway mapping. Primary interviews with extrusion process engineers, health food retail category buyers, and heritage grain procurement managers at integrated millers combined with secondary validation from Nielsen retail audit data and customs trade records. Bottom-up SKU-level volume builds and top-down category spend estimates underwent triangulation across the analysis window.
Historical trendline analysis of instant oatmeal volume trajectories and steel-cut oat premium capture rates informed the projection framework. Segmentation modeling spanned product format, end-user macro-balancing requirements, distribution channel compatibility, and packaging sustainability credentials. CAGRs derived from weighted average of segment growth rates adjusted for protein fortification penetration curves and overnight oats format adoption velocity. Forecast inputs incorporated oat input cost volatility scenarios and regulatory reclassification risk timelines.
Revisions become necessary when FDA isolated fiber definition proposals advance to final rulemaking, EFSA contaminant threshold enforcement intensifies, or Prairie Provinces weather events disrupt heritage grain supply. Forecasts reflect assumptions around organic certification conversion timelines and health food retail channel consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Tahini Market
Specialty Foods
Brahmi Market
Specialty Foods
Halal Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Mexico Guacamole Market