
 Global Honey Market | 2026-2036
Global Honey Market Size, Share, and Industry Trends Forecast 2026-2036
Global Honey Market Analysis
Multi-source apiary contracting is restructuring supply security for large honey packers. Bee Maid Honey Limited leverages cooperative beekeeper networks across Canadian prairie provinces to sustain volume consistency through seasonal variability. Dabur India Ltd. anchors its procurement through backward integration into tribal and rural apiary clusters in Madhya Pradesh and Rajasthan. Comvita Limited differentiates via vertical control over Manuka honey sourcing from New Zealand's North Island.
Honey is a viscous, enzymatically active sweet substance produced by Apis mellifera from floral nectar, containing glucose, fructose, pollen traces, and hydrogen peroxide-generating compounds, with moisture content typically below 18% to prevent fermentation; it serves as a natural humectant, antimicrobial agent, and clean-label sweetener across food, therapeutic, and cosmetic applications. Organic honey commands premium shelf positioning as retailers respond to EFSA-influenced pesticide residue thresholds, while Manuka honey occupies the highest margin tier due to methylglyoxal grading systems and pharmacy-channel certification. Raw honey competes aggressively in direct-to-consumer channels where glass jar packaging signals authenticity and traceability to specific floral sources.
FDA enforces identity standards under 21 CFR 101.80 for honey labeling and adulteration detection, while EU REACH and residue monitoring programs shape import acceptance criteria for non-European suppliers. China's SAMR and GB standards govern domestic honey purity testing and genetically modified organism screening, creating compliance layers for cross-border trade. Stakeholders must monitor evolving pollinator health regulations and carbon footprint disclosure requirements as these frameworks reshape apiary economics and origin verification protocols.
Market Dynamics
EU Green Deal sustainability requirements and F-Gas Regulation climate protocols are tightening traceability standards across member states, forcing packers to restructure apiary contracting and authentication systems.
Growth Catalysts
- Clean-label sweetener substitution:Food manufacturers in Germany and France are reformulating processed products to replace high-fructose corn syrup with honey as consumer rejection of artificial additives accelerates.
- EU Green Deal procurement mandates:Public sector foodservice contracts across member states now require documented pollinator-friendly sourcing, creating preferential market access for certified apiary networks.
- Medicinal-grade demand concentration:Hospital and pharmacy channels in China are expanding methylglyoxal-graded Manuka honey inventories for wound care and digestive health applications.
Market Restraints
- Input cost volatility:Bee feed supplement prices fluctuate with soybean meal markets, compressing margins for prairie province apiaries dependent on artificial pollen substitutes during winter dormancy.
- Supply concentration risk:Premium Manuka honey sourcing clusters on New Zealand's North Island, creating single-origin vulnerability to weather events and territorial access disputes with Māori landholders.
- Substitution threat:Monk fruit extract and allulose are capturing clean-label beverage formulations where honey's hygroscopicity complicates shelf-stable processing.
Strategic Opportunities
- Underpenetrated pharmacy channels:Brazil's ANVISA is streamlining medical-grade honey registration pathways, opening hospital procurement for hydrogel wound dressings and oral care formulations.
- Technology convergence:Blockchain-integrated isotope ratio mass spectrometry is enabling real-time origin verification that satisfies EU REACH documentation requirements without laboratory bottlenecks.
- Regulatory tailwind:China's dual carbon goals are accelerating SAMR incentives for carbon-neutral apiary certification, rewarding producers with preferential e-commerce platform placement.
Industry Challenges
- Certification timeline compression:EFSA-influenced pesticide residue thresholds now require seasonal batch testing that extends inventory holding periods by 8-12 weeks before EU market release.
- Apiary skill attrition:Experienced queen breeding specialists are aging out of the workforce faster than vocational programs in Madhya Pradesh and Rajasthan can replenish technical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Honey Market |
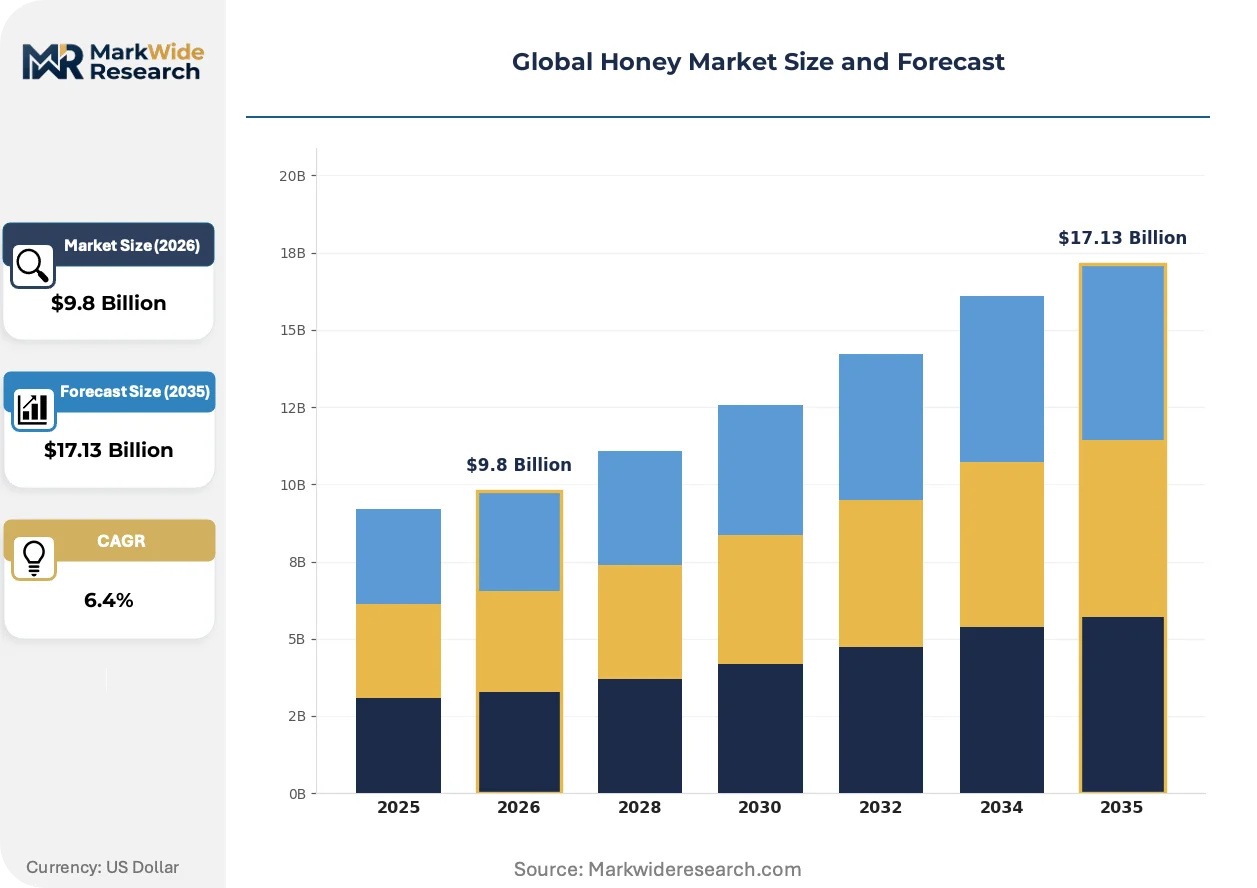
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Honey, Organic Honey, Manuka Honey, Blended Honey Application: Food & Beverage, Healthcare, Cosmetics, Dietary Supplements End User: Food Manufacturers, Pharmacies, Cosmetic Brands, Retail Consumers Packaging Type: Glass Jars, Plastic Bottles, Pouches, Bulk Containers |
| Companies Covered | Bee Maid Honey Limited, Billy Bee Honey Products, Dabur India Ltd., Streamland Biological Technology Ltd., Dutch Gold Honey Inc., Comvita Limited, Yamada Bee Company, Jiangsu Anweizhen Food Co., Ltd., Capilano Honey Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Honey Market Emerging Trajectories
Authentication technologies and procurement transparency are restructuring competitive advantage, separating vertically controlled origin stories from commodity bulk supply.
Nuclear magnetic resonance spectroscopy combined with DNA barcoding of pollen traces is expanding into premium private-label verification programs. German and Swiss retailers are adopting these systems to preempt adulteration scandals. The technology is expanding into mid-tier supermarket chains that previously relied on supplier certificates alone.
EU F-Gas Regulation phase-down schedules are accelerating cold-chain energy audits for honey storage facilities. Warehouse operators in Spain and Italy are retrofitting refrigeration with natural refrigerant systems to maintain organic certification eligibility. Small-scale packers in Greece face compliance cost barriers that favor cooperative consolidation.
Direct-to-consumer subscription models are displacing traditional wholesale relationships for single-origin varietals. Urban consumers in Shanghai and Seoul are purchasing traceable jar-to-hive products through livestream commerce channels. This pattern is most visible among millennial households prioritizing antimicrobial credential transparency over price comparison.
Global Honey Market Segmentation
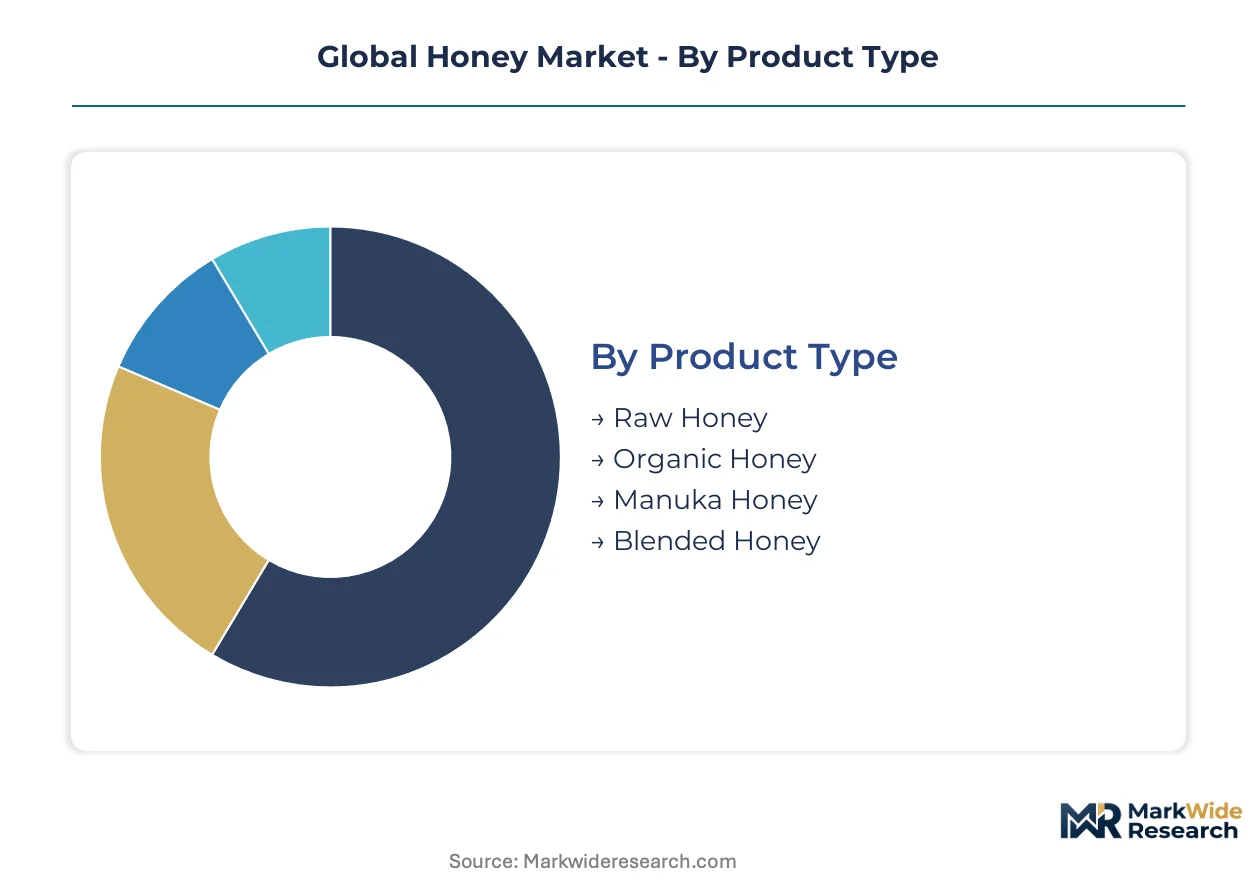
Honey segmentation separates bulk commodity flows from authenticated premium tiers. Product origin and certification grade determine channel access and margin capture across foodservice, pharmacy, and direct-to-consumer routes.
Product Type:
Volume concentrates in minimally processed grades while premium extraction commands pharmacy and specialty retail placement.
- Raw Honey:Unfiltered and unpasteurized, retaining enzymatic activity and pollen traces that signal authenticity to direct-to-consumer buyers. Demand clusters in Shanghai and Seoul livestream commerce channels where jar-to-hive traceability justifies price premiums over heat-treated alternatives.
- Manuka Honey:Methylglyoxal-graded monofloral honey from Leptospermum scoparium nectar, with UMF certification tiers determining pharmacy eligibility. Hospital procurement in China and wound-care formulations in Germany concentrate demand in the highest methylglyoxal brackets.
- Organic Honey:EFSA-compliant residue thresholds enable EU supermarket placement; apiary certification requires 3-kilometer buffer zones from conventional agriculture.
- Blended Honey:Multi-origin mixing achieves color and moisture consistency for industrial food manufacturing; cost positioning serves bakery and confectionery bulk buyers.
Mature deployment sits with Blended Honey. Newer deployment is concentrated in Manuka Honey.
Application:
Formulation requirements split the market between clean-label food substitution and therapeutic credentialing.
- Food & Beverage:Natural sweetener replacement for high-fructose corn syrup in German and French processed products; hygroscopicity challenges shelf-stable beverage developers.
- Healthcare:Hydrogel wound dressings and oral care formulations; ANVISA registration pathways in Brazil are streamlining hospital procurement for medical-grade honey.
- Cosmetics:Humectant and antimicrobial properties drive Korean skincare formulations; humectant function competes with synthetic alternatives in mass-market positioning.
- Dietary Supplements:Functional positioning around digestive health and immune support; capsule and lozenge formats bypass honey's handling complexity.
Healthcare applications are climbing the fastest as pharmacy channels expand methylglyoxal-graded inventories.
End User:
Procurement scale separates industrial volume contracting from authenticated small-batch purchasing.
- Food Manufacturers:Bulk procurement for natural sweetener reformulation; EU Green Deal mandates now require pollinator-friendly sourcing documentation for public sector contracts.
- Pharmacies:Medical-grade honey for wound care and digestive health; methylglyoxal grading systems determine inventory tiers and shelf placement.
- Cosmetic Brands:Ingredient sourcing for premium skincare lines; Korean and French formulators prioritize Manuka and organic certifications for clean-label positioning.
- Retail Consumers:Direct-to-subscription purchasing of single-origin varietals; glass jar packaging signals authenticity in Shanghai and Seoul livestream commerce.
Food Manufacturers dominate volume throughput. Retail Consumers are gaining share fastest in value terms.
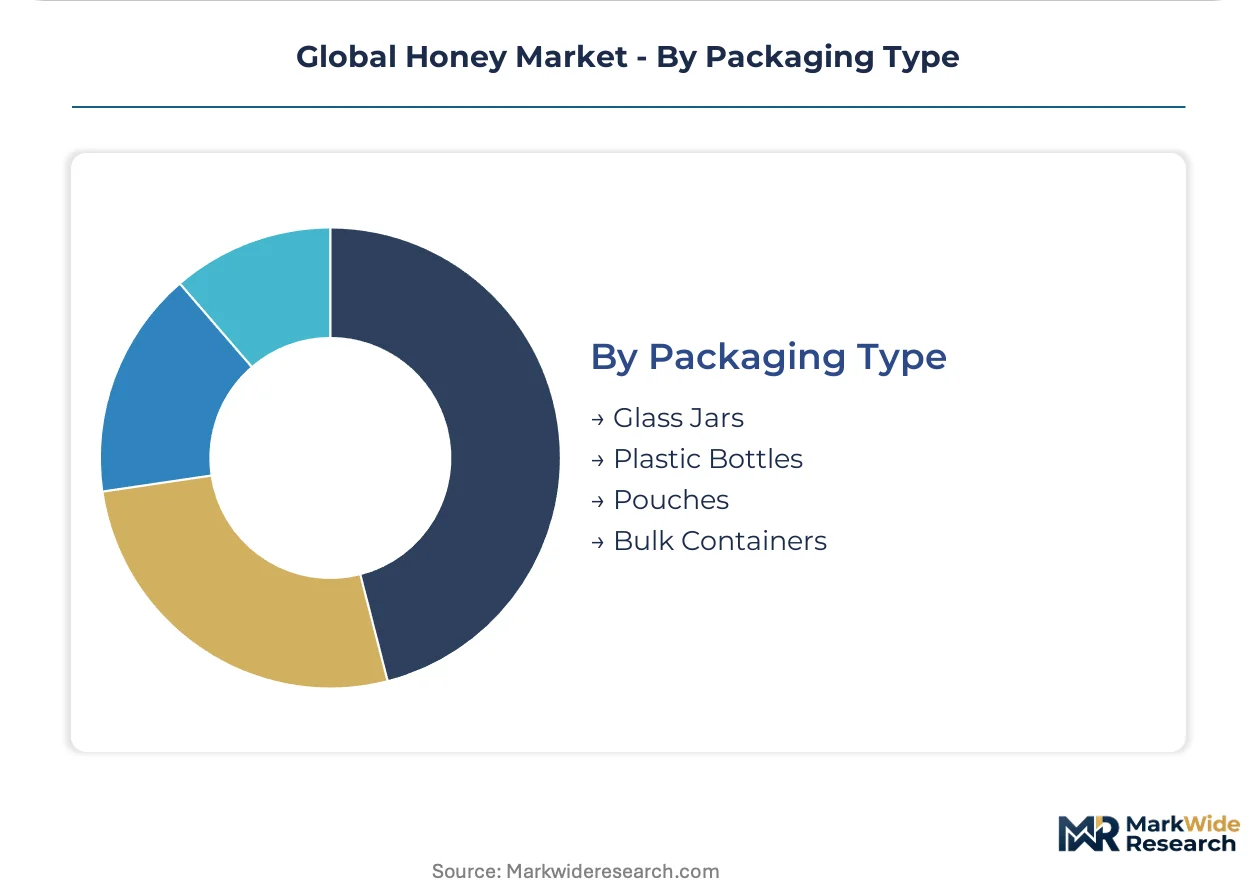
Packaging Type:
Material choice reflects channel positioning and shelf-life requirements across temperature-controlled and ambient distribution.
- Glass Jars:Premium positioning for traceable single-origin products; weight and breakage costs limit e-commerce scalability.
- Plastic Bottles:Squeeze formats for foodservice and household convenience; polymer selection faces EU F-Gas Regulation compliance for cold-chain storage.
- Pouches:Flexible formats for food manufacturing and foodservice portion control; reduced shipping weight appeals to bulk buyers.
- Bulk Containers:Drum and tote formats for industrial honey procurement; cooperative consolidation in Greece and Spain optimizes logistics for small-scale packers.
Bulk Containers anchor industrial supply. Glass Jars are expanding most quickly in premium direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manuka nectar concentration on New Zealand's North Island and prairie province apiary networks across Canada anchor supply-side geography. Demand clusters in China, Germany, and the United States reshape procurement routing and certification requirements.
China
Hospital and pharmacy channels in Shanghai and Beijing are expanding methylglyoxal-graded Manuka honey inventories for wound care applications. SAMR and GB standards govern domestic purity testing and GMO screening, creating compliance layers for cross-border trade. Livestream commerce platforms in Shanghai are displacing traditional wholesale relationships for traceable jar-to-hive products.
Germany
Food manufacturers in Bavaria and Baden-Württemberg are reformulating processed products to replace high-fructose corn syrup with honey as consumer rejection of artificial additives accelerates. EFSA-influenced pesticide residue thresholds now require seasonal batch testing that extends inventory holding periods before market release. German retailers are adopting nuclear magnetic resonance spectroscopy combined with DNA barcoding to preempt adulteration scandals.
United States
FDA enforces identity standards under 21 CFR 101.80 for honey labeling and adulteration detection, shaping import acceptance criteria. The Pacific Northwest and California apiary clusters are restructuring contracting to satisfy pollinator-friendly sourcing mandates in public sector foodservice contracts. Direct-to-consumer subscription models are displacing traditional wholesale relationships for single-origin varietals.
New Zealand
Premium Manuka honey sourcing clusters on the North Island, creating single-origin vulnerability to weather events and territorial access disputes with Māori landholders. Comvita Limited anchors vertical control over Manuka sourcing through cooperative arrangements. UMF certification tiers determine pharmacy eligibility in export markets, concentrating value capture in the highest methylglyoxal brackets.
Canada
Bee Maid Honey Limited leverages cooperative beekeeper networks across prairie provinces to sustain volume consistency through seasonal variability. Health Canada and PMRA requirements shape residue monitoring for export eligibility into EU and US markets. Cold-chain energy audits are accelerating warehouse retrofitting with natural refrigerant systems to maintain organic certification eligibility.
Global Honey Market Vendor Landscape
Global majors compete with regional champions across authentication technology and origin verification. The vendor base separates into vertically integrated origin controllers, cooperative network aggregators, and bulk commodity blenders. Three strategic archetypes dominate: North Island Manuka specialists, Canadian prairie cooperative packers, and Indian backward-integrated Ayurvedic houses. Competitive moves concentrate on blockchain-integrated provenance systems and cooperative consolidation to achieve cold-chain compliance scale.
Within the cooperative network tier, Bee Maid Honey Limited and Capilano Honey Ltd. represent prairie and Southern Hemisphere aggregator models respectively. Dabur India Ltd. occupies a position exemplifying backward integration into tribal and rural apiary clusters. Comvita Limited anchors the premium vertical control archetype through North Island Manuka specialization. These three patterns illustrate how procurement architecture determines authentication credibility and pharmacy channel access.
| Leading Market Players |
|---|
| Bee Maid Honey Limited |
| Billy Bee Honey Products |
| Dabur India Ltd. |
| Streamland Biological Technology Ltd. |
| Dutch Gold Honey Inc. |
| Comvita Limited |
| Yamada Bee Company |
| Jiangsu Anweizhen Food Co., Ltd. |
| Capilano Honey Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into tribal and rural apiary clusters anchors both supply security and pricing power for integrated Ayurvedic houses, while cooperative networks across Canadian prairie provinces sustain volume consistency without captive margin capture. This procurement architecture directly shapes how methylglyoxal grading systems and UMF certification tiers translate into pharmacy-channel premium realization versus commodity bulk positioning.
Pricing Analysis
Warranty and certification bundling separates authenticated Manuka honey with UMF documentation from unverified bulk supply, with laboratory testing costs embedded in premium tiers rather than unbundled add-ons. Three-tier pricing structure across premium, standard, and economy levels stratifies by methylglyoxal concentration, organic certification status, and jar-to-hive traceability depth. Pricing pressure stems from monk fruit extract and allulose capturing clean-label beverage formulations where honey's hygroscopicity complicates processing. Industrial food manufacturers exhibit highest price sensitivity due to reformulation volume scale, while pharmacy procurement committees prioritize therapeutic credentialing over unit cost.
Supply Chain Analysis
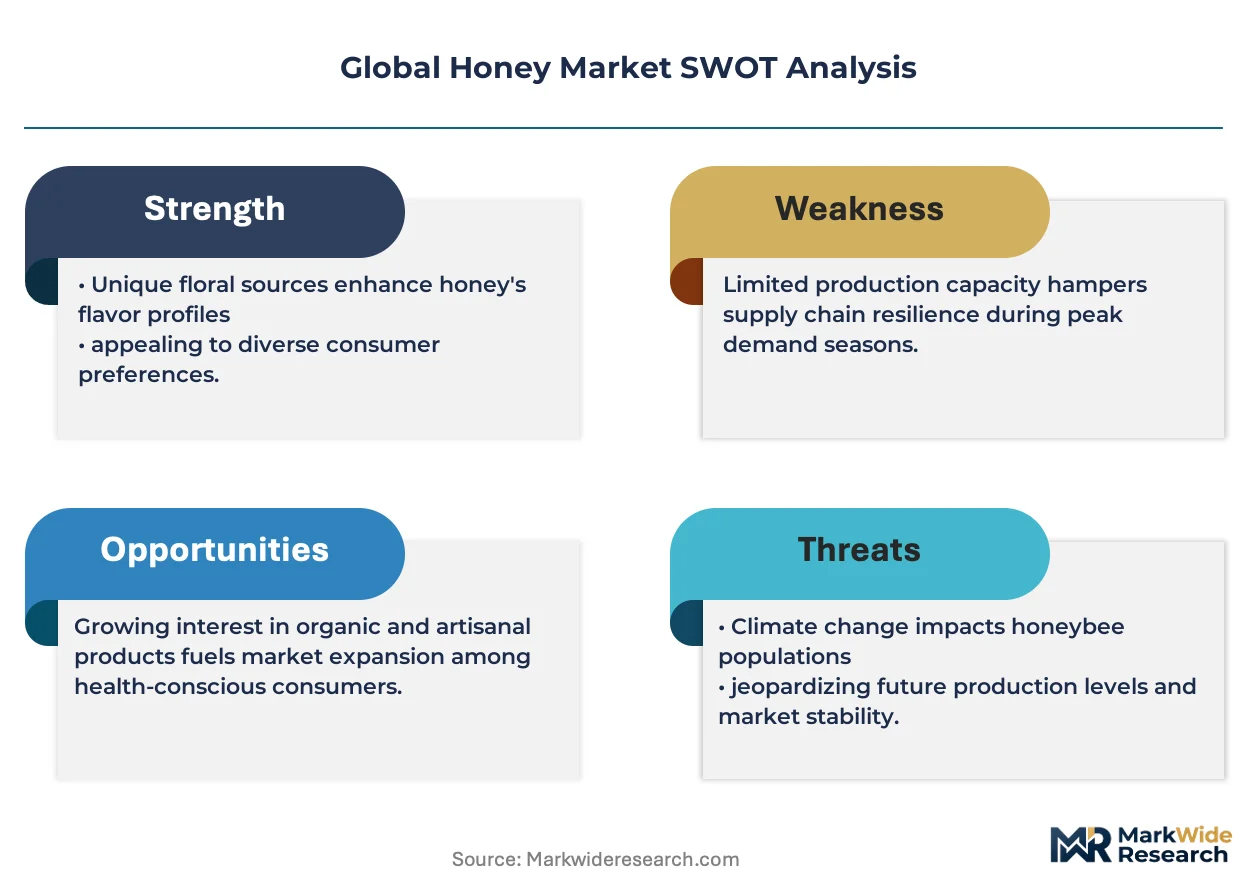
Workforce availability constraints in Madhya Pradesh and Rajasthan apiary clusters are accelerating faster than vocational programs can replenish queen breeding technical capacity, tightening skilled labor pools for backward-integrated operators. Supply concentrates in New Zealand's North Island for Manuka monofloral nectar, Canada's prairie provinces for volume consistency, and China's interior provinces for domestic consumption grade. Raw material dependencies center on Leptospermum scoparium floral density, soybean meal bee feed supplements, and glass packaging for premium positioning. Single-origin vulnerability to weather events and territorial access disputes with Māori landholders constitutes the dominant structural risk. Distribution runs through cooperative packer networks for bulk industrial supply and direct-to-consumer livestream commerce for authenticated single-origin varietals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over methylglyoxal-graded Manuka sourcing and backward integration into certified organic apiary clusters determines pharmacy-channel access and margin capture.
For Market Incumbents: Extend authentication technology investments into blockchain-integrated isotope ratio mass spectrometry to preempt EFSA-influenced adulteration detection requirements. Deepen cooperative consolidation across prairie province networks to achieve cold-chain compliance scale against F-Gas Regulation phase-down schedules. Allulose and monk fruit substitution in beverage applications threatens volume throughput in industrial sweetener segments.
For New Entrants and Emerging Players: Capture underpenetrated pharmacy channels in Brazil where ANVISA registration streamlining creates hospital procurement entry points for hydrogel wound dressings. Target direct-to-consumer subscription models in Seoul and Shanghai livestream commerce where millennial households prioritize antimicrobial credential transparency. Position through single-origin varietal storytelling with glass jar packaging signaling authenticity.
For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative network aggregators with established cold-chain infrastructure and backward-integrated Ayurvedic houses with tribal apiary cluster control. Long-term viability hinges on authentication credibility and regulatory compliance scale rather than commodity volume positioning. Watch methylglyoxal grading system adoption rates in Chinese hospital procurement as inflection indicator for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Integrated Provenance Systems | Real-time origin verification satisfies EU REACH documentation without laboratory bottlenecks. |
| Cooperative Network Consolidation | Cold-chain compliance scale achieves F-Gas Regulation eligibility for organic certification maintenance. |
| Pharmacy Channel Registration | ANVISA streamlining in Brazil opens hospital procurement for medical-grade honey formulations. |
| Backward Integration into Apiary Clusters | Tribal and rural network control secures volume consistency through seasonal variability. |
| Direct-to-Consumer Subscription Launch | Livestream commerce in Shanghai and Seoul displaces traditional wholesale relationships. |
Methodological Framework
Document review covered regulatory filings with FDA, EFSA, SAMR, and ANVISA, complemented by interviews with cooperative packer operations managers, pharmacy procurement directors, apiary cluster supervisors, and food manufacturer reformulation leads. Secondary validation drew from customs and trade data, organic certification registry records, methylglyoxal grading databases, and hospital procurement contract disclosures. Bottom-up volume modeling across apiary cluster outputs triangulated against top-down consumption estimates from retail audit channels and foodservice distribution records.
Segment-level projections incorporated product type stratification across raw, Manuka, organic, and blended grades; application splits between food and beverage, healthcare, cosmetics, and dietary supplements; and end-user differentiation among food manufacturers, pharmacies, cosmetic brands, and retail consumers. CAGRs were derived from historical volume trajectories adjusted for regulatory enforcement intensity and substitution threat penetration. Forecast inputs included bee colony health indices, floral source availability modeling, and e-commerce platform placement algorithm changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pollinator health regulation expansion, carbon footprint disclosure mandate adoption, and territorial access dispute resolution with Māori landholders in New Zealand. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Edible Cutlery Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Tahini Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Poke Food Market
Specialty Foods
Global Truffle Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
North America Hummus Market
Specialty Foods
Halal Products Market
Specialty Foods
Global Guilt-Free Desserts Market