
 North America Paper Machine Oil Market | 2026-2036
North America Paper Machine Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paper Machine Oil Market Analysis
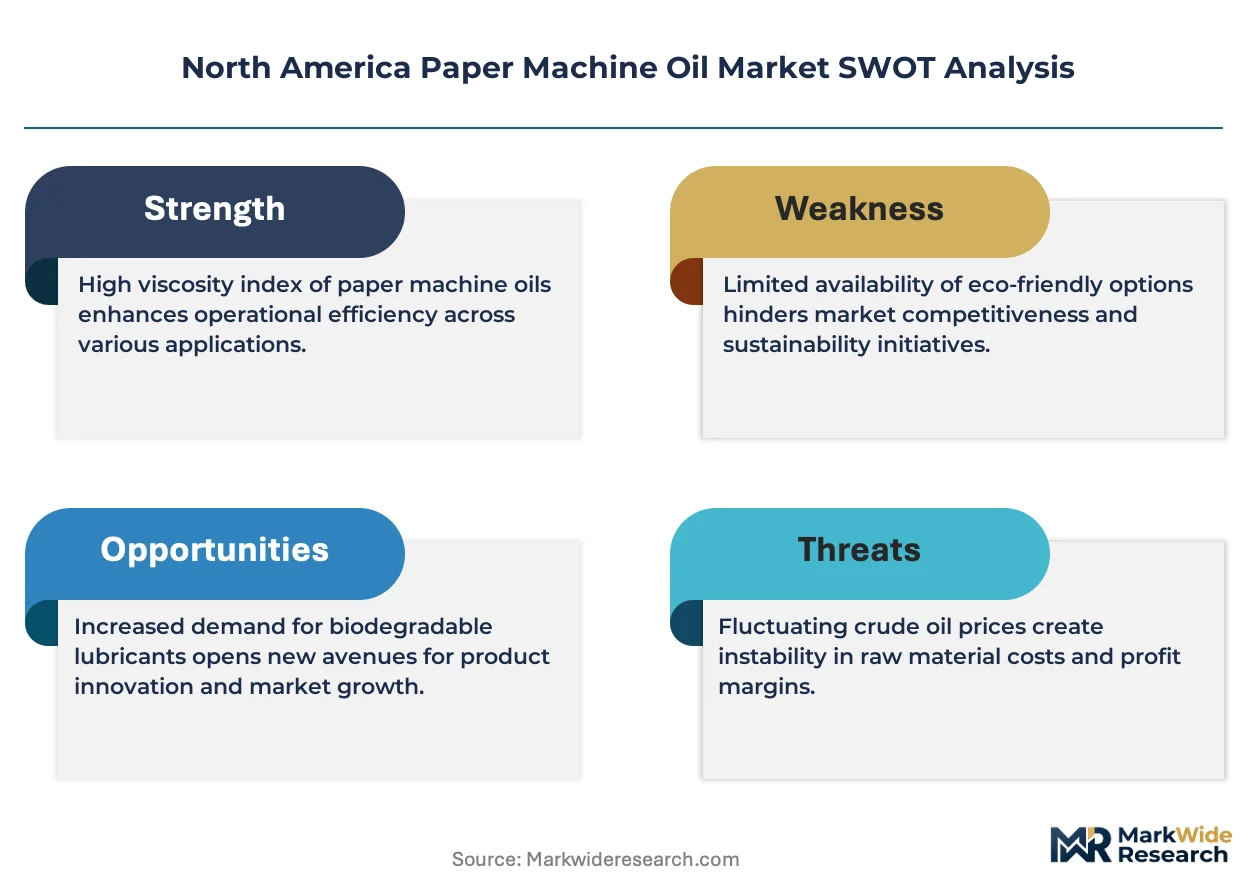
Specialty packaging paper output is pivoting toward higher basis-weight grades that stress bearing and hydraulic systems more severely, intensifying oil consumption per ton of finished product. Exxon Mobil Corporation leverages its integrated base oil refining network to secure feedstock cost advantages across the Great Lakes and Gulf Coast mill corridors. Chevron Corporation sustains technical service density through on-site lubrication engineers stationed at major integrated pulp facilities. Castrol differentiates via synthetic ester formulations engineered for high-temperature dryer section operation.
Paper machine oil comprises refined mineral or synthetic base stocks fortified with anti-wear, oxidation inhibitor, and demulsifier additive packages, formulated to ISO VG 32-150 viscosity grades for circulating systems operating at 50-80°C film temperatures. Its primary purpose is to reduce friction in wet-end forming sections, dry-end calender stacks, and supercalender drives while removing particulate and thermal loads. Hydraulic oils dominate product type demand because press and calendar hydraulics represent the largest volume consumption point with the shortest drain intervals. Lubricating oils for bearing housings carry higher per-gallon margins due to extended service life claims and OEM approval requirements. Distributor channels capture the majority of volume as mills consolidate procurement through regional lubricant jobbers offering tankage and filtration services.
EPA stormwater and spill prevention rules tighten storage and handling compliance costs for on-site lubricant inventories, favoring suppliers with environmental services bundling. NSF H1 and H2 food-grade registrations from the USDA-recognized certification body govern oil selection at paper mills supplying direct-contact food packaging grades. OSHA process safety management standards for pulp mill chemical recovery areas indirectly influence lubricant specification through equipment reliability mandates. Stakeholders must monitor how state-level carbon intensity scoring in California and Washington affects synthetic base stock sourcing decisions relative to Group II mineral alternatives.
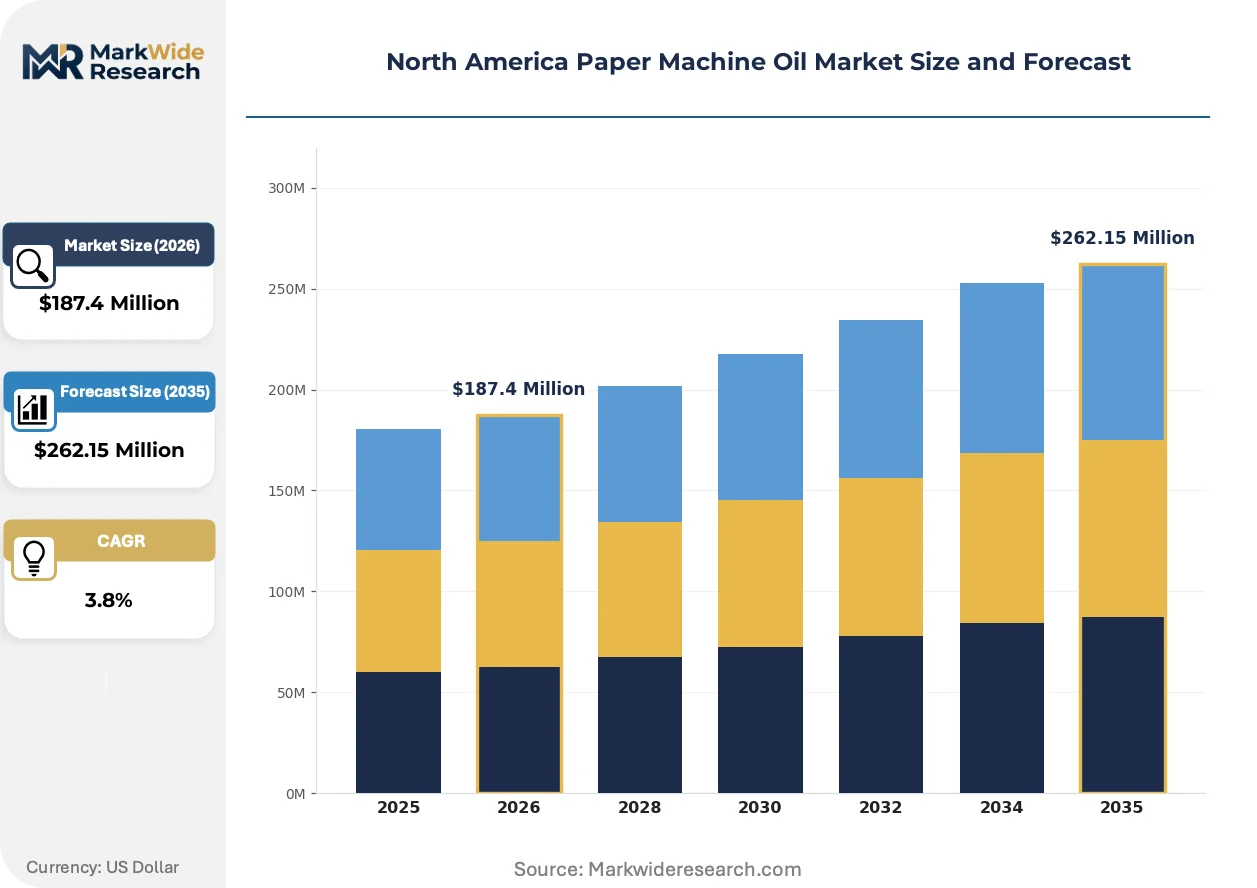
Market Dynamics
EPA stormwater regulations and NSF food-grade certification mandates are compressing formulation flexibility while simultaneously expanding addressable volume for premium synthetic grades across southeastern US mill clusters.
Growth Catalysts
- Food-Grade Certification Mandates:NSF H1 registrations now govern oil selection at mills supplying direct-contact food packaging, forcing upgrades from general industrial grades.
- Pulp Mill Capacity Concentration:Georgia and Alabama host expanding specialty paper operations where machine uptime targets intensify lubricant procurement cycles.
- Synthetic Ester Performance:High-temperature dryer section operation demands formulations with superior oxidative stability, accelerating adoption of Group V base stocks.
Market Restraints
- Group II/III Base Oil Supply Concentration:Gulf Coast refining capacity constraints create feedstock cost volatility for mineral-based formulations.
- Extended Drain Interval Claims:OEM warranty requirements and in-service monitoring limitations cap pricing power for premium synthetic offerings.
- EPA Spill Prevention Friction:SPCC plan compliance costs for on-site tankage disproportionately burden smaller regional jobbers versus integrated suppliers.
Strategic Opportunities
- Environmental Services Bundling:Suppliers combining lubricant delivery with waste oil recovery and filtration maintenance capture sticky mill relationships.
- California Carbon Intensity Scoring:State-level lifecycle assessments favor synthetic base stocks with verified lower carbon footprints versus mineral alternatives.
- On-Site Technical Service Density:Embedded lubrication engineers at integrated pulp facilities create switching costs and specification lock-in.
Industry Challenges
- Tribology Expertise Scarcity:Paper machine systems spanning wet-end forming to dry-end calendering require specialized knowledge in film thickness optimization and bearing failure analysis that outpaces training pipeline output.
- Legacy Circulating System Compatibility:Mills operating 1970s-era lube oil consoles face retrofit costs and flushing protocol complexity when upgrading to higher-detergency synthetic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paper Machine Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Oils, Lubricating Oils, Gear Oils, Compressor Oils Industry Vertical: Pulp & Paper, Chemical Processing, Food Processing, Textile Manufacturing Application: Machine Lubrication, Equipment Cooling, Rust Prevention, Sealing Distribution Channel: Direct Sales, Distributors, Online Retail, Retail Outlets |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, Castrol, Bechem GmbH, Brewer Hendley Oil Corporation, Phillips 66 Company, Petro-Canada Lubricants, Fuchs Schmierstoffe, ALCO LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paper Machine Oil Market Emerging Trajectories
Synthetic formulation chemistry, regulatory compliance architecture, and procurement consolidation are converging to reshape competitive positioning across the North American paper machine oil value chain.
Polyalkylene glycol (PAG) and synthetic ester base stocks are unifying thermal stability and biodegradability performance in a single fluid architecture. Specialty packaging producers in the southeastern United States are adopting these formulations at accelerated pace to meet simultaneous NSF food-grade and EPA discharge requirements. This chemistry convergence is compressing the historical trade-off between high-temperature oxidative resistance and environmental acceptability that previously forced mills into dual-inventory strategies.
EPA stormwater discharge permitting under the Clean Water Act is tightening allowable oil-in-water concentrations at mill outfalls. Industrial consequence includes mandatory secondary containment upgrades and real-time monitoring investments that favor suppliers with environmental liability bundling. Integrated pulp and paper facilities in Georgia and Alabama are responding by consolidating procurement through regional jobbers offering tankage, filtration, and spill response services as unified contracts.
Mill procurement departments are compressing supplier rosters from fragmented regional coverage to three-to-four preferred partnerships with national distribution networks. The distributor channel is capturing volume as mills demand consolidated billing, predictive maintenance analytics, and just-in-time delivery reliability that smaller jobbers cannot provision. This concentration is most visible across the Great Lakes corridor where multi-site paper companies negotiate enterprise lubricant agreements spanning Wisconsin, Michigan, and Ohio operations.
North America Paper Machine Oil Market Segmentation
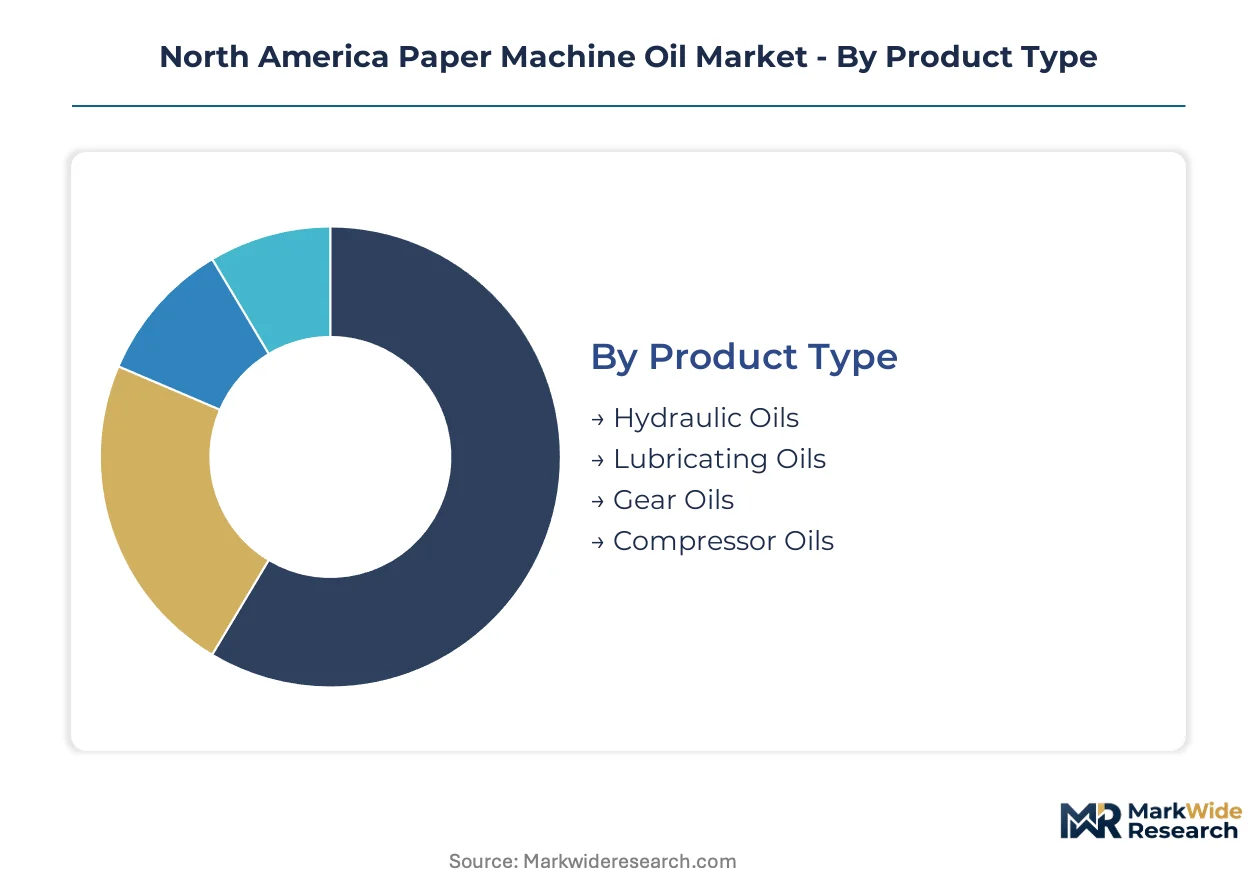
Segmentation in paper machine oil markets reflects divergent technical specifications, regulatory compliance burdens, and procurement channel economics. Buyers prioritize formulation chemistry against specific machine subsystems while weighing NSF certification requirements and distributor service capabilities.
Product Type:
Cost tier differentiation shapes procurement decisions as mills balance drain interval economics against upfront formulation premiums.
- Hydraulic Oils:Formulated to ISO VG 32-68 grades with anti-wear additive packages for high-pressure press and calender hydraulics. Georgia and Alabama pulp mills consume the largest volumes due to shortest drain intervals and continuous circulation demands. EPA spill prevention rules intensify storage compliance costs for these high-turnover formulations.
- Lubricating Oils:Bearing housing formulations span ISO VG 68-150 with extended service life claims and OEM approval requirements. Southeastern US specialty paper producers specify these for dryer section applications where synthetic ester chemistry commands margin premiums over mineral alternatives.
- Gear Oils:EP-additive fortified formulations for supercalender and winder drive systems.
- Compressor Oils:Oxidation-inhibited grades for air compression systems in integrated pulp facilities.
Hydraulic oils lead on scale; lubricating oils lead on momentum.
Industry Vertical:
Application severity and certification stringency create distinct specification tiers across end-use industries.
- Pulp & Paper:Wet-end forming sections, dry-end calender stacks, and supercalender drives demand circulating systems operating at 50-80°C film temperatures. Georgia and Alabama capacity clusters concentrate procurement volume where machine uptime targets tighten lubricant replacement cycles.
- Food Processing:NSF H1 registrations govern direct-contact packaging applications, forcing upgrades from general industrial grades to synthetic formulations with verified biodegradability.
- Chemical Processing:Process safety management standards influence lubricant selection through equipment reliability mandates in hazardous areas.
- Textile Manufacturing:Lower-specification mineral grades dominate where thermal loads remain moderate and regulatory pressure attenuates.
Pulp and paper leads on scale; food processing leads on momentum.
Application:
Functional performance requirements determine additive package selection and base stock chemistry across machine subsystems.
- Machine Lubrication:Friction reduction in bearing housings, gearboxes, and hydraulic circuits constitutes the core value proposition. Synthetic ester and PAG base stocks unify thermal stability with biodegradability for high-temperature dryer section operation.
- Equipment Cooling:Heat removal from circulating systems demands demulsifier additives and oxidation inhibitors to maintain thermal transfer efficiency.
- Rust Prevention:Corrosion inhibitor packages protect wet-end forming section components from moisture exposure.
- Sealing:Elastomer compatibility requirements influence formulation selection for hydraulic system integrity.
Machine lubrication leads on scale; equipment cooling leads on momentum.
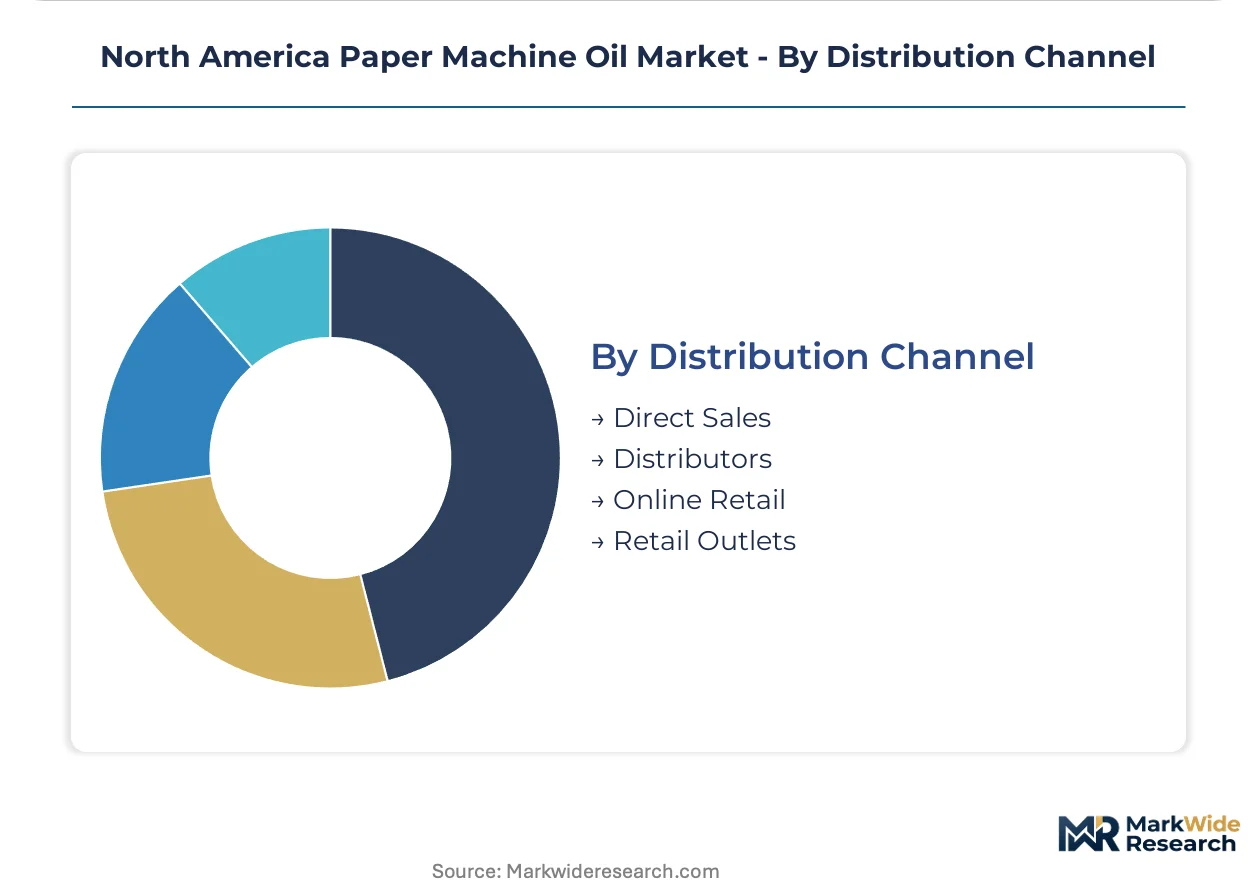
Distribution Channel:
Service bundling capabilities and geographic coverage density determine channel selection for mill procurement departments.
- Distributors:Regional jobbers offering tankage, filtration maintenance, and spill response services capture sticky relationships across southeastern US mill clusters. Consolidated billing and predictive maintenance analytics favor these intermediaries over fragmented alternatives.
- Direct Sales:National suppliers with embedded lubrication engineers at integrated pulp facilities create switching costs and specification lock-in through technical service density.
- Online Retail:Limited penetration due to bulk delivery requirements and environmental liability bundling demands.
- Retail Outlets:Minimal relevance for industrial-scale paper machine applications.
Distributors lead on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Georgia-Alabama pulp and paper corridor concentrates North American demand for paper machine oils, with specialty packaging producers driving specification upgrades across wet-end forming and dry-end calendering systems.
United States
Southeastern mill clusters in Georgia and Alabama consume the largest hydraulic oil volumes due to press and calender circulation demands. EPA stormwater discharge rules under the Clean Water Act tighten allowable oil-in-water concentrations at mill outfalls, forcing secondary containment investments. Integrated pulp facilities around Savannah, Georgia negotiate enterprise lubricant agreements spanning multi-site operations.
Canada
Ontario and Quebec host specialty paper producers supplying food-grade packaging to North American markets. Health Canada and PMRA regulations on chemical handling in food-contact applications reinforce NSF H1 certification requirements for direct-contact packaging oils. Mill procurement in the Great Lakes corridor consolidates through distributors offering tankage and filtration maintenance.
Mexico
Packaging paper capacity expansion in Nuevo León and the Bajío Region drives lubricant procurement for new machine installations. Mexican environmental regulations on industrial wastewater discharge create compliance burdens analogous to EPA frameworks, favoring suppliers with environmental services bundling. Monterrey-area mills specify synthetic formulations for high-temperature dryer sections.
North America Paper Machine Oil Market Vendor Landscape
Environmental services bundling dominates the current landscape as mills consolidate procurement through intermediaries offering unified tankage, filtration, and spill response contracts. The vendor base organizes around three strategic archetypes: integrated petroleum majors with captive base oil refining, specialty lubricant formulators with synthetic chemistry expertise, and regional distributors with embedded technical service capabilities. Capacity expansion in southeastern US mill corridors and strategic partnerships for predictive maintenance analytics represent the principal competitive vectors.
Among integrated petroleum majors, Exxon Mobil Corporation and Chevron Corporation anchor the scale-driven tier with Gulf Coast and Great Lakes supply infrastructure. Castrol occupies a position exemplifying specialty synthetic formulation expertise, particularly for high-temperature dryer section applications. Regional distributors including Brewer Hendley Oil Corporation represent the service-density archetype through on-site lubrication engineering capabilities.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| Castrol |
| Bechem GmbH |
| Brewer Hendley Oil Corporation |
| Phillips 66 Company |
| Petro-Canada Lubricants |
| Fuchs Schmierstoffe |
| ALCO LLC |
| Others |
Supply Flow & Price Mechanics
Synthetic ester and PAG base stock adoption across southeastern US dryer sections simultaneously compresses formulation cost curves and concentrates supply leverage among integrated petroleum majors with captive Group V refining infrastructure.
Pricing Analysis
Group II and Group III mineral base oil costs pass through directly to hydraulic oil pricing, with Gulf Coast refining constraints amplifying volatility for high-turnover press and calender formulations. Three-tier pricing structure across premium synthetic, mid-grade Group III, and economy mineral levels segments buyers by drain interval economics and NSF certification requirements. Cost compression in standard mineral grades is intensifying because extended drain interval claims from OEMs cap pricing power for synthetic alternatives. Integrated pulp facilities with enterprise procurement contracts show lowest price sensitivity; smaller specialty packaging mills without tankage infrastructure exhibit highest sensitivity.
Supply Chain Analysis
Tribology expertise scarcity across Georgia and Alabama mill corridors lengthens lead times for on-site technical service deployment, forcing distributors to compete on engineering workforce density rather than product availability alone. Base stock supply concentrates in United States Gulf Coast refineries, Canadian oil sands upgraders, and South Korean Group III export facilities. Finished lubricant formulation draws from polyalphaolefin, synthetic ester, and additive package inputs subject to agricultural commodity and petrochemical feedstock swings. Single-source vulnerability in specialty ester chemistry creates procurement risk for NSF H1 food-grade formulations. Distribution runs through regional jobbers with embedded tankage and filtration maintenance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American paper machine oil functions as a stable compounder, with EPA regulatory ratcheting driving perpetual specification upgrades that sustain premium pricing power.
For Market Incumbents: Deploy environmental services bundling to deepen mill relationships beyond transactional lubricant supply. Integrate waste oil recovery and real-time filtration monitoring into unified contracts to raise switching costs. Invest in synthetic ester capacity additions at Gulf Coast refining complexes to secure feedstock cost advantages against mineral-based competitors. Counter the threat from regional distributors by embedding lubrication engineers directly at integrated pulp facilities in Georgia and Alabama. For New Entrants and Emerging Players: EPA stormwater discharge rules under the Clean Water Act in the United States open a window for environmental liability bundling specialists without legacy tankage infrastructure burdens. Target smaller specialty packaging mills in the Georgia-Alabama corridor lacking in-house tribology expertise. Pursue white-space in predictive maintenance analytics partnerships, offering oil condition monitoring as a subscription overlay to commodity lubricant supply. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with dense technical service footprints because mill procurement consolidation favors intermediaries offering unified tankage, filtration, and spill response contracts. Focus acquisition screening on southeastern US jobbers with established relationships at expanding pulp facilities. Watch synthetic base stock carbon intensity scoring adoption in California and Washington as an inflection signal for Group V demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stocks | Captive Group V supply secures margin control against Gulf Coast mineral feedstock volatility. |
| Environmental Services Bundling | Unified tankage and spill response contracts create sticky mill relationships in EPA-regulated jurisdictions. |
| On-Site Technical Service Expansion | Embedded lubrication engineers at Georgia and Alabama pulp facilities generate specification lock-in. |
| Predictive Maintenance Analytics Partnership | Oil condition monitoring subscriptions differentiate commodity lubricant supply for cost-conscious mills. |
| NSF H1 Certification Investment | Food-grade registration opens direct-contact packaging segments with premium pricing power. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and specification decision dynamics. Primary discussions engaged lubricant procurement managers at integrated pulp facilities, technical directors at regional distributor operations, and maintenance engineers at specialty packaging mills. Secondary validation drew from EPA enforcement data, NSF certification registries, SEC filings of publicly traded petroleum majors, and American Forest and Paper Association capacity reports. Bottom-up mill consumption estimates triangulated against top-down base stock production and trade flow analysis.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across product type, industry vertical, application function, and distribution channel dimensions. CAGRs were derived from fitted growth curves calibrated to pulp and paper capacity expansion timelines and regulatory compliance phase-in schedules. Machine uptime targets and drain interval extension trends served as industry-specific demand drivers in the forecasting framework.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA regulatory acceleration or synthetic base stock supply disruption scenarios. Material deviation in Georgia-Alabama pulp capacity buildout rates or California carbon intensity scoring implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Hydrogen Silicone Fluid Market