
 Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market | 2026-2036
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market Foresight
Modular adhesive formulations that combine APAO with tackifying resins and waxes in pre-optimized ratios is realigning procurement decisions for mid-sized converters. Eastman Chemical Company leverages its integrated hydrocarbon feedstock position to sustain cost-competitive APAO supply across multiple viscosity grades. Huntsman Corporation anchors its position through specialized polymer architectures that differentiate performance in high-temperature automotive bonding applications. Henkel AG & Company KGaA competes by controlling direct customer relationships with global packaging OEMs and specifying APAO content in approved adhesive recipes.
Amorphous Polyalphaolefin for Hot Melt denotes a non-crystalline, low-molecular-weight polyalphaolefin polymer produced via metallocene or Ziegler-Natta catalysis, characterized by a glass transition temperature typically below minus 50 degrees Celsius and broad compatibility with tackifiers and waxes; it functions primarily as the base polymer in hot melt adhesive formulations that soften upon heating and set rapidly upon cooling without solvent evaporation. Medium Viscosity APAO dominates volume shipments due to its balanced wetting characteristics and open time suitable for general packaging lines, while Modified APAO represents the fastest-expanding structural category as grafted maleic anhydride and silane variants capture premium positions in automotive and electronics assembly where polar substrate adhesion is critical. Packaging Adhesives anchors the application hierarchy through food and beverage carton sealing demand, whereas Automotive Bonding generates disproportionate margin pools as OEMs specify APAO-based solutions for interior trim and wire harness fixation.
EPA regulations governing volatile organic compound emissions from adhesive formulations restrict solvent-based alternatives and redirect specification engineers toward APAO hot melts in U.S. manufacturing facilities. REACH registration requirements and the EU Green Deal's chemical sustainability targets compel European formulators to document APAO supply chain transparency and carbon intensity across polymer grades. ECHA substance evaluation protocols further influence raw material qualification timelines for adhesive producers serving personal care and consumer goods sectors. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and secure multi-regional product registrations ahead of tightening compliance deadlines.
Market Dynamics
Converters across packaging and automotive sectors are consolidating adhesive procurement around pre-formulated APAO modules that compress technical qualification cycles and reduce in-house compounding labor.
Growth Catalysts
- EPA VOC limits:Adhesive formulators in U.S. manufacturing facilities face mandatory solvent reduction timelines, redirecting specification engineers toward APAO hot melts that eliminate volatile organic compound emissions entirely.
- Automotive interior assembly:OEMs specify APAO-based bonding solutions for wire harness fixation and trim attachment as vehicle electrification raises thermal management requirements for cabin materials.
- China adhesive production expansion:Domestic converters are scaling APAO consumption to supply carton sealing demand from e-commerce fulfillment centers and food packaging export operations.
Market Restraints
- Propylene feedstock volatility:APAO production economics remain tethered to propylene monomer pricing swings that compress margin predictability for polymer producers and compounders alike.
- Asian supply concentration:A disproportionate share of metallocene catalyst production and specialized hydrogenation capacity sits in South Korea and Japan, creating geographic vulnerability for European and North American formulators.
- Hot melt temperature ceiling:APAO formulations face adhesion failure thresholds above 80 degrees Celsius that restrict deployment in under-hood automotive applications where polyamide and polyester alternatives dominate.
Strategic Opportunities
- India packaging conversion:Carton sealing operations in Maharashtra and Gujarat remain underpenetrated by APAO technology, presenting first-mover positioning for adhesive suppliers establishing local technical service presence.
- EU Green Deal carbon accounting:REACH registration documentation now rewards supply chain transparency with preferential qualification status, advantaging APAO producers with verified low-carbon hydrogenation processes.
- Silane-grafting convergence:Modified APAO architectures combining maleic anhydride functionality with silane crosslinking are opening electronics assembly applications requiring polar substrate adhesion and moisture resistance.
Industry Challenges
- Metallocene catalyst expertise scarcity:Formulation chemists capable of optimizing APAO molecular weight distribution for specific open-time requirements remain concentrated at a handful of polymer producers and technical universities.
- REACH evaluation timelines:ECHA substance evaluation protocols for polymer constituents are extending raw material qualification cycles to 18-24 months, delaying new adhesive product introductions in European personal care and consumer goods sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market |
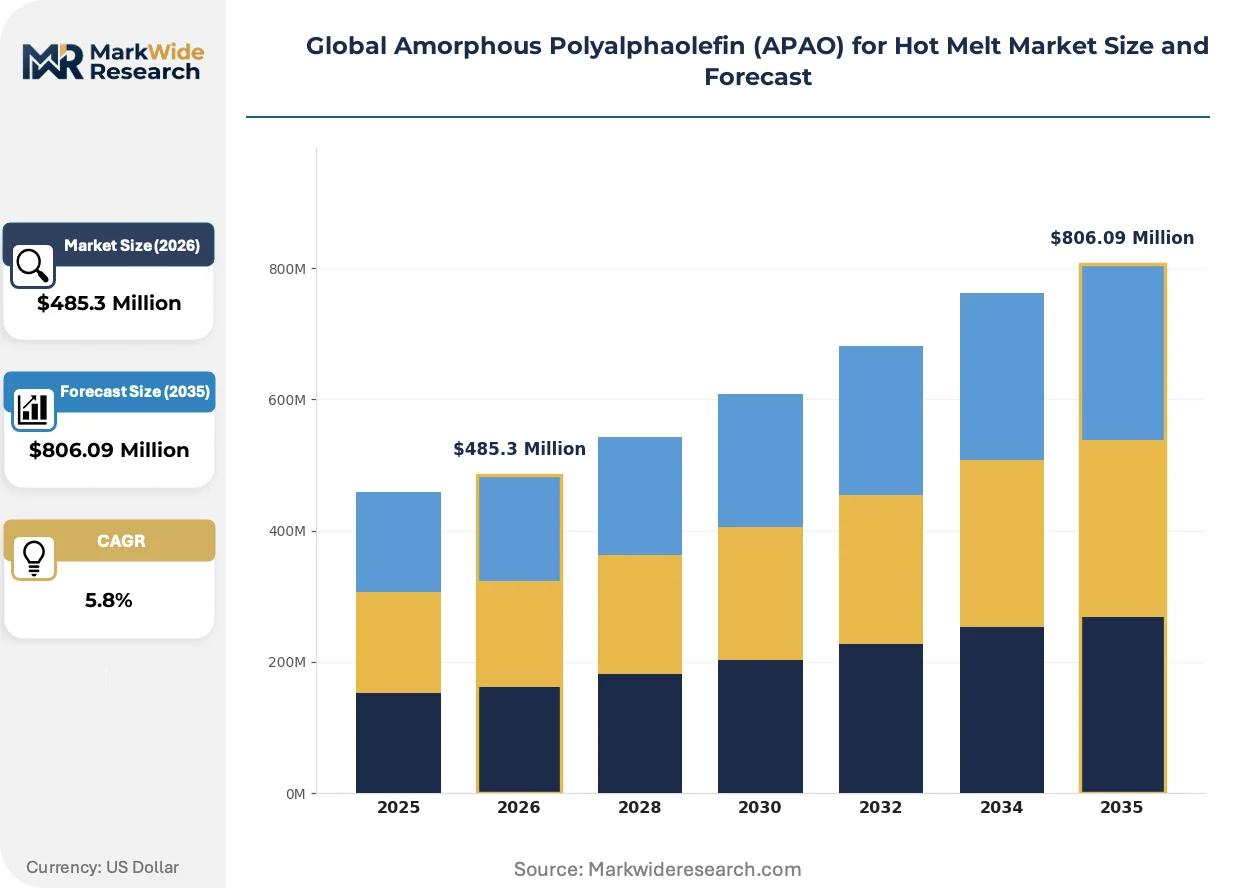
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Viscosity APAO, Medium Viscosity APAO, High Viscosity APAO, Modified APAO Application: Packaging Adhesives, Automotive Bonding, Bookbinding, Textile Lamination, Footwear Manufacturing End User Industry: Consumer Goods Manufacturers, Construction Firms, Electronic Assemblers, Paper Goods Producers, Personal Care Product Makers Packaging Type: Drums, Bulk Bags, Carboys, Intermediate Bulk Containers, Totes |
| Companies Covered | Eastman Chemical Company, Huntsman Corporation, H.B. Fuller, Henkel AG & Company KGaA, Evonik Industries AG, REXtac LLC, Bostik, Arkema S.A., Liaoyang Liaohua Qida Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market Shifts & Advancements
Metallocene-catalyzed APAO production is compressing the performance gap between commodity hot melts and specialized reactive polyurethane systems, enabling specification engineers to simplify formulation architectures without sacrificing bond durability.
Metallocene catalyst platforms are overtaking conventional Ziegler-Natta systems in medium-viscosity APAO manufacturing. Packaging converters in Germany and the United States are adopting these polymers at accelerating rates for high-speed carton sealing lines. The technology is overtaking legacy production methods by delivering narrower polydispersity indices that improve thermal stability and reduce char formation in adhesive melters.
REACH registration requirements are tightening documentation obligations for polymer importers and downstream formulators serving European markets. The regulation mandates carbon intensity disclosure across supply chains and restricts substances of very high concern in adhesive applications. Personal care packaging producers are responding by pre-qualifying APAO grades with complete SVHC screening to accelerate customer audit cycles.
Specification authority is migrating from adhesive compounders to end-use OEMs with centralized materials engineering functions. Automotive assemblers and global packaging brands are consolidating approved vendor lists and dictating base polymer chemistry in sourcing contracts. This concentration is most visible in China where domestic appliance manufacturers and beverage bottlers now specify APAO content minimums in annual adhesive procurement tenders.
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market Segmentation
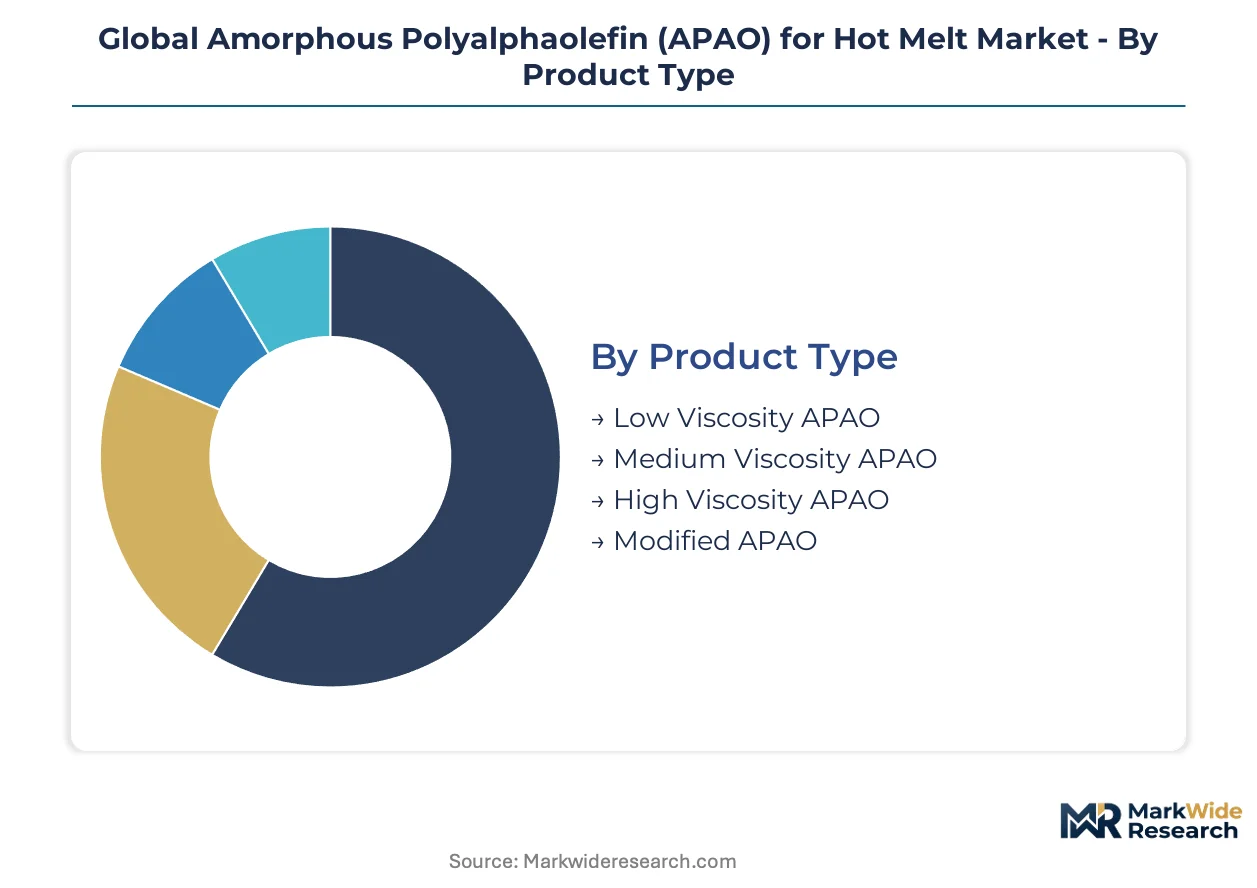
APAO segmentation reflects divergent technical requirements across adhesive performance tiers and end-use thermal environments. Procurement patterns concentrate around viscosity-grade standardization in high-volume packaging while modified variants capture specification-driven automotive and electronics assembly.
Product Type:
Volume shipments cluster in mid-range viscosity grades where cost efficiency meets processing latitude, while premium positions concentrate in functionalized architectures.
- Medium Viscosity APAO:Balanced molecular weight distribution delivers optimal wetting characteristics and controlled open time for high-speed carton sealing operations. German packaging converters specify this grade for automated fulfillment lines serving e-commerce distribution centers. Demand concentrates in China where domestic adhesive compounders supply carton sealing operations for food export logistics.
- Modified APAO:Grafted maleic anhydride and silane variants enable polar substrate adhesion in automotive interior trim and moisture-resistant electronics assembly. Japanese automotive OEMs specify silane-grafted grades for wire harness fixation in electric vehicle platforms. Premium pricing reflects hydrogenation complexity and catalyst specialization concentrated in South Korean production facilities.
- Low Viscosity APAO:Reduced molecular weight enables sprayable hot melt formulations for nonwoven hygiene applications.
- High Viscosity APAO:Elevated cohesive strength supports structural bonding in construction panel lamination and heavy-duty corrugated packaging.
Today's leader: Medium Viscosity APAO. Tomorrow's challenger: Modified APAO.
Application:
Application segmentation tracks regulatory displacement of solvent systems against thermal performance boundaries that constrain material selection.
- Packaging Adhesives:Food and beverage carton sealing represents the dominant volume channel as EPA VOC limits eliminate solvent-based alternatives in U.S. manufacturing facilities. E-commerce fulfillment expansion in China and India drives specification of APAO-based case and carton sealing across ambient-temperature supply chains.
- Automotive Bonding:Interior trim attachment and wire harness fixation generate disproportionate margin contribution as electrification raises thermal management requirements for cabin materials. OEMs in Germany and Japan specify APAO content minimums in annual adhesive procurement tenders for vehicle assembly platforms.
- Bookbinding:Spine bonding and edge sealing applications favor medium-viscosity grades with rapid set characteristics.
- Textile Lamination:Nonwoven and fabric bonding for medical and industrial applications requires controlled peel strength and wash resistance.
- Footwear Manufacturing:Upper-to-sole bonding and component assembly in athletic and casual footwear production.
Packaging Adhesives commands current volume leadership; Automotive Bonding exhibits the steepest expansion trajectory as thermal specification requirements intensify.
End User Industry:
End user segmentation reveals procurement authority migration toward OEMs with centralized materials engineering functions.
- Paper Goods Producers:Corrugated container and folding carton manufacturers specify APAO content in annual adhesive procurement tenders across China and India. E-commerce packaging demand from domestic fulfillment centers drives volume concentration in Zhejiang and Maharashtra production clusters.
- Consumer Goods Manufacturers:Personal care and household product packaging producers pre-qualify APAO grades with complete SVHC screening to accelerate customer audit cycles under REACH documentation requirements.
- Construction Firms:Panel lamination and insulation bonding applications in residential and commercial building systems.
- Electronic Assemblers:Device housing and component fixation requiring moisture resistance and polar substrate adhesion.
- Personal Care Product Makers:Hygiene and cosmetic packaging with demanding aesthetic and regulatory compliance requirements.
Paper Goods Producers anchor present procurement volumes; Consumer Goods Manufacturers are gaining specification influence fastest through centralized sustainability audit requirements.
Packaging Type:
Packaging configuration follows adhesive compounder scale and inventory velocity requirements across regional supply chains.
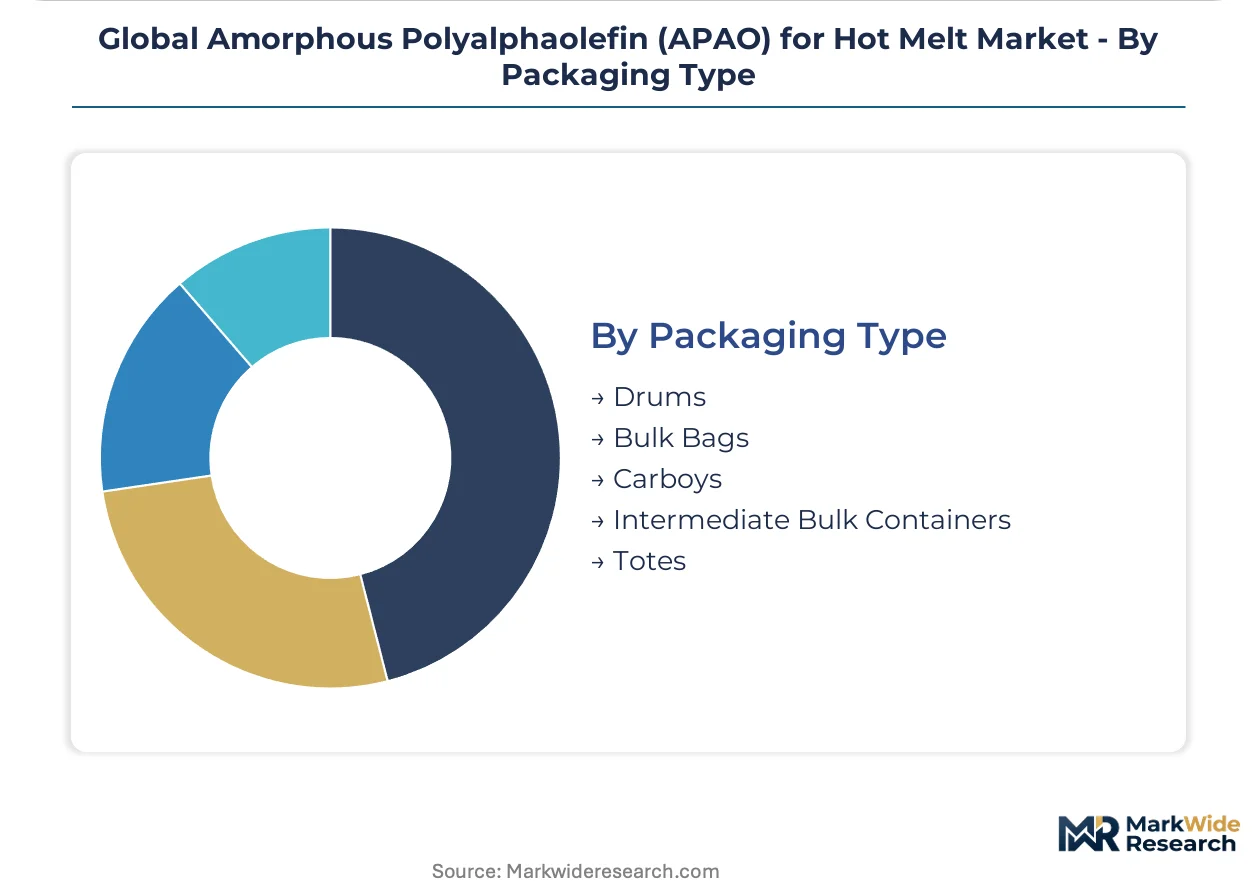
- Bulk Bags:High-volume packaging converters in China and Germany favor flexible intermediate bulk containers for just-in-time compounding operations with rapid inventory turnover.
- Drums:Standard 200-liter steel and polymer drums serve mid-sized European and North American formulators with moderate consumption rates and established material handling infrastructure.
- Intermediate Bulk Containers:Rigid composite IBCs support automated dispensing systems in large-scale automotive adhesive production facilities.
- Totes:Collapsible and rigid tote systems enable returnable packaging programs for closed-loop supply chains.
- Carboys:Smaller-volume polymer carboys serve specialty compounders and laboratory-scale formulation development.
Bulk Bags dominate throughput economics currently; Intermediate Bulk Containers are capturing share fastest in automated automotive adhesive production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amorphous Polyalphaolefin hot melt adhesive technology originated in United States petrochemical research facilities during the 1970s, with commercial scale-up following in German chemical manufacturing corridors. Production economics subsequently gravitated toward East Asian metallocene catalyst centers as packaging demand industrialized across Pacific Rim manufacturing zones.
United States
EPA VOC emission limits are redirecting specification engineers toward solvent-free APAO formulations across Midwest packaging corridors. Automotive OEMs in Michigan and Ohio specify APAO content minimums for interior trim bonding as electrification raises thermal management requirements. Adhesive compounders in the Chicago-Detroit industrial corridor are consolidating procurement around pre-formulated modules to compress technical qualification cycles.
Germany
REACH registration requirements and the EU Green Deal's chemical sustainability targets compel formulators to document supply chain transparency across polymer grades. ECHA substance evaluation protocols extend raw material qualification timelines for personal care packaging producers. Bavarian adhesive manufacturers serving automotive OEMs in Stuttgart and Munich are pre-qualifying APAO grades with complete SVHC screening to accelerate customer audit cycles.
China
Domestic adhesive production capacity expansion and automotive assembly output continue climbing in Yangtze River Delta manufacturing clusters. E-commerce fulfillment center proliferation in Zhejiang and Jiangsu provinces drives carton sealing demand for APAO-based case and carton adhesives. NMPA-equivalent standards for food contact materials are tightening formulation documentation requirements for export-oriented packaging compounders.
Japan
Automotive OEMs specify silane-grafted APAO grades for wire harness fixation in electric vehicle platforms manufactured in Toyota City and Yokohama assembly complexes. METI industrial standards for adhesive performance in transportation applications are elevating qualification thresholds for cabin material bonding. Hydrogenation catalyst specialization remains concentrated in Chiba and Kawasaki petrochemical corridors.
South Korea
Metallocene catalyst production and specialized hydrogenation capacity for modified APAO architectures concentrate in Ulsan and Yeosu industrial complexes. Domestic electronics assemblers in Gyeonggi Province are adopting functionalized APAO variants for device housing requiring moisture resistance and polar substrate adhesion. MFDS-equivalent chemical substance notification requirements are extending import documentation timelines for adhesive raw materials.
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hydrogenation complexity and catalyst specialization tiers, with modified APAO architectures commanding pricing multiples over standard viscosity grades. The vendor base organizes into three strategic archetypes: integrated petrochemical majors with captive propylene feedstock positions, specialized polymer producers with metallocene catalyst expertise, and adhesive formulators with direct OEM specification authority. Dominant competitive moves include backward integration into metallocene catalyst production and geographic expansion through technical service partnerships in underpenetrated packaging markets.
Among integrated petrochemical majors, Eastman Chemical Company exemplifies the feedstock-anchored archetype with hydrocarbon integration sustaining cost-competitive supply across multiple viscosity grades. Huntsman Corporation occupies a position within the specialized polymer tier through differentiated molecular architectures. Henkel AG & Company KGaA represents the formulation-integrated archetype controlling direct customer relationships with global packaging OEMs and specifying base polymer chemistry in approved adhesive recipes.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Huntsman Corporation |
| H.B. Fuller |
| Henkel AG & Company KGaA |
| Evonik Industries AG |
| REXtac LLC |
| Bostik |
| Arkema S.A. |
| Liaoyang Liaohua Qida Chemicals |
| Others |
Supply & Pricing Matrix
Global packaging OEMs with centralized materials engineering functions command specification authority that compresses pricing power for compounders and drives contract structures toward volume-based rebates. Their consolidated procurement tenders in China and Germany favor long-term offtake agreements with embedded price adjustment clauses tied to propylene feedstock indices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates modified APAO with silane grafting from medium-viscosity commodity grades and low-viscosity sprayable formulations. Price differentiation rests on hydrogenation complexity and metallocene catalyst specialization concentrated in South Korean and Japanese production facilities. Cost compression in standard viscosity tiers is intensifying because domestic Chinese producers are scaling metallocene capacity and eroding historical import premiums. Mid-sized European converters exhibit the sharpest price sensitivity due to REACH compliance costs, while Japanese automotive OEMs demonstrate minimal elasticity for silane-grafted grades specified in electric vehicle platforms.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston maintain 30-60 day inventory buffers for just-in-time compounding operations across European, Asian, and North American packaging corridors. Geographic supply concentration clusters in South Korea, Japan, and China, where Ulsan and Yeosu industrial complexes anchor metallocene catalyst production and specialized hydrogenation capacity. Raw material dependencies draw from propylene monomer, metallocene catalyst systems, and hydrogenation reagents sourced from integrated petrochemical complexes. Single-source vulnerability around metallocene catalyst expertise creates chokepoint exposure for European and North American formulators. Distribution runs through bulk bag and drum configurations for mid-sized compounders, with intermediate bulk containers capturing share in automated automotive adhesive production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH carbon accounting requirements in Europe create compliance cost premiums that South Korean and Japanese producers with verified low-carbon hydrogenation processes can undercut through technical service partnerships in underpenetrated Indian packaging markets.
For Market Incumbents: Anticipate propylene feedstock volatility and Asian supply concentration by securing captive hydrogenation capacity or long-term catalyst supply agreements with South Korean producers. Backward integration into metallocene catalyst production in Ulsan or Chiba corridors defends margin position against domestic Chinese capacity expansion. Prioritize REACH registration documentation with complete SVHC screening to accelerate European personal care packaging qualification cycles ahead of ECHA evaluation timeline extensions. For New Entrants and Emerging Players: Capture Maharashtra and Gujarat carton sealing operations where technical service presence remains sparse and APAO penetration lags solvent-based alternatives. Target silane-grafting convergence in electronics assembly applications requiring moisture resistance and polar substrate adhesion, where specification authority has not yet consolidated around incumbent adhesive recipes. Establish local compounding partnerships with domestic Indian converters rather than direct polymer import models. For Investors and Strategic Acquirers: Specialized adhesive formulators with direct OEM specification authority are the most active acquirer in this space, seeking polymer producers with metallocene catalyst expertise to secure supply chain control. Long-term viability centers on hydrogenation complexity differentiation and geographic diversification beyond East Asian catalyst concentration. Watch for EPA VOC limit enforcement acceleration in Midwest packaging corridors as the signal indicating inflection toward solvent-free formulation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Catalyst Production | Eastman Chemical Company's hydrocarbon feedstock position enables captive catalyst supply security across viscosity grades. |
| Green Manufacturing Transition | Verified low-carbon hydrogenation processes unlock preferential REACH qualification status under EU Green Deal carbon accounting. |
| Long-term Supply Agreement | German automotive OEMs specify APAO content minimums in annual procurement tenders with embedded volume commitments. |
| Joint Venture | Technical service partnerships in Maharashtra and Gujarat accelerate local qualification cycles for carton sealing applications. |
| Capacity Expansion | Ulsan and Yeosu industrial complexes anchor modified APAO hydrogenation capacity for silane-grafted automotive grades. |
Research Methodology
Bottom-up adhesive formulation modeling reconciled against top-down polymer production tracking forms the analytical core of this study. Primary interviews with adhesive compounders, automotive OEM materials engineers, packaging procurement managers, and metallocene catalyst technical directors were validated against secondary sources including customs and trade data, SEC 10-K filings from integrated petrochemical majors, REACH registration databases, and ECHA substance evaluation protocols. Triangulation between demand-side qualification timelines and supply-side capacity announcements ensures segmentation integrity across viscosity grades and modified architectures.
Historical trendline analysis of propylene feedstock pricing, metallocene catalyst deployment rates, and EPA VOC enforcement patterns established baseline growth parameters. The projection framework models demand across viscosity grade, application segment, end-use industry, and regional production hub dimensions. CAGRs were derived from adhesive consumption intensity ratios per corrugated container output, automotive interior trim content per vehicle, and electronics assembly unit forecasts. Industry-specific inputs include e-commerce fulfillment center buildout rates in Zhejiang and Jiangsu provinces and electric vehicle platform thermal specification evolution.
Propylene monomer price shocks, ECHA evaluation timeline extensions, and metallocene catalyst supply disruptions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented supply chain configurations and regulatory enforcement patterns without claiming predictive certainty. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market