
 HFO (Hydrofluoro-Olefin) Refrigerants Market | 2026-2036
HFO (Hydrofluoro-Olefin) Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
HFO (Hydrofluoro-Olefin) Refrigerants Market Insights
Phase-down mandates for high-GWP hydrofluorocarbons is tilting the refrigeration technology stack toward unsaturated fluoroolefin chemistry with near-zero ozone depletion potential. Honeywell International Inc. leverages its proprietary manufacturing process for HFO-1234yf to anchor supply relationships with Detroit-based automotive OEMs. The Chemours Company competes through backward integration into fluorinated feedstock production, while Arkema specializes in HFO-1234ze formulations for commercial foam-blowing and stationary cooling applications.
Hydrofluoro-olefins are unsaturated organic fluorine compounds containing at least one carbon-carbon double bond, with HFO-1234yf exhibiting a global warming potential below one and atmospheric lifetimes measured in days rather than decades. Their primary industrial purpose is to replace HFC refrigerants in cooling circuits subject to environmental regulation. HFO-1234yf dominates automotive retrofit and original equipment demand as the standard R-134a successor under EU F-Gas Regulation and EPA SNAP program requirements. Commercial refrigeration applications for HFO-1234ze and HFO-1336mzz are expanding fastest in supermarket cascade systems and industrial chillers where toxicity and flammancy constraints are manageable. Cooling systems as an application category occupies the deepest margin pool due to long service intervals and captive refrigerant recovery protocols.
The EU F-Gas Regulation, EPA SNAP program, and Kigali Amendment to the Montreal Protocol collectively restrict market access for legacy HFC formulations and mandate GWP thresholds that only HFO chemistry satisfies at commercial scale. Japan's METI refrigerant certification scheme and China's GB standards for fluorocarbon alternatives further fragment compliance requirements across manufacturing jurisdictions. Stakeholders must monitor divergence between regional flammability classification standards and service technician certification rules, as these determine retrofit economics and aftermarket refrigerant availability.
Market Dynamics
EPA SNAP rules and the Kigali Amendment are compressing the allowable global warming potential for refrigerants, forcing original equipment manufacturers to redesign thermal management systems around unsaturated fluoroolefin chemistry with sub-1 GWP ratings.
Growth Catalysts
- Automotive OEM conversion schedules:Detroit-based vehicle manufacturers face binding phase-down timelines under EPA SNAP that mandate HFC-134a replacement in new model year production lines.
- EU F-Gas Regulation:The European framework imposes stepped GWP ceilings that disqualify legacy hydrofluorocarbons from commercial refrigeration and mobile air conditioning applications.
- Stationary cooling retrofit demand:Supermarket operators in Germany and France are accelerating cascade system upgrades to avoid refrigerant quota penalties under national implementation schemes.
Market Restraints
- Fluorinated feedstock concentration:Manufacturing of HFO-1234yf precursor chemicals clusters in Chinese industrial zones, exposing supply chains to export licensing volatility.
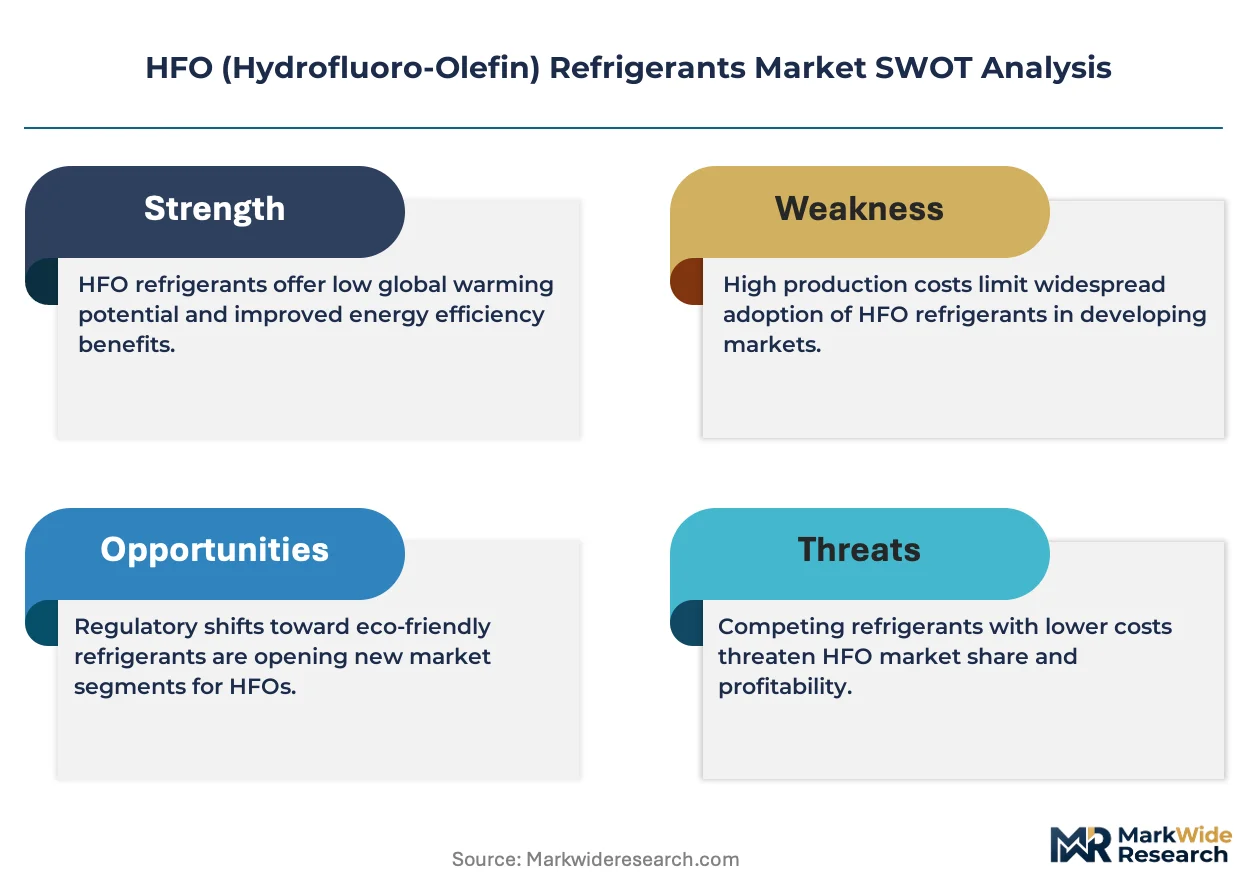
- Flammability classification friction:Divergent A2L handling standards between ASHRAE guidelines and EU ATEX directives complicate technician training and service tool standardization.
- Patent-thicket licensing costs:Proprietary manufacturing processes for unsaturated fluoroolefins impose royalty burdens that inflate unit economics versus commodity HFC alternatives.
Strategic Opportunities
- India's cooling action plan:The country's Bureau of Energy Efficiency is drafting refrigerant specifications for commercial cold chain expansion that favor low-GWP alternatives.
- Data center liquid cooling convergence:HFO-1336mzz formulations are penetrating two-phase immersion systems as thermal design power thresholds exceed air-cooling limits.
- Marine transport refrigeration:Container shipping lines operating EU-flagged vessels face MRV regulation compliance gaps that HFO-based retrofits can address.
Industry Challenges
- A2L certification bottlenecks:HVAC technician licensing bodies in the United States and Germany are struggling to scale qualified service personnel ahead of refrigerant transition deadlines.
- Legacy system incompatibility:Existing R-134a infrastructure requires seal material replacement and compressor oil conversion, extending payback periods for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HFO (Hydrofluoro-Olefin) Refrigerants Market |
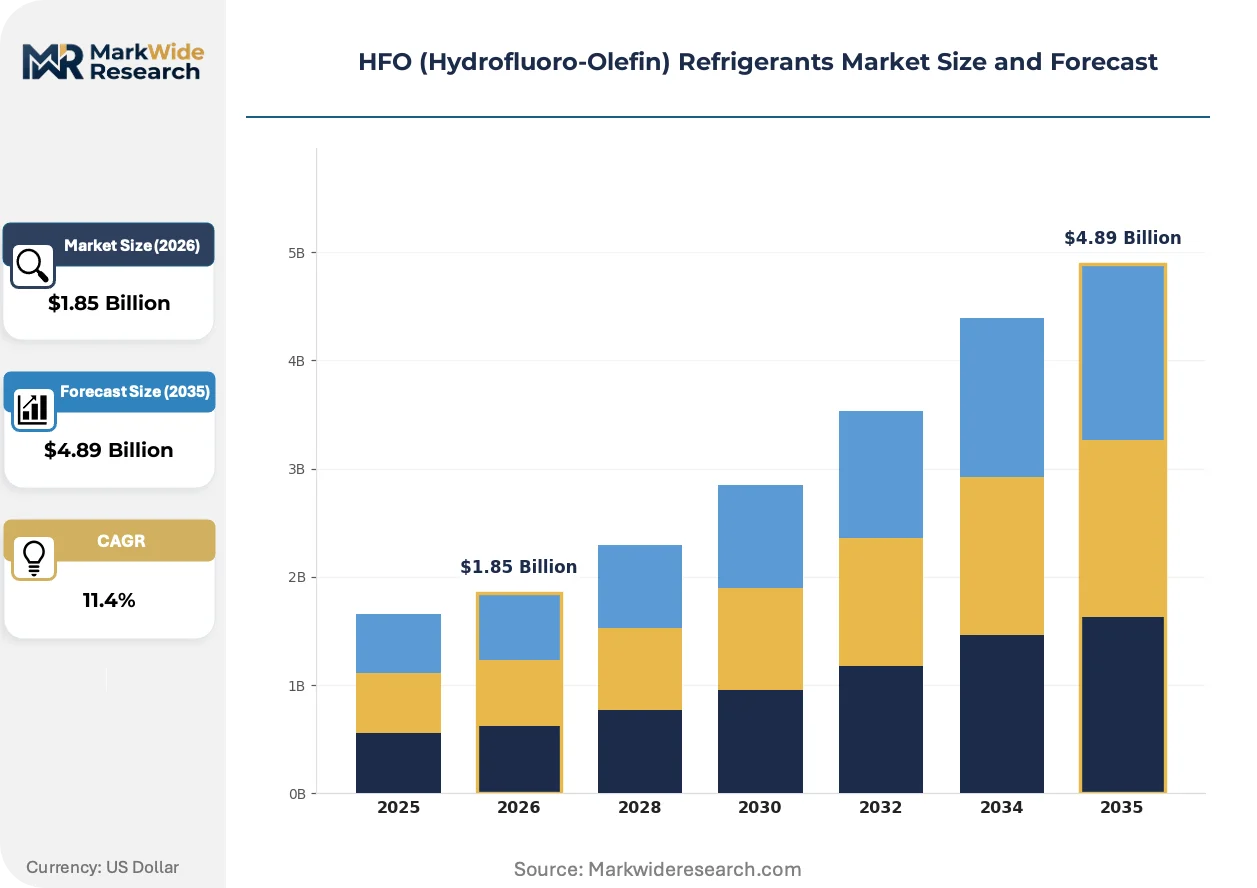
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFO-1234yf, HFO-1234ze, HFO-1336mzz, HFO-1233zd End User: Automotive, Commercial Refrigeration, Air Conditioning, Industrial Application: Cooling Systems, Chillers, Heat Pumps, Refrigerators Installation Type: Centralized, Mini-Split, Mobile, Portable |
| Companies Covered | Honeywell International Inc., The Chemours Company, Arkema, Linde PLC, Daikin Industries, Ltd., Mitsubishi Electric, AGC Chemicals, Zhejiang Juhua Co., Ltd., Navin Fluorine International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HFO (Hydrofluoro-Olefin) Refrigerants Market Trends and Innovations
Refrigerant chemistry is pivoting from saturated hydrofluorocarbons to unsaturated fluoroolefins, with formulation science and handling infrastructure racing to match regulatory velocity.
Low-GWP HFO blends are rendering obsolete the high-GWP HFC-134a and R-404A formulations that dominated automotive and commercial cooling for three decades. German supermarket chains and Japanese automotive suppliers are converting production lines at accelerated cadences to preempt quota restrictions. The transition is compressing margins for legacy refrigerant distributors while elevating value capture toward formulation patent holders.
The Kigali Amendment's phasedown schedule is tightening binding GWP ceilings across ratifying nations, with the United States implementing EPA SNAP rules that prohibit specific high-GWP refrigerants in new equipment categories annually. Industrial consequence includes forced obsolescence of R-134a in mobile air conditioning and R-404A in commercial refrigeration. European OEMs are responding fastest, integrating HFO-1234yf into vehicle platforms ahead of 2025 model year deadlines.
Service contracting is unbundling refrigerant supply from maintenance agreements as buyers seek price transparency on fluorinated gas purchases. Large fleet operators in China and the United States are direct-sourcing HFO formulations through chemical distributors rather than HVAC service intermediaries. The shift is most visible in commercial transport refrigeration, where logistics companies operating cross-border routes face fragmented refrigerant availability and prefer captive supply arrangements.
HFO (Hydrofluoro-Olefin) Refrigerants Market Segmentation
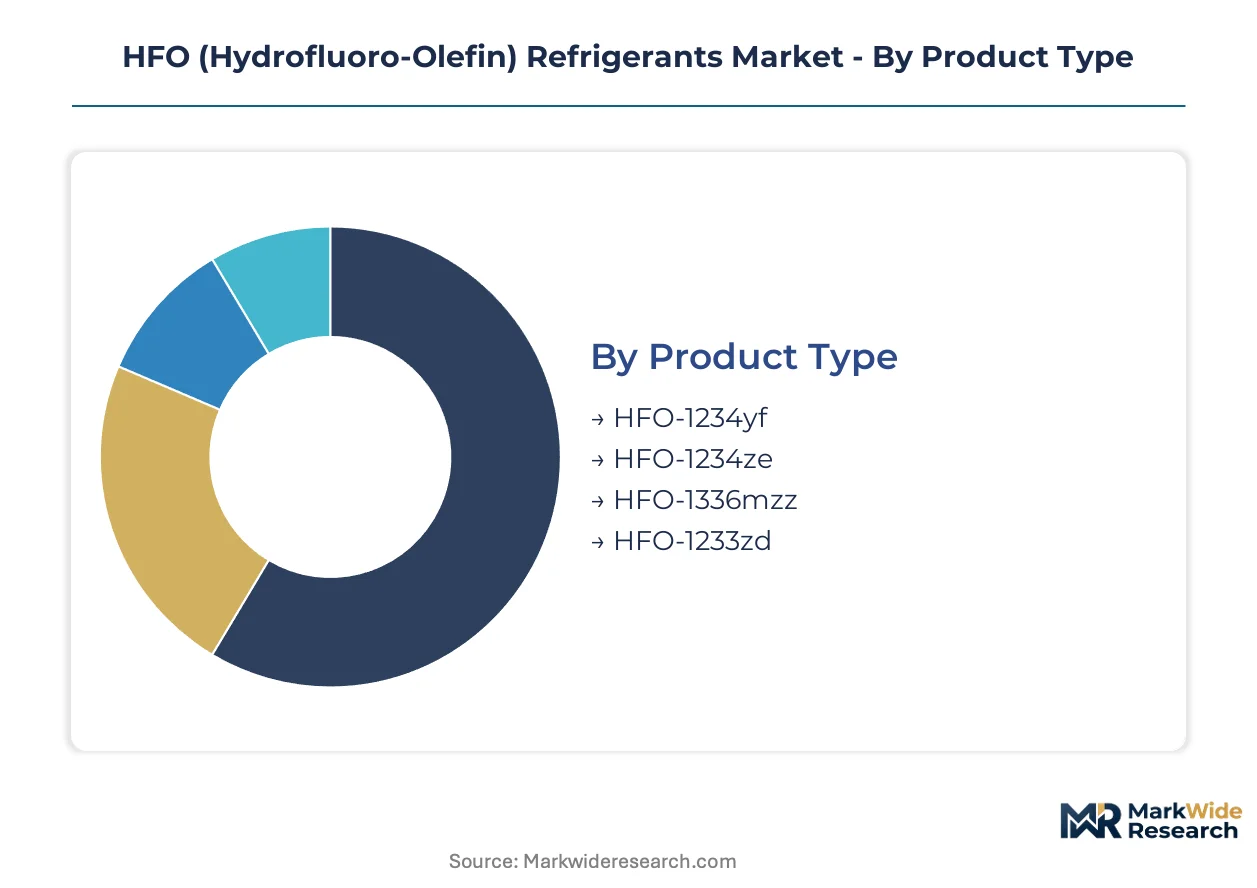
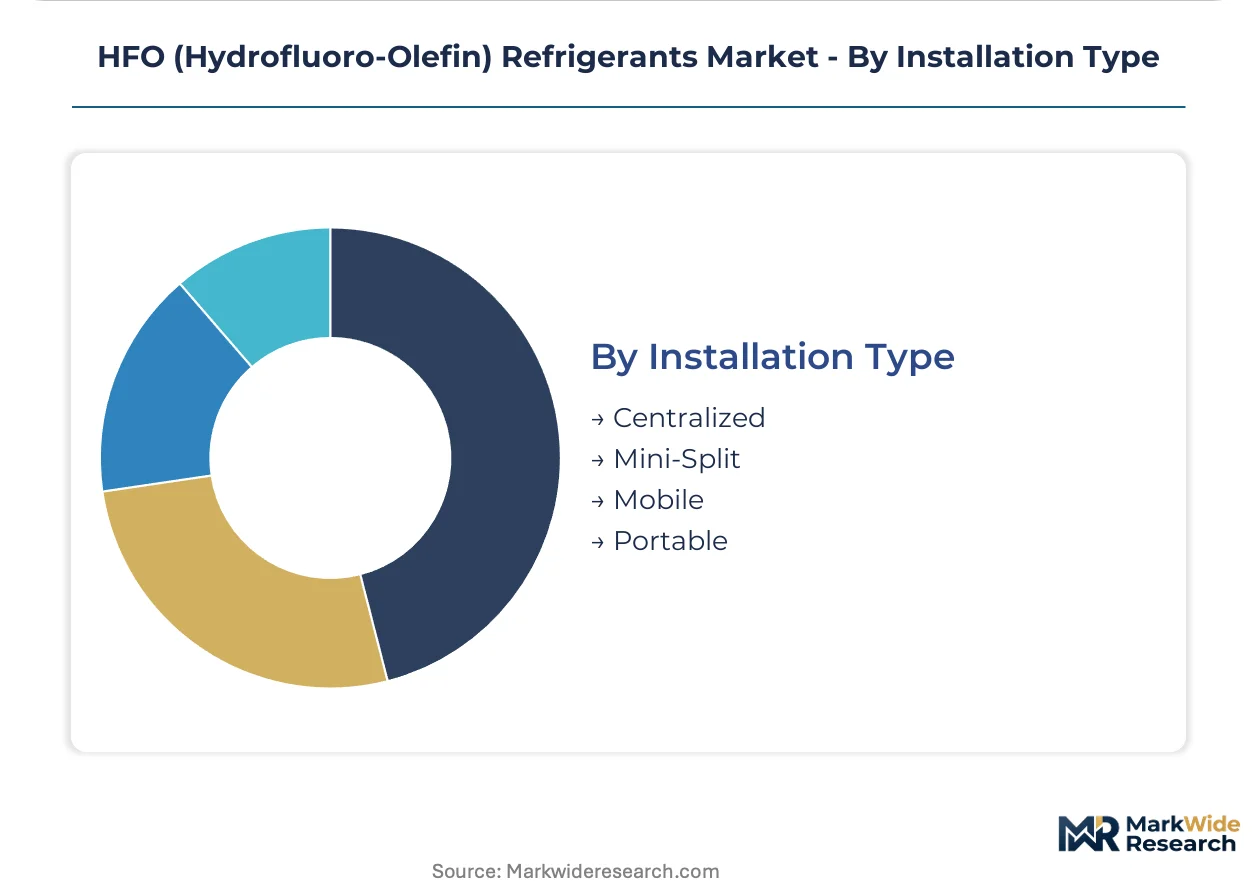
HFO refrigerant procurement patterns diverge sharply across product chemistries and installation contexts. Service intensity, retrofit compatibility, and regulatory phase-down timelines determine margin capture and distributor positioning in each segment.
Product Type:
After-sales service intensity varies dramatically by HFO chemistry, with automotive-grade formulations demanding specialized recovery equipment and technician certification that commodity blends do not require.
- HFO-1234yf:This unsaturated fluoroolefin carries a GWP below one and serves as the designated replacement for R-134a in vehicle air conditioning. Detroit OEMs and German automotive suppliers anchor demand as EPA SNAP and EU F-Gas deadlines compress conversion windows. Service networks require A2L-rated tools and refrigerant identifiers, elevating aftermarket capture rates for certified distributors.
- HFO-1234ze:A lower-pressure variant optimized for commercial foam-blowing and stationary cooling applications where flammability constraints are manageable. Supermarket operators in France and Germany specify this chemistry for cascade refrigeration systems to preempt national quota penalties under EU implementation schemes.
- HFO-1336mzz:Penetrates data center liquid cooling and industrial chiller segments as thermal design power thresholds exceed air-cooling limits.
- HFO-1233zd:Targets blowing agent applications and low-pressure industrial cooling circuits with extended atmospheric lifetimes relative to other HFO variants.
By volume, HFO-1234yf leads. By growth pace, HFO-1336mzz is ahead.
End User:
Cost tier stratification separates premium-specification automotive and industrial buyers from price-sensitive commercial refrigeration operators.
- Automotive:OEM conversion schedules under EPA SNAP and Kigali Amendment mandates drive specification lock-ins years ahead of production. Tier 1 suppliers in Japan and Germany qualify refrigerant batches against proprietary compressor warranties, creating captive supply relationships.
- Commercial Refrigeration:Supermarket chains and cold storage operators face stepped GWP ceilings that disqualify legacy R-404A. German and French national implementation schemes impose refrigerant quota penalties that accelerate cascade system upgrades.
- Air Conditioning:Mini-split and centralized residential systems in China and the United States transition toward HFO blends as GB standards and SNAP rules tighten.
- Industrial:Process cooling and pharmaceutical manufacturing facilities specify high-purity HFO formulations with batch traceability requirements.
Automotive commands premium pricing. Commercial Refrigeration offers the deepest retrofit volume pool.
Application:
Volume concentration clusters in cooling systems where long service intervals and captive recovery protocols deepen margin pools.
- Cooling Systems:Mobile and stationary air conditioning circuits dominate unit demand. Automotive MAC and commercial transport refrigeration in China and the United States drive specification velocity as fleet operators seek cross-border refrigerant availability.
- Chillers:Industrial and district cooling infrastructure in Germany and Japan converts toward low-GWP alternatives ahead of equipment end-of-life. Two-phase immersion systems for data centers specify HFO-1336mzz as thermal loads intensify.
- Heat Pumps:Residential and commercial heating electrification in Europe accelerates adoption of A2L-rated refrigerants in reverse-cycle equipment.
- Refrigerators:Domestic appliance manufacturers specify HFO-1234ze for foam insulation blowing agents and secondary cooling loops.
Cooling Systems holds the largest installed base. Chillers is climbing the fastest.
Installation Type:
Customer type fragmentation separates centralized infrastructure buyers from distributed mini-split and mobile equipment purchasers.
- Centralized:Large-format commercial and industrial facilities in Germany and China specify engineered HFO systems with integrated leak detection and automated refrigerant recovery. Procurement runs through mechanical contractors with EPA Section 608 or EU F-Gas certification.
- Mini-Split:Residential and light commercial ductless systems in Japan and the United States transition toward lower-GWP refrigerants as regional standards tighten. Installation volume concentrates in replacement markets with shorter payback periods.
- Mobile:Vehicle-mounted transport refrigeration units face fragmented refrigerant availability across cross-border routes. Fleet operators in the United States and China direct-source HFO formulations to ensure supply continuity.
- Portable:Temporary cooling and spot air conditioning equipment represents a price-sensitive segment with limited HFO penetration due to equipment cost premiums.
Centralized dominates value capture. Mini-Split offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese chemical manufacturers export HFO-1234yf precursors to automotive assembly plants in Germany and the United States, creating a trade-flow corridor that concentrates conversion demand in these three manufacturing centers.
United States
Detroit-based OEMs face binding EPA SNAP deadlines that mandate HFC-134a elimination from new vehicle platforms. The EPA's phasedown schedule prohibits high-GWP refrigerants in mobile air conditioning on specific model year timelines. Michigan and Ohio automotive corridors anchor domestic HFO-1234yf consumption as Tier 1 suppliers qualify refrigerant batches against compressor warranties.
Germany
German supermarket operators accelerate cascade system retrofits to preempt EU F-Gas quota penalties on refrigerant purchases. The EU F-Gas Regulation imposes stepped GWP ceilings that disqualify legacy R-404A from commercial refrigeration. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate stationary cooling demand as facility operators convert ahead of equipment end-of-life.
China
Domestic manufacturing of HFO-1234yf expands to serve both export markets and domestic automotive production under tightening GB standards. China's Ministry of Ecology and Environment implements national refrigerant management schemes that align with Kigali Amendment commitments. Yangtze River Delta chemical zones supply fluorinated feedstocks to global formulation plants while Shanghai and Guangzhou automotive hubs drive local absorption.
Japan
Japanese automotive suppliers qualify HFO formulations against proprietary thermal management specifications for export vehicle platforms. METI refrigerant certification schemes fragment compliance requirements for equipment manufacturers serving multiple jurisdictions. Kansai and Chubu industrial corridors concentrate compressor manufacturing and refrigerant blending capacity.
India
The Bureau of Energy Efficiency drafts refrigerant specifications for commercial cold chain expansion that favor low-GWP alternatives. India's cooling action plan targets temperature-controlled logistics infrastructure as agricultural export capacity scales. Maharashtra and Gujarat pharmaceutical manufacturing clusters generate demand for high-purity HFO formulations with batch traceability requirements.
HFO (Hydrofluoro-Olefin) Refrigerants Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical producers with captive fluorinated feedstock production and proprietary manufacturing processes for unsaturated fluoroolefins. Three strategic archetypes dominate: multinational diversified chemicals conglomerates with patent-protected HFO processes, regional fluorochemical specialists with backward integration into precursor supply, and industrial gas distributors with refrigerant blending and logistics networks. Competitive moves concentrate on capacity expansion in Chinese industrial zones and strategic partnerships with automotive OEMs for refrigerant specification lock-ins.
Among multinational diversified chemicals conglomerates, Honeywell International Inc., The Chemours Company, and Arkema occupy positions that exemplify the patent-holding tier. These entities anchor supply relationships through proprietary process technology rather than commodity positioning. Regional specialists including Zhejiang Juhua Co., Ltd. and Navin Fluorine International Limited represent the feedstock-integrated archetype with manufacturing concentration in Chinese and Indian chemical corridors respectively.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| The Chemours Company |
| Arkema |
| Linde PLC |
| Daikin Industries, Ltd. |
| Mitsubishi Electric |
| AGC Chemicals |
| Zhejiang Juhua Co., Ltd. |
| Navin Fluorine International Limited |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta-to-Detroit chemical freight corridor transmits cost volatility from Chinese fluorinated feedstock zones directly into North American automotive refrigerant pricing, compressing margins for distributors while amplifying price differentiation between patent-licensed HFO-1234yf and commodity HFC alternatives.
Pricing Analysis
The technology-generation pricing gap separates first-generation HFO-1234yf formulations from legacy R-134a stockpiles and emerging HFO-1336mzz next-generation blends. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with automotive OEMs least price-sensitive due to warranty lock-ins while commercial refrigeration operators face acute cost compression. Pricing pressure stems from patent-thicket royalty burdens that inflate unit economics versus commodity HFC alternatives, forcing fleet operators to extend payback calculations for retrofit investments.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta chemical manufacturers to German and U.S. formulation plants have become standard supply-chain finance facilities as feedstock concentration intensifies. Manufacturing of HFO-1234yf precursor chemicals clusters in China, with secondary blending capacity in Germany and Japan, creating single-source vulnerability around fluorinated feedstock export licensing. The supply chain draws from trifluoropropene, hydrogen fluoride, and chlorinated intermediates as critical inputs. Distribution runs through certified mechanical contractors with EPA Section 608 or EU F-Gas technician credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the cyclical trough of HFC phase-down regulatory lag, with EPA SNAP and Kigali Amendment enforcement now accelerating replacement demand across automotive and commercial cooling segments.
For Market Incumbents: Insulate proprietary formulation margins by deepening backward integration into Chinese fluorinated feedstock production and securing A2L certification capacity ahead of technician shortage bottlenecks. Patent-holding chemical conglomerates face emerging entrant pressure from regional feedstock-integrated specialists in India and China, making captive precursor supply the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's commercial cold chain expansion as the Bureau of Energy Efficiency finalizes low-GWP refrigerant specifications for agricultural logistics infrastructure. The most penetrable white-space sits in data center liquid cooling applications for HFO-1336mzz, where thermal design power thresholds exceed air-cooling limits and incumbent patent positions remain less dense. A direct-sourcing go-to-market angle targeting cross-border fleet operators bypasses established HVAC service intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors feedstock-integrated regional specialists with backward integration into precursor chemistry and established relationships with domestic automotive OEMs. Long-term viability over the next decade hinges on regulatory enforcement consistency across EPA SNAP, EU F-Gas, and Kigali Amendment ratification timelines. The signal to watch is A2L technician certification throughput in the United States and Germany as a leading indicator of retrofit execution capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Captive fluorinated feedstock supply from Yangtze River Delta zones insulates against export licensing volatility. |
| A2L Technician Certification Scale-Up | EPA Section 608 and EU F-Gas credential expansion unlocks aftermarket service revenue pools ahead of conversion deadlines. |
| Patent Licensing Partnership | Proprietary HFO-1234yf process agreements with Detroit OEMs lock in specification standards across model year transitions. |
| India Cold Chain Market Entry | Bureau of Energy Efficiency refrigerant specifications favor low-GWP alternatives in agricultural logistics infrastructure buildout. |
| Data Center Liquid Cooling Formulation | HFO-1336mzz penetration into two-phase immersion systems captures thermal load growth beyond air-cooling thresholds. |
Research Methodology
The analysis maps automotive air conditioning, commercial refrigeration, industrial chillers, and foam-blowing applications, each validated through refrigerant procurement managers at Tier 1 automotive suppliers, supermarket chain facility directors, and HVAC mechanical contractors. Primary interviews with plant managers at Chinese fluorochemical zones, EPA-certified technician training bodies, and European supermarket operators combined with secondary validation from customs trade data, SEC 10-K filings of patent-holding chemical conglomerates, and EU F-Gas quota registry records. Bottom-up volume builds triangulated against top-down regulatory phase-down schedules.
The assumption-set held fixed EPA SNAP enforcement timelines and Kigali Amendment ratification status while varying automotive OEM conversion cadences and A2L technician certification throughput across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, installation type, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and refrigerant quota trajectory modeling incorporated automotive production forecasts and commercial refrigeration retrofit pipeline data as industry-specific inputs.
Stress conditions across fluorinated feedstock export licensing volatility, A2L flammability standard divergence, and patent expiration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
North America Quicklime Market