
 Paper Machine Systems Market | 2026-2036
Paper Machine Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Machine Systems Market Analytics
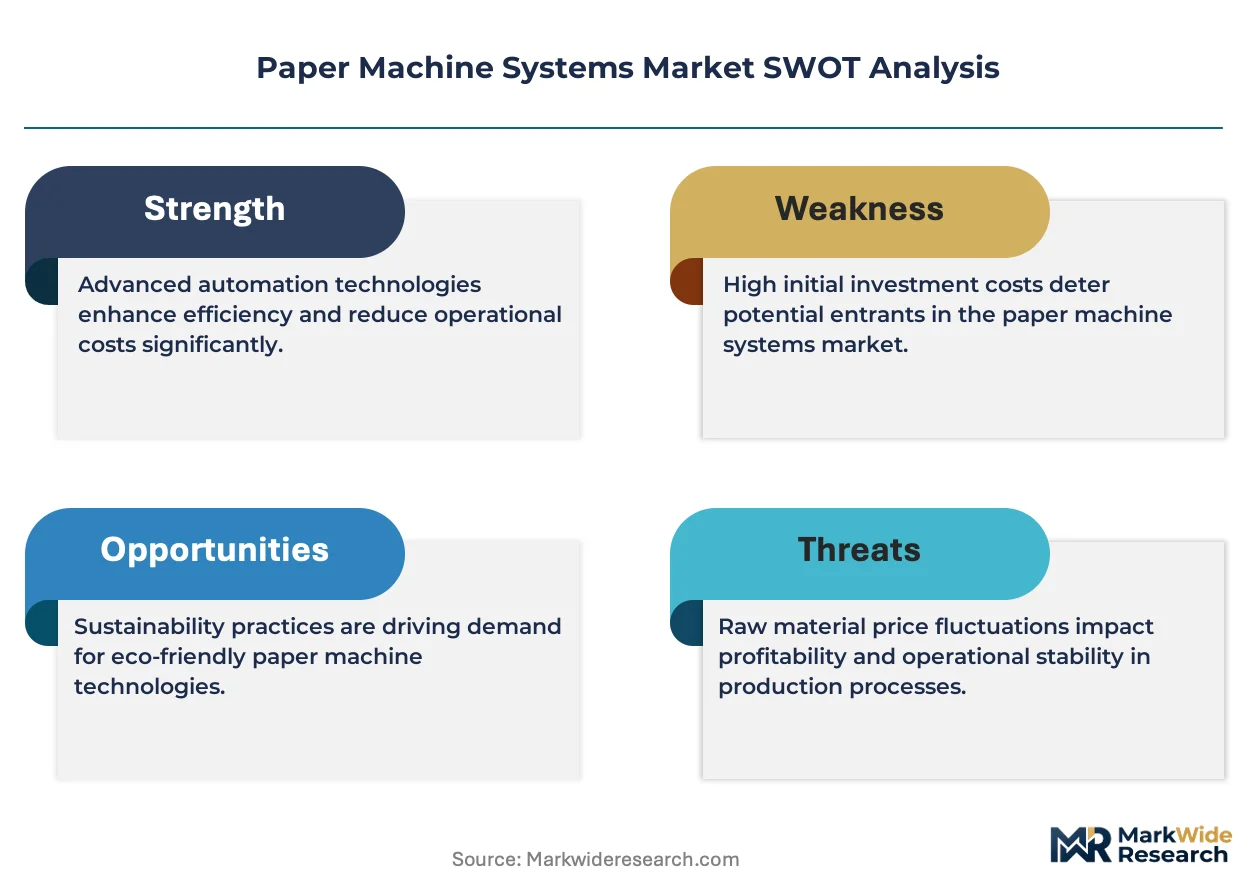
Skilled millwright and automation technician availability is collapsing across mature pulp-producing regions, forcing OEMs to redesign service models around remote diagnostics and predictive maintenance. Valmet leverages its digital platform footprint to capture recurring service revenue from mills in Scandinavia and North America. Voith anchors its competitive stance through deep backward integration into rolls and fabrics, controlling critical wear-component supply. Andritz specializes in rebuild and retrofit scope, occupying a niche where capital-constrained mills extend asset life rather than commission greenfield lines.
Paper machine systems encompass the integrated mechanical, thermal, and control equipment that converts diluted pulp slurry into finished reels through sequential drainage, pressing, drying, and winding operations. Modern machines operate at wire speeds exceeding 2,000 meters per minute for lightweight grades, demanding precision in stock preparation consistency and cross-machine moisture profile control. Mechanical presses and drying sections together represent the dominant capital allocation within new machine budgets, though margin pools increasingly shift toward automation solutions and digital sensor packages that reduce energy intensity per ton. Green technology retrofits command premium positioning as mills face Scope 1 and 2 emissions targets.
The EPA enforces Maximum Achievable Control Technology standards for pulp and paper effluent, directly shaping wet-end chemistry and water-loop closure requirements in US-based mills. REACH and the EU Green Deal mandate substitution of hazardous process chemicals and drive heat-recovery system upgrades across European installations. India's BIS certification for imported paper machinery creates a compliance threshold for foreign OEMs seeking access to its expanding packaging board sector. Stakeholders must monitor how carbon border adjustment mechanisms redefine the cost calculus between regional machine rebuilds and full replacement imports.
Market Dynamics
Skilled millwright and automation technician availability is collapsing across mature pulp-producing regions, forcing OEMs to redesign service models around remote diagnostics and predictive maintenance platforms.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Machinery efficiency standards tighten across Europe, compelling integrated mills in Germany to modernize aging stock with energy-recovery systems and advanced control packages.
- E-commerce packaging volume:Corrugated board producers in the United States and India expand machine capacity to serve fulfillment center demand, driving orders for high-speed linerboard machines.
- Heat pump drying:Steam compression technology replaces conventional cylinder drying in Scandinavian pilot installations, cutting Scope 1 emissions per ton of finished paper.
Market Restraints
- Specialized alloy supply concentration:Dryer cylinder castings and press roll shells depend on a limited supplier base in Germany and Japan, creating lead time vulnerability for rebuild projects.
- REACH chemical substitution timelines:European mills face compressed deadlines to replace hazardous wet-end additives, forcing unplanned chemistry system overhauls during already constrained maintenance windows.
- Recycled fiber quality degradation:Contamination rates in post-consumer OCC streams rise, reducing machine runnability and increasing broke generation that degrades effective output.
Strategic Opportunities
- India packaging board sector:BIS certification requirements filter out smaller foreign OEMs, creating protected market space for compliant suppliers with localized service infrastructure.
- Carbon border adjustment mechanisms:EU CBAM implementation revalues the cost calculus between regional machine rebuilds and full replacement imports, favoring European refurbishment specialists.
- Digital twin convergence with edge computing:Real-time simulation of sheet formation and drying profiles enables predictive grade changes without manual intervention, opening premium automation service contracts.
Industry Challenges
- Millwright apprenticeship gaps:Retirement waves in Finland and Canada outpace training pipeline output, forcing extended reliance on OEM field service for routine mechanical work.
- Legacy DCS integration complexity:1990s-era distributed control systems in North American mills resist seamless connection to modern IoT sensor networks, fragmenting data architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Machine Systems Market |
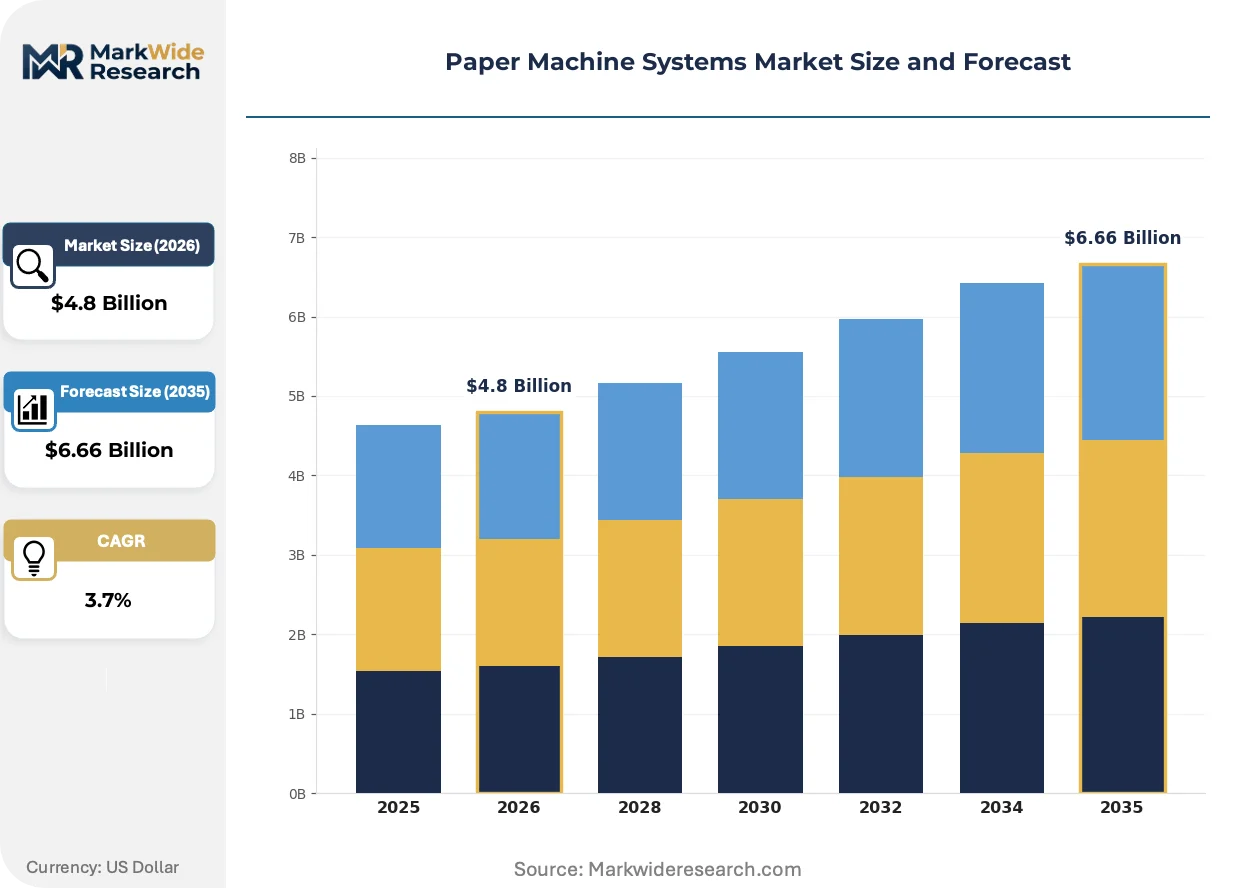
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Presses, Drying Sections, Control Systems, Reels End User: Pulp Manufacturers, Paper Manufacturers, Packaging Firms, Converters Technology: Digital Sensors, Automation Solutions, Energy Recovery, Green Technology Installation: On-site Installation, Off-site Assembly, Retrofit Solutions, Turnkey Projects |
| Companies Covered | Valmet, Voith, Metso, Andritz, Parason Machinery, Bellmer GmbH, Kadant, Mitsubishi Heavy Industries, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Machine Systems Market Evolving Landscape
Digitalization of machine operations is compressing the traditional divide between mechanical equipment supply and ongoing performance optimization services.
Advanced shoe press technology is displacing conventional roll presses in containerboard applications. Packaging producers in the United States adopt extended nip designs to achieve higher dryness before the drying section, cutting steam consumption. This displacement is compressing the installed base of traditional press configurations and redirecting capital toward integrated press-drying optimization packages.
EPA Maximum Achievable Control Technology standards for pulp and paper effluent tighten discharge limits on color, toxicity, and total suspended solids. US-based mills respond with closed water-loop designs and advanced biological treatment, particularly affecting virgin pulp facilities in the Southeast. The regulation is accelerating wet-end chemistry innovation as mills seek process additives compatible with zero-liquid-discharge configurations.
After-sales service unbundling reshapes buyer-supplier relationships in Scandinavia and North America. Maintenance contracts separate from original equipment purchases, with mills procuring predictive analytics and spare parts logistics as standalone subscriptions. This shift concentrates purchasing authority in mill reliability engineering teams rather than capital project departments, favoring vendors with established digital platform footprints.
Paper Machine Systems Market Segmentation
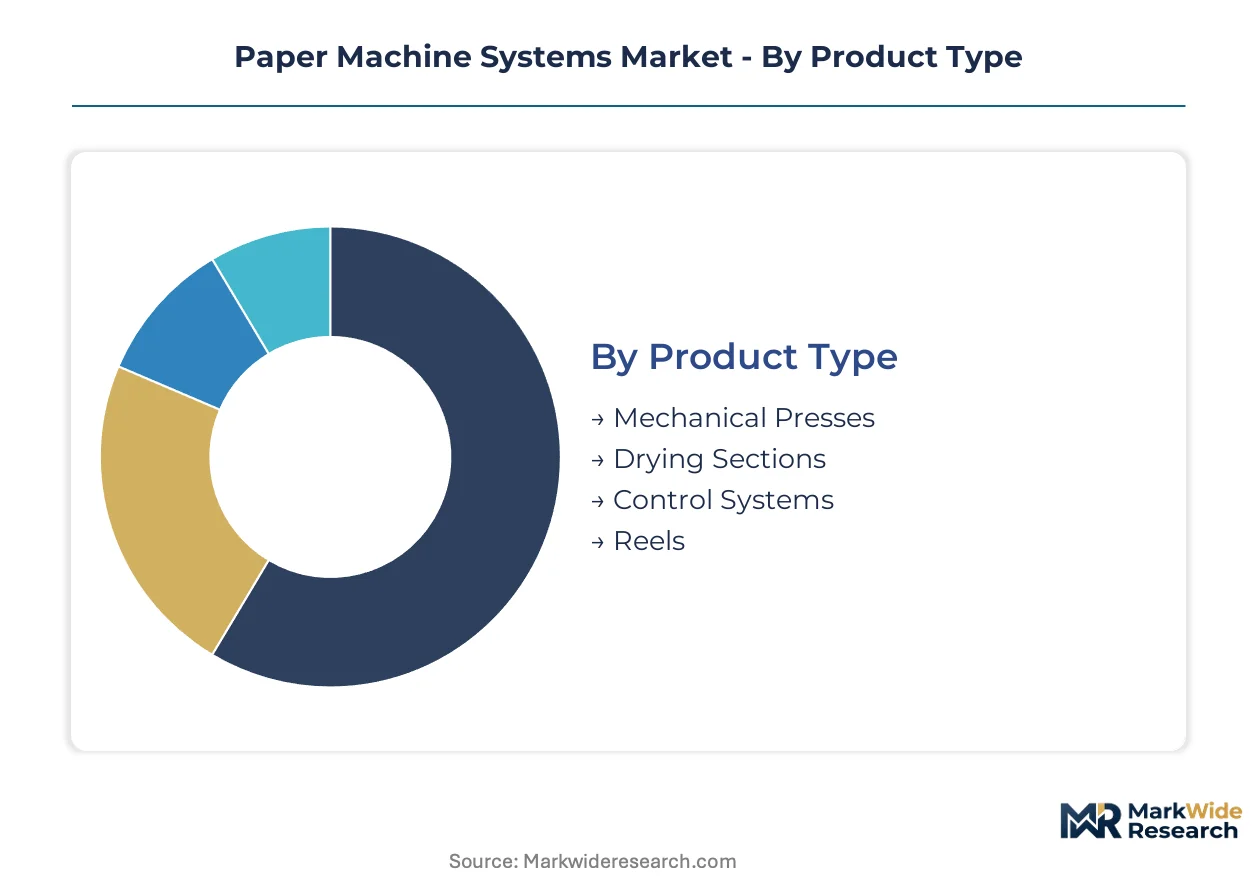
Paper machine systems fragment across product, technology, and installation dimensions that reshape procurement authority and margin capture. OEMs now structure commercial teams around these divides, recognizing that control systems and retrofit solutions command recurring revenue models distinct from capital-heavy drying sections.
Product Type:
Mechanical presses face the most acute substitution pressure from advanced shoe press configurations that displace conventional roll designs in linerboard applications.
- Mechanical Presses:Extended nip and shoe press configurations extract higher dryness before the drying section, cutting steam consumption per ton. Demand concentrates in United States corrugated board producers modernizing virgin pulp lines to serve e-commerce fulfillment centers.
- Drying Sections:Steam compression and heat pump technologies pilot in Scandinavian installations to eliminate Scope 1 emissions. German integrated mills drive replacement orders as EU Ecodesign for Sustainable Products Regulation tightens machinery efficiency standards.
- Control Systems:Cross-machine moisture profile control and stock preparation consistency algorithms enable wire speeds exceeding 2,000 meters per minute for lightweight grades.
- Reels:Precision winding equipment handles finished paper output at high-speed containerboard machines without sheet breaks.
Drying sections retain volume leadership; control systems hold the steepest expansion curve.
End User:
Customer type determines contract structure, with packaging firms shifting procurement toward outcome-based service agreements while pulp manufacturers retain capital project authority.
- Packaging Firms:Corrugated board producers in India and the United States expand machine capacity for fulfillment center demand, driving orders for high-speed linerboard configurations. BIS certification requirements filter supplier pools to compliant OEMs with localized service infrastructure.
- Paper Manufacturers:Virgin pulp facilities in the US Southeast respond to EPA Maximum Achievable Control Technology standards with closed water-loop designs and advanced biological treatment systems.
- Pulp Manufacturers:Integrated mills in Germany modernize aging stock with energy-recovery systems as Ecodesign regulation compels efficiency upgrades.
- Converters:Specialty finishing operations require precision reel handling and grade change flexibility without production stops.
Packaging firms capture the fastest share gains; paper manufacturers anchor installed base maintenance spend.
Technology:
Technology segmentation separates capital equipment from recurring revenue streams, with digital and automation solutions expanding margin pools beyond mechanical hardware.
- Automation Solutions:Predictive grade change algorithms and edge computing convergence enable real-time sheet formation simulation without manual intervention. Scandinavian and North American mills unbundle maintenance contracts from original equipment purchases, concentrating purchasing authority in reliability engineering teams.
- Digital Sensors:IoT networks monitor cross-machine moisture profiles and stock preparation consistency at wire speeds exceeding 2,000 meters per minute.
- Energy Recovery:Heat pump drying and steam compression technologies cut Scope 1 emissions per ton of finished paper in pilot Scandinavian installations.
- Green Technology:Retrofit packages command premium positioning as mills face Scope 1 and 2 emissions targets under EU Green Deal frameworks.
Automation solutions expand most quickly; green technology retrofits capture the highest margin premiums.
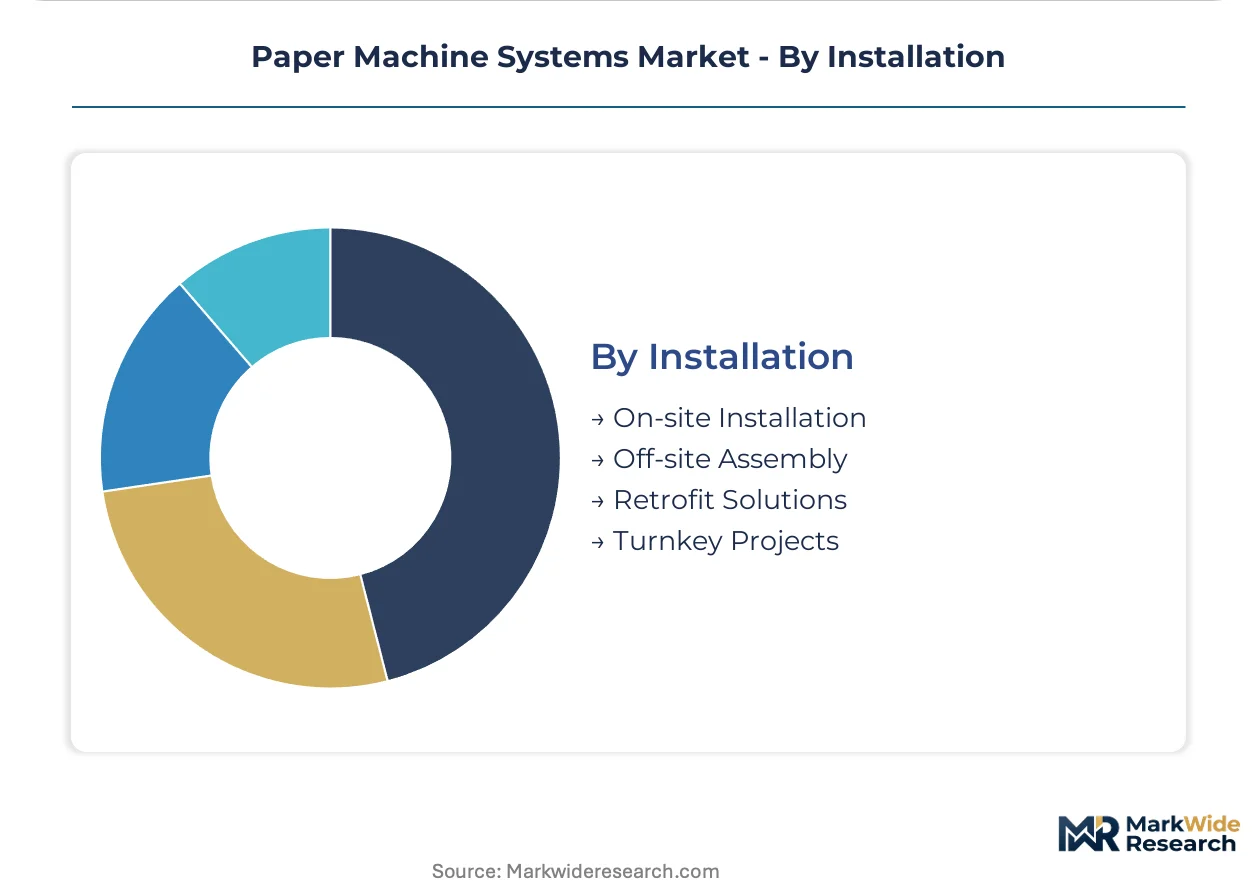
Installation:
Installation mode determines project risk allocation and OEM working capital exposure, with turnkey structures concentrating liability on suppliers.
- Retrofit Solutions:Capital-constrained mills extend asset life through rebuild and retrofit scope rather than commissioning greenfield lines, occupying a niche where specialized engineering commands premium pricing. Carbon border adjustment mechanisms revalue cost calculus between regional rebuilds and full replacement imports.
- Turnkey Projects:Integrated mills in Germany and India demand complete responsibility transfer for greenfield linerboard capacity additions.
- On-site Installation:Field assembly of large drying cylinders and press rolls requires millwright coordination where skilled technician availability is collapsing across mature pulp-producing regions.
- Off-site Assembly:Modular construction reduces site labor exposure where apprenticeship gaps in Finland and Canada outpace training pipeline output.
Retrofit solutions gain share fastest; turnkey projects retain the highest average contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations anchor United States demand, while EU Ecodesign standards reshape European procurement. India's BIS certification filters supplier pools as packaging board capacity expands.
United States
E-commerce fulfillment center expansion drives corrugated board machine orders across the Southeast. EPA Maximum Achievable Control Technology standards tighten effluent discharge limits, compelling closed water-loop designs. Virgin pulp facilities in Georgia and Alabama modernize wet-end chemistry systems to meet zero-liquid-discharge configurations.
Germany
Integrated pulp-to-paper mills face compressed deadlines to replace aging stock with energy-recovery equipment. EU Ecodesign for Sustainable Products Regulation mandates machinery efficiency upgrades across Baden-Württemberg and North Rhine-Westphalia. Voith's backward integration into rolls and fabrics secures supply chain control for regional rebuild projects.
India
Packaging board producers expand capacity to serve domestic consumer goods demand and export markets. BIS certification requirements for imported machinery create compliance thresholds that filter smaller foreign OEMs. Gujarat and Maharashtra clusters attract compliant suppliers establishing localized service infrastructure.
Japan
Dryer cylinder casting expertise concentrates among specialized alloy suppliers serving regional rebuild markets. METI industrial efficiency programs accelerate heat-recovery system adoption in legacy installations. Equipment fabricators in Nagoya and Osaka anchor aftermarket service networks across mature pulp-producing regions.
Finland
Scandinavian pilot installations deploy steam compression drying to eliminate Scope 1 emissions per ton of finished paper. Valmet leverages its digital platform footprint to capture recurring service revenue from regional mills. Skilled millwright retirement waves in the Tampere region outpace apprenticeship pipeline output.
Paper Machine Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in drying section and control system supply. The middle tier fragments across regional rebuild specialists and component fabricators. Two strategic archetypes dominate: full-line OEMs with captive aftermarket platforms, and niche engineering houses focused on retrofit scope. Competitive moves center on digital service unbundling and backward integration into wear-component supply.
Among Nordic-based integrated suppliers, Valmet and Metso occupy positions defined by digital platform reach and pulp processing integration respectively. Voith anchors the German engineering tier through upstream control over critical consumables. Andritz exemplifies the retrofit-specialist archetype, serving capital-constrained mills extending asset life rather than commissioning greenfield capacity.
| Leading Market Players |
|---|
| Valmet |
| Voith |
| Metso |
| Andritz |
| Parason Machinery |
| Bellmer GmbH |
| Kadant |
| Mitsubishi Heavy Industries |
| IHI Corporation |
| Others |
Value Network & Pricing Analysis
Long-term maintenance contracts lock in both spare parts access and predictable service pricing for mills navigating skilled technician shortages across Scandinavia and North America. This contract structure concentrates purchasing authority in reliability engineering teams rather than capital project departments, reshaping how OEMs monetize aftermarket relationships.
Pricing Analysis
German and Japanese suppliers command 15-20% premiums over Asian competitors for dryer cylinder castings and press roll shells due to metallurgical certification standards. Three-tier pricing structure across premium, standard, and economy levels separates OEMs with captive digital platforms from component fabricators and regional rebuild specialists. Cost compression in standard mechanical equipment is intensifying as Indian packaging producers expand capacity and demand localized service infrastructure. Packaging firms in India exhibit highest price sensitivity due to BIS compliance costs, while integrated German mills prioritize energy-recovery specifications over upfront capital outlays.
Supply Chain Analysis
Extended lead times for specialized alloy dryer cylinder castings now stretch 8-14 months, forcing mills to pre-position critical spares before scheduled rebuild windows. Supply concentrates in Germany and Japan for press roll shells and drying section components, with India and China expanding fabrication capacity for standard mechanical assemblies. Raw material dependencies center on nickel-chromium-molybdenum alloys, high-grade carbon steel forgings, and ceramic roll coatings. Single-source vulnerability persists for large-diameter dryer cylinder castings exceeding 5 meters in diameter. Distribution runs through OEM-direct channels for complex rebuild scope, with third-party logistics providers handling standard spare parts fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the competitive landscape creates entry niches as digital service unbundling separates predictive analytics from original equipment purchases. This demand-side shift opens space for specialized automation vendors and regional rebuild specialists.
For Market Incumbents: Shield installed base relationships by deepening backward integration into wear-component supply, mirroring Voith's captive rolls and fabrics production. Accelerate digital platform deployment to capture recurring service revenue as mills unbundle maintenance contracts from capital purchases. Prioritize certification investment for India's BIS requirements to defend position against emerging regional competitors. For New Entrants and Emerging Players: Anchor in India's packaging board sector where BIS certification filters out smaller foreign OEMs and localized service infrastructure remains underdeveloped. Target retrofit solutions for capital-constrained North American mills facing EPA compliance deadlines without greenfield capital. Pursue partnership-based go-to-market models with established component fabricators to bypass heavy in-house manufacturing investment. For Investors and Strategic Acquirers: Capital is best deployed toward digital automation specialists with established edge computing platforms and recurring revenue visibility across the analysis window. Acquisition targets should demonstrate installed base penetration in Scandinavian or North American mills where technician shortages lock in long-term service contracts. Watch for inflection when carbon border adjustment mechanisms trigger accelerated European rebuild activity versus Asian import substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wear Components | Captive supply of press rolls and dryer fabrics secures margin control for Voith in German rebuild markets. |
| Digital Platform Deployment | Valmet's predictive analytics subscriptions capture recurring revenue as Scandinavian mills unbundle service contracts. |
| Green Technology Retrofit Packages | Heat pump drying pilots in Finland position early movers for EU Ecodesign compliance mandates. |
| Localized Service Infrastructure | BIS certification compliance in Gujarat and Maharashtra creates protected market space for compliant OEMs. |
| Modular Off-site Assembly | Reduced site labor exposure addresses millwright apprenticeship gaps in Finland and Canada. |
Research Methodology
A spread of perspectives from maintenance directors at integrated mills, OEM aftermarket service heads, plant engineers at packaging producers, and procurement leads at corrugated board manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement records, EU Ecodesign regulatory filings, BIS certification databases, and trade flow data from pulp and paper machinery customs classifications. Bottom-up equipment order tracking triangulated against top-down mill capacity utilization surveys.
Segmentation dimensions modeled include product type, end-user category, technology tier, and installation mode across the projection horizon. CAGRs derived from equipment shipment volumes, retrofit project backlogs, and digital service contract expansions. Forecast inputs incorporated wire speed evolution curves, energy intensity benchmarks per ton of finished paper, and regulatory compliance timeline probabilities.
Decision-makers should treat outputs as directional under assumptions of continued skilled technician shortage, stable alloy supply concentration, and phased CBAM implementation; material deviation would warrant model refresh. Specific risks include accelerated REACH chemical substitution timelines, sudden tariff adjustments on Asian machinery imports, and faster-than-expected heat pump drying adoption displacing conventional steam systems. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Overlay Paper Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Paper Making Machine Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Billing Paper Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Paper Based Laminates Market
Paper Products
Cheque Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Sawn Wood Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Softwood Pulp Market
Paper Products
Super Calendered Glassine Paper Market