
 Beneficiation Reagents Market | 2026-2036
Beneficiation Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Beneficiation Reagents Market Insights
ISO 14001 environmental management certification is rotating the competitive set toward suppliers with verified lifecycle credentials. BASF leverages its integrated polymer chemistry platform to control raw material quality for collector synthesis. Clariant anchors its position through specialized emulsion formulations that reduce solvent exposure at high-altitude Latin American mines. Solvay competes on alkali-activated reagent portfolios tailored to complex sulfide ores.
Beneficiation reagents are chemical formulations engineered to selectively separate target minerals from gangue material through surface chemistry modification, with active concentrations typically ranging from 10 to 500 grams per metric ton of ore processed. Their primary industrial purpose is enabling economically viable extraction from declining ore grades across copper, iron ore, phosphate, and rare earth operations. Flotation reagents command the largest value pool given their irreplaceable role in sulfide mineral separation, while flocculants represent the fastest-expanding category as tailings thickening and dry stacking mandates intensify water recovery requirements. Ore concentration applications consume the majority of volumes, though tailings treatment is emerging as a margin-rich segment where regulatory closure obligations create captive demand.
EPA effluent limitation guidelines in the United States restrict residual reagent discharge from mineral processing facilities, forcing formulation shifts toward biodegradable alternatives. ECHA REACH registrations in Europe impose full toxicity dossier requirements on imported collector chemistries, raising compliance costs for non-European suppliers. China's MEE standards on mine wastewater reuse mandate closed-circuit reagent recovery systems in new processing plant approvals. Stakeholders must monitor evolving tailings dam safety protocols across multiple jurisdictions, as these rules directly determine reagent selection criteria and supplier qualification timelines.
Market Dynamics
Ore grade depletion across Chilean and Peruvian copper belts is intensifying reagent consumption per ton of metal recovered, forcing suppliers to engineer higher-selectivity formulations for complex polymetallic feeds.
Growth Catalysts
- EPA effluent limitation guidelines:Mandates for residual reagent discharge reduction in US mineral processing facilities accelerate biodegradable collector adoption.
- Copper flotation intensity:Declining head grades in Chile's Atacama mining corridor drive volume expansion for xanthate collectors and polyglycol frothers.
- Dry stacking mandates:Tailings thickening requirements in Brazil's Minas Gerais iron ore district expand anionic flocculant demand for water recovery circuits.
Market Restraints
- Xanthate feedstock volatility:Carbon disulfide and caustic soda price swings compress formulation margins for sulfide collectors.
- ECHA REACH registration costs:Full toxicity dossier requirements for imported collector chemistries raise compliance barriers for non-European suppliers.
- Alkali-activated reagent substitution:Solvay's proprietary complex sulfide portfolios threaten conventional fatty acid collector market share.
Strategic Opportunities
- Rare earth element flotation:Underdeveloped separation chemistry for bastnäsite and monazite ores creates white space for novel collectors in Mountain Pass and Bayan Obo operations.
- China MEE wastewater reuse standards:Closed-circuit reagent recovery mandates in new processing plant approvals favor suppliers with closed-loop system integration capabilities.
- Digital reagent dosing platforms:Integration of machine learning with X-ray fluorescence sensors enables real-time collector optimization, displacing manual dosage protocols.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system verification delays supplier qualification for tier-one mining contracts by 12-18 months.
- Surface chemistry expertise scarcity:Shortage of flotation specialists with deep knowledge of zeta potential modification limits R&D throughput for custom formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beneficiation Reagents Market |
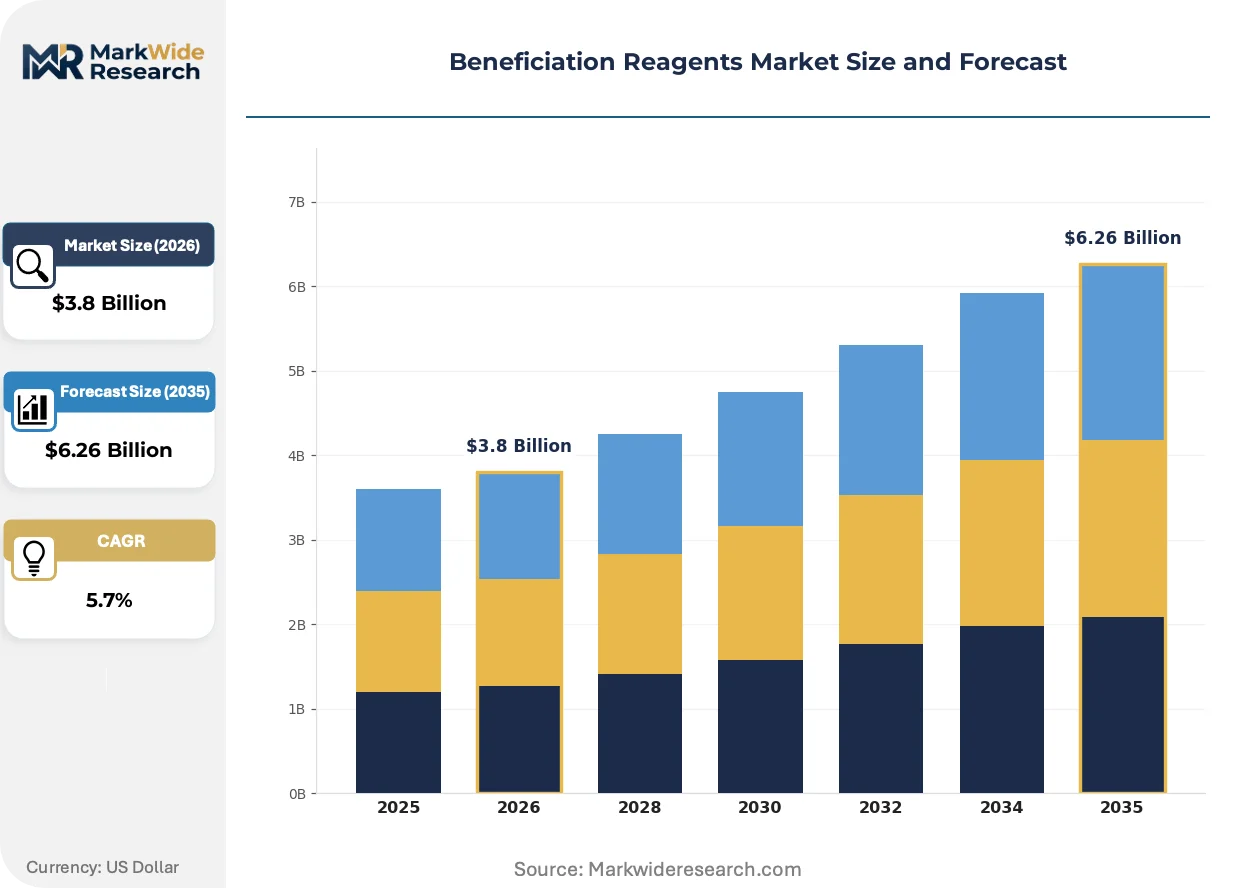
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flotation Reagents, Flocculants, Depressants, Collectors, Activators, pH Modifiers Application: Ore Concentration, Tailings Treatment, Wastewater Treatment, Mineral Recycling, Sludge Conditioning End User: Mining Contractors, Mineral Processing Plants, Metal Refiners, Chemical Suppliers Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | BASF, Clariant, Solvay, Orica, Nouryon, Ecolab, Evonik Industries, Chevron Phillips Chemical, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beneficiation Reagents Market Trends and Innovations
Formulation science is converging with process automation to deliver reagent systems that self-optimize against variable ore mineralogy, compressing the traditional assay-feedback loop that governed dosage decisions.
Micro-emulsion collector technology is miniaturizing active agent droplet size to sub-micron scales, enhancing mineral surface coverage efficiency. Copper-molybdenum bulk flotation circuits in Arizona and Utah adopt these systems to reduce collector consumption by half while maintaining recovery rates. The technology is miniaturizing the effective dose-response curve, allowing operators to treat lower-grade feeds without proportional reagent cost escalation.
REACH authorization requirements under ECHA's sunset date protocols are phasing out nonylphenol ethoxylate frothers across European mineral processing imports. Formulators must submit substitution plans for affected chemistries by specified deadlines or lose market access. Collector suppliers with pre-registered alkoxylated alternatives capture displaced volume as Spanish and Portuguese tungsten operations reformulate.
Buyer concentration among top-tier mining houses is consolidating procurement authority into centralized technical committees. Rio Tinto and BHP now specify reagent performance through guaranteed recovery metrics rather than chemical composition, forcing suppliers to assume metallurgical risk. Chile's state-owned Codelco operates the most advanced outcome-based contracting framework, penalizing underperformance through clawback provisions tied to monthly concentrate grades.
Beneficiation Reagents Market Segmentation
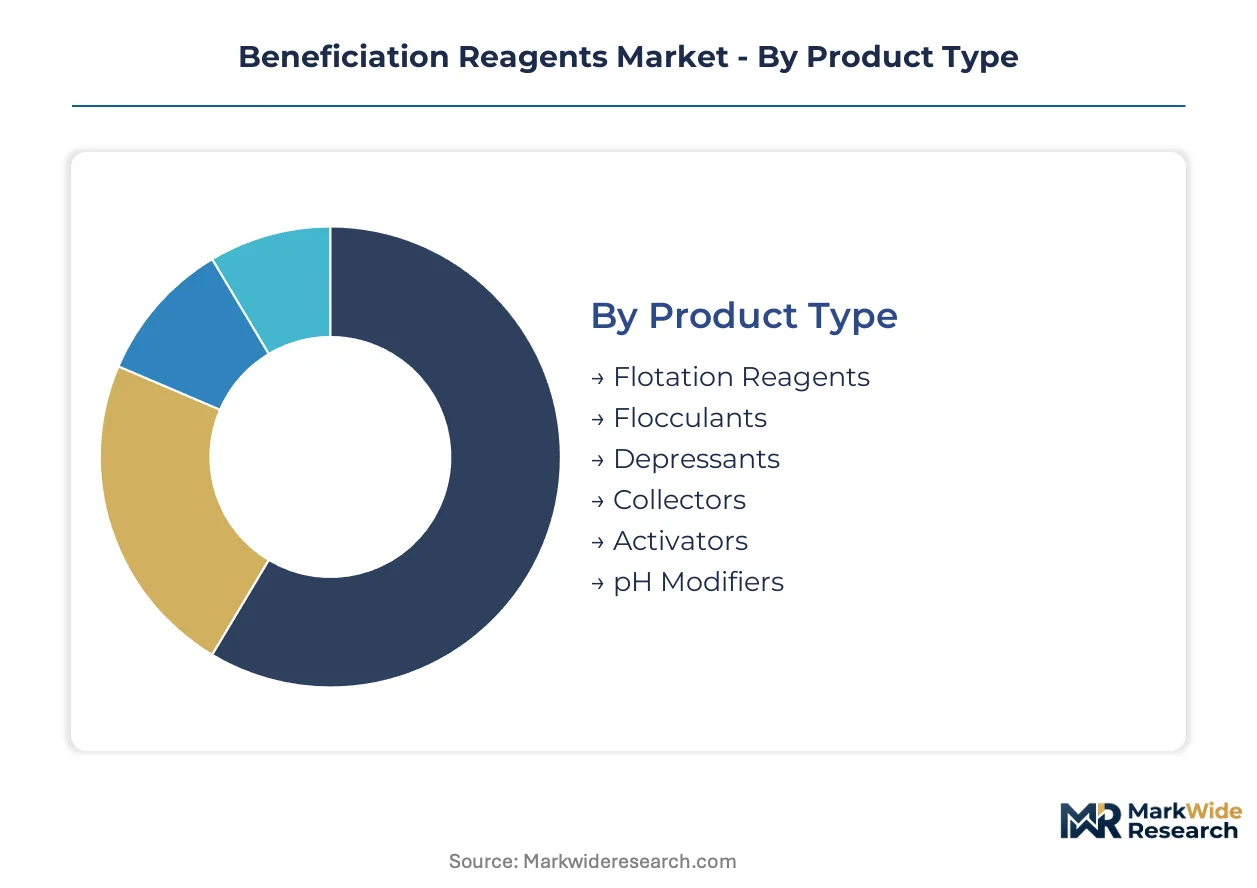
Beneficiation reagents serve distinct operational roles across mineral processing circuits, with product chemistry and physical form determining compatibility with specific ore types and equipment configurations. Segmentation reveals where formulation innovation concentrates versus where commodity supply dominates procurement decisions.
Product Type:
Channel flow splits between direct technical sales for complex flotation chemistries and distributor networks for standardized pH modifiers and basic collectors.
- Flotation Reagents:Surface-active formulations including frothers and collectors that modify mineral hydrophobicity for selective separation. Demand clusters in Chile's Atacama copper corridor where declining head grades force higher reagent intensity per ton milled.
- Flocculants:High-molecular-weight polymers that agglomerate fine particles for solid-liquid separation. Brazil's Minas Gerais iron ore district drives fastest expansion as dry stacking mandates intensify tailings thickening requirements.
- Depressants:Selective mineral surface deactivators preventing unwanted gangue flotation in polymetallic feeds.
- Collectors:Xanthate and dithiophosphate families commanding largest volume share in sulfide ore processing.
- Activators:Copper sulfate and other metal salts enabling flotation of previously unresponsive mineral surfaces.
- pH Modifiers:Lime and sulfuric acid commodities supplied through regional distribution networks with minimal technical service attachment.
Collectors dominate installed base. Flocculants are where expansion concentrates.
Application:
Cost tier separation emerges between high-margin specialty formulations for complex separation challenges and commodity reagents for bulk tonnage operations.
- Ore Concentration:Primary flotation and gravity separation circuits consuming the majority of reagent volumes. Copper-molybdenum bulk operations in Arizona and Utah prioritize micro-emulsion collectors for dose efficiency at lower grades.
- Tailings Treatment:Thickening, filtration, and dry stacking preparation creating captive demand from regulatory closure obligations. Anionic flocculant specifications tighten as water recovery targets escalate.
- Wastewater Treatment:Neutralization and clarification chemistry for process water discharge compliance.
- Mineral Recycling:Secondary material recovery from tailings reprocessing and smelter slag.
- Sludge Conditioning:Dewatering aid applications in metallurgical waste management.
Ore concentration commands volume leadership. Tailings treatment offers the steepest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, with tier-one mining houses centralizing technical specifications versus contractor-driven spot purchasing.
- Mining Contractors:Site operators specifying reagent performance through guaranteed recovery metrics rather than chemical composition, transferring metallurgical risk to suppliers.
- Mineral Processing Plants:Captive facilities with integrated technical teams capable of custom formulation development.
- Metal Refiners:Downstream consumers with limited direct reagent procurement, primarily sourcing conditioned concentrates.
- Chemical Suppliers:Intermediaries distributing commodity pH modifiers and basic flotation aids with minimal value-added services.
Mining contractors dominate procurement authority. Mineral processing plants concentrate formulation customization demand.
Form:
Supply concentration varies by physical state, with liquid emulsions requiring specialized production assets versus powder handling infrastructure.
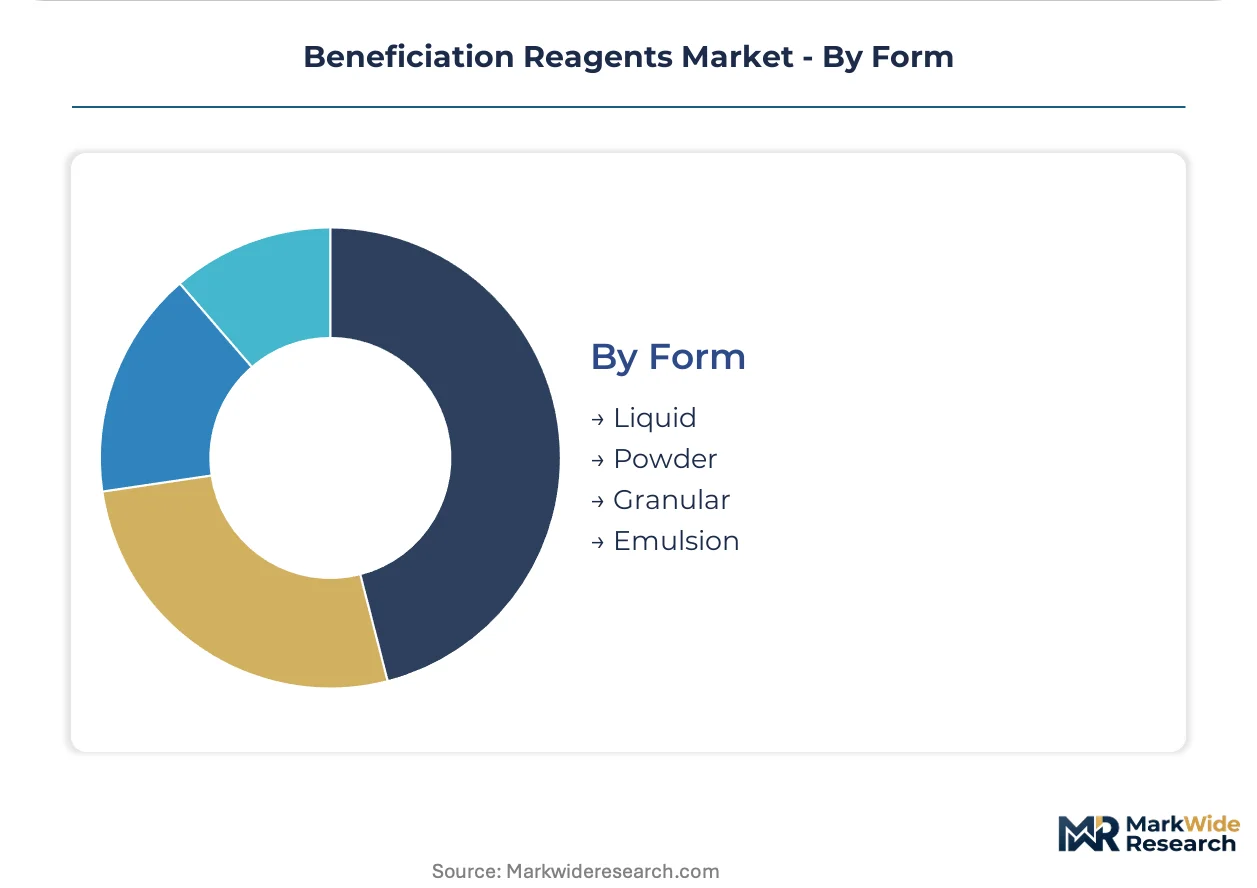
- Liquid:Pump-ready solutions and dispersions preferred for continuous dosing systems and automated process control integration.
- Powder:Dry polymer flocculants requiring on-site dissolution equipment, common in remote operations with limited liquid handling infrastructure.
- Granular:Low-dust pH modifiers and activators with extended shelf stability for bulk storage.
- Emulsion:Micro-emulsion collector technology miniaturizing active agent droplet size to sub-micron scales for enhanced surface coverage efficiency.
Liquid forms dominate continuous process installations. Emulsion technology is gaining share fastest in high-altitude Latin American mines where solvent exposure reduction matters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining contractors in Chile, Australia, and Brazil concentrate procurement authority for beneficiation reagents, with state-owned enterprises in China and Peru adding substantial volume through centralized technical specifications.
Chile
Declining copper head grades in the Atacama mining corridor intensify xanthate collector and polyglycol frother consumption per ton milled. The national mining regulator Sernageomin enforces tailings dam safety protocols that determine reagent qualification timelines for new supplier approvals. Antofagasta and Calama host the densest concentration of flotation circuit operations where Codelco operates outcome-based contracting frameworks.
Australia
Iron ore operations in the Pilbara region drive bulk flocculant demand for dry stack tailings preparation as water recovery mandates tighten. The Department of Industry, Science and Resources coordinates mine closure liability frameworks that create captive demand for tailings treatment chemistry. Perth serves as the regional procurement hub where tier-one mining houses centralize technical committee decisions on reagent performance guarantees.
Brazil
Minas Gerais iron ore districts expand anionic flocculant specifications as dry stacking regulations intensify thickening requirements for water recovery circuits. ANM, the national mining agency, mandates updated tailings management plans that directly influence reagent selection criteria for new processing approvals. Belo Horizonte anchors the southeastern mining corridor where Vale and contractor networks coordinate large-volume collector procurement.
China
MEE wastewater reuse standards mandate closed-circuit reagent recovery systems in new processing plant approvals across Inner Mongolia and Jiangxi rare earth operations. The Ministry of Ecology and Environment enforces dual carbon goals that favor suppliers with integrated closed-loop system capabilities. Bayan Obo hosts underdeveloped bastnäsite separation chemistry where novel collector development creates white space for formulation specialists.
Peru
Polymetallic copper-zinc feeds in the Andean cordillera force higher-selectivity collector formulations as ore complexity increases. OEFA, the environmental enforcement agency, monitors effluent discharge from mineral processing facilities in the Junín and Áncash regions. Cerro de Pasco and La Oroya concentrate polymetallic flotation expertise where declining grades per ton recovered expand reagent intensity requirements.
Beneficiation Reagents Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with polymer synthesis capabilities and specialized mining chemical divisions. Three structural tiers emerge: diversified multinationals controlling raw material quality through captive supply chains, mid-cap specialists anchoring positions through emulsion formulation expertise, and regional distributors handling commodity pH modifiers with minimal technical attachment. Competitive moves concentrate on backward integration into carbon disulfide feedstocks and technology licensing partnerships for micro-emulsion dosing systems.
Within the integrated chemistry tier, BASF leverages its polymer platform to control collector synthesis inputs, while Clariant anchors specialized emulsion capabilities for high-altitude Latin American operations. Solvay occupies a position exemplifying alkali-activated portfolio development for complex sulfide separation challenges. These three represent distinct strategic archetypes: feedstock-integrated manufacturing, application-specific formulation science, and reagent-system integration for polymetallic feeds.
| Leading Market Players |
|---|
| BASF |
| Clariant |
| Solvay |
| Orica |
| Nouryon |
| Ecolab |
| Evonik Industries |
| Chevron Phillips Chemical |
| Kemira |
| Others |
Pricing and Supply Chain Analysis
Carbon disulfide reactor scale economics in China and Germany anchor global xanthate collector production, concentrating supply among three integrated chemical conglomerates whose captive feedstock access sets price floors that regional formulators cannot match without backward integration into raw material synthesis.
Pricing Analysis
Cost-plus contracts with caustic soda and carbon disulfide indexation dominate long-term supply agreements between collectors and Chilean copper contractors. Three-tier pricing structure across ISO 14001-certified premium formulations, standard technical grades, and commodity pH modifiers separates procurement tiers by metallurgical risk transfer and environmental compliance burden. Pricing pressure stems from alkali-activated reagent substitution in complex sulfide circuits as Solvay's proprietary portfolios displace conventional fatty acid collectors. Mining contractors exhibit lowest price sensitivity where outcome-based contracting ties reagent costs to concentrate grade guarantees, while regional distributors of commodity modifiers face highest sensitivity to spot caustic soda movements.
Supply Chain Analysis
Inventory buffers for carbon disulfide extend lead times for xanthate collector orders to 8-12 weeks, forcing Chilean and Peruvian copper operations to maintain 60-day safety stocks of critical flotation chemistries. Manufacturing concentration in China, Germany, and Belgium draws from n-butanol and phosphorus pentasulfide feedstocks where caustic soda price volatility transmits directly to formulation costs. Single-source vulnerability in carbon disulfide reactor capacity creates supply chain risk for sulfide collector availability during feedstock contract renegotiations. Distribution runs through technical sales teams for complex flotation formulations and regional chemical distributors for standardized pH modifiers with minimal service attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers must defend against alkali-activated reagent substitution threatening conventional collector market share in polymetallic separation circuits. The imperative centers on locking in backward integration and certification advantages before formulation chemistry shifts accelerate.
For Market Incumbents: Secure captive carbon disulfide supply through reactor capacity expansion or long-term offtake agreements with Chinese and German feedstock producers. Accelerate ISO 14001 certification pipelines to compress supplier qualification timelines for Codelco and Rio Tinto technical committees. Alkali-activated portfolio substitution from Solvay demands defensive R&D investment in zeta potential modification expertise for complex sulfide feeds. For New Entrants and Emerging Players: Anchor in rare earth element flotation chemistry where bastnäsite and monazite separation remains underdeveloped at Mountain Pass and Bayan Obo operations. White space exists for novel collectors targeting REE-specific surface chemistry with lower environmental burden than conventional fatty acid systems. Go-to-market positioning should emphasize closed-loop reagent recovery system integration to satisfy China MEE wastewater reuse mandates in new processing plant approvals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors emulsion formulation specialists with proven high-altitude Latin American deployment records over commodity pH modifier distributors. Long-term viability hinges on differentiation through metallurgical risk transfer capabilities rather than chemical composition specifications. Acquisition targets should demonstrate machine learning integration with X-ray fluorescence dosing platforms. Signal to watch: Codelco outcome-based contract renewal rates as proxy for supplier switching costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Disulfide | Captive feedstock supply insulates margins from caustic soda volatility in xanthate synthesis. |
| Micro-Emulsion Technology Licensing | Sub-micron droplet collectors reduce dosage intensity for declining copper head grades in Atacama operations. |
| ISO 14001 Certification Acceleration | Compressed qualification timelines unlock tier-one mining house procurement authority before competitors. |
| Closed-Loop Recovery System Partnerships | Integration capabilities satisfy China MEE wastewater mandates in rare earth and copper processing approvals. |
| Digital Dosing Platform Development | Machine learning optimization displaces manual protocols and creates switching costs through operational data capture. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Chilean copper concentrators, procurement leads at Australian iron ore operations, technical R&D directors at integrated chemical suppliers, and distribution channel partners in Brazil's Minas Gerais corridor; and secondary validation through customs and trade data, mining chemical association reports, SEC 10-K filings of diversified chemical conglomerates, and national mining regulator technical bulletins from Sernageomin and ANM. Bottom-up reagent consumption modeling triangulated against top-down market sizing from ore processing capacity and grade decline projections.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type (flotation reagents, flocculants, depressants, collectors, activators, pH modifiers), application segment (ore concentration, tailings treatment, wastewater treatment, mineral recycling), end user category (mining contractors, mineral processing plants, metal refiners, chemical suppliers), and physical form (liquid, powder, granular, emulsion). CAGRs derived from ore grade depletion curves, dry stacking regulatory adoption timelines, and reagent intensity coefficients per ton milled. Industry-specific inputs included copper head grade decline rates in Chile's Atacama corridor and anionic flocculant specification tightening in Brazilian iron ore tailings circuits.
Decision-makers should treat outputs as directional under base assumptions of sustained ore grade depletion, continued REACH and EPA regulatory tightening, and stable carbon disulfide feedstock availability; material deviation in mining investment cycles or substitution technology adoption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Hydrogen Sulphide Market