
 Alkyl Acrylate Market | 2026-2036
Alkyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyl Acrylate Market Outlook
Asian petrochemical producers is expanding alkyl acrylate output to serve regional coatings and adhesive supply chains. BASF SE leverages integrated acrylic acid-ester complexes across Ludwigshafen and Antwerp to sustain margin capture from upstream propylene. Evonik Industries AG specializes in high-purity grades for medical and electronics applications, while Nippon Shokubai Co Ltd anchors Asia-Pacific supply through Osaka-based esterification capacity.
Alkyl acrylates are ester derivatives of acrylic acid produced via acid-catalyzed esterification of acrylate acid with C1-C4 alcohols, yielding monomers with glass transition temperatures between -54°C and +10°C depending on alkyl chain length. These monomers polymerize to form thermoplastic resins with exceptional weatherability, optical clarity, and adhesive tack for protective coatings, pressure-sensitive adhesives, and textile binders. Butyl acrylate dominates volume demand through emulsion polymerization routes serving architectural coatings, while methyl acrylate leads growth in solvent-based adhesives and textile finishing where harder, more rigid polymer films are required. Powder and emulsion forms concentrate margin pools through differentiated dispersion stability and handling properties.
REACH registration requirements in Europe and EPA Toxic Substances Control Act oversight in the United States constrain monomer impurity profiles and emission thresholds during esterification. China's MEE enforces volatile organic compound discharge limits that push manufacturers toward waterborne emulsion technologies over solvent-based systems. Stakeholders must monitor regulatory tightening on residual acrylic acid content and carbon-intensity benchmarks that could reshape feedstock sourcing and process licensing decisions.
Market Dynamics
Waterborne emulsion technologies are displacing solvent-based coating systems across Asia-Pacific manufacturing clusters, compressing demand for high-VOC alkyl acrylate formulations while expanding food-grade and medical-grade purity requirements.
Growth Catalysts
- REACH purity mandates:ECHA tightening on residual acrylic acid content in European coatings imports is pulling high-grade ester capacity upgrades across Ludwigshafen and Antwerp production corridors.
- China's dual carbon goals:MEE enforcement of VOC discharge limits at Shanghai and Ningbo chemical parks is accelerating waterborne architectural coating adoption, expanding butyl acrylate emulsion polymerization demand.
- Pressure-sensitive adhesives:Electronics manufacturing clusters in Vietnam and Indonesia are consuming methyl acrylate for solvent-based adhesive films serving smartphone and wearable assembly lines.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha cracking margins in Northeast Asian refineries transmit cost instability directly to acrylic acid-ester integrated producers.
- Chinese capacity concentration:Zhejiang and Shandong province expansions by state-backed petrochemical groups concentrate global supply risk in a single regulatory jurisdiction.
- Bio-based acrylate substitution:Lignin-derived methacrylate platforms from Finnish and Swedish biotechnology developers threaten emulsion polymerization share in sustainable packaging coatings.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing in Tamil Nadu and Karnataka are creating captive demand for ultra-high-purity methyl acrylate in optical adhesive films.
- EU Green Deal carbon border adjustments:CBAM phase-in on imported chemicals is incentivizing European coatings formulators to source alkyl acrylates from low-carbon intensity esterification assets.
- Medical device convergence:ISO 10993 biocompatibility certification requirements are opening premium pricing tiers for Evonik-style high-purity grades in drug-delivery patch substrates.
Industry Challenges
- Specialized esterification engineering talent:Acid-catalyzed process optimization and reactive distillation design expertise concentrates among retiring cohorts at Ludwigshafen and Osaka technical centers.
- MEE environmental licensing timelines:New capacity approvals in China's Yangtze River Delta now require 18-24 month carbon-intensity benchmarking studies, delaying project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyl Acrylate Market |
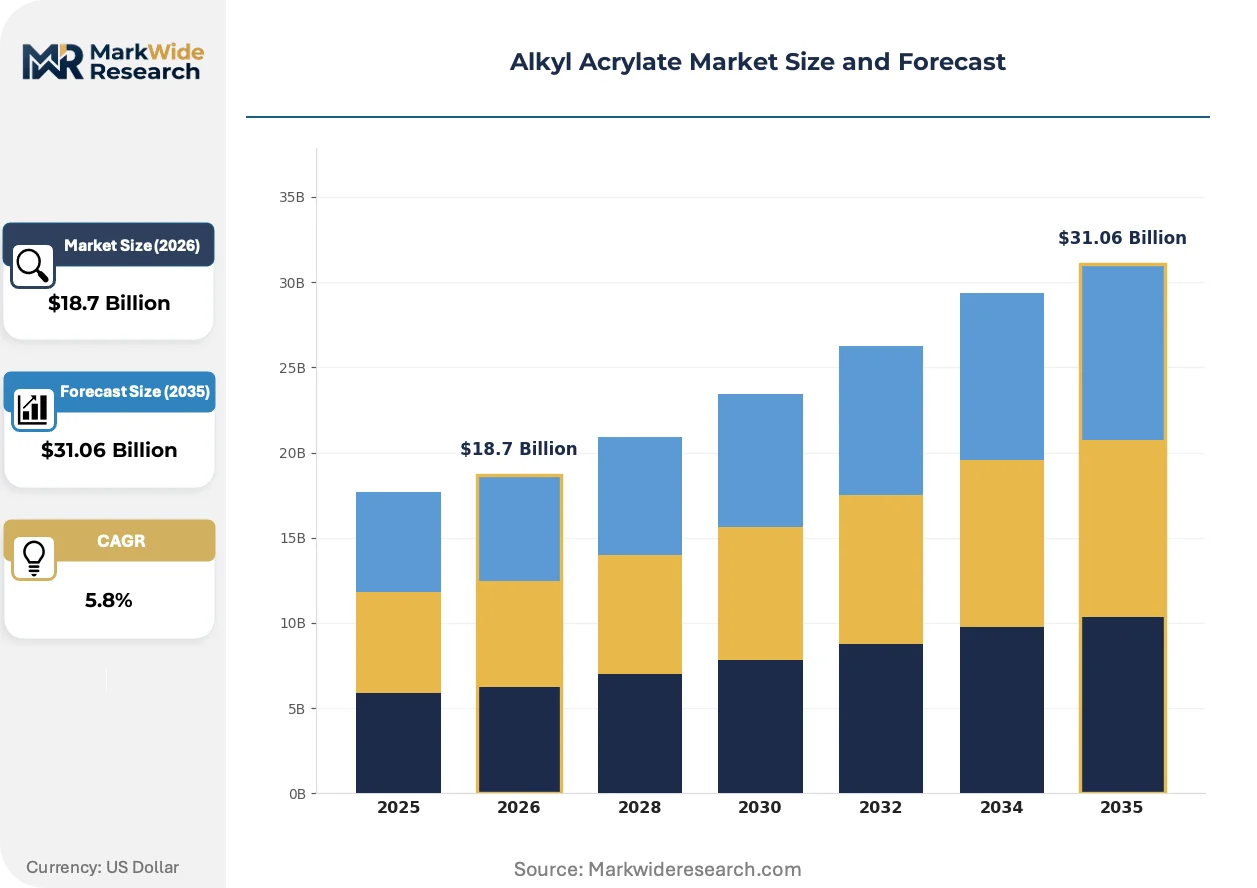
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Acrylate, Ethyl Acrylate, Methyl Acrylate, Propyl Acrylate End Use Industry: Adhesives, Paints, Coatings, Textiles Application: Emulsion Polymerization, Solvent-Based Adhesives, Textile Finishing, Surface Coating Form: Liquid, Powder, Emulsion, Dispersion |
| Companies Covered | Arkema Group, BASF SE, The Dow Chemical Company, Nippon Shokubai Co Ltd, LG Chem Ltd, Evonik Industries AG, Osaka Organic Chemical Industry Ltd, Sumitomo Chemical Co Ltd, San Ester Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyl Acrylate Market Strategic Shifts
Continuous-flow reactor technology is compressing batch cycle times while digital process control systems enable real-time purity monitoring that satisfies tightening pharmaceutical-grade specifications.
Membrane-assisted reactive distillation is integrating water removal directly into esterification loops, eliminating separate dehydration units. Coatings formulators in Germany and the Netherlands are adopting this at pilot scale to reduce energy intensity. The technology is integrating upstream propylene oxide co-product streams into integrated acrylic acid complexes, tightening margin capture for BASF-style operators.
ECHA's 2023 REACH restriction proposal on skin-sensitizing acrylate monomers in consumer adhesives is forcing reformulation toward lower-migration oligomer systems. Industrial tape manufacturers in Northern Italy and Catalonia are accelerating testing of UV-cured acrylate oligomers as drop-in replacements. Medical-grade pressure-sensitive adhesive producers face the steepest compliance timelines, with ANSM France already requiring migration testing documentation for hospital-grade products.
Formulator procurement teams are consolidating supplier bases from spot-market traders toward direct offtake contracts with integrated propylene-acrylic acid-ester producers. Tier-one coatings manufacturers in the US Midwest and Benelux are locking in five-year supply agreements with volume commitments exceeding ten thousand metric tons annually. This consolidation is most visible in automotive refinish coatings, where PPG and Axalta-style formulators demand lot-traceable purity certificates for every drum delivered to assembly plant paint shops.
Alkyl Acrylate Market Segmentation
Alkyl acrylate purchasing decisions pivot on polymerization compatibility, VOC emission profiles, and end-use purity requirements. Formulators select monomers based on glass transition temperature targets and regulatory constraints in destination markets.
Product Type:
Buyers prioritize monomer selection around polymer hardness requirements and weatherability specifications in target applications.
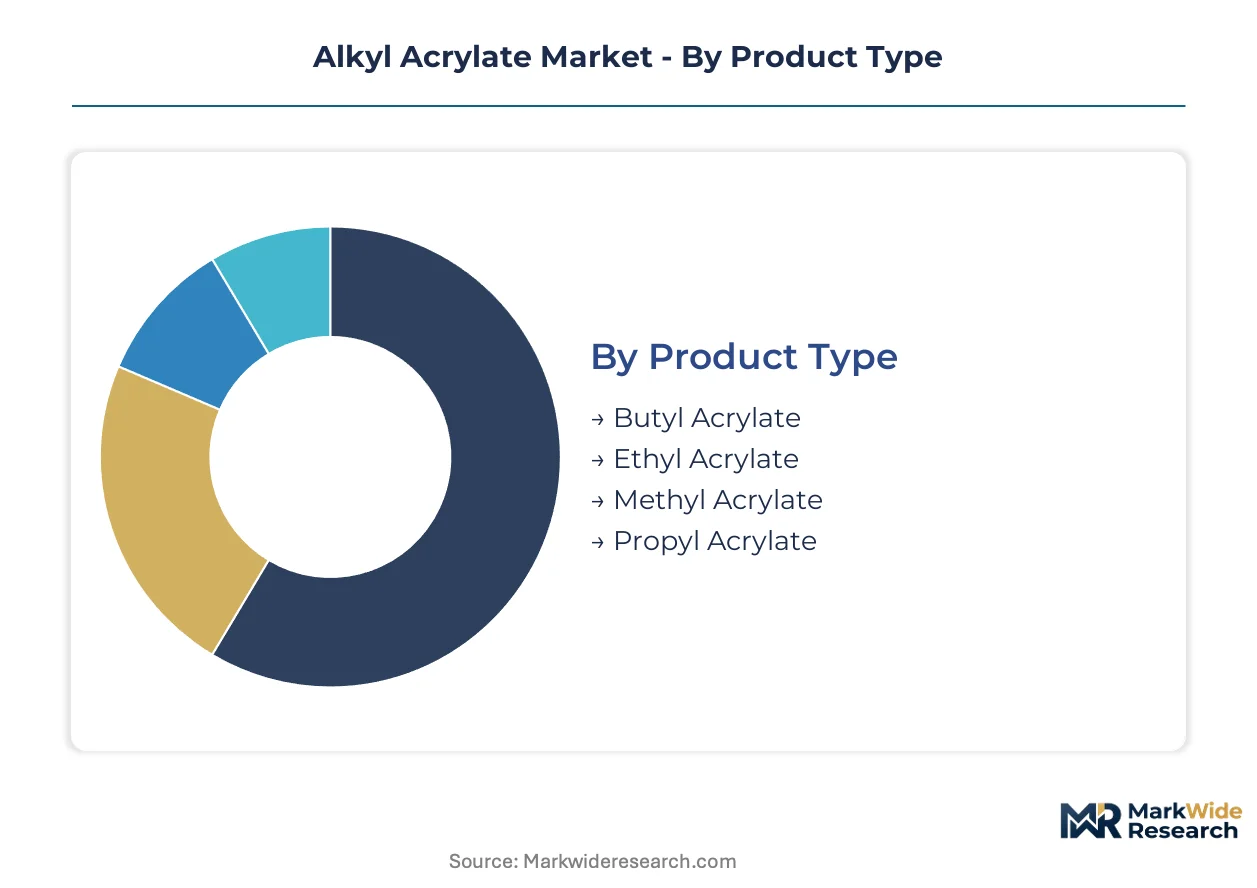
- Butyl Acrylate:C4 ester delivering glass transition temperatures near -54°C enables soft, flexible films. Waterborne architectural coatings in Shanghai and Ningbo manufacturing clusters absorb volume as MEE VOC discharge limits tighten.
- Methyl Acrylate:Shortest alkyl chain yields hardest polymer films with Tg near +10°C. Solvent-based adhesive manufacturers in Vietnam and Indonesia electronics clusters specify this grade for smartphone assembly tape.
- Ethyl Acrylate:Intermediate Tg characteristics suit pressure-sensitive adhesive intermediates requiring balanced tack and cohesion.
- Propyl Acrylate:Niche specialty monomer serving high-performance coating segments demanding specific rheological properties.
Butyl acrylate leads on scale; methyl acrylate leads on momentum.
End Use Industry:
Application-specific purity certifications and formulation compatibility drive procurement patterns across consuming sectors.
- Adhesives:Pressure-sensitive and structural bonding applications. Electronics manufacturing in Tamil Nadu and Karnataka under India's PLI scheme is pulling ultra-high-purity methyl acrylate for optical films.
- Paints:Architectural and industrial coating systems. REACH residual acrylic acid mandates in Germany and Benelux are forcing grade upgrades.
- Coatings:Protective and automotive refinish layers. Lot-traceable purity certificates now required by PPG-style formulators for assembly plant deliveries.
- Textiles:Binder applications for fabric finishing and nonwoven reinforcement. Harder polymer films from methyl acrylate dominate this segment.
Coatings command the largest volume position; adhesives are expanding most quickly.
Application:
Polymerization route selection determines monomer purity requirements and emission control investments.
- Emulsion Polymerization:Waterborne process dominating architectural coatings. China's dual carbon goals and MEE enforcement are accelerating butyl acrylate uptake in Shanghai chemical parks.
- Solvent-Based Adhesives:Solution polymerization for electronics and industrial tapes. ANSM France migration testing requirements are complicating hospital-grade product qualification.
- Textile Finishing:Fabric binder and sizing applications. Methyl acrylate's rigid film characteristics align with technical textile specifications.
- Surface Coating:Direct application systems including automotive refinish and protective industrial layers.
Emulsion polymerization leads on scale; solvent-based adhesives gain share fastest.
Form:
Handling logistics and dispersion stability requirements shape form selection for downstream integration.
- Liquid:Bulk monomer delivery for integrated polymerization operations. BASF Ludwigshafen and Antwerp complexes optimize around liquid feedstock economics.
- Emulsion:Pre-dispersed systems reducing formulator processing steps. Waterborne coating manufacturers in Germany and the Netherlands are adopting membrane-assisted reactive distillation feeds.
- Powder:Solid form for specialized adhesive and coating applications requiring extended shelf stability.
- Dispersion:Stabilized particle systems for direct incorporation into coating formulations.
Liquid form leads on scale; emulsion form shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting alkyl acrylate capacity toward jurisdictions with streamlined environmental licensing and lower carbon-intensity compliance costs, while established production corridors absorb margin pressure from tightening purity mandates.
China
Waterborne architectural coatings in Shanghai and Ningbo chemical parks absorb butyl acrylate volumes as MEE VOC discharge limits tighten. The country's dual carbon goals enforce carbon-intensity benchmarking studies extending 18-24 months for new capacity approvals. Zhejiang and Shandong province expansions by state-backed petrochemical groups concentrate supply risk in this single regulatory jurisdiction.
Germany
REACH residual acrylic acid mandates pull high-grade ester capacity upgrades across Ludwigshafen and Antwerp production corridors. ECHA's 2023 restriction proposal on skin-sensitizing acrylate monomers forces reformulation toward lower-migration oligomer systems. The Ludwigshafen technical center anchors specialized esterification engineering expertise for acid-catalyzed process optimization.
United States
Automotive refinish coatings in the US Midwest demand lot-traceable purity certificates for every drum delivered to assembly plant paint shops. EPA Toxic Substances Control Act oversight constrains monomer impurity profiles and emission thresholds during esterification. Tier-one coatings manufacturers are locking in five-year supply agreements with volume commitments exceeding ten thousand metric tons annually.
India
Electronics manufacturing clusters in Tamil Nadu and Karnataka under the PLI scheme create captive demand for ultra-high-purity methyl acrylate in optical adhesive films. BIS standards and CDSCO oversight shape medical-grade pressure-sensitive adhesive qualification requirements. The country's national pharmaceutical regulator is tightening migration testing documentation for hospital-grade products.
Vietnam
Smartphone and wearable assembly lines in northern manufacturing zones consume methyl acrylate for solvent-based adhesive films. The country's environmental ministry enforces volatile organic compound discharge limits that push manufacturers toward waterborne emulsion technologies. Electronics manufacturing investments from regional supply chain relocations expand derivative consumption in Bac Ninh and Hai Phong industrial parks.
Alkyl Acrylate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty-grade and bio-based adjacent spaces. The market structure consolidates around integrated propylene-acrylic acid-ester complexes and regional esterification specialists. Three archetypes dominate: petrochemical conglomerates with backward integration into propylene feedstocks, precision chemical specialists targeting pharmaceutical and electronics purity tiers, and regional Asian producers scaling emulsion-grade output for domestic coatings demand. Capacity expansion and direct offtake contracting constitute the dominant competitive moves, with formulators abandoning spot-market traders for volume-committed supply relationships.
Among European-headquartered chemical conglomerates, BASF SE and Evonik Industries AG exemplify divergent strategic positioning within the alkyl acrylate value chain. BASF SE represents the integrated petrochemical archetype with acrylic acid-ester complexes sustaining margin capture from upstream propylene, while Evonik Industries AG occupies the high-purity specialty tier serving medical and electronics applications. Nippon Shokubai Co Ltd anchors Asia-Pacific supply through Osaka-based esterification capacity, representing the regional production-scale archetype concentrated in East Asian manufacturing clusters.
| Leading Market Players |
|---|
| Arkema Group |
| BASF SE |
| The Dow Chemical Company |
| Nippon Shokubai Co Ltd |
| LG Chem Ltd |
| Evonik Industries AG |
| Osaka Organic Chemical Industry Ltd |
| Sumitomo Chemical Co Ltd |
| San Ester Corp |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between pharmaceutical-tier and industrial-grade alkyl acrylates manifests in both contract pricing spreads and supplier qualification timelines, with REACH-registered producers commanding premium positions while commodity esterification assets compete on volume scale and carbon-intensity benchmarks.
Pricing Analysis
Distributor margins compress as formulators migrate toward direct offtake contracts with integrated propylene-acrylic acid-ester producers. Contract-based long-term offtake dominates, with price differentiation resting on ISO 10993 biocompatibility certification and lot-traceable purity documentation. Cost compression in standard-grade butyl acrylate intensifies because Chinese state-backed petrochemical groups expand Zhejiang and Shandong capacity. Architectural coatings manufacturers in Germany and the Netherlands exhibit highest price sensitivity; medical-device adhesive producers show least sensitivity due to regulatory switching costs.
Supply Chain Analysis
ISO 10993 and REACH registration requirements gate supplier access to pharmaceutical and electronics tiers, elongating qualification cycles. Supply concentrates in China, Germany, and Japan, with propylene feedstock, acrylic acid, and C1-C4 alcohols anchoring raw material dependencies. Single-source vulnerability runs through Northeast Asian naphtha cracking corridors where crude-linked margins transmit volatility. Distribution runs through integrated petrochemical complexes and regional esterification specialists serving direct formulator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkyl acrylate demand compounds steadily as waterborne architectural coatings displace solvent systems across Asia-Pacific manufacturing clusters, with regulatory tightening on VOC emissions and residual monomer content reinforcing structural volume growth.
For Market Incumbents: Hedge propylene feedstock exposure through backward integration into acrylic acid production or long-term naphtha supply agreements with Northeast Asian refiners. BASF-style integrated complexes in Ludwigshafen and Antwerp sustain margin capture advantages that pure-play esterification assets cannot replicate. Invest in membrane-assisted reactive distillation to reduce energy intensity and satisfy EU Green Deal carbon border adjustment thresholds. For New Entrants and Emerging Players: Specialty distributors serving medical-device and electronics manufacturers represent the most accessible channel entry point. White-space opportunity concentrates in ultra-high-purity methyl acrylate for India's PLI-funded electronics clusters in Tamil Nadu and Karnataka, plus bio-based acrylate adjacent platforms for sustainable packaging coatings. Pursue toll-manufacturing arrangements with established esterification assets to bypass 18-24 month MEE licensing timelines in China. For Investors and Strategic Acquirers: Consolidation pressure builds where carbon-intensity benchmarking and REACH purity mandates strand sub-scale commodity producers. Long-term viability favors integrated propylene-acrylic acid-ester complexes with captive pharmaceutical-grade certification capabilities. Watch for MEE enforcement intensity in Shanghai and Ningbo chemical parks as inflection indicator for Chinese capacity rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captures margin pools from propylene through esterification for Ludwigshafen-style producers. |
| Long-term Supply Agreement | Locks volume commitments from PPG-style automotive refinish formulators seeking lot-traceable purity. |
| Green Manufacturing Transition | Membrane-assisted reactive distillation reduces energy intensity for EU Green Deal CBAM compliance. |
| Capacity Expansion | Zhejiang and Shandong province additions concentrate global supply risk in single regulatory jurisdiction. |
| Joint Venture | Partnerships with Indian electronics manufacturers under PLI scheme secure captive methyl acrylate demand. |
Study Parameters
Multiple input streams — plant manager interviews at Ludwigshafen and Osaka technical centers, procurement lead discussions at coatings OEMs, and distributor channel partner assessments — were reconciled against customs trade data, Cefic industry reports, and SEC 10-K filings from integrated petrochemical conglomerates. Primary fieldwork with technical R&D directors and downstream adhesive formulators informed grade-tier segmentation, while bottom-up capacity build-ups and top-down demand elasticity models were cross-validated.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning grade tier (pharmaceutical versus industrial), end-use industry (coatings, adhesives, textiles), packaging format (liquid, emulsion, powder), and regional production hub. CAGRs were derived from elasticity-adjusted demand curves and capacity commissioning timelines, incorporating propylene feedstock cost trajectories and MEE environmental licensing velocity as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude-linked naphtha cracking margins, REACH regulatory tightening timelines, and bio-based acrylate substitution rates in sustainable packaging segments. A model refresh is warranted upon material change in MEE carbon-intensity benchmarking enforcement or ECHA restriction proposal implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Lime Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Hydrogenated Bisphenol a Market