
 Dipotassium Guanylate Market | 2026-2036
Dipotassium Guanylate Market Size, Share, and Industry Trends Forecast 2026-2036
Dipotassium Guanylate Market Outlook
The EU Green Deal's Farm to Fork strategy is broadening demand for clean-label flavor enhancers across European food manufacturing. Ajinomoto Co., Inc. leverages its integrated fermentation technology to sustain cost leadership in nucleotide production. Angel Yeast Co., Ltd. anchors its position through captive yeast-fermentation supply chains in China. Fufeng Group competes on manufacturing scale across multiple amino acid and nucleotide product lines.
Dipotassium guanylate functions as a disodium guanylate analog, a potassium salt of guanylic acid produced via microbial fermentation of carbohydrates, primarily serving as an umami-intensifying flavor enhancer in processed foods and savory formulations. The food additive segment dominates volume consumption due to entrenched use in soups, sauces, and snack seasonings, while the dietary supplements end-use channel represents the fastest-expanding margin pool as sports-nutrition brands incorporate nucleotides into recovery formulations. Powder form leads industrial procurement for blending flexibility, though granules gain traction in automated manufacturing environments for reduced dusting and improved flow characteristics.
EFSA purity specifications and China's SAMR food additive registration requirements shape product standards and market access protocols for cross-border nucleotide trade. The FDA's GRAS self-affirmation pathway and FSSAI's additive approval framework in India create divergent compliance burdens that fragment go-to-market strategies. Stakeholders must monitor evolving regulatory convergence between EU REACH-aligned chemical safety assessments and emerging GB standard revisions in China to anticipate reformulation requirements and qualification timelines.
Market Dynamics
Fermentation capacity clustering in China's Shandong province concentrates nucleotide supply chains, while EFSA's tightening purity specifications and China's SAMR registration protocols force simultaneous compliance investments across export-oriented producers.
Growth Catalysts
- Clean-label reformulation mandates:The EU Green Deal's Farm to Fork strategy compels food manufacturers to replace artificial flavor systems with fermentation-derived alternatives in savory applications.
- Sports-nutrition nucleotide incorporation:Recovery formulation brands are integrating potassium-salt nucleotides into post-workout products for electrolyte-functional umami delivery.
- Yeast-fermentation yield improvements:Strain optimization and carbohydrate feedstock processing advances are compressing unit economics for microbial guanylate production.
Market Restraints
- Input carbohydrate volatility:Molasses and starch feedstock price swings directly compress fermentation margin structures for nucleotide producers.
- Single-province supply concentration:Shandong's dominance in yeast-fermentation infrastructure creates geographic risk exposure for downstream formulators.
- Disodium guanylate substitution pressure:Lower-cost sodium-salt alternatives retain entrenched positions in cost-sensitive seasoning applications.
Strategic Opportunities
- India FSSAI additive approval pathway:Formal clearance for nucleotide flavor enhancers would unlock formulation access to subcontinent processed-food manufacturing.
- Granule format automation compatibility:Automated seasoning lines favor dust-reduced granule flow characteristics over conventional powder handling.
- Dietary supplement channel expansion:Nucleotide positioning for immune and recovery benefits is penetrating sports-nutrition and clinical nutrition segments.
Industry Challenges
- Fermentation specialist talent scarcity:Industrial microbiology and downstream purification expertise shortages constrain capacity expansion timelines.
- Dual-registration compliance burden:Simultaneous EFSA REACH-aligned assessments and China GB standard revisions fragment qualification resources.
- Legacy powder handling infrastructure:Existing seasoning plant equipment requires retrofit investment to accommodate granule format specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dipotassium Guanylate Market |
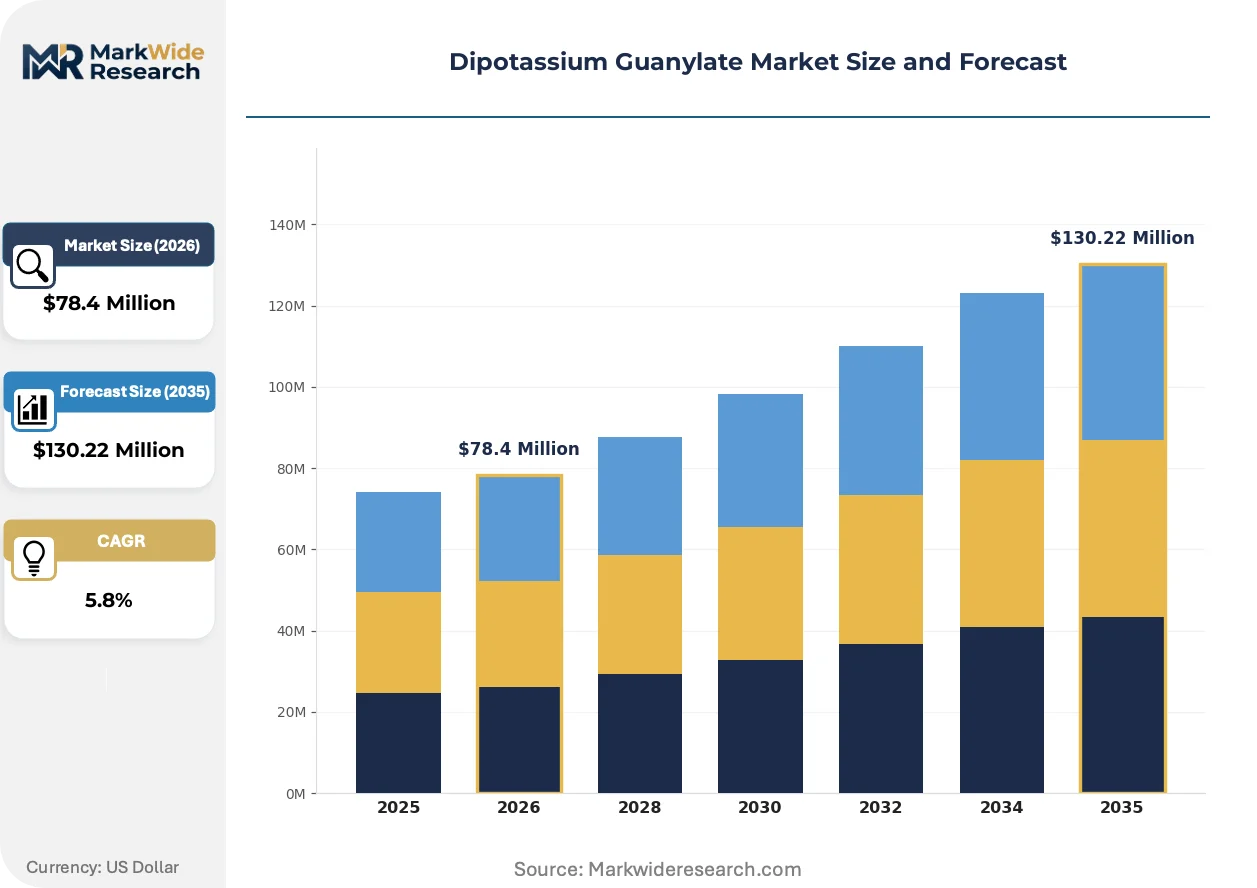
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $130.22 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Pharmaceuticals, Nutraceuticals, Cosmetics End Use: Food & Beverage, Personal Care, Dietary Supplements, Animal Feed Form: Powder, Granules, Liquid, Tablets Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Ajinomoto Co., Inc., Angel Yeast Co., Ltd., Fufeng Group, Meihua Holdings Group, Vedan International Holdings Ltd., DSM-Firmenich, Kerry Group, Tate & Lyle PLC, CJ CheilJedang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dipotassium Guanylate Market Strategic Shifts
Fermentation-derived ingredient authenticity is displacing synthetic chemical positioning across European and North American savory formulation procurement. Three interconnected developments are compressing traditional supply relationships.
Continuous fermentation monitoring via inline spectroscopy is rewriting process control economics for nucleotide manufacturers. Mid-cap producers are adopting these systems to reduce batch-to-batch variation and accelerate release timelines. The technology is compressing quality assurance labor intensity while enabling real-time carbohydrate feedstock adjustment.
EFSA's 2023-2024 food additive re-evaluation protocols are forcing nucleotide suppliers to generate extended toxicity datasets beyond historical submission requirements. European savory seasoning manufacturers face reformulation holds pending positive opinions. The regulatory friction is diverting R&D investment toward documentation rather than product innovation.
Direct-procurement relationships between nucleotide producers and multinational seasoning houses are displacing traditional distributor intermediaries. Large food manufacturers are consolidating supplier panels to capture volume pricing and secure fermentation capacity allocation. This consolidation pattern is most visible in European soup and sauce manufacturing, where three buyers now represent a majority of contract nucleotide offtake.
Dipotassium Guanylate Market Segmentation
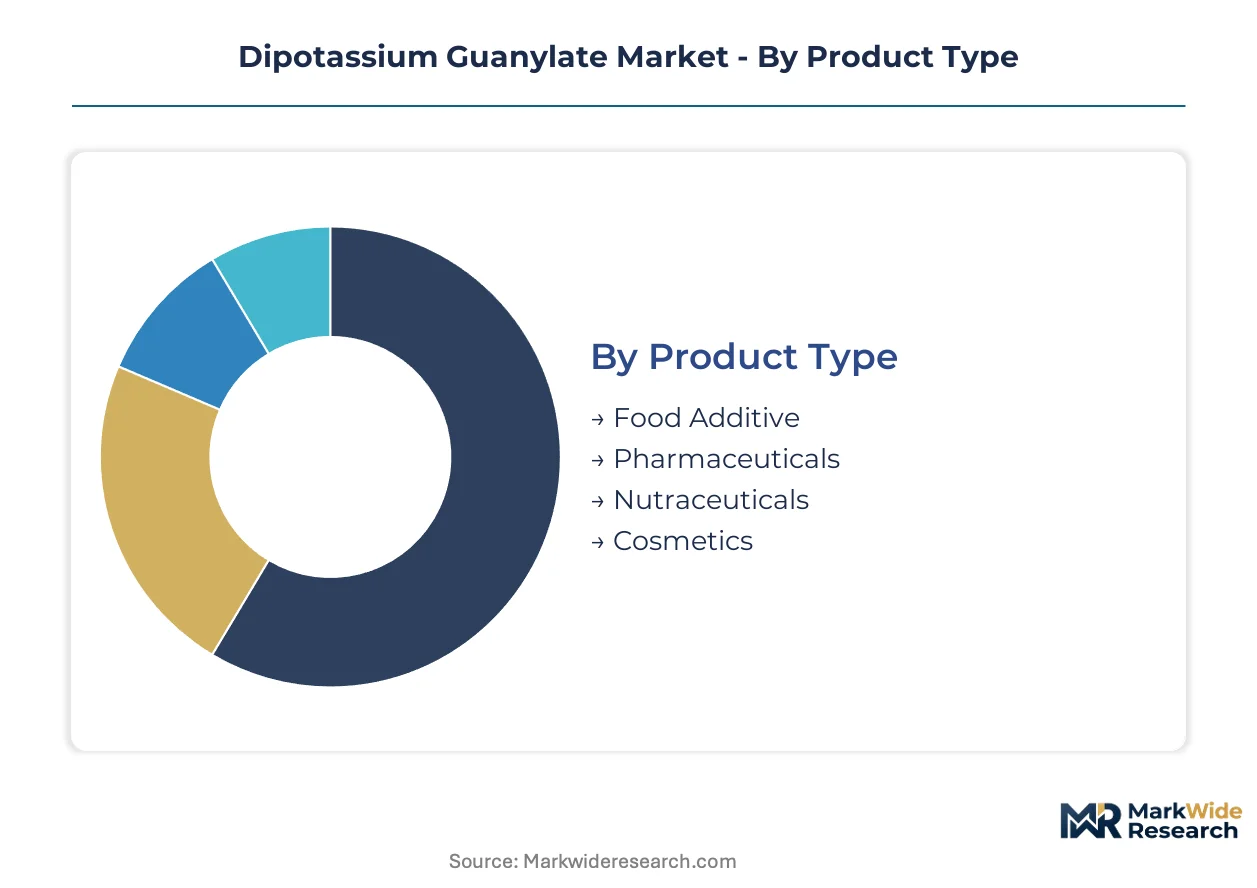
Dipotassium guanylate procurement patterns diverge sharply across application contexts, with fermentation-derived purity requirements and formulation compatibility driving segment-specific supplier selection. Manufacturers optimize channel strategies and physical formats based on end-use regulatory thresholds and handling infrastructure.
Product Type:
Yeast-fermentation capacity in Shandong province concentrates supply for high-purity grades, while downstream formulators source lower-specification variants from distributed chemical processors.
- Food Additive:The potassium salt of guanylic acid serves as an umami-intensifying flavor enhancer in processed savory formulations. Demand concentrates in China's seasoning manufacturing clusters, where EFSA purity specifications and SAMR registration requirements enforce dual-compliance sourcing.
- Pharmaceuticals:USP-grade material meets injectable and oral dosage purity thresholds for nucleotide-based therapeutic applications. European compounding pharmacies and clinical nutrition formulators in Germany and Switzerland drive specification premiums for endotoxin-controlled batches.
- Nutraceuticals:Sports-recovery brands incorporate potassium-salt nucleotides for electrolyte-functional positioning.
- Cosmetics:Skin-conditioning applications in Korean and Japanese personal care formulations utilize lower-concentration nucleotide complexes.
Today's leader: Food Additive. Tomorrow's challenger: Pharmaceuticals.
End Use:
Cost-tier differentiation separates commodity seasoning applications from premium clinical and sports-nutrition positioning, with price multiples expanding across the value chain.
- Food & Beverage:Soups, sauces, and snack seasonings represent entrenched volume consumption for fermentation-derived flavor enhancement. Automated manufacturing lines in European soup manufacturing favor granule formats for dust-reduced handling.
- Dietary Supplements:Post-workout recovery formulations and immune-support positioning drive nucleotide incorporation. Sports-nutrition brands in North America and Western Europe represent the steepest expansion trajectory for potassium-salt variants.
- Personal Care:Cosmetic nucleotide applications remain niche, concentrated in East Asian skin-care innovation pipelines.
- Animal Feed:Palatability enhancement for aquaculture and pet food applications utilizes lower-purity fermentation byproducts.
Volume dominance: Food & Beverage. Margin expansion: Dietary Supplements.
Form:
Customer-type preferences segment procurement between legacy powder-handling infrastructure and automation-compatible granule investments.
- Powder:Standard crystalline form dominates industrial procurement for blending flexibility in seasoning compounding. Existing plant infrastructure across mid-scale sauce manufacturers in Italy and Spain retains powder-based workflows.
- Granules:Agglomerated particles reduce dusting and improve flow characteristics for automated dispensing systems. New seasoning line installations in Northern European manufacturing favor this format for occupational safety compliance.
- Liquid:Aqueous solutions serve ready-to-use sauce and broth applications.
- Tablets:Compressed forms target direct-consumer supplement positioning.
Installed base: Powder. Greenfield preference: Granules.
Distribution Channel:
Geographic reach constraints and order-scale economics determine channel selection, with multinational seasoning houses consolidating toward direct-procurement relationships.
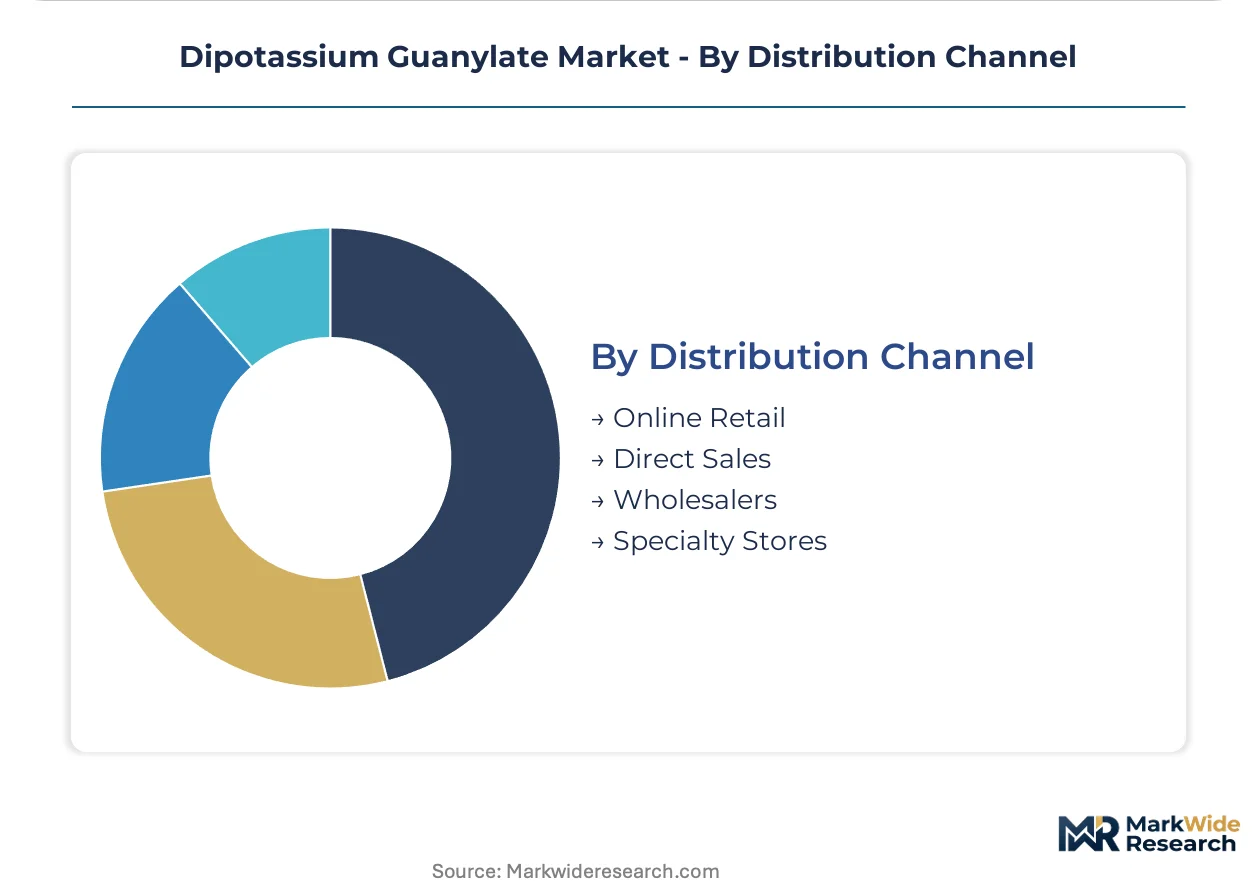
- Direct Sales:Contract nucleotide offtake between Shandong fermentation producers and European soup manufacturers eliminates distributor margins. Three buyers now represent majority contract volume in this channel.
- Wholesalers:Regional chemical distributors serve mid-scale seasoning compounders and smaller nutraceutical formulators across fragmented European markets.
- Online Retail:E-commerce platforms target small-batch dietary supplement manufacturers and research procurement.
- Specialty Stores:Niche channels serve cosmetic and pharmaceutical compounding segments.
Consolidation direction: Direct Sales. Coverage gap filler: Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based nucleotide production originated in post-war Japan before scaling through Chinese microbial engineering. Shandong province now anchors global capacity, while European regulatory tightening and North American sports-nutrition formulation drive demand diversification across three continents.
China
Shandong province concentrates yeast-fermentation infrastructure for nucleotide manufacturing, serving both domestic seasoning compounders and export markets. SAMR's GB standard revisions for food additive purity are forcing simultaneous compliance investments across fermentation facilities. Weifang and Yantai host captive supply chains linking Angel Yeast to downstream nucleotide processors.
Japan
Ajinomoto pioneered industrial nucleotide fermentation, maintaining integrated production for umami-enhancer supply to domestic and Southeast Asian food manufacturers. METI's chemical substance management frameworks align with evolving international purity standards. The Kansai region retains specialized fermentation expertise for high-specification nucleotide grades.
Germany
European soup and sauce manufacturers source fermentation-derived flavor enhancers under EFSA's tightened food additive re-evaluation protocols. REACH-aligned chemical safety assessments create documentation burdens for nucleotide importers. Bavarian seasoning compounders favor granule formats for automated manufacturing lines.
United States
Sports-nutrition brands in North America incorporate potassium-salt nucleotides into post-workout recovery formulations for electrolyte-functional positioning. FDA's GRAS self-affirmation pathway permits faster market entry compared to European registration requirements. California and New Jersey host formulation R&D for nucleotide-based dietary supplements.
India
Processed food manufacturers await FSSAI formal clearance for nucleotide flavor enhancers to unlock domestic formulation access. Current additive approval frameworks restrict penetration into the subcontinent's savory seasoning sector. Maharashtra and Gujarat seasoning clusters represent latent demand pending regulatory resolution.
Dipotassium Guanylate Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity-grade and application-certification dimensions. The vendor base organizes into three tiers: integrated fermentation specialists with captive yeast supply, diversified amino acid producers leveraging shared carbohydrate feedstock infrastructure, and regional chemical processors serving lower-specification industrial applications. Dominant competitive moves include backward integration into yeast-strain development and direct-procurement contracting with multinational seasoning houses.
Within the integrated fermentation tier, Ajinomoto Co., Inc. and Angel Yeast Co., Ltd. exemplify archetypes of microbial engineering depth and captive supply chain control respectively. Fufeng Group occupies a position among diversified biochemical producers spanning multiple nucleotide and amino acid product lines. These three entities represent contrasting scale-versus-specialization positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Angel Yeast Co., Ltd. |
| Fufeng Group |
| Meihua Holdings Group |
| Vedan International Holdings Ltd. |
| DSM-Firmenich |
| Kerry Group |
| Tate & Lyle PLC |
| CJ CheilJedang |
| Others |
Value Chain & Pricing Dynamics
Industrial microbiology talent clustering in Shandong province compresses fermentation labor costs, widening the spread between USP-grade pharmaceutical pricing and commodity food-additive tiers across global nucleotide markets.
Pricing Analysis
Contract-based long-term offtake agreements dominate nucleotide procurement, with pricing stratifying across pharmaceutical-grade, food-additive, and feed-grade certification levels. Price differentiation hinges on endotoxin-controlled batch documentation and dual-registration compliance investment. Cost compression in standard-grade material is intensifying because of molasses feedstock volatility and Shandong capacity expansion. Mid-scale seasoning compounders in Southern Europe exhibit the highest price sensitivity, while German clinical nutrition formulators absorb specification premiums.
Supply Chain Analysis
Reverse-logistics flows for fermentation equipment refurbishment and strain-bank maintenance create secondary service revenue streams for Shandong-based producers. Supply concentrates in China, Japan, and South Korea for high-purity nucleotide manufacturing. Raw material dependencies draw from molasses, corn starch, and specialized yeast strains. Single-province concentration in Shandong creates geographic risk exposure for downstream formulators. Distribution runs through direct-procurement contracts between fermentation specialists and multinational seasoning houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in dipotassium guanylate rests on yeast-fermentation yield improvements compressing unit economics, while sports-nutrition positioning commands triple-digit price multiples over commodity seasoning grades.
For Market Incumbents: Anticipate EFSA re-evaluation documentation burdens diverting R&D resources from strain optimization. Prioritize backward integration into captive yeast-strain development to defend against Angel Yeast's supply chain control. Accelerate granule-format capacity to capture automated manufacturing line retrofits in Northern Europe. For New Entrants and Emerging Players: Capture India FSSAI approval pathway whitespace before formal nucleotide clearance unlocks subcontinent formulation access. Target dietary supplement channel expansion in North American sports-nutrition as the most penetrable margin pool. Lead with electrolyte-functional positioning for post-workout recovery formulations. For Investors and Strategic Acquirers: Food ingredient multinationals are the most active acquirer in this space, consolidating fermentation capacity to secure nucleotide supply allocation. Five-to-ten year viability favors integrated producers with SAMR-EFSA dual-registration capabilities. Monitor FSSAI additive approval timeline as the critical inflection signal for India market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Yeast Strain Optimization | Carbohydrate-to-nucleotide yield improvements compress unit economics for Shandong producers. |
| Dual-Registration Investment | Simultaneous EFSA REACH alignment and SAMR GB compliance unlocks European and Chinese market access. |
| Granule Format Capacity Addition | Dust-reduced flow characteristics align with automated seasoning line installations in Bavaria. |
| Direct-Procurement Contracting | Volume pricing capture with multinational soup manufacturers displaces distributor intermediaries. |
| Sports-Nutrition Channel Expansion | Potassium-salt electrolyte positioning penetrates North American post-workout recovery formulations. |
Study Parameters
Bottom-up dietary supplement modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Shandong nucleotide facilities, procurement leads at European seasoning compounders, regulatory affairs specialists navigating SAMR registration, and sports-nutrition formulators in North America combined with secondary validation from customs trade data, GB standard revision notices, EFSA food additive opinions, and SEC filings from listed fermentation specialists. Triangulation between end-use demand signals and supply-side infrastructure investments ensures cross-verification.
Historical trendline analysis of nucleotide pricing spreads and fermentation yield trajectories informed projection modeling across the analysis window. Segmentation dimensions include product grade tier, end-use industry, physical form, and regional regulatory cluster. CAGRs derived from volume-price elasticity modeling incorporate yeast-fermentation capacity utilization rates and clean-label reformulation adoption curves in European savory manufacturing.
Molasses price volatility, EFSA re-evaluation timeline extensions, and India FSSAI approval delays are the dominant revision risks to forecast assumptions. Practitioners should monitor carbohydrate feedstock futures, regulatory opinion publication schedules, and subcontinent additive clearance announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Feed Additive Nosiheptide Premix Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Paint Additives Market
Additives
Indonesia Feed Additives Market
Additives
Nucleotide Premix Market
Additives
Organic Dispersants Market
Additives
Liquid Silage Additive Market
Additives
Crystal Growth Modifier Market
Additives
Ethoxyquin Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Global Cement Additives Market
Additives
Shortstop Inhibitor Market
Additives
Anti-Creasing Agent Market
Additives
Nucleating and Clarifying Agents Market
Additives
LAMEA Driveline Additives Market
Additives
Global Acidulants Market