
 Global Coalescing Agent Market | 2026-2036
Global Coalescing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coalescing Agent Market Foresight
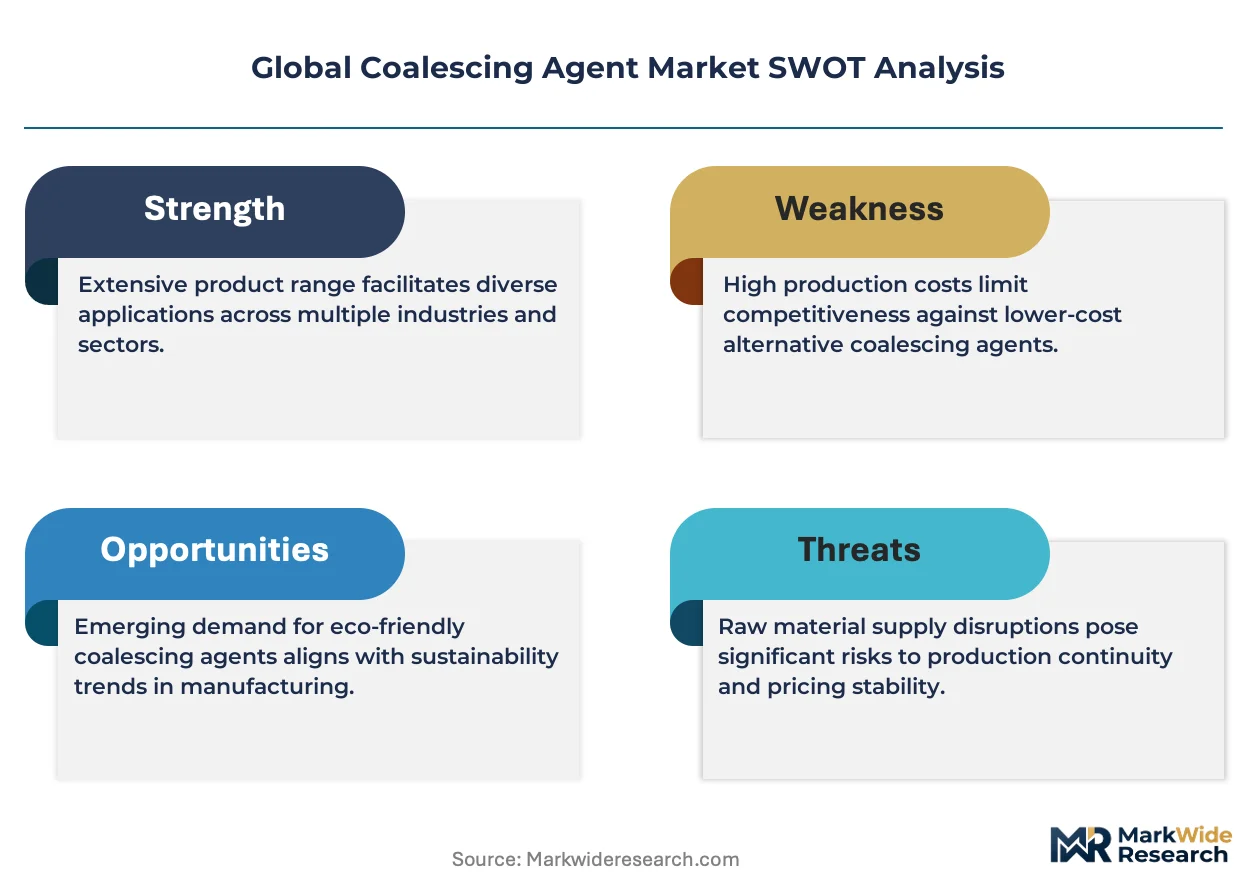
Modular additive bundling is consolidating buyer choice across the coalescing agent value chain. Arkema leverages backward integration into ester alcohol chemistry to control feedstock quality and delivery reliability. Celanese Corporation anchors its position through manufacturing scale in acetyl derivatives serving industrial coatings customers. BASF SE differentiates via R&D intensity in low-VOC coalescent platforms aligned with tightening environmental standards.
Coalescing agents are film-forming additives, typically ester alcohols or glycol ethers with boiling points between 250°C and 300°C, that temporarily soften latex polymer particles during waterborne coating drying to enable continuous film formation without cracking. Texanol and butyl cellosolve variants dominate mature architectural coatings applications where cost efficiency matters. Dioxane derivatives represent the fastest-expanding product class due to superior freeze-thaw stability and compatibility with high-performance industrial formulations. Metal fabricators and packaging companies are concentrating procurement in liquid-form coalescents that integrate cleanly into automated dosing systems.
EPA VOC regulations in the United States, REACH in Europe, and China's MEE emission standards are collectively restricting solvent-based alternatives and redirecting formulation investment toward compliant waterborne systems. ISO 11890 and ASTM D6886 test methods govern how manufacturers verify VOC content for market access across jurisdictions. Stakeholders must monitor regulatory divergence between jurisdictions where compliance thresholds and test protocols are tightening on different schedules.
Market Dynamics
Waterborne coating formulation mandates across industrialized economies are compressing solvent-based alternatives while concentrating procurement among ester alcohol specialists with verified low-VOC platforms. This regulatory compression is reshaping supplier qualification criteria and accelerating backward integration among feedstock-controlled manufacturers.
Growth Catalysts
- REACH Phase-Down Schedules:The EU Green Deal's tightening VOC thresholds are forcing architectural coatings producers to reformulate with compliant coalescents, expanding addressable demand for ester alcohol platforms that meet ISO 11890 certification.
- China's Dual Carbon Goals:MEE emission standards are redirecting state-backed infrastructure procurement toward waterborne industrial coatings, concentrating volume in domestic construction chemicals channels serving urban housing builds.
- Automated Dosing Integration:Metal fabricators and packaging converters are standardizing liquid-form coalescent specifications that feed directly into precision blending systems, locking in supplier relationships with logistics-calibrated delivery windows.
Market Restraints
- Propylene Feedstock Volatility:Ester alcohol production depends on acetyl derivative supply chains exposed to petrochemical price swings, compressing margin predictability for non-integrated formulators.
- Supplier Concentration in East Asia:Glycol ether intermediate production clusters in coastal China, creating geographic risk exposure for European and North American coatings manufacturers seeking supply security.
- Freeze-Thaw Performance Trade-offs:Low-VOC coalescent alternatives often sacrifice stability under thermal cycling, limiting deployment in exterior architectural applications subject to seasonal temperature extremes.
Strategic Opportunities
- India's PLI-Backed Chemicals Sector:Production-linked incentive schemes are attracting specialty additive manufacturing investment, creating localized supply options for domestic construction chemicals demand.
- Industrial Wood Coatings Conversion:Furniture and flooring manufacturers are migrating solvent-based finishing lines to waterborne systems, opening specification windows for high-performance coalescents with enhanced block resistance.
- Bio-Based Ester Alcohol Development:Renewable feedstock-derived coalescents are qualifying for EU taxonomy-aligned procurement preferences, positioning early movers in green public tender pipelines.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Waterborne polymer science expertise remains concentrated among legacy coatings specialists, constraining rapid technical service expansion for new market entrants.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with EPA Method 24, REACH Annex XVII, and China's GB standards extends product registration timelines and fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coalescing Agent Market |
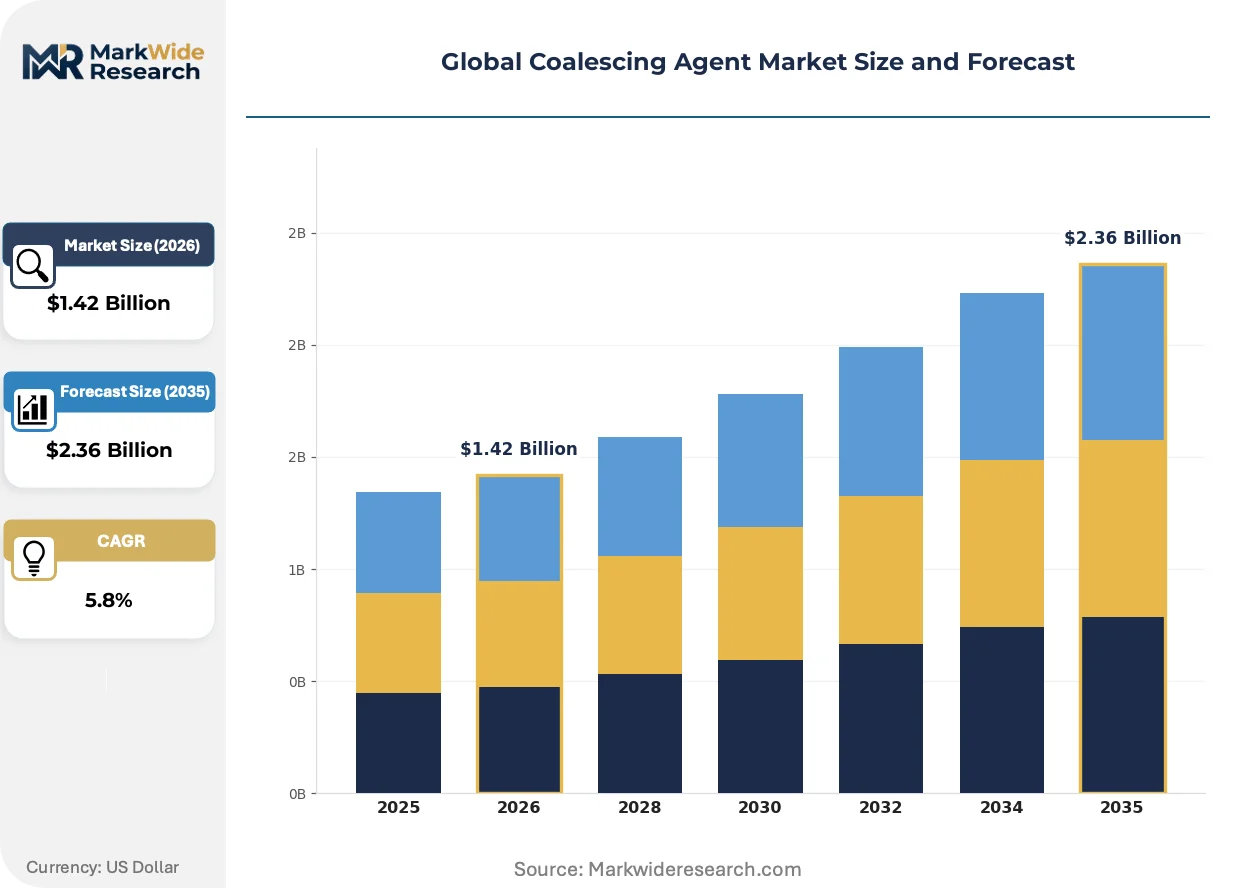
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Vinyl Acetate, Dioxane Derivatives, Butyl Cellosolve, Texanol, Amyl Acetate, Others Application: Architectural Coatings, Industrial Coatings, Inks, Adhesives, Metal Coatings, Wood Coatings End User: Paint Manufacturers, Printing Firms, Adhesive Producers, Furniture Makers, Metal Fabricators, Packaging Companies Form: Liquid, Emulsion, Powder, Paste |
| Companies Covered | Arkema, Celanese Corporation, BASF SE, Croda International Plc, Synthomer Plc, Dow Inc., Evonik Industries AG, Elementis Plc, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coalescing Agent Market Shifts & Advancements
Dioxane derivative coalescents are absorbing specification share from conventional ester alcohols as freeze-thaw stability becomes a non-negotiable performance metric for high-value industrial applications. This chemistry rotation is compressing legacy product lifecycles while rewarding suppliers with integrated derivative manufacturing capabilities.
Polymeric coalescent technology is absorbing volume in premium architectural segments where film integrity under humidity stress determines warranty coverage. German and Japanese coatings manufacturers are specifying these materials for exterior facade systems exposed to monsoon or maritime climate cycles. The technology is absorbing margin from commodity ester alcohols by enabling extended re-coat windows and reduced touch-up frequency.
REACH authorization requirements for certain glycol ethers are forcing reformulation investment across European industrial maintenance coatings. ECHA's sunset date scheduling is compressing transition timelines for protective coatings serving offshore energy infrastructure. Marine and corrosion-protection segments are responding by qualifying alternative ester alcohol blends that maintain salt-spray resistance without restricted substance content.
Specification authority is migrating from formulator technical teams to procurement functions with total-cost-of-ownership mandates. Large-scale coatings buyers in the US and Germany are consolidating supplier panels around vendors offering bundled additive packages with volume-rebate structures. This concentration is most visible in automotive OEM refinish channels where single-source agreements now cover coalescents, defoamers, and rheology modifiers.
Global Coalescing Agent Market Segmentation
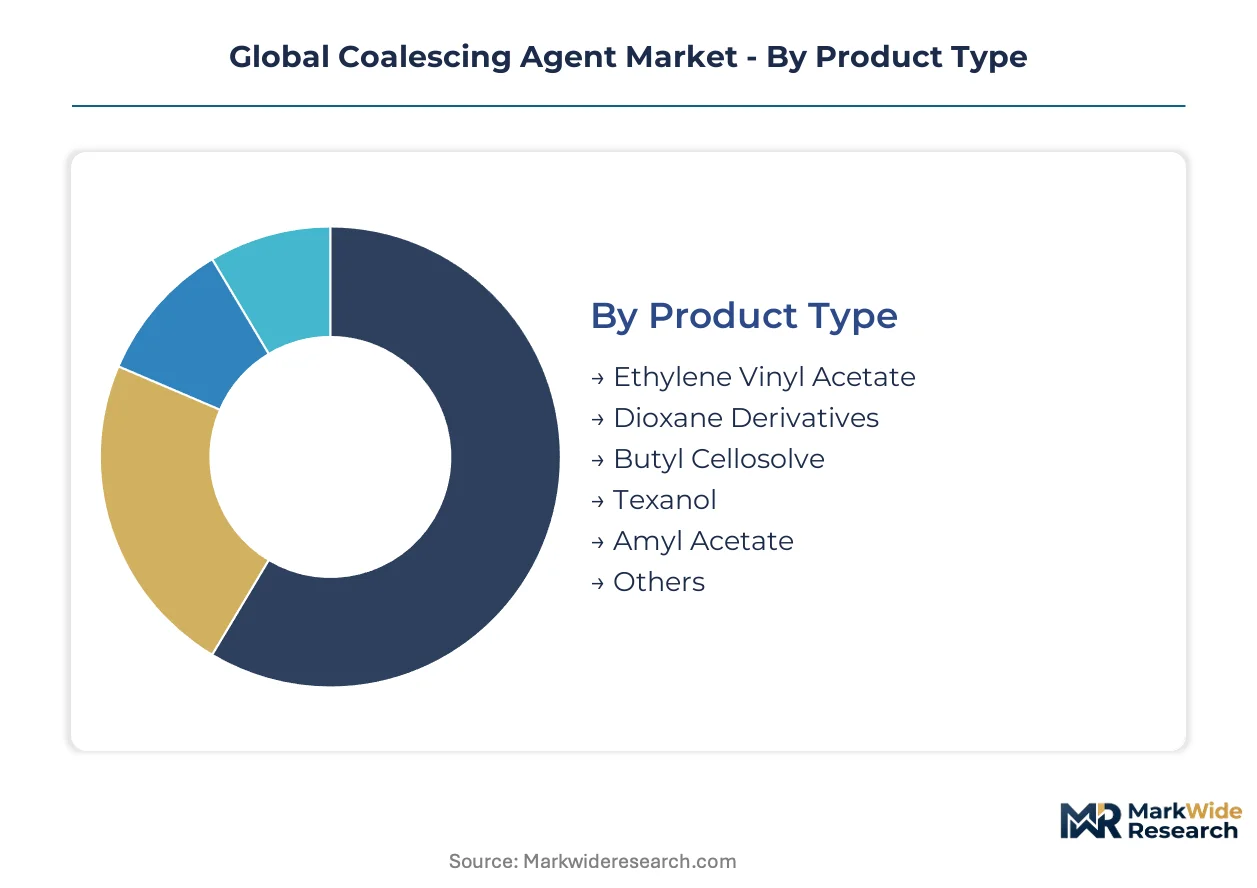
Coalescing agent procurement decisions pivot on formulation compatibility, regulatory compliance thresholds, and automated dosing requirements. Buyers segment supply by chemistry type, application performance, and physical form to align with specific coating line configurations and end-use durability standards.
Product Type:
Formulation cost tiers drive chemistry selection, with ester alcohols commanding premium positioning against glycol ether alternatives.
- Texanol:Ester alcohol chemistry with 250°C boiling point range dominates mature architectural coatings where cost efficiency and proven film formation matter. Residential construction channels in the United States concentrate procurement of this standard-grade coalescent for interior latex paints.
- Dioxane Derivatives:Cyclic ether structure delivers superior freeze-thaw stability across thermal cycling extremes. Industrial coatings manufacturers in Germany and Japan specify these materials for exterior facade systems exposed to monsoon humidity stress and maritime corrosion cycles.
- Butyl Cellosolve:Glycol ether variant serves legacy industrial maintenance formulations.
- Ethylene Vinyl Acetate:Polymer-compatible coalescent for specialty adhesive applications.
- Amyl Acetate:Ester solvent for niche printing ink formulations.
- Others:Emerging bio-based ester alcohols qualifying for EU taxonomy-aligned procurement.
Volume sits with Texanol; growth tilts toward Dioxane Derivatives.
Application:
End-use performance requirements separate specification authority between architectural generalists and industrial specialists.
- Architectural Coatings:Interior and exterior waterborne paints for residential and commercial buildings. China's state-backed urban housing programs concentrate demand through domestic construction chemicals channels serving high-volume roll-out schedules.
- Industrial Coatings:Protective and OEM finishes for machinery, equipment, and infrastructure. REACH authorization deadlines for restricted glycol ethers are compressing reformulation timelines across European marine and corrosion-protection segments.
- Wood Coatings:Furniture and flooring manufacturers in Italy and Vietnam are migrating solvent-based finishing lines to waterborne systems.
- Metal Coatings:Coil and extrusion coatings for automotive and appliance substrates.
- Inks:Waterborne printing formulations for packaging graphics.
- Adhesives:Pressure-sensitive and construction adhesive film formation.
Procurement concentrates in Architectural Coatings; specification intensity peaks in Industrial Coatings.
End User:
Customer scale and technical sophistication determine service model requirements and contract structures.
- Paint Manufacturers:Large-scale coatings producers with automated blending systems. German and US buyers are consolidating supplier panels around bundled additive packages covering coalescents, defoamers, and rheology modifiers.
- Metal Fabricators:Precision dosing integration demands liquid-form coalescents with logistics-calibrated delivery windows. Automotive OEM refinish channels in the United States now favor single-source agreements spanning multiple additive categories.
- Packaging Companies:Converters specifying liquid coalescents for automated flexographic and gravure lines.
- Printing Firms:Specialty ink formulators with batch-scale procurement.
- Adhesive Producers:Tape and label manufacturers with film-integrity requirements.
- Furniture Makers:Wood finishing operations converting from solvent-based systems.
Contract value aggregates with Paint Manufacturers; technical service intensity clusters with Metal Fabricators.
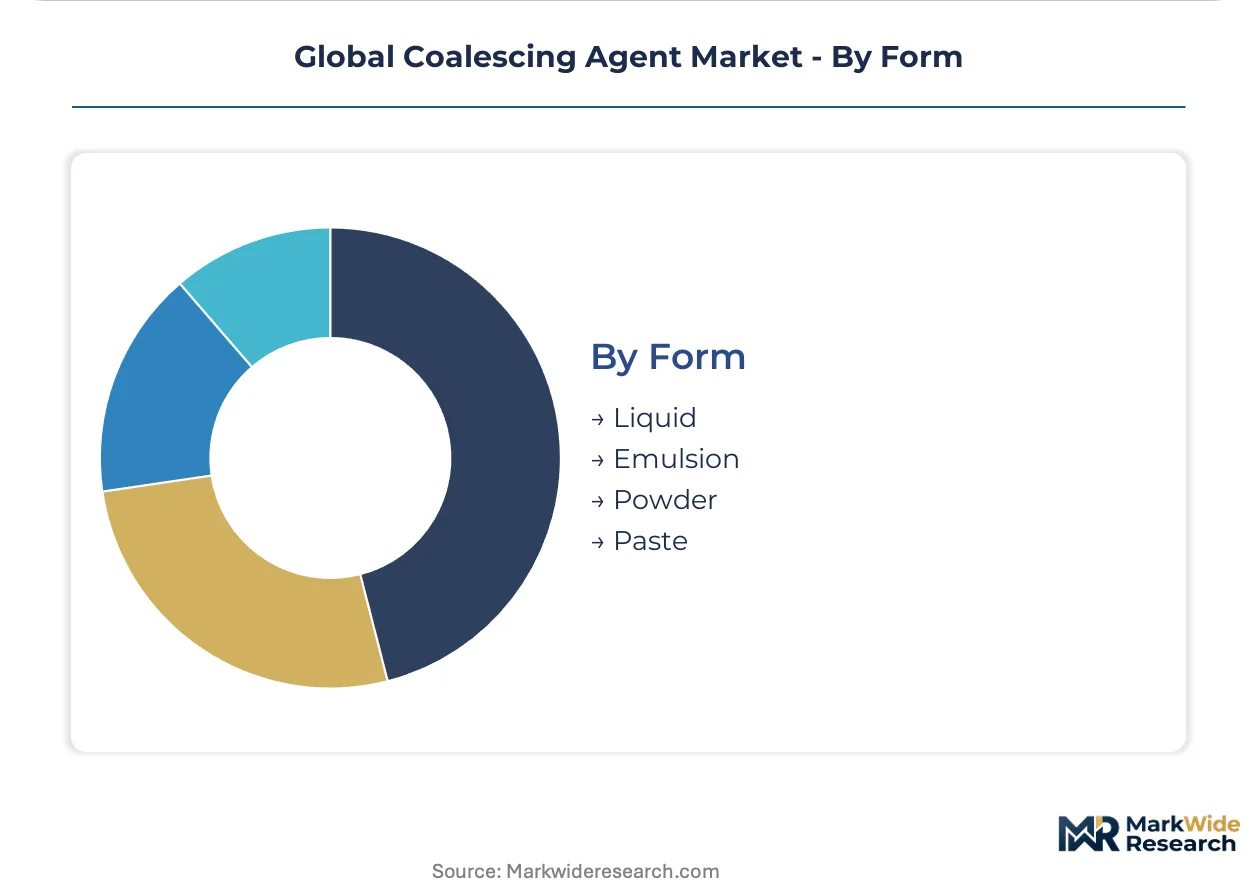
Form:
Physical state determines handling infrastructure compatibility and dosing precision capabilities.
- Liquid:Standard delivery format for automated coating lines. Metal fabricators and packaging converters across the United States and Germany are standardizing liquid-form specifications that feed directly into precision blending systems.
- Emulsion:Pre-dispersed format for high-solids waterborne formulations.
- Powder:Solid-state option for powder coating additive packages.
- Paste:High-concentration form for specialty compounding operations.
Volume flows through Liquid; Emulsion gains specification share in premium industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in coastal China and the US Gulf Coast while consumption concentrates in European architectural coatings and Indian infrastructure chemicals. This geographic mismatch creates freight-logistics dependencies that shape procurement security planning.
United States
Residential construction recovery and automotive OEM refinish demand drive ester alcohol consumption through domestic paint manufacturers. EPA Method 24 VOC enforcement compresses solvent-based formulation alternatives, redirecting specification toward compliant waterborne platforms. The Texas-Louisiana chemical corridor hosts acetyl derivative production serving Gulf Coast coatings clusters.
Germany
Industrial maintenance coatings for automotive machinery and offshore energy infrastructure absorb high-performance coalescent volumes. ECHA sunset date scheduling for restricted glycol ethers forces marine protective coatings reformulation toward alternative ester alcohol blends. The Rhine-Ruhr industrial belt concentrates technical service capabilities for specialty industrial formulations.
China
State-backed urban housing programs and dual carbon goals redirect infrastructure procurement toward waterborne construction chemicals. MEE emission standards tighten manufacturing compliance thresholds, accelerating domestic ester alcohol capacity expansion. The Yangtze River Delta anchors glycol ether intermediate production serving regional coatings manufacturers.
India
PLI-backed chemicals sector incentives attract specialty additive manufacturing investment aligned with domestic construction demand. BIS certification requirements for imported coalescents create localization pressure for multinational suppliers. Maharashtra and Gujarat industrial corridors concentrate paint manufacturing capacity serving north Indian housing builds.
Japan
Exterior facade system specifications for monsoon and maritime climate exposure drive polymeric coalescent qualification. METI chemical safety standards govern VOC content verification for architectural coatings serving Tokyo-Osaka commercial construction. The Kansai region hosts precision coatings formulators specifying humidity-stable film formation additives.
Global Coalescing Agent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across differentiated chemistry platforms. The vendor base organizes into three tiers: integrated petrochemical majors controlling acetyl derivative feedstocks, mid-scale ester alcohol specialists with regional formulation expertise, and niche polymeric coalescent developers serving premium architectural segments. Consolidation pressure concentrates among glycol ether intermediates while ester alcohol capacity fragments across Asian manufacturing sites. Dominant competitive moves include backward integration into propylene-derived feedstocks and strategic partnerships with automated dosing system manufacturers.
Among European-headquartered chemical majors, BASF SE and Evonik Industries AG occupy positions spanning multiple additive categories with integrated manufacturing footprints. Arkema exemplifies the feedstock-controlled archetype through captive ester alcohol chemistry capabilities. Eastman Chemical Company anchors the North American supply position with Gulf Coast derivative production. These three represent distinct strategic postures: diversified platform breadth, upstream integration depth, and regional scale concentration.
| Leading Market Players |
|---|
| Arkema |
| Celanese Corporation |
| BASF SE |
| Croda International Plc |
| Synthomer Plc |
| Dow Inc. |
| Evonik Industries AG |
| Elementis Plc |
| Eastman Chemical Company |
| Others |
Supply & Pricing Matrix
EU Green Deal VOC thresholds gate qualified supply access and premium-tier pricing power for coalescing agent manufacturers serving European architectural coatings channels. REACH-compliant ester alcohol platforms command price premiums against standard-grade alternatives, while non-compliant producers face exclusion from specification panels at major paint manufacturers.
Pricing Analysis
Margin tightening in standard-grade ester alcohols reflects propylene feedstock volatility and Asian capacity expansion. Contract-based long-term offtake dominates procurement between integrated majors and large paint manufacturers, while spot transactions serve smaller formulators. Price differentiation rests on REACH certification tier and automated dosing compatibility. Metal fabricators exhibit highest price sensitivity due to volume consolidation pressures; premium polymeric coalescent buyers show lowest sensitivity given warranty-driven specification requirements.
Supply Chain Analysis
Ester alcohol production rests on acetyl derivative supply chains anchored in the United States Gulf Coast, coastal China, and the Rhine-Ruhr industrial belt. Key inputs include propylene oxide, n-butanol, and specialty catalyst systems. Single-source vulnerability concentrates in glycol ether intermediates manufactured along China's Yangtze River Delta. Distribution runs through regional chemical distributors serving coatings clusters, with direct supply agreements locking in large paint manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dioxane derivative chemistry is displacing legacy Texanol formulations across high-performance industrial segments, creating technology-transition arbitrage for positioned suppliers.
For Market Incumbents: Hedge feedstock exposure through backward integration into propylene derivative production or captive ester alcohol manufacturing. Lock in specification authority at automotive OEM refinish channels through bundled additive packages covering coalescents, defoamers, and rheology modifiers. Defend against Asian cost competitors by accelerating REACH and EPA Method 24 certification investments that gate European and North American market access. For New Entrants and Emerging Players: Capture specification windows in India's PLI-backed chemicals sector where domestic construction demand outruns localized supply capacity. Target wood coatings conversion in Vietnam and Italy where solvent-based finishing lines migrate to waterborne systems without incumbent supplier lock-in. Lead with bio-based ester alcohol platforms qualifying for EU taxonomy-aligned procurement preferences at green public tender pipelines. For Investors and Strategic Acquirers: ECHA sunset date announcements for restricted glycol ethers are the leading indicator that marine and corrosion-protection segments will force rapid reformulation investment, creating M&A demand for alternative ester alcohol specialists. Long-term viability favors feedstock-integrated platforms with captive acetyl derivative production. Watch for BIS certification enforcement in India as the signal triggering multinational localization investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene derivative production insulates margin from petrochemical volatility at Arkema and Celanese. |
| Green Manufacturing Transition | Bio-based ester alcohol development unlocks EU taxonomy-aligned procurement at German and French public tenders. |
| Long-term Supply Agreement | Automated dosing integration contracts lock in logistics-calibrated delivery windows with US metal fabricators. |
| Joint Venture | Localized production partnerships in Maharashtra and Gujarat serve PLI-backed Indian construction chemicals demand. |
| Capacity Expansion | Dioxane derivative scale-up in Yangtze River Delta captures freeze-thaw stability specification share from legacy ester alcohols. |
Research Methodology
Document review covered customs and trade flow databases, SEC and ECHA regulatory filings, and ACC and Cefic industry reports, complemented by interviews with coatings plant managers, procurement leads at paint manufacturers, distribution channel partners, and technical R&D directors. Primary fieldwork validated supply chain configurations and pricing dynamics through structured discussions across Germany, the United States, China, and India. Bottom-up volume modeling triangulated against top-down market sizing from petrochemical derivative consumption patterns.
Segmentation outputs reflect chemistry type, application performance tier, physical form, and regional production hub clustering across the projection horizon. CAGRs derived from regression analysis of historical ester alcohol demand against residential construction starts, industrial coatings production indices, and regulatory phase-down schedules. Forecast inputs incorporated propylene price elasticity coefficients and REACH authorization timeline probabilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity in China, ECHA sunset date scheduling, and propylene derivative supply disruptions. A small set of named triggers—BIS certification implementation, PLI scheme expansion, and marine coatings reformulation deadlines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Piperonyl Butoxide (PBO) Market
Additives
Coating Additives Market
Additives
Europe Citric Acid Market
Additives
Global Calcium Formate Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Anti-Pollution Ingredients Market
Additives
Global Silica-Based Matting Agents Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Friction Modifier Additives Market
Additives
Global Metal Scavenging Agents Market
Additives
Phenolic Antioxidant Market
Additives
Rheological Additives Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Anti-Block Additives Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Glacial Acetic Acid Market