
 Phenolic Antioxidant Market | 2026-2036
Phenolic Antioxidant Market Size, Share, and Industry Trends Forecast 2026-2036
Phenolic Antioxidant Market Intelligence
Asset-light manufacturing models, relying on outsourced production and specialized tolling agreements, is tilting the competitive field away from capital-intensive incumbents. This shift allows specialists like SI Group to compete effectively on agility and custom formulations. Meanwhile, large-scale producers such as BASF SE leverage extensive production infrastructure to maintain dominance in high-volume segments. SONGWON differentiates through its targeted focus on polymer stabilizer solutions.
Phenolic antioxidants are organic compounds that inhibit oxidation by donating a hydrogen atom from a hydroxyl group to terminate free radical chain reactions. Their primary industrial purpose is to prevent degradation in materials such as plastics and foods. Synthetic phenolics dominate the product landscape, especially for plastics applications, due to performance and cost advantages. The natural phenolics segment, however, is expanding rapidly, particularly for use in food preservation and cosmetics.
Regulatory frameworks from the US FDA and Europe's ECHA under REACH dictate permissible substances and migration limits in food contact materials. In parallel, China's GB standards impose strict purity requirements for use in plastics and consumer goods. Successfully navigating these divergent regional compliance pathways while investing in bio-phenol development is a critical strategic imperative for manufacturers.
Market Dynamics
The central tension shaping the phenolic antioxidant market is the divergent demand between high-volume, cost-effective synthetic grades for industrial applications and the expanding requirement for high-purity or natural-origin phenolics in regulated consumer-facing sectors.
Growth Catalysts
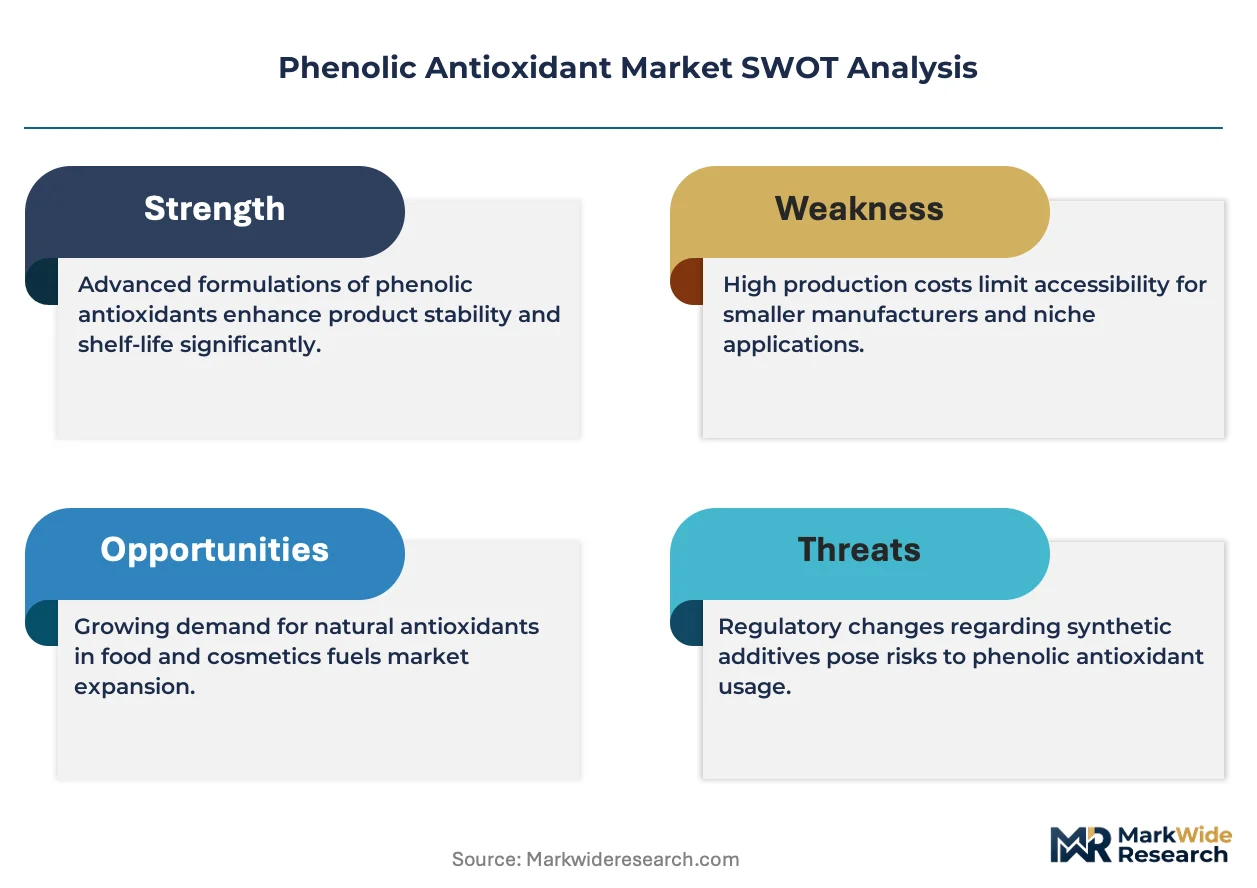
- Food Safety Mandates:Stricter regulations from bodies like the US FDA and Europe's EFSA concerning food preservation and shelf-life extension directly compel the use of approved antioxidants in processed foods and beverages.
- Polymer Industry Expansion:The concentration of polymer and plastics manufacturing, particularly in China, creates sustained volume demand for synthetic phenolic antioxidants to prevent material degradation during processing and end-use.
- Natural Product Demand:Consumer preference for "clean label" ingredients is driving the adoption of natural phenolic antioxidants beyond food into high-value cosmetics and personal care formulations for their functional properties.
Market Restraints
- Feedstock Price Volatility:The production costs for synthetic phenolics are directly linked to the price of petrochemical derivatives like phenol and isobutylene, creating margin pressure during periods of crude oil market instability.
- Regulatory Divergence:Manufacturers face complexity and increased compliance costs navigating disparate regional rules, such as Europe's ECHA REACH framework versus China's distinct GB standards for purity and food contact.
- Substitution from Non-Phenolics:In certain applications, alternative antioxidant chemistries, such as phosphites and aminic antioxidants, or non-chemical preservation methods can present a technical or cost-based substitution threat.
Strategic Opportunities
- Bio-Phenol Development:Investment in R&D for producing phenolic compounds from renewable feedstocks like lignin or plant oils opens new markets in the bio-based economy and meets sustainability goals.
- Expansion in Southeast Asia:The region's growing food processing and manufacturing sectors represent an underpenetrated market for both synthetic and natural antioxidants to improve product quality and export readiness.
- High-Purity Grades for Electronics:Developing ultra-pure phenolic antioxidants offers an opportunity to enter the specialty electronics materials market, where they can be used to protect sensitive polymer components from oxidative degradation.
Industry Challenges
- Navigating Compliance Pathways:The operational burden of securing and maintaining approvals across multiple jurisdictions with evolving chemical safety regulations, including the US, EU, and China, is a significant challenge.
- Supply Chain Agility:Incumbent manufacturers with large-scale, capital-intensive assets face challenges adapting their supply chains to compete with asset-light specialists on custom formulations and smaller batch orders.
- Technical Service Expertise:A shortage of polymer and food scientists with deep expertise in antioxidant formulation is a challenge for companies seeking to differentiate through application-specific technical support and customer collaboration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenolic Antioxidant Market |
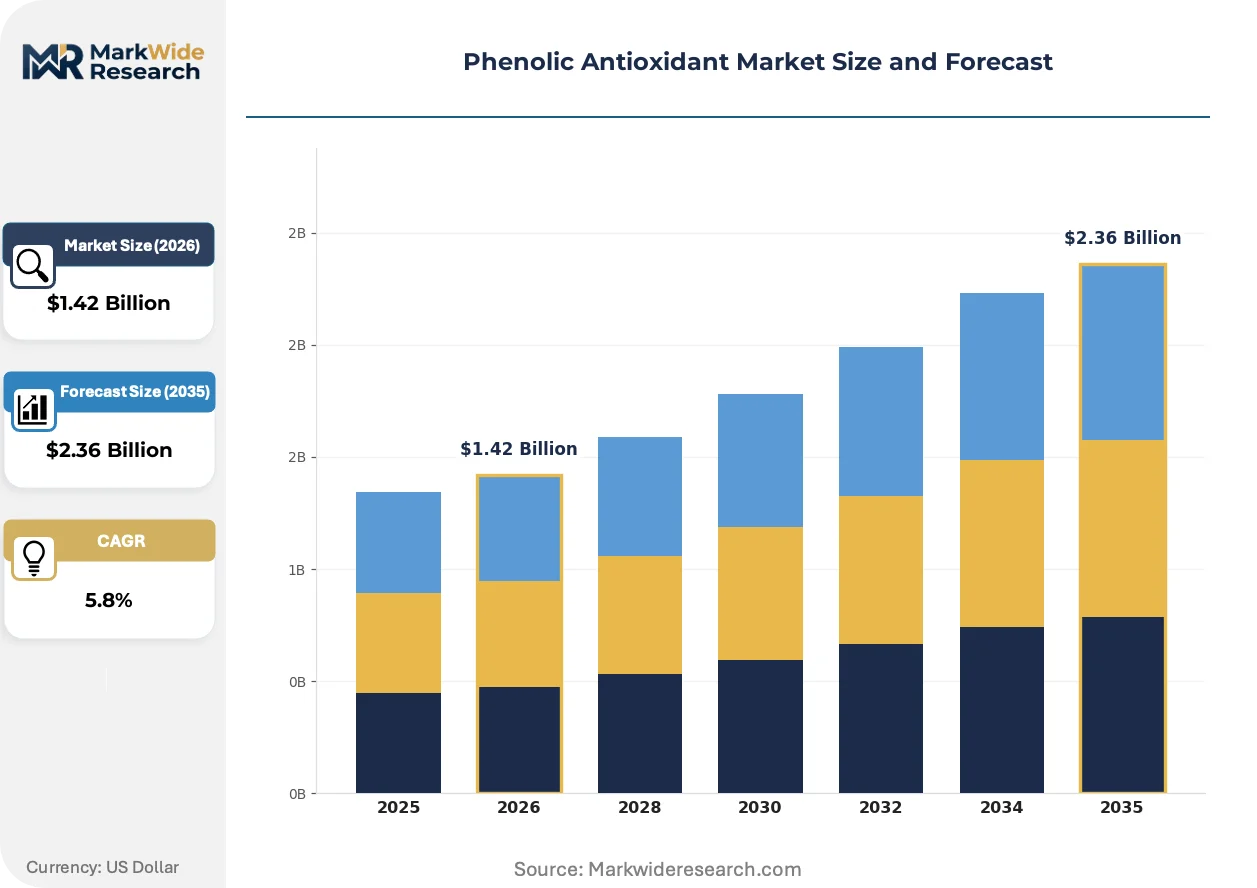
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Phenolics, Synthetic Phenolics, Bio-Phenols, Modified Phenolics Application: Food Preservation, Plastics, Cosmetics, Pharmaceuticals Form: Powder, Liquid, Granule, Tablet End User: Food & Beverage, Personal Care, Healthcare, Material Science |
| Companies Covered | ADEKA Corporation, Oxiris Chemicals, BASF SE, Clariant, DSM, SONGWON, Sumitomo Chemical Company, Mayzo Inc., SI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenolic Antioxidant Market Strategic Shifts & Innovations
The market's evolution is defined by a push-pull between the industrial need for cost-effective performance and the consumer-driven quest for sustainable and clean-label ingredients. This dynamic forces innovation in both raw material sourcing and product formulation to meet divergent end-use requirements.
Bio-phenols, derived from renewable sources like plant-based lignin, function as effective antioxidants. Adoption by the food, beverage, and cosmetics industries is accelerating to satisfy consumer demand for natural and sustainable ingredients. The market's product development focus is migrating from a reliance on purely petrochemical-based antioxidants toward a more balanced portfolio that includes bio-based alternatives for premium, consumer-facing applications.
Europe's REACH regulation, enforced by the European Chemicals Agency (ECHA), mandates comprehensive data submission for chemical registration. This process increases the cost and time required to bring new phenolic antioxidants to market within the EU. The plastics and food-contact material segments are most affected, as they must provide extensive documentation proving the substance's safety and limited migration, pushing investment toward pre-approved or bio-derived compounds.
A clear behavioral shift is occurring in how end-users source antioxidants, moving away from bulk commodity purchases. This change favors suppliers capable of providing application-specific formulation guidance and customized antioxidant blends over those competing solely on volume. This trend is most pronounced within the specialty plastics and adhesives sectors in North America, where performance optimization is a key competitive differentiator.
Phenolic Antioxidant Market Segmentation
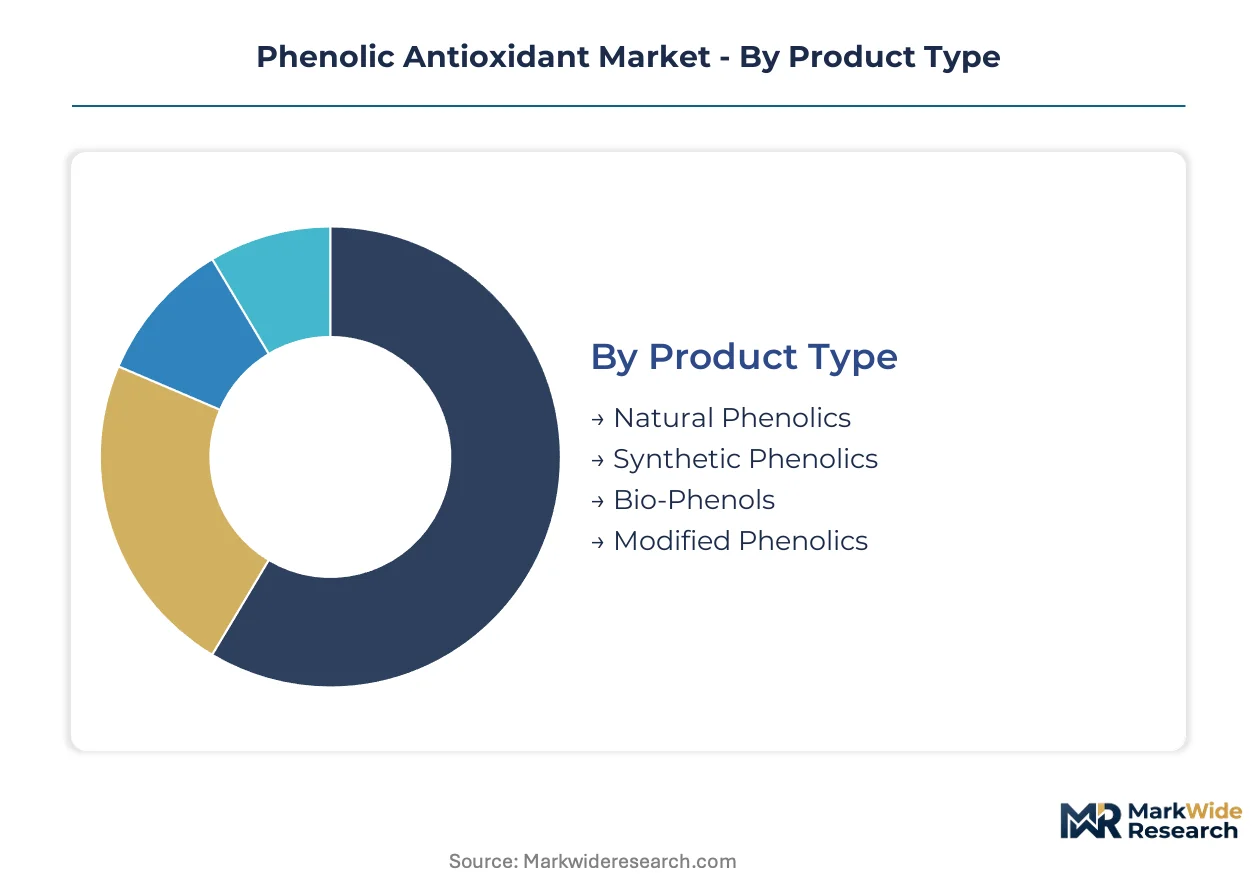
Phenolic antioxidants are crucial for material stability across diverse industries, preventing degradation and extending product lifespans. This segmentation illuminates the varied product forms, applications, and end-user requirements shaping market dynamics. Understanding these distinctions is vital for strategic positioning and product development within the market.
Product Type:
The spectrum of phenolic antioxidant product types caters to specific performance requirements and regulatory landscapes across various industries.
- Synthetic Phenolics:These are chemically synthesized compounds offering high performance and cost-effectiveness for industrial applications. Demand is concentrated in China's polymer and plastics manufacturing sector, driven by the need to prevent material degradation.
- Natural Phenolics:Derived from plant sources, these compounds are increasingly adopted for their "clean label" appeal and functional benefits. Their use is expanding rapidly in food preservation and cosmetics, driven by consumer preference.
- Bio-Phenols:These are phenolic compounds produced from renewable feedstocks like lignin or plant oils. Investment in research and development aims to meet sustainability goals and open new markets in the bio-based economy.
- Modified Phenolics:These are chemically altered phenolic structures designed to enhance specific properties such as solubility, stability, or compatibility. They address niche applications requiring tailored performance characteristics.
Established volume favors Synthetic Phenolics; emerging adoption favors Natural Phenolics.
Application:
The wide diversity of applications for phenolic antioxidants reflects their versatile protective properties across industrial and consumer sectors.
- Plastics:Phenolic antioxidants are essential for preventing oxidative degradation in polymers during processing and end-use, extending product lifespan. The concentration of polymer manufacturing, particularly in China, creates sustained volume demand.
- Food Preservation:These compounds inhibit spoilage and extend the shelf-life of processed foods and beverages by preventing oxidation. Stricter regulations from bodies like the US FDA and Europe's EFSA directly compel their use.
- Cosmetics:Phenolic antioxidants protect cosmetic formulations from degradation and offer benefits for skin health. Consumer preference for "clean label" ingredients drives adoption in high-value personal care products.
- Pharmaceuticals:Antioxidants stabilize active pharmaceutical ingredients and excipients, preserving drug efficacy and shelf-life. High-purity grades are critical for regulatory compliance and product integrity.
Industrial scale demand anchors the Plastics segment, while consumer health concerns elevate Food Preservation requirements.
Form:
The physical form of phenolic antioxidants significantly influences their handling, storage, and integration into various manufacturing processes.
- Powder:This form is widely used due to its ease of storage, transport, and precise dosing in many industrial applications. It is particularly prevalent in the plastics and polymer industries for bulk processing.
- Liquid:Liquid forms offer advantages in terms of ease of dispersion and consistent blending, especially in continuous manufacturing processes. They are often preferred in certain food and beverage applications for uniform distribution.
- Granule:Granular forms reduce dust and improve flowability, enhancing worker safety and processing efficiency. They are suitable for bulk handling in large-scale industrial settings.
- Tablet:Tablet forms provide pre-measured doses, simplifying application and reducing potential for error or contamination. This form finds use in specific, controlled batch processes.
Versatility and cost-effectiveness drive the Powder segment, while processing efficiency favors Liquid formulations.
End User:
Diverse end-user industries impose distinct performance, purity, and regulatory requirements on phenolic antioxidant suppliers.
- Food & Beverage:This sector uses phenolic antioxidants extensively to prevent spoilage, maintain freshness, and extend the shelf-life of products. Stricter mandates from regulators like the US FDA and Europe's EFSA bolster this use case.
- Material Science:This segment encompasses polymer, plastics, and other industrial material manufacturers that rely on antioxidants to prevent degradation. Demand for synthetic phenolics is concentrating in China's polymer and plastics manufacturing sector.
- Personal Care:This industry utilizes phenolic antioxidants in cosmetics and personal care products for their anti-aging and preservative properties. Consumer preference for "clean label" ingredients drives adoption of natural variants.
- Healthcare:The healthcare sector employs antioxidants in pharmaceutical formulations and medical devices to ensure product stability and integrity. High-purity grades are essential for sensitive applications.
The Food & Beverage sector remains a foundational consumer, while Material Science represents broad industrial consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global phenolic antioxidant market exhibits varied import-export dynamics, significantly influenced by regional manufacturing capacities and regulatory demands. Countries with advanced chemical industries often serve as net exporters, while emerging economies with expanding industrial bases drive import volumes. This balance dictates local supply availability and pricing structures across different geographies.
China
Demand for synthetic phenolics in China stems from its dominant polymer and plastics manufacturing sector, crucial for preventing material degradation. China's GB standards impose strict purity requirements for these materials, influencing local production and import specifications. Industrial clusters in the Yangtze River Delta and Pearl River Delta drive sustained volume consumption for a wide array of industrial applications.
United States
The United States market sees strong demand for phenolic antioxidants in food preservation and specialty plastics, driven by consumer safety. US FDA regulations directly compel their use for shelf-life extension in processed foods and beverages, ensuring product integrity. Chemical manufacturing hubs in Texas and Louisiana concentrate production and distribution activities, supporting diverse end-user industries.
Germany
Germany's market for phenolic antioxidants is shaped by advanced manufacturing and stringent European Union regulations for chemical safety. Europe's ECHA REACH framework dictates permissible substances and migration limits in food contact materials, impacting formulation choices. The Rhine-Ruhr region, a major industrial area, leverages these compounds in high-performance polymers and innovative food packaging solutions.
Vietnam
Vietnam's expanding food processing and manufacturing sectors create a rising demand for phenolic antioxidants, especially for export-oriented goods. The country's food safety standards are evolving, aligning with international export requirements for product quality and shelf-life. Industrial zones near Ho Chi Minh City and Hanoi are seeing increased adoption for both synthetic and natural variants in various consumer products.
Phenolic Antioxidant Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large-scale incumbents and agile specialist manufacturers. Large producers leverage extensive infrastructure to dominate high-volume segments, while asset-light models enable specialists to compete on custom formulations. Key strategic archetypes include global chemical conglomerates, regional niche players, and technology-focused innovators. Dominant competitive moves involve capacity expansion for commodity grades and strategic partnerships for specialized applications.
At the scale-driven end, Germany-based BASF SE exemplifies a global chemical conglomerate, leveraging extensive production infrastructure to maintain dominance in high-volume segments. This entity benefits from integrated supply chains and broad geographic reach across industrial applications. Switzerland-based SI Group, conversely, represents agile specialists, focusing on custom formulations and specialized tolling agreements that enable responsiveness. SI Group competes effectively on agility and provides tailored solutions for diverse customer needs. SONGWON, a South Korean firm, occupies a position as a targeted innovator, differentiating through its focused development of polymer stabilizer solutions for specific material performance requirements.
| Leading Market Players |
|---|
| ADEKA Corporation |
| Oxiris Chemicals |
| BASF SE |
| Clariant |
| DSM |
| SONGWON |
| Sumitomo Chemical Company |
| Mayzo Inc. |
| SI Group |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for global trade, influence cost dynamics for phenolic antioxidants, directly impacting supply concentration and downstream price differentiation across regions. This critical corridor determines the economic viability of importing bulk synthetic phenolics, especially for industrial applications.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for high-volume synthetic phenolic antioxidants. Price differentiation stems from quality grade, adherence to US FDA or China GB purity standards, and the volume scale of purchases. Margin pressure stems from petrochemical feedstock volatility, impacting synthetic product costs. Plastics manufacturers demonstrate high price sensitivity for synthetic grades, contrasting with lower sensitivity among personal care brands for bio-phenols.
Supply Chain Analysis
Regulatory restrictions on chemical purity and migration limits, such as Europe's ECHA REACH framework, limit the flow of non-compliant phenolic antioxidants across borders. Supply concentration centers on China for synthetic phenolics, with specialized production also in Germany and the United States. Raw material dependencies include phenol and isobutylene for synthetics, alongside lignin and plant oils for bio-phenols. Feedstock price volatility represents a significant structural risk. Downstream distribution involves direct sales to large industrial users and specialized distributors for consumer-facing sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phenolic antioxidant market is undergoing high-growth disruption, driven by the bio-phenol development trend and stricter food safety mandates. Strategic positioning is crucial for sustained competitiveness.
For Market Incumbents:Harden core synthetic portfolios by investing in process efficiency and backward integration into petrochemical feedstocks. This defends against margin pressure from feedstock volatility and competition from asset-light specialists. Invest in advanced R&D for customized formulations to counter substitution threats from non-phenolics. Enhance technical service expertise to support application-specific customer needs.
For New Entrants and Emerging Players:Build out capabilities in bio-phenol production from renewable feedstocks like lignin, targeting the rapidly expanding natural phenolics segment. Focus on Southeast Asia's growing food processing sector, which is underpenetrated for high-purity antioxidants. Offer application-specific technical support and customized blends to differentiate from bulk commodity suppliers.
For Investors and Strategic Acquirers:Carve-out targets emerge from large chemical conglomerates seeking to divest non-core specialty chemical divisions. Over a five-to-ten-year window, strategic investors should prioritize agile specialists with strong R&D in bio-phenols or high-purity grades for electronics. The signal to watch is an acceleration in regulatory approvals for novel bio-derived antioxidant compounds.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-Phenols | Supports rising consumer demand for natural and sustainable ingredients in food and cosmetics. |
| Investment in Custom Formulation R&D | Addresses end-user shift towards application-specific guidance and tailored antioxidant blends. |
| Strategic Partnerships for Regulatory Navigation | Simplifies compliance across US FDA, Europe's ECHA, and China's GB standards. |
| Development of High-Purity Grades | Opens new market opportunities in sensitive electronics and pharmaceutical applications. |
| Backward Integration into Renewable Feedstocks | Mitigates feedstock price volatility and aligns with sustainability goals for bio-based economy. |
Research Approach
A standing panel of polymer R&D directors, food safety specialists, chemical procurement leads, and regulatory affairs experts provided ongoing calibration for market insights. This primary input was combined with secondary validation from US FDA public filings, Europe's ECHA REACH database, China's GB standards publications, and industry association reports, employing both bottom-up and top-down triangulation.
Scenario-bracketing framed the analytical framework, assessing market evolution across the analysis window. Segmentation dimensions modeled included product type (synthetic, natural, bio-phenol), application (plastics, food preservation, cosmetics), end-user (Food & Beverage, Material Science), and regional regulatory clusters. Compound annual growth rates were derived by factoring historical trends, market dynamics, and projected shifts in key industry-specific forecast inputs like petrochemical feedstock prices and consumer preference shifts for natural ingredients.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large-scale producers or innovative specialists would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Flux Injection System Market
Additives
Global Coalescing Agent Market
Additives
Antimicrobial Additives Market
Additives
United Kingdom Feed Additives Market
Additives
Apocarotenal Market
Additives
Global Sodium Acetate Market
Additives
Triazine UV Absorber Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Sodium Benzoate Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Additives for Floor Coatings Market
Additives
Dipotassium Guanylate Market
Additives
Nucleating and Clarifying Agents Market
Additives
Maltitol Based on Corn Starch Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Global Scale Inhibitors Market