
 Europe Anti-Caking Market | 2026-2036
Europe Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anti-Caking Market Foresight
German chemical producers is repositioning silica gel capacity toward pharmaceutical-grade specifications. BASF SE leverages integrated precursor supply chains to dominate technical-grade powder output. Evonik Industries AG specializes in precipitated silica for moisture-sensitive drug formulations. Merck KGaA anchors high-purity calcium carbonate production for European tablet manufacturers.
Anti-caking agents are hygroscopic or hydrophobic substances, typically silica gel with surface areas exceeding 300 m²/g or modified starches with amylopectin ratios above 70%, applied at 0.5-2.0% w/w to maintain free-flowing properties in bulk solids. Silica gel formulations command premium positioning in moisture-critical pharmaceutical applications where caking compromises dosage uniformity. Starch alternatives register the fastest trajectory as food processors reformulate around clean-label mandates and EFSA scrutiny of synthetic additives. Powder forms sustain volume leadership across agricultural fertilizer blending operations where mechanical handling demands consistent flow behavior.
REACH registration requirements and EFSA additive authorizations shape product development timelines and reformulation costs for suppliers seeking European market access. The EU Green Deal's chemical sustainability targets and national implementations of CSRD reporting obligations force disclosure of anti-caking agent sourcing and carbon intensity. Stakeholders must monitor evolving ECHA substance evaluations and member-state fertilizer regulations to anticipate restriction cascades affecting calcium carbonate and talc applications.
Market Dynamics
REACH substance evaluations and EFSA additive authorizations are compressing development timelines for synthetic anti-caking formulations while redirecting R&D budgets toward bio-based starch alternatives. German and French food processors now mandate supplier disclosure of carbon intensity under CSRD reporting obligations, forcing upstream chemical producers to reconfigure precursor supply chains.
Growth Catalysts
- Clean-label reformulation mandates:EFSA scrutiny of synthetic additives drives food manufacturers toward modified starch alternatives with amylopectin ratios above 70%. French dairy processors lead adoption of rice-derived anti-caking systems.
- Pharmaceutical moisture-control specifications:Precipitated silica with surface areas exceeding 300 m²/g commands premium positioning in moisture-sensitive drug formulations. German tablet manufacturers anchor regional demand for pharmaceutical-grade powder.
- Fertilizer blending automation:Mechanical handling requirements in Western European agricultural corridors sustain volume demand for free-flowing calcium carbonate formulations. Powder forms dominate bulk solids processing operations.
Market Restraints
- Input cost volatility in silicate precursors:Sodium silicate price fluctuations compress margins for precipitated silica producers dependent on energy-intensive fusion processes.
- REACH registration concentration:Only five chemical conglomerates hold complete dossiers for synthetic anti-caking substances, creating supply bottleneck risk for specialty formulations.
- Technical limitation in high-fat matrices:Hydrophobic silica gel demonstrates reduced efficacy in lipid-rich food systems above 15% fat content, limiting application scope in premium confectionery.
Strategic Opportunities
- Underpenetrated Eastern European processed food corridors:Polish and Romanian salt and spice processors lag Western counterparts in anti-caking adoption, presenting white-space expansion for starch-based formulations.
- EU Green Deal chemical sustainability targets:National implementation of bio-based substitution mandates creates procurement preference for carbon-negative starch alternatives in public-sector food contracts.
- Technology convergence in nano-encapsulation:Combination of modified starches with cellulose nanocrystals enables dual-function anti-caking and controlled-release systems for functional food applications.
Industry Challenges
- Certification timeline compression:Novel Food approvals under EFSA procedures now average 18-24 months, delaying market entry for innovative bio-based formulations and straining working capital.
- Cross-border regulatory fragmentation:Member-state fertilizer regulations diverge on calcium carbonate purity thresholds, forcing producers to maintain multiple product specifications for intra-EU trade.
- Legacy equipment incompatibility:Existing pneumatic conveying systems in German chemical plants require retrofitting to handle lower-bulk-density starch alternatives without segregation or dusting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anti-Caking Market |
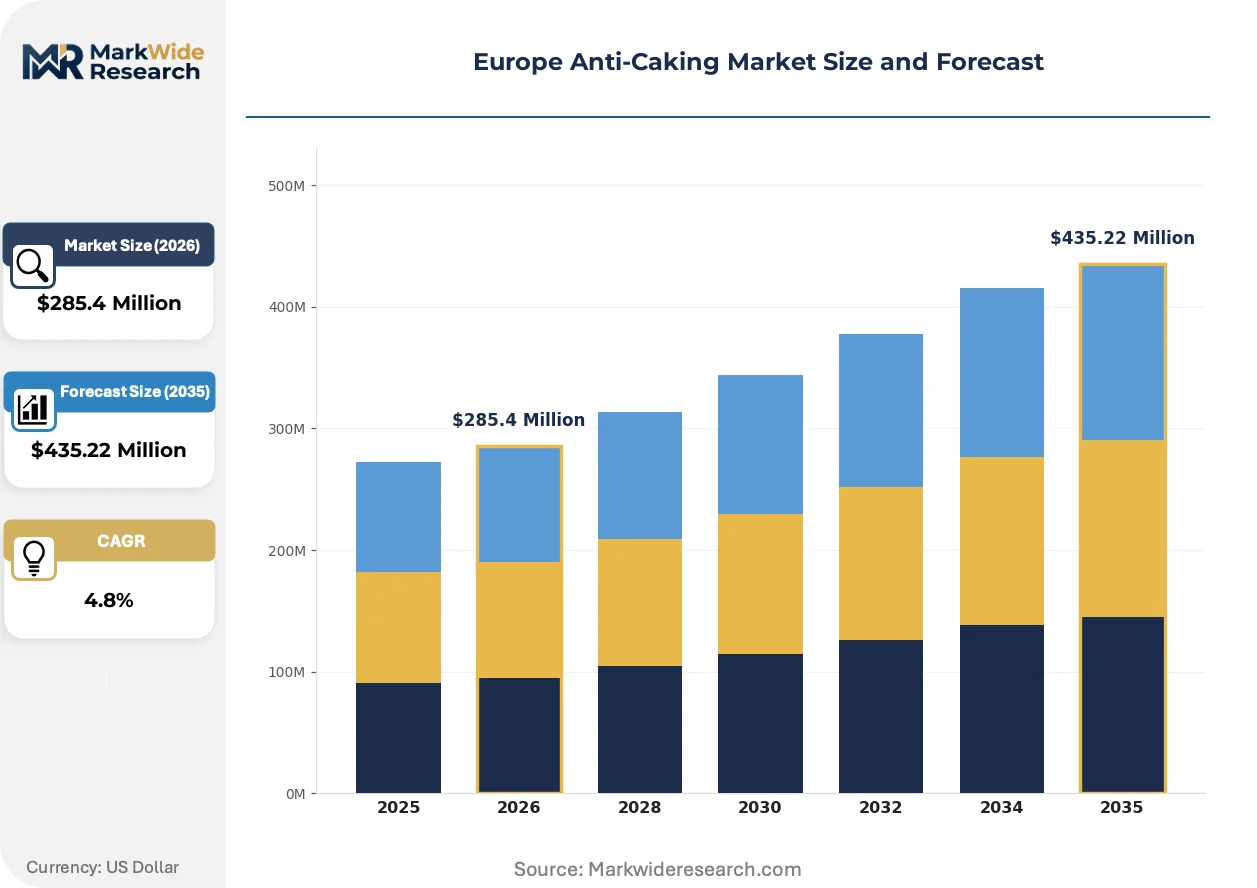
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel, Calcium Carbonate, Talc, Starch Application: Food Products, Pharmaceuticals, Chemicals, Agriculture Form: Powder, Granules, Liquid, Pellets Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | BASF SE, Merck KGaA, Evonik Industries AG, Cargill, Incorporated, Kao Corporation, Roquette Frères, Norkem Limited, PPG Industries, Solvay, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anti-Caking Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine competitive positioning in European anti-caking supply. Three developments dominate current strategic planning.
Enzymatically debranched starches with tailored amylopectin architecture are rewriting performance benchmarks for clean-label applications. Italian pasta and German bakery producers are accelerating qualification timelines for these bio-based alternatives. The technology is compressing the historical premium commanded by synthetic silica in mid-tier food segments.
REACH authorization sunset dates for synthetic silicates are forcing portfolio restructuring among specialty chemical producers. The industrial consequence is accelerated divestment of technical-grade powder capacity toward pharmaceutical-grade specifications. Moisture-critical drug formulations in Switzerland and the Netherlands face supply tightest as producers prioritize higher-margin segments.
Direct-procurement platforms linking agricultural cooperatives with anti-caking suppliers are disintermediating traditional distributor networks in fertilizer applications. French and Belgian crop nutrition blenders now contract powder volumes through digital tender systems. This channel shift is most visible in the Benelux corridor where mechanical blending operations concentrate.
Europe Anti-Caking Market Segmentation
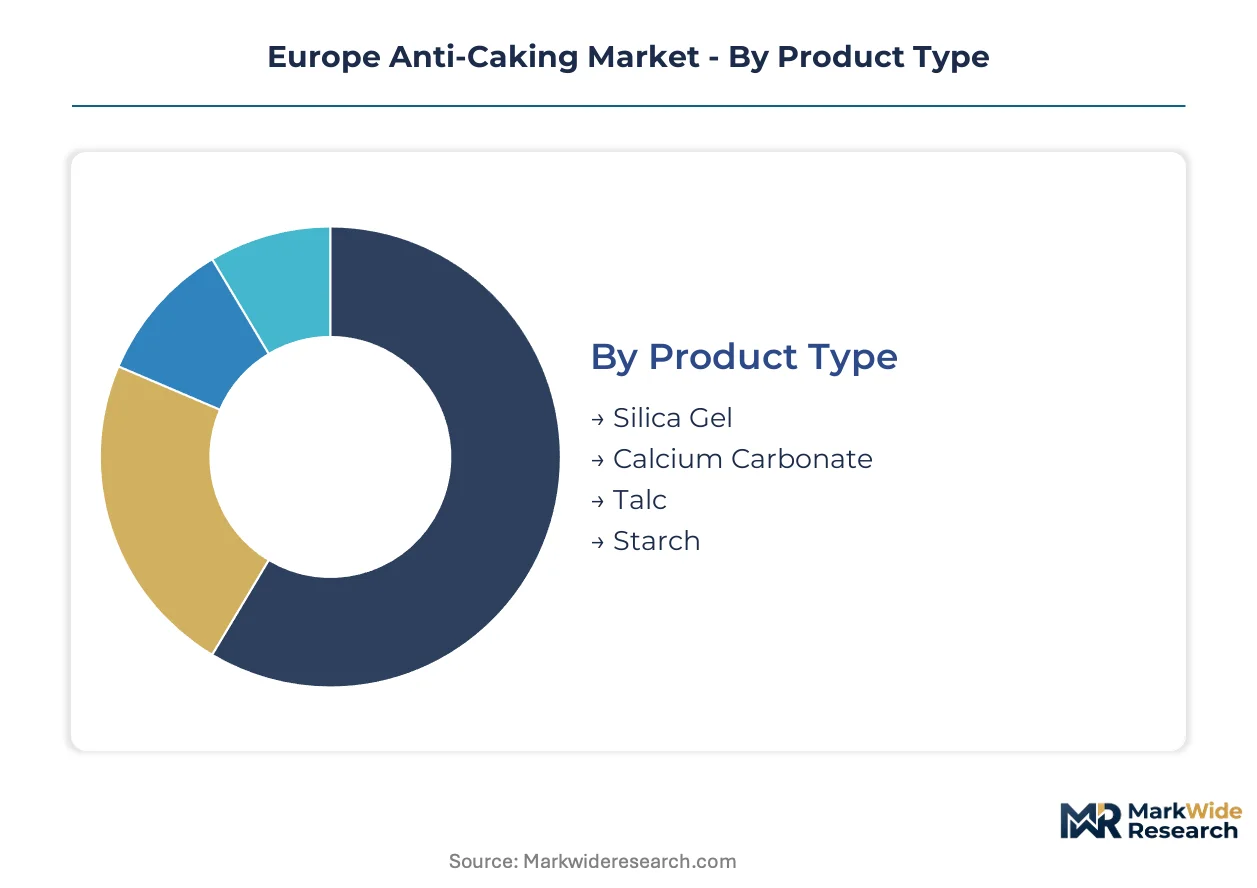
Anti-caking agent procurement patterns diverge sharply across end-use specifications, with pharmaceutical moisture-control tolerances demanding surface-area thresholds that agricultural applications ignore. Formulation chemistry and regulatory classification together determine supplier qualification pathways and margin structures.
Product Type:
Precipitated silica capacity concentrates among German and Dutch chemical producers with fused-silicate precursor integration.
- Silica Gel:Amorphous silicon dioxide with surface areas exceeding 300 m²/g delivers superior moisture adsorption for pharmaceutical tablet formulations. German tablet manufacturers anchor regional demand for pharmaceutical-grade specifications where caking compromises dosage uniformity.
- Starch:Enzymatically modified starches with amylopectin ratios above 70% enable clean-label positioning for EFSA-compliant food applications. French dairy processors lead adoption of rice-derived systems as synthetic additive scrutiny intensifies.
- Calcium Carbonate:Ground and precipitated grades serve fertilizer blending operations across Western European agricultural corridors.
- Talc:Magnesium silicate formulations face REACH substance evaluation pressures restricting food-contact applications.
Silica gel absorbs the bulk of installed capacity; starch is expanding most quickly.
Application:
End-use specifications fragment procurement requirements across moisture-sensitivity thresholds and regulatory exposure levels.
- Food Products:Clean-label mandates from French and German processors drive starch substitution for synthetic additives in salt, spice, and dairy powder formulations. EFSA authorization timelines compress supplier development cycles for novel bio-based entrants.
- Pharmaceuticals:Moisture-critical drug formulations in Switzerland and the Netherlands command premium positioning for precipitated silica with validated surface-area specifications. Evonik Industries and Merck KGaA anchor supply relationships with dosage-form manufacturers.
- Chemicals:Industrial powder handling operations rely on calcium carbonate and talc for bulk solids flow assurance.
- Agriculture:Mechanical fertilizer blending across Benelux and French crop nutrition corridors sustains volume demand for free-flowing powder formulations.
Food products command the widest supplier base; pharmaceuticals extract the steepest specification premiums.
Form:
Physical presentation determines handling economics and dispersion uniformity across pneumatic conveying systems.
- Powder:Fine particulate grades dominate agricultural fertilizer blending and high-volume food processing where mechanical handling demands consistent flow behavior. German chemical plants require retrofitting to accommodate lower-bulk-density alternatives without segregation.
- Granules:Intermediate particle sizes reduce dusting in salt and spice processing operations across Polish and Romanian facilities.
- Liquid:Suspension formulations enable spray-application integration in specialized coating operations.
- Pellets:Compacted forms address specific handling requirements in automated dosing systems.
Powder forms carry the volume concentration; granules are gaining adoption in Eastern European processing corridors.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and procurement digitization maturity across end-use segments.
- Direct Sales:Large-volume fertilizer blenders in France and Belgium increasingly contract powder volumes through digital tender platforms, disintermediating traditional distributor networks. Agricultural cooperatives drive this channel shift in the Benelux corridor.
- Distributors:Technical-grade silica and calcium carbonate move through specialty chemical distributors serving mid-tier food processors without direct supplier relationships.
- Online:E-procurement platforms gain traction for standardized grades with documented specifications.
- Retail:Small-format packaging serves artisanal food producers and research-scale pharmaceutical operations.
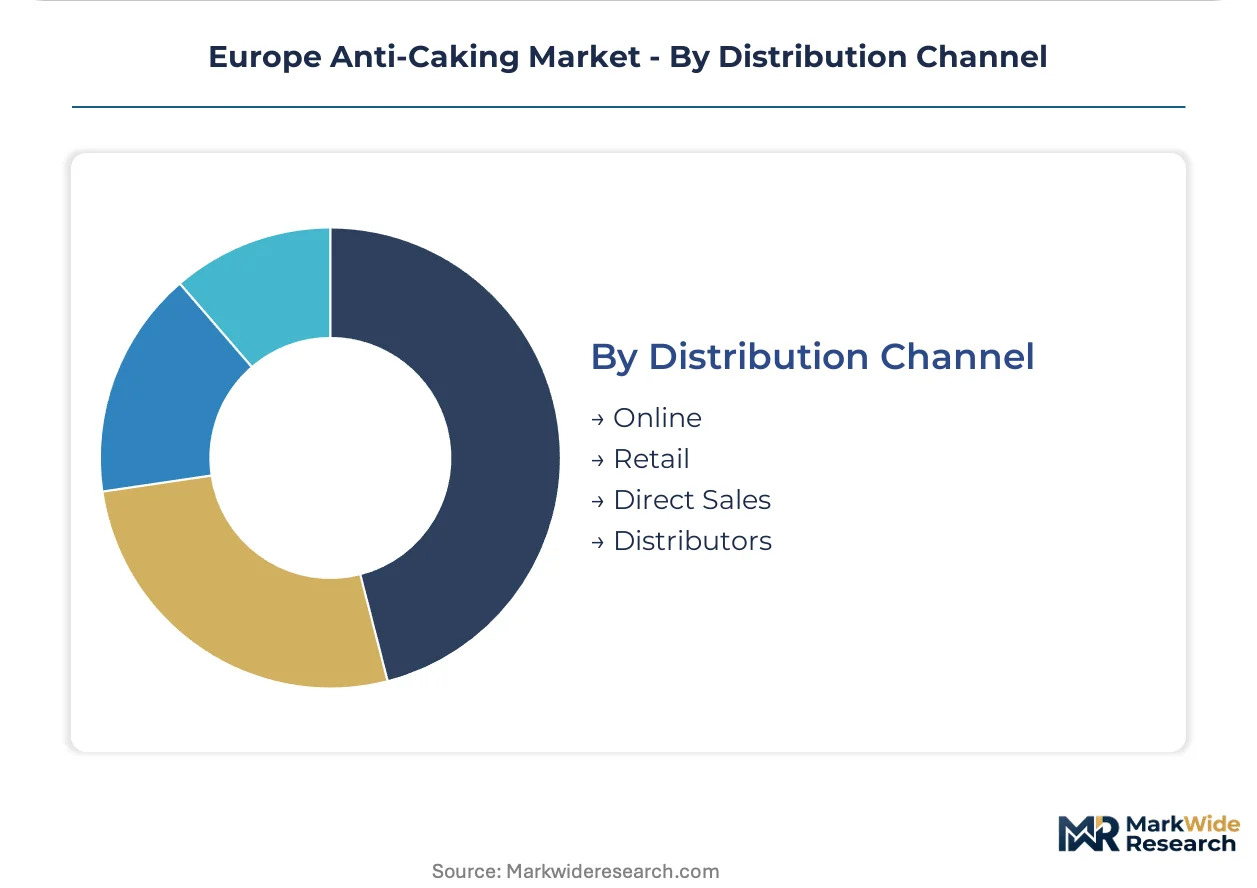
Direct sales capture the largest contract values; online channels are climbing the fastest in standardized-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sodium silicate fusion capacity clusters along the Rhine corridor anchor European precipitated silica supply. German chemical producers leverage integrated precursor chains to serve pharmaceutical and food-grade demand. REACH authorization timelines and CSRD carbon disclosure obligations reshape procurement patterns across national borders.
Germany
Pharmaceutical tablet manufacturers in North Rhine-Westphalia drive demand for high-purity precipitated silica with validated surface-area specifications. REACH registration concentration among five chemical conglomerates creates supply bottleneck risk for specialty formulations. BASF SE and Evonik Industries AG anchor production clusters in Ludwigshafen and Hanau, repurposing technical-grade capacity toward pharmaceutical-grade output.
France
Dairy powder processors in Brittany and Normandy accelerate adoption of rice-derived starch anti-caking systems under clean-label mandates. EFSA scrutiny of synthetic additives compresses supplier development cycles for novel bio-based entrants. Roquette Frères maintains starch modification facilities in Lestrem, supplying enzymatically debranched alternatives to Parisian food conglomerates.
Netherlands
Mechanical fertilizer blending operations in the Rotterdam-Antwerp corridor sustain volume demand for free-flowing calcium carbonate formulations. Direct-procurement platforms disintermediate traditional distributor networks as agricultural cooperatives adopt digital tender systems. Merck KGaA anchors high-purity calcium carbonate production for Benelux pharmaceutical tablet manufacturers.
Poland
Salt and spice processors in the Łódź and Poznań regions lag Western counterparts in anti-caking adoption, presenting white-space expansion for starch-based formulations. Member-state fertilizer regulations on calcium carbonate purity thresholds diverge from German standards, forcing producers to maintain multiple product specifications. Granule-form anti-caking agents gain traction in Eastern European processing corridors to reduce dusting.
Switzerland
Moisture-critical drug formulations in Basel and Zurich command premium positioning for precipitated silica as producers prioritize higher-margin pharmaceutical segments. Swissmedic regulatory requirements exceed EMA baseline standards for excipient documentation. Evonik Industries AG specializes in supply relationships with Swiss dosage-form manufacturers facing supply tightness from capacity reallocation.
Europe Anti-Caking Market Competitive Landscape
Global majors compete with regional champions across integrated precursor access and regulatory dossier completeness. Five chemical conglomerates hold complete REACH registration portfolios for synthetic anti-caking substances, creating tiered supply access. The competitive structure segments into integrated silicate producers, starch modification specialists, and regional chemical distributors. Dominant moves include capacity reallocation toward pharmaceutical-grade specifications and backward integration into bio-based feedstock cultivation.
Among integrated chemical producers, BASF SE, Evonik Industries AG, and Merck KGaA occupy positions anchored by fused-silicate precursor chains and validated pharmaceutical-grade output. BASF SE exemplifies the technical-grade-to-pharmaceutical pivot as REACH sunset dates approach. Evonik Industries AG represents specialization in moisture-critical drug formulations. Merck KGaA anchors high-purity mineral production for tablet manufacturers. Cargill, Incorporated and Roquette Frères sit within the starch modification tier, supplying enzymatically processed alternatives to synthetic silica as EFSA clean-label pressure intensifies.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Evonik Industries AG |
| Cargill, Incorporated |
| Kao Corporation |
| Roquette Frères |
| Norkem Limited |
| PPG Industries |
| Solvay |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification premiums diverge sharply from technical-grade commodity pricing, compressing margins for synthetic silica producers while rewarding REACH-registered incumbents with pricing power anchored in regulatory dossier completeness. This tiered structure manifests in supply chain configurations where German and Dutch chemical producers with fused-silicate precursor integration capture value upstream, while Eastern European fertilizer blenders face procurement constraints from REACH registration concentration among five conglomerates.
Pricing Analysis
Technical service bundling separates pharmaceutical-grade precipitated silica from unbundled commodity powder, with validation documentation and surface-area certification commanding substantial premiums over agricultural-grade calcium carbonate. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and REACH dossier completeness, with pharmaceutical tablet manufacturers showing lowest price sensitivity and Eastern European salt processors most responsive to volume discounts. Pricing pressure stems from sodium silicate precursor volatility in energy-intensive fusion processes, squeezing margins for technical-grade producers without backward integration into silicate supply.
Supply Chain Analysis
Dual-sourcing mandates from French dairy processors and German pharmaceutical manufacturers require multi-supplier qualification for critical anti-caking inputs, forcing procurement teams to maintain parallel relationships with both integrated chemical majors and specialized starch modifiers. Supply concentrates in Germany, the Netherlands, and France, with sodium silicate fusion capacity clustering along the Rhine corridor and enzymatic starch modification facilities anchoring in northern France. Raw material dependencies span silicate precursors, agricultural feedstocks for enzymatic processing, and mineral carbonates for fertilizer applications. Single-source vulnerability risks emerge from REACH registration concentration, while distribution runs through direct-procurement platforms disintermediating traditional specialty chemical distributors in the Benelux agricultural corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
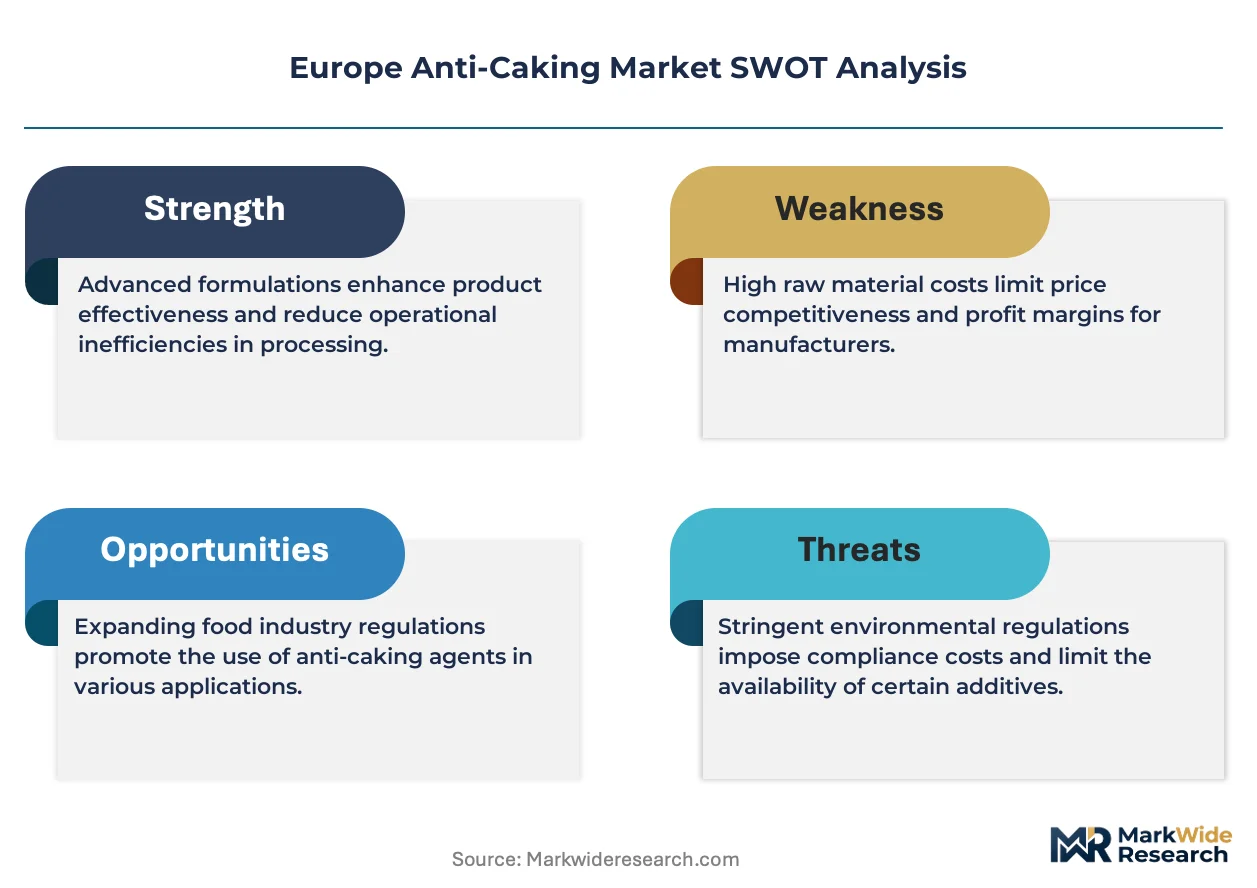
REACH authorization timelines and EFSA additive scrutiny have erected a cost-of-compliance moat that rewards dossier-complete incumbents while straining working capital for novel bio-based entrants facing 18-24 month Novel Food approval cycles.
For Market Incumbents: Deepen backward integration into enzymatic starch feedstock cultivation to secure cost positioning against synthetic silica substitution, while accelerating capacity reallocation toward pharmaceutical-grade specifications before REACH sunset dates eliminate technical-grade revenue streams. Defensive consolidation through selective acquisition of Eastern European distribution networks addresses emerging competitor threats from Polish and Romanian salt processors adopting granule-form alternatives. For New Entrants and Emerging Players: Capture white-space expansion in Polish and Romanian salt and spice processing corridors where anti-caking adoption lags Western European benchmarks by several years, positioning rice-derived starch systems as clean-label alternatives to synthetic additives. Direct-procurement platform partnerships with agricultural cooperatives offer the most penetrable go-to-market angle, bypassing entrenched distributor relationships in the Benelux fertilizer corridor. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic starch modification specialists given EU Green Deal bio-based substitution mandates and carbon-negative procurement preferences in public-sector food contracts. Long-term viability across the next decade hinges on regulatory dossier completeness rather than scale alone, making REACH-registered mid-tier producers with novel bio-based pipelines attractive acquisition targets. Watch ECHA substance evaluation cascades affecting calcium carbonate and talc applications as the critical inflection signal for portfolio restructuring timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzymatic Feedstock Supply | Roquette Frères and Cargill secure captive rice and waxy maize cultivation to reduce input cost volatility for modified starch output. |
| REACH Dossier Completion for Novel Silicates | Specialty chemical producers invest registration resources to maintain market access before authorization sunset dates eliminate competitors. |
| Pharmaceutical-Grade Capacity Reallocation | BASF SE and Evonik Industries AG pivot technical-grade silica production toward validated surface-area specifications for moisture-critical drug formulations. |
| Direct-Procurement Platform Partnerships | Agricultural cooperatives in France and Belgium adopt digital tender systems, disintermediating traditional distributor networks in fertilizer applications. |
| Cellulose Nanocrystal Technology Convergence | Modified starch producers combine with nanocellulose platforms to enable dual-function anti-caking and controlled-release systems. |
Research Methodology
Document review covered EFSA additive authorization databases, REACH registration dossiers, and EU Green Deal implementation guidelines, complemented by interviews with plant managers at German chemical producers, procurement leads at French dairy processors, and regulatory affairs directors at pharmaceutical excipient suppliers. Secondary validation drew from ECHA substance evaluation reports, Cefic chemical industry statistics, and customs trade data for silicate precursor flows. Bottom-up demand modeling across end-use segments triangulated with top-down capacity assessments from integrated producers.
Cross-referencing historical price trajectories for sodium silicate and modified starches against panel input from procurement officers anchored forecast calibration across the projection horizon. Segmentation dimensions modeled included product type tier, end-use application specification, physical form factor, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating EFSA scrutiny intensity and CSRD carbon disclosure adoption curves as industry-specific demand shapers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization timeline delays, EFSA Novel Food approval bottlenecks, and EU Green Deal bio-based mandate enforcement variance. Deviation in ECHA substance evaluation cascades affecting synthetic silicate classifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Defoaming Coating Additives Market
Additives
Middle East Feed Additives Market
Additives
Shortstop Inhibitor Market
Additives
Citric Acid Market
Additives
Global Coalescing Agent Market
Additives
Polyols and Sorbitols Products Market
Additives
Global Corrosion Inhibitor Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Paint Additives Market
Additives
Packaging Coating Additives Market
Additives
Global Isosorbide Market
Additives
Metal Deactivators Market
Additives
Sodium Potassium Tartrate Market
Additives
Automotive Coolant Additives Market
Additives
Cement Grinding Aid and Performance Enhancers Market