
 Cassia Gum Market | 2026-2036
Cassia Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Cassia Gum Market Analysis
Plant-based hydrocolloid purification is narrowing the performance gap between cassia gum and established galactomannans like locust bean gum. Tate & Lyle leverages its ingredient science infrastructure to develop standardized cassia gum grades for pet food multinationals. Roquette Frères anchors European supply security through backward integration into Indian raw material sourcing. Altrafine Gums dominates regional extraction capacity from its Ahmedabad base.
Cassia gum, derived from the endosperm of Cassia tora and Cassia obtusifolia seeds, contains a galactomannan polysaccharide with a mannose-to-galactose ratio of approximately 5:1, functioning primarily as a viscosifier and water-binding agent in canned pet food and textured protein systems. The food industry segment leads volume consumption due to pet food reformulation trends, while the thickening agent application captures the dominant margin pool as manufacturers seek cost-stable alternatives to guar and carob derivatives. Online retail distribution is accelerating fastest among channels, reflecting bulk ingredient procurement digitization by mid-sized processors.
FDA recognition of cassia gum as Generally Recognized As Safe for pet food applications under 21 CFR establishes US market access parameters, while EU REACH registration and EFSA evaluations govern European import and labeling standards. India's BIS quality certification and FSSAI food-grade specifications shape export readiness for domestic processors. Stakeholders must monitor regulatory divergence between pet food-grade and human food-grade approval pathways as classification decisions in major jurisdictions will determine addressable market boundaries.
Market Dynamics
Pet food manufacturers in the United States and Western Europe are systematically reformulating wet pet food to replace locust bean gum with cassia gum, creating a structural demand pull that is concentrating procurement contracts among processors capable of delivering standardized, EU-compliant grades.
Growth Catalysts
- EU REACH Registration:Completed registrations under ECHA enable European pet food manufacturers to legally incorporate cassia gum into wet formulations, removing a decade-long regulatory barrier to adoption.
- Clean-Label Pet Food:Consumer preference for recognizable ingredient declarations drives multinational pet food brands to seek plant-based hydrocolloids with simpler supply chains than guar derivatives.
- Gujarat Processing Clusters:Concentrated extraction capacity around Ahmedabad and Rajkot provides volume scalability and cost structures that match industrial procurement thresholds.
Market Restraints
- Seed Price Volatility:Raw material costs for Cassia tora seeds fluctuate with monsoon patterns across Rajasthan and Gujarat, compressing processor margins during poor harvest cycles.
- Supply Concentration Risk:Over 80% of global cassia gum extraction capacity sits within a 200-kilometer radius in western India, creating single-point vulnerability to regional logistics disruptions.
- Human Food-Grade Exclusion:EFSA has not approved cassia gum for direct human consumption, limiting addressable market to pet food and industrial applications despite functional equivalence to approved galactomannans.
Strategic Opportunities
- Textured Protein Systems:Plant-based meat manufacturers in Germany and the Netherlands are piloting cassia gum as a water-binding agent in extruded protein matrices, opening adjacent demand beyond pet food.
- Online Bulk Procurement:Digital platforms connecting Indian processors directly with mid-sized European pet food co-manufacturers are compressing distributor margins and capturing volume previously routed through traditional trading houses.
- PLI Scheme Alignment:India's Production Linked Incentive schemes for food processing infrastructure could subsidize extraction facility upgrades, lowering capital barriers for quality certification investments.
Industry Challenges
- Galactomannan Standardization:Batch-to-batch viscosity variation in crude extracts requires processors to invest in chromatographic purification equipment, extending payback periods for smaller operators.
- Dual Certification Burden:Simultaneous compliance with FDA 21 CFR pet food standards and EU REACH registration demands parallel documentation systems that strain quality assurance teams at mid-cap processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cassia Gum Market |
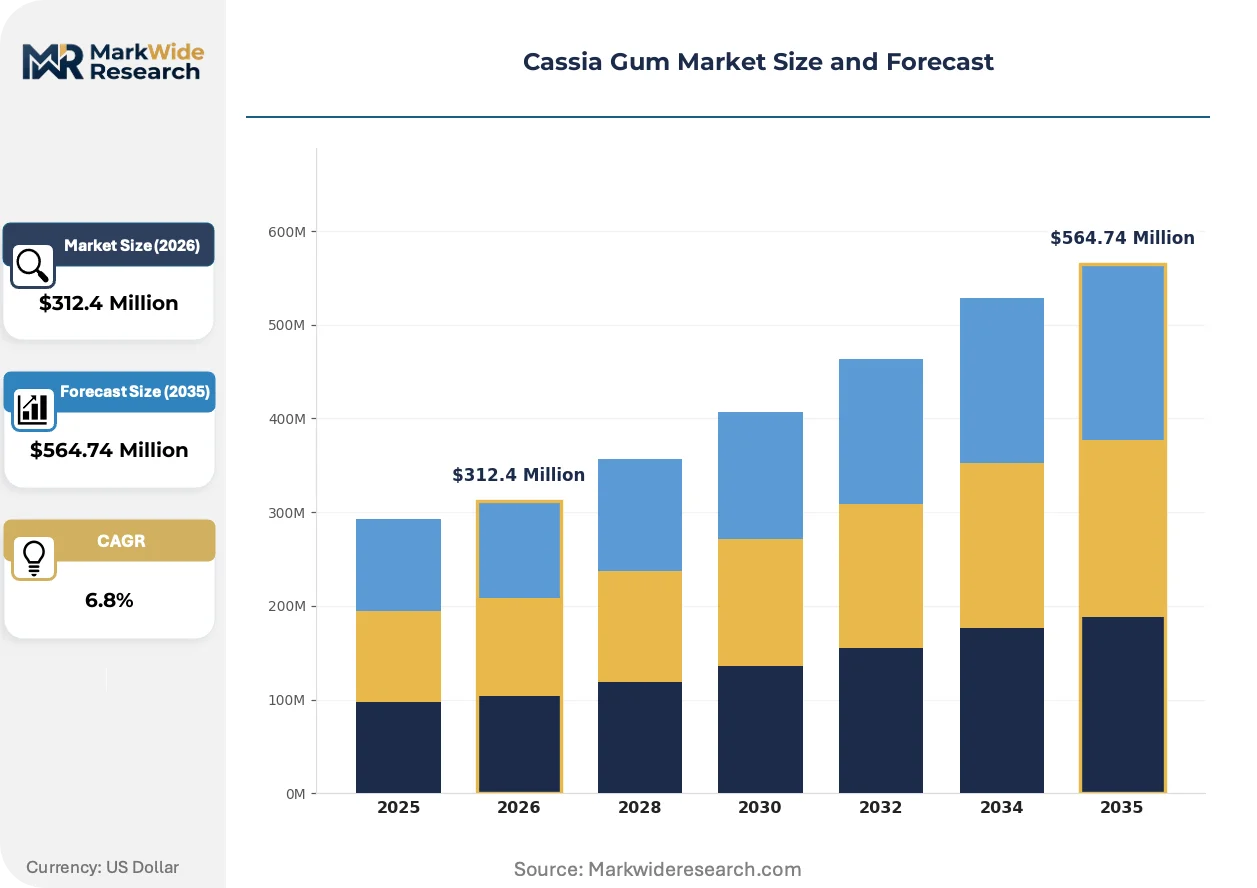
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
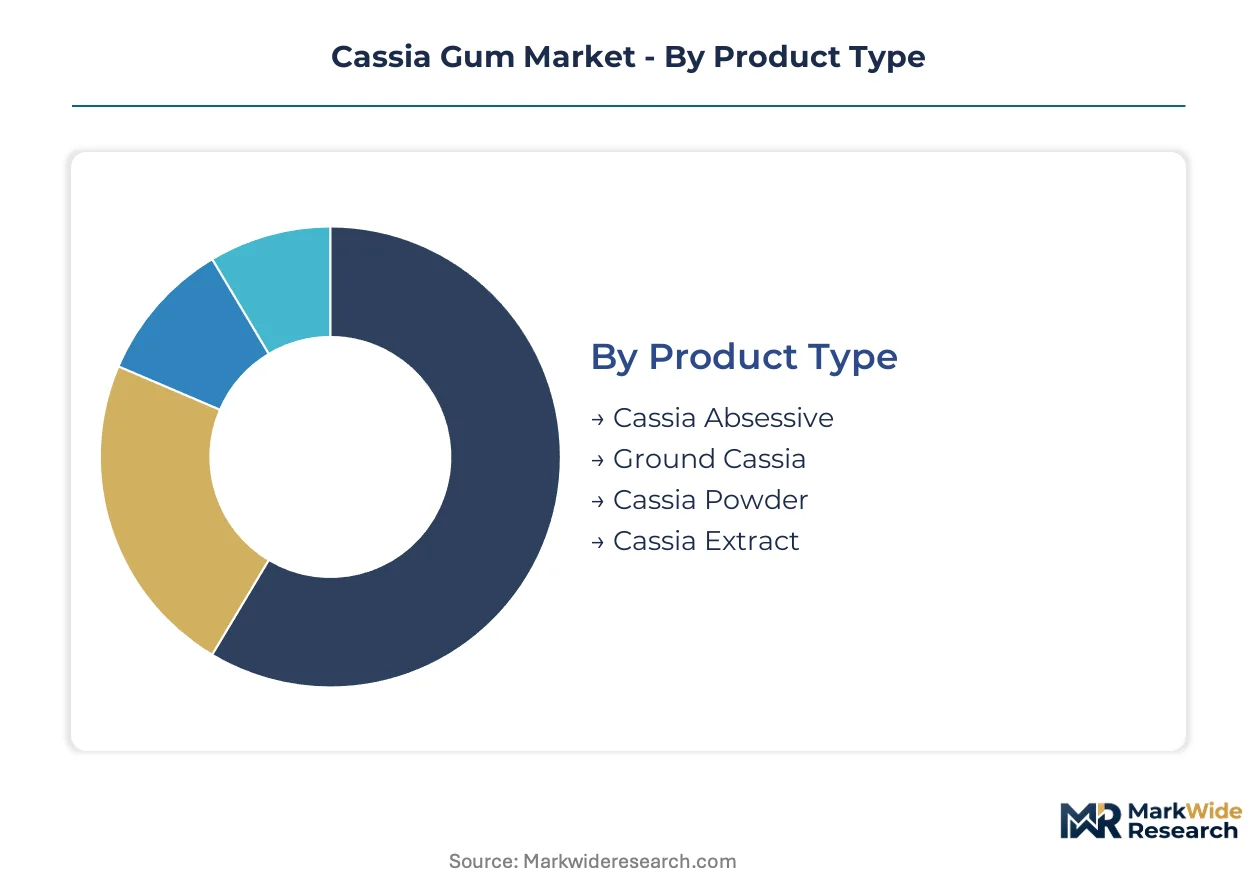
| Segmentation | Product Type: Cassia Absessive, Ground Cassia, Cassia Powder, Cassia Extract End User: Food Industry, Pharmaceuticals, Personal Care, Nutrition Application: Thickening Agent, Flavoring Agent, Stabilizer, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Tate & Lyle, Roquette Frères, Ingredion Incorporated, CP Kelco, The Lubrizol Corporation, Altrafine Gums, Agro Gums, JD Gums and Chemicals, Hindustan Gum & Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cassia Gum Market Emerging Trajectories
Processing technology and regulatory alignment are converging to elevate cassia gum from a commodity substitute to a specification-grade ingredient, with digitization of procurement channels accelerating competitive restructuring among suppliers.
Enzymatic purification of cassia gum extracts is migrating from pilot-scale demonstration to commercial deployment among Ahmedabad-based processors. European pet food multinationals are qualifying these enzyme-treated grades for premium wet food lines previously reserved for locust bean gum. This technology is compressing the performance gap between cassia gum and established galactomannans, enabling specification substitution without formulation rework.
EFSA evaluations of cassia gum for extended pet food applications are tightening purity thresholds for anthraquinone content. Processors must deploy solvent extraction or supercritical CO2 systems to meet emerging limits, raising capital intensity for market access. German and Dutch pet food manufacturers are responding by consolidating supplier lists to processors with verified in-house testing capabilities, privileging integrated over merchant extraction operations.
Direct procurement relationships between European pet food co-manufacturers and Indian extraction facilities are displacing traditional Amsterdam and Hamburg trading houses as the primary intermediaries. Mid-sized processors in Gujarat are establishing dedicated export desks with FSSAI-certified laboratories to serve this channel shift. This pattern is most visible in wet cat food formulations, where batch sizes and formulation stability requirements favor direct supplier accountability over spot-market purchasing.
Cassia Gum Market Segmentation
Cassia gum's functional versatility across viscosity modification, water binding, and texturization creates distinct specification requirements by downstream application. Procurement patterns diverge sharply between pet food multinationals demanding standardized grades and industrial buyers prioritizing cost-stable volume supply.
Product Type:
Processing intensity defines the use-case spectrum, from minimally processed seed derivatives to refined galactomannan isolates.
- Cassia Powder:Finely milled endosperm flour with standardized mesh size and moisture content serves wet pet food manufacturers requiring consistent hydration control. European pet food co-manufacturers in Germany and the Netherlands specify enzyme-treated powder grades for premium textured protein systems.
- Cassia Extract:Purified galactomannan concentrate with elevated mannose-to-galactose ratios targets high-viscosity applications. Ahmedabad-based processors deploy chromatographic separation to meet EFSA anthraquinone thresholds for EU REACH-compliant export.
- Cassia Absessive:Crude seed preparation with minimal processing retains hull fragments for cost-sensitive industrial applications.
- Ground Cassia:Coarsely fractured endosperm material functions as a bulk texturizer in lower-specification feed formulations.
The dominant share belongs to Cassia Powder, while Cassia Extract is closing the gap fastest.
End User:
Regulatory approval boundaries shape customer access, with pet food-grade clearance separating addressable from restricted demand pools.
- Food Industry:Wet pet food manufacturers in the United States leverage FDA 21 CFR recognition to reformulate locust bean gum out of canned dog and cat food. Clean-label positioning drives multinational brands toward plant-based hydrocolloids with traceable Indian supply chains.
- Nutrition:Functional food developers in Germany pilot cassia gum as a soluble fiber source in digestive health products, pending expanded EFSA safety evaluations.
- Pharmaceuticals:Excipient applications remain constrained by absence of human food-grade regulatory clearance in major jurisdictions.
- Personal Care:Cosmetic formulators explore galactomannan rheology modification for natural-positioned skincare emulsions.
Food Industry commands the largest volume position, with Nutrition expanding most quickly as regulatory pathways mature.
Application:
Functional performance requirements stratify by the physical stresses each application imposes on hydrocolloid stability.
- Thickening Agent:Viscosity-building in high-moisture systems demands precise galactomannan concentration and heat stability. Canned pet food retort processing in US and European facilities requires grades that maintain rheological integrity across sterilization cycles.
- Stabilizer:Freeze-thaw and emulsion stability applications in textured vegetable protein systems attract German and Dutch plant-based meat manufacturers seeking cost alternatives to guar derivatives.
- Flavoring Agent:Minimal processing preserves volatile compounds for traditional medicine and specialty food applications.
- Nutraceuticals:Prebiotic fiber positioning targets gut health formulations with specific viscosity and fermentability profiles.
Thickening Agent holds the established revenue base, while Stabilizer gains share fastest through plant-based protein adoption.
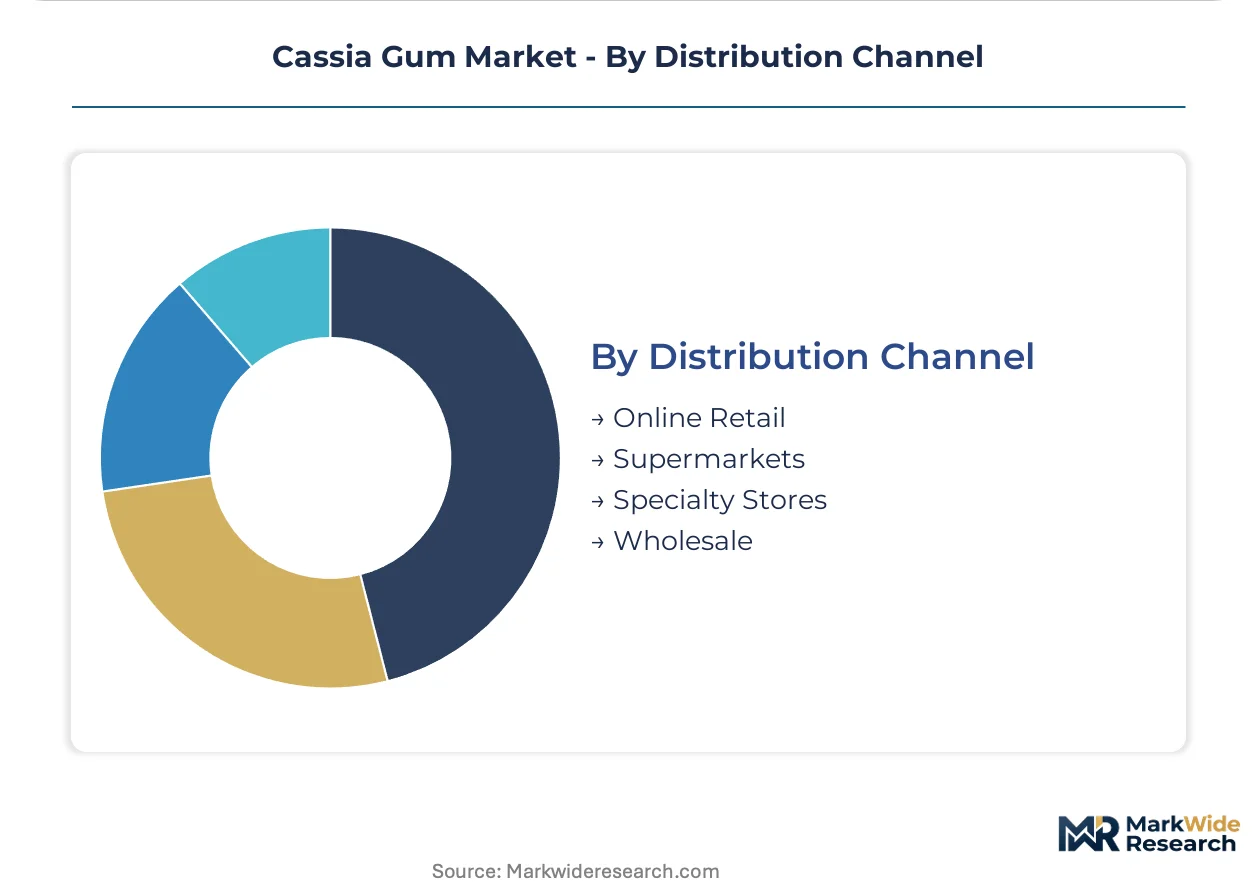
Distribution Channel:
Procurement scale and relationship intensity determine channel selection, with digitization reshaping mid-market access patterns.
- Online Retail:Digital platforms enable direct contracting between Gujarat processors and mid-sized European pet food co-manufacturers, compressing traditional Amsterdam and Hamburg trading house margins.
- Wholesale:Volume aggregation through established importers serves multinational pet food brands with standardized procurement protocols and audit requirements.
- Supermarkets:Limited retail-packaged cassia gum availability targets small-scale food processors and specialty bakers.
- Specialty Stores:Regional ingredient distributors serve niche cosmetic and pharmaceutical formulators with technical consultation.
Wholesale retains the dominant volume flow, though Online Retail is climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Indian processing clusters dominate international trade, while import demand concentrates among pet food manufacturers seeking EU-compliant and FDA-recognized grades. The geographic distribution reflects raw material proximity on the supply side and regulatory clearance thresholds on the demand side.
India
Gujarat and Rajasthan cultivation belts supply over 80% of global raw material, with Ahmedabad and Rajkot hosting concentrated extraction capacity. FSSAI food-grade specifications and BIS quality certification shape export readiness for domestic processors. The PLI scheme for food processing infrastructure is subsidizing chromatographic purification equipment upgrades among mid-cap operators.
Germany
Wet pet food manufacturers in Lower Saxony and Bavaria drive European demand for enzyme-treated cassia gum grades. EFSA evaluations and ECHA REACH registration govern import eligibility and purity thresholds. Hamburg trading houses are losing volume share to direct procurement relationships between co-manufacturers and Gujarat processors.
United States
Multinational pet food brands reformulate canned dog and cat food under FDA 21 CFR recognition of cassia gum as GRAS. Midwestern production facilities source standardized powder grades for retort-stable formulations. The absence of human food-grade clearance limits addressable market to pet food applications despite functional equivalence to approved hydrocolloids.
Netherlands
Plant-based meat manufacturers in the Randstad region pilot cassia gum as a water-binding agent in extruded protein matrices. Dutch facilities require EU REACH-compliant extracts with verified anthraquinone levels below emerging EFSA thresholds. Rotterdam logistics hubs facilitate bulk ingredient consolidation for redistribution to German and Belgian processors.
France
Pet food co-manufacturers in Brittany and the Grand Est region qualify Indian-sourced grades for private-label wet food lines. ANSM oversight of feed-grade imports runs parallel to EU REACH requirements. Paris-based ingredient distributors are consolidating supplier lists to processors with in-house solvent extraction capabilities.
Cassia Gum Market Vendor Landscape
On the supply side, the industry is bifurcated between multinational ingredient houses with formulation science infrastructure and regional Indian processors with captive raw material access. European and North American buyers concentrate procurement among REACH-registered and FDA-recognized suppliers capable of delivering standardized viscosity grades. Three archetypes dominate: integrated hydrocolloid specialists with backward control over Indian sourcing, merchant extraction operations in Gujarat selling commodity grades, and pet food-focused distributors bridging specification gaps. Competitive moves center on enzymatic purification technology licensing and direct export desk establishment to bypass traditional trading intermediaries.
Among multinational ingredient houses, Tate & Lyle and Roquette Frères exemplify the integrated specialist archetype with upstream control over raw material procurement. Altrafine Gums anchors the regional processor tier from its Ahmedabad base, representing merchant extraction operations that dominate volume supply. These three companies illustrate the competitive structure: global formulators with specification-grade capabilities, and Indian processors with cost-advantaged extraction capacity navigating dual certification burdens.
| Leading Market Players |
|---|
| Tate & Lyle |
| Roquette Frères |
| Ingredion Incorporated |
| CP Kelco |
| The Lubrizol Corporation |
| Altrafine Gums |
| Agro Gums |
| JD Gums and Chemicals |
| Hindustan Gum & Chemicals |
| Others |
Supply Flow & Price Mechanics
Ahmedabad and Rajkot processing clusters concentrate over 80% of global extraction capacity within a 200-kilometer radius, granting Gujarat-based processors asymmetric leverage over European and North American pet food manufacturers seeking EU REACH-compliant and FDA-recognized grades. This geographic chokepoint amplifies pricing power during monsoon-deficient harvest cycles when Cassia tora seed availability tightens and procurement competition intensifies among multinational ingredient houses.
Pricing Analysis
Enzyme-treated purification technology commands a 15-20% premium over solvent-extracted grades, while chromatographically purified extracts for EFSA anthraquinone compliance sit at the top tier. Three-tier pricing structure across premium enzyme-treated, standard solvent-extracted, and economy crude powder grades reflects certification burden and viscosity standardization investment. Cost compression in the economy tier is intensifying as merchant processors in Gujarat expand capacity without purification upgrades. Mid-sized European pet food co-manufacturers exhibit highest price sensitivity due to thin formulation margins, while multinational brands prioritize specification stability over unit cost.
Supply Chain Analysis
Extended payment terms of 90-120 days from European pet food multinationals strain working capital at Ahmedabad-based merchant processors, driving supply-chain finance facility adoption through Indian banking networks. Raw material sourcing draws from Rajasthan and Gujarat cultivation belts, with seed cleaning and dehulling equipment concentrated around Rajkot industrial zones. Single-source vulnerability to regional logistics disruptions represents the dominant structural risk, as monsoon flooding or interstate transport strikes can sever export flows. Distribution runs through direct procurement relationships displacing traditional Amsterdam and Hamburg trading houses, with Rotterdam consolidation hubs serving redistribution to German and Dutch processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where direct digital procurement platforms are disintermediating traditional trading intermediaries, with interoperability between Indian FSSAI-certified laboratories and European pet food quality systems determining supplier inclusion in qualified vendor lists.
For Market Incumbents: Pre-empt merchant processor consolidation by acquiring chromatographic purification capabilities in Gujarat before EFSA anthraquinone thresholds tighten, as regulatory compliance investment represents the primary lever to exclude undercapitalized competitors. Defend position against emerging enzyme-technology licensors by locking long-term offtake contracts with Rajasthan seed aggregators, securing raw material priority access during deficit harvest cycles. For New Entrants and Emerging Players: Mid-market Dutch and German pet food co-manufacturers represent the most penetrable entry point, as these buyers seek direct supplier accountability without multinational ingredient house markups. Enzymatic purification technology licensing from Ahmedabad research institutes offers a capital-light go-to-market angle, enabling specification-grade production without full facility buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with backward control over seed sourcing and forward certification to EU REACH standards. Long-term viability hinges on regulatory pathway expansion toward human food-grade clearance, with EFSA safety evaluation progression serving as the critical inflection signal to monitor for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Purification Technology Licensing | Enables merchant processors to meet EFSA anthraquinone thresholds without full chromatographic facility investment. |
| Backward Integration into Seed Aggregation | Captures margin compression risk from Rajasthan monsoon volatility and secures priority raw material access. |
| Direct Export Desk Establishment | Bypasses Amsterdam and Hamburg trading house margins by connecting Gujarat facilities to European co-manufacturers. |
| FSSAI-EU REACH Dual Certification Investment | Qualifies processors for multinational pet food brand procurement lists requiring parallel documentation systems. |
| Plant-Based Protein Application Development | Opens adjacent demand from German and Dutch textured vegetable protein manufacturers piloting cassia gum substitution. |
Methodological Framework
Initial hypotheses were tested against primary input from extraction facility operators in Gujarat, pet food formulation scientists at European multinationals, regulatory affairs specialists navigating EFSA evaluations, and procurement directors at Dutch co-manufacturers, then refined against secondary validation from ECHA REACH registration databases, FSSAI food-grade specification documents, FDA 21 CFR pet food additive filings, and Indian customs export statistics. Bottom-up capacity assessments across Ahmedabad and Rajkot processing clusters were triangulated with top-down demand estimates from European pet food production data.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning purification technology tier, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections incorporating seed yield variability and substitution dynamics from locust bean gum. Industry-specific forecast inputs included EFSA evaluation timelines for extended pet food applications and PLI scheme infrastructure subsidy uptake rates among mid-cap processors.
Macroeconomic conditions sit as an overlay; deviation in Indian rupee-euro exchange rates, European energy costs affecting pet food production, or Rajasthan monsoon patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance pathways and technology adoption curves, with macroeconomic, regulatory, or technological deviation prompting revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Canada Anti-Caking Market
Additives
Wax Additives Market
Additives
Potassium Nitrate Market
Additives
Lead Stearate Market
Additives
Friction Modifier Additives Market
Additives
Caprylyl Glycol Market
Additives
Drilling Fluid Additives Market
Additives
Phthalate Plasticizer Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Impact Modifier Market
Additives
Global Packaging Additives Market
Additives
Nucleating and Clarifying Agents Market
Additives
Emulsifiers In Personal Care Market
Additives
Oxygen Scavengers Market
Additives
China Citric Acid Market