
 Middle East Lubricant Additives Market | 2026-2036
Middle East Lubricant Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Lubricant Additives Market Foresight
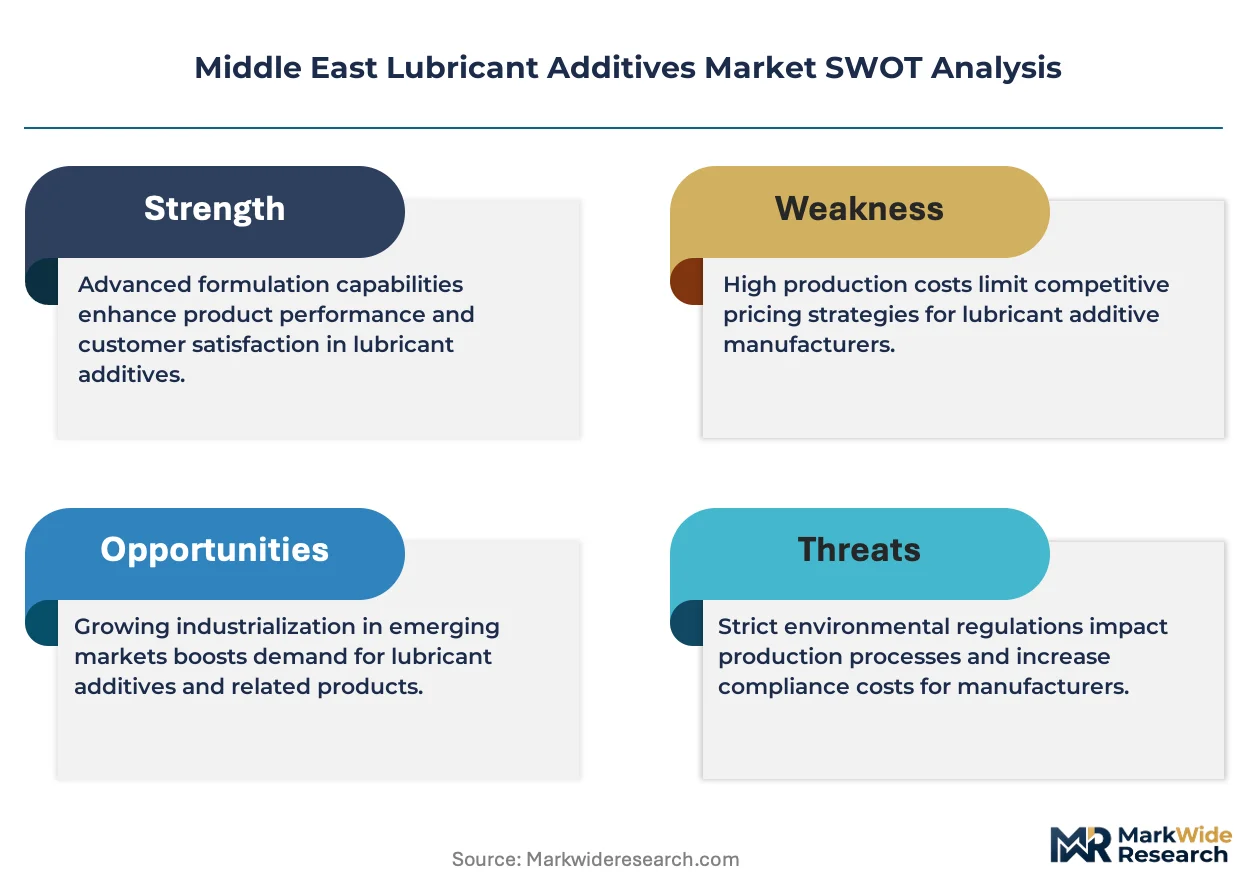
API SP and ILSAC GF-6 qualification cycles is bifurcating the competitive landscape into formulators with full passenger car licensure and those serving only commercial and industrial accounts. Lubrizol leverages its integrated additive chemistry platform to supply both certified automotive packages and specialized industrial formulations across Gulf Cooperation Council states. Afton Chemical Corp. anchors its regional position through backward integration into dispersant manufacturing and direct technical service teams stationed in Dubai and Dammam. BASF SE competes on antioxidant and corrosion inhibitor specialization, particularly for high-temperature Middle Eastern operating conditions where thermal degradation accelerates oil oxidation.
Lubricant additives constitute functional chemical compounds blended into base oils at concentrations typically ranging from five to twenty-five percent by weight to enhance viscosity stability, detergency, oxidation resistance, and wear protection across extreme temperature and load regimes. These formulations enable extended drain intervals, fuel economy gains, and equipment longevity in combustion engines, transmissions, and hydraulic systems operating under severe service conditions. Viscosity modifiers command the largest product-type value pool because multigrade engine oils dominate both automotive and heavy-duty segments throughout the Gulf's hot-climate operating environment. Synthetic source additives are expanding fastest as national oil companies and independent blenders pursue longer service intervals and lower volatility specifications for export-grade finished lubricants. Engine oils application segment retains the deepest margin pool due to OEM certification requirements and the technical complexity of balancing emissions compatibility with deposit control.
SFDA and national petroleum regulators across Gulf Cooperation Council member states enforce additive registration and finished lubricant labeling standards that shape product approval timelines and import documentation burdens for foreign suppliers. REACH-aligned substance notification requirements from European headquarters increasingly influence regional formulation choices as major suppliers operate through EU-registered parent entities. OEM factory-fill approvals from Caterpillar, Mercedes-Benz, and Volvo serve as de facto market access filters for commercial segment suppliers. Stakeholders must monitor the divergence between API's North American certification timeline and Gulf-specific specification adoptions, as lagging local standard updates create formulation portfolio complexity for suppliers serving both export and domestic blenders.
Market Dynamics
Saudi Arabia's national petroleum regulator is tightening specifications for high-sulfur fuel compatibility, forcing formulators to accelerate detergent dispersant package upgrades across the Gulf Cooperation Council.
Growth Catalysts
- Extended drain interval mandates:Heavy-duty engine fleets across Saudi Arabia and the UAE are expanding additive purchases as OEM specifications lengthen service cycles.
- SFDA registration frameworks:Gulf Cooperation Council additive registration standards are consolidating quality tiers, advantaging suppliers with pre-approved formulation libraries.
- Synthetic base oil conversion:National oil companies and independent blenders are pursuing lower volatility specifications for export-grade finished lubricants.
Market Restraints
- API SP qualification costs:Passenger car motor oil certification cycles demand capital-intensive engine test sequences that exclude smaller regional blenders.
- Dispersant supply concentration:Backward-integrated manufacturers control critical detergent chemistry, creating procurement bottlenecks for non-integrated formulators.
- High-temperature thermal degradation:Antioxidant loadings must increase substantially for Middle Eastern operating conditions, raising formulation cost baselines.
Strategic Opportunities
- UAE industrial corridor expansion:Dubai and Abu Dhabi power generation and mining operations are consuming premium hydraulic and gear oil formulations at accelerating rates.
- ILSAC GF-6 specification lag:The gap between North American certification timelines and Gulf-specific adoptions creates formulation portfolio complexity that agile suppliers can exploit.
- Direct technical service deployment:On-site formulator presence in Dammam and Dubai is displacing distributor-dependent support models for commercial accounts.
Industry Challenges
- OEM factory-fill approval timelines:Caterpillar, Mercedes-Benz, and Volvo certification cycles stretch 18-24 months, freezing supplier selection decisions.
- REACH-aligned substance notification:European headquarters registration requirements are forcing reformulation of corrosion inhibitor packages for regional export compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Lubricant Additives Market |
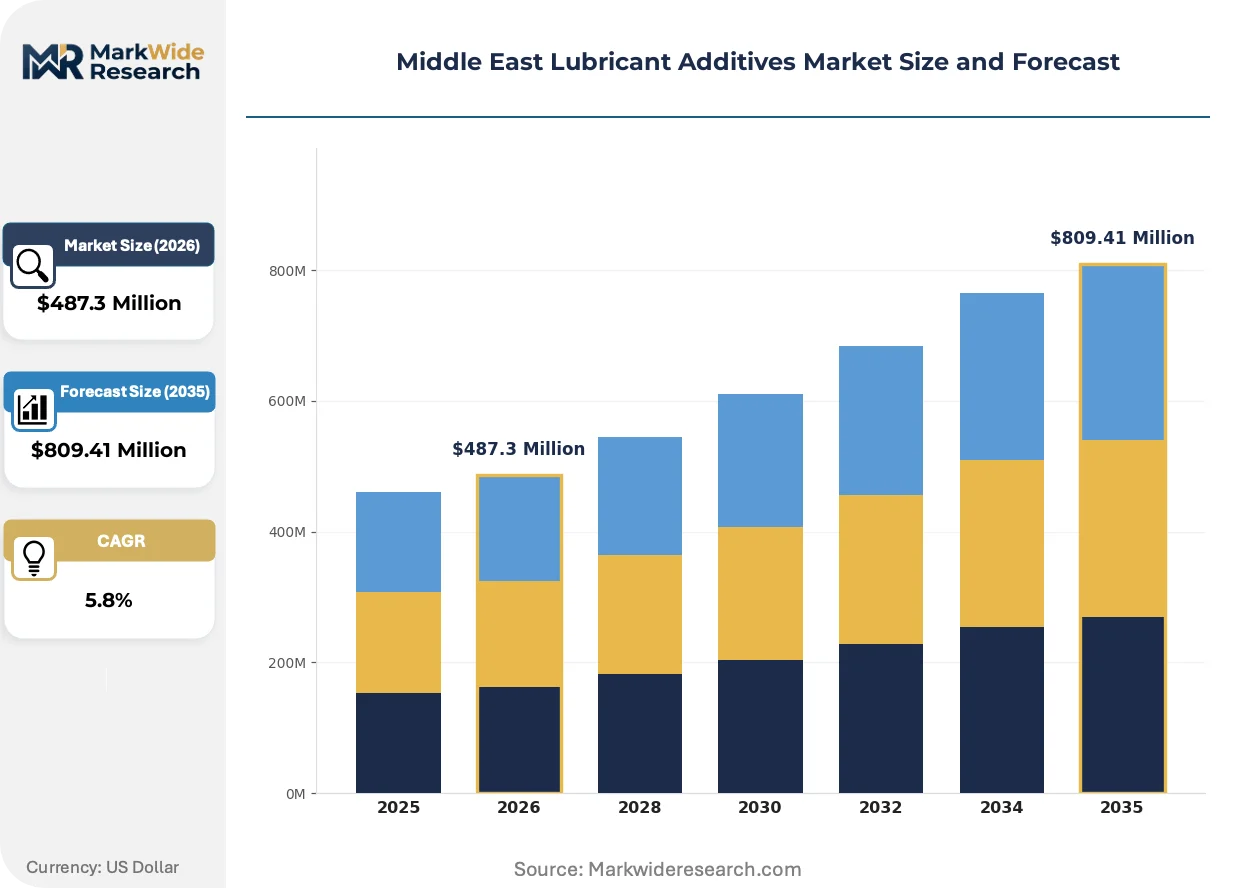
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscosity Modifiers, Detergent Dispersants, Antioxidants, Corrosion Inhibitors End User: Automotive, Industrial, Marine, Heavy-Duty Engines Source: Synthetic, Bio-based, Mineral, Semi-synthetic Application: Engine Oils, Metalworking Fluids, Gear Oils, Hydraulic Fluids |
| Companies Covered | Lubrizol, Afton Chemical Corp., BASF SE, Chevron Oronite Company LLC, Evonik Industries AG, LANXESS, Infineum International, Croda International PLC, Dorf Ketal Chemicals India Pvt. Ltd., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Lubricant Additives Market Shifts & Advancements
Multigrade engine oil specifications are driving chemistry investments across the Gulf's hot-climate operating environment, with synthetic additive packages and direct technical service models restructuring competitive positioning.
Polymer-containing viscosity modifiers are supplanting conventional monograde formulations in heavy-duty and passenger car segments alike. Fleet operators in Saudi Arabia's industrial corridor are adopting these packages to meet extended drain specifications. The shift is compressing demand for single-grade base stocks while expanding value capture for integrated additive-chemistry platforms.
SFDA and Gulf Cooperation Council petroleum regulators are enforcing additive registration and finished lubricant labeling standards that extend product approval timelines. These documentation burdens are reshaping import strategies for foreign suppliers. Commercial segment formulators are responding by pre-positioning certified packages in Jebel Ali and Dammam bonded warehouses.
Direct technical service teams are displacing distributor-mediated support relationships for large commercial accounts. Mining and power generation operators in the UAE now expect on-site formulation troubleshooting and used oil analysis. This service unbundling is most visible in Dubai and Abu Dhabi, where equipment density justifies dedicated chemist deployment.
Middle East Lubricant Additives Market Segmentation
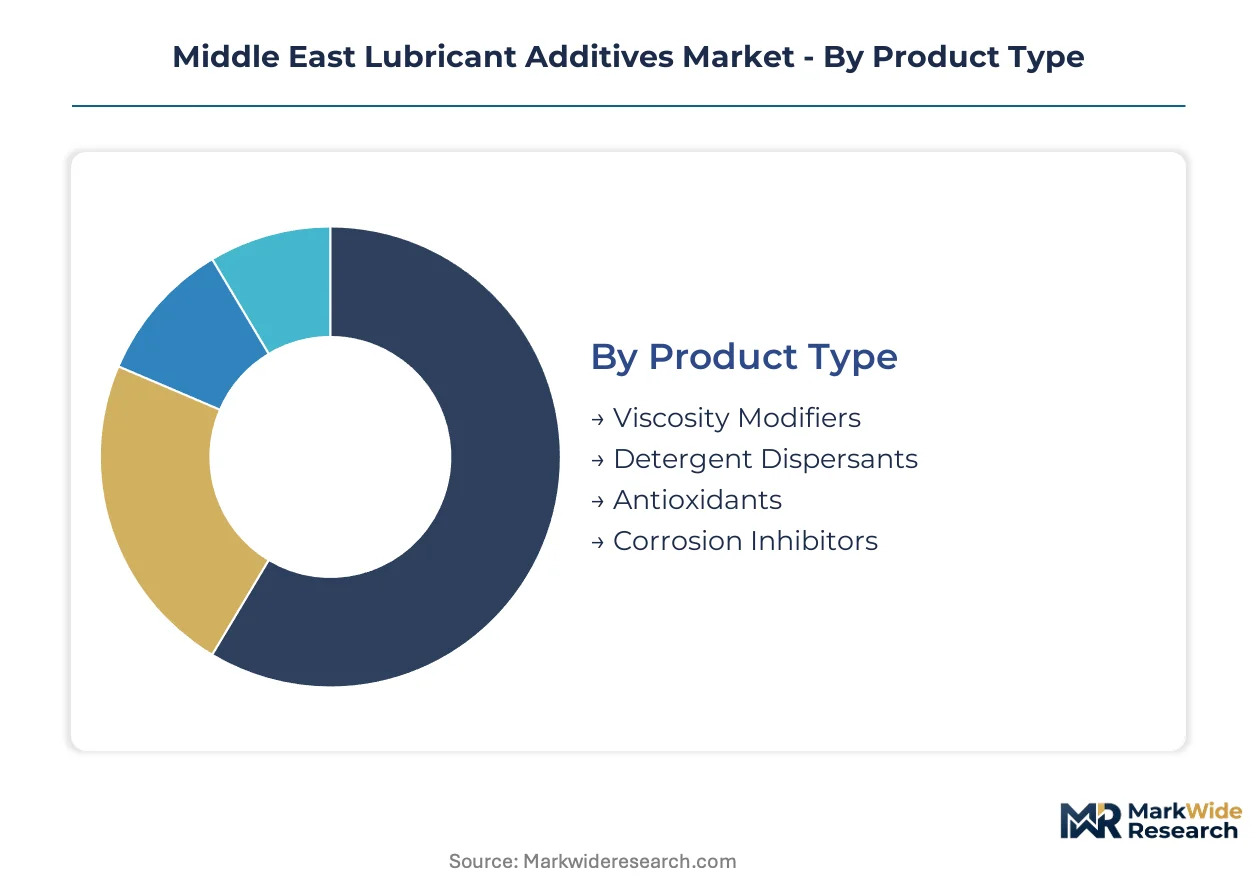
Segmentation in the Middle East lubricant additives market reveals how regulatory pressure and operating environment specificity reshape procurement priorities. Formulators must align product portfolios with divergent certification requirements across automotive OEM approvals and industrial equipment mandates.
Product Type:
SFDA registration frameworks treat viscosity modifiers and detergent dispersants as distinct quality tiers, with pre-approved formulation libraries accelerating market access for integrated suppliers.
- Viscosity Modifiers:Polymer-containing formulations enable multigrade engine oils to maintain performance across the Gulf's extreme temperature swings. Demand concentrates in Saudi Arabia's heavy-duty fleet sector, where extended drain specifications now mandate synthetic viscosity index improvers.
- Detergent Dispersants:Ashless and metallic detergent packages neutralize combustion byproducts and suspend particulates in high-sulfur fuel environments. Procurement bottlenecks favor backward-integrated manufacturers with captive dispersant production, particularly for Caterpillar and Mercedes-Benz factory-fill approvals.
- Antioxidants:Hindered phenol and amine-based oxidation inhibitors address accelerated thermal degradation in Middle Eastern operating conditions. Loadings must increase substantially versus temperate climate formulations.
- Corrosion Inhibitors:Sulfonate and carboxylate chemistry protects ferrous and non-ferrous surfaces from humidity-induced rust in coastal UAE and Saudi Arabian installations.
Established volume favors Viscosity Modifiers; emerging adoption favors Detergent Dispersants.
End User:
Customer procurement scale determines technical service intensity, with mining and power generation operators demanding on-site chemist deployment that distributor models cannot match.
- Automotive:Passenger car motor oil specifications require API SP and ILSAC GF-6 qualification cycles that exclude smaller regional blenders. The segment concentrates in UAE retail channels and Saudi Arabian dealership networks.
- Heavy-Duty Engines:Extended drain interval mandates from Volvo and Mercedes-Benz commercial divisions are expanding additive purchases across Saudi Arabia and UAE fleet operations. Direct technical service teams in Dammam and Dubai anchor supplier relationships.
- Industrial:Hydraulic and gear oil formulations serve manufacturing and processing facilities throughout the Gulf Cooperation Council. Demand is climbing fastest in Dubai's industrial corridor expansion.
- Marine:Cylinder and crankcase lubricants for bunkering operations and port logistics face high-sulfur fuel compatibility requirements under tightening national petroleum regulator specifications.
Heavy-Duty Engines command the deepest service investment; Industrial applications are gaining share fastest.
Source:
Base oil volatility specifications for export-grade finished lubricants are restructuring procurement toward lower-VOC additive packages.
- Synthetic:Polyalphaolefin and ester-derived additives deliver thermal stability and extended service intervals. National oil companies and independent blenders in the UAE and Saudi Arabia are converting formulation portfolios.
- Semi-synthetic:Blended base stocks balance cost and performance for mid-tier commercial applications across the Gulf Cooperation Council.
- Mineral:Conventional petroleum-derived additives retain position in price-sensitive industrial segments and legacy equipment fleets.
- Bio-based:Vegetable oil and synthetic ester chemistry from renewable feedstocks addresses emerging sustainability procurement criteria in select UAE and Saudi Arabian accounts.
Synthetic sources dominate new formulation development; Semi-synthetic maintains volume leadership in commercial blending.
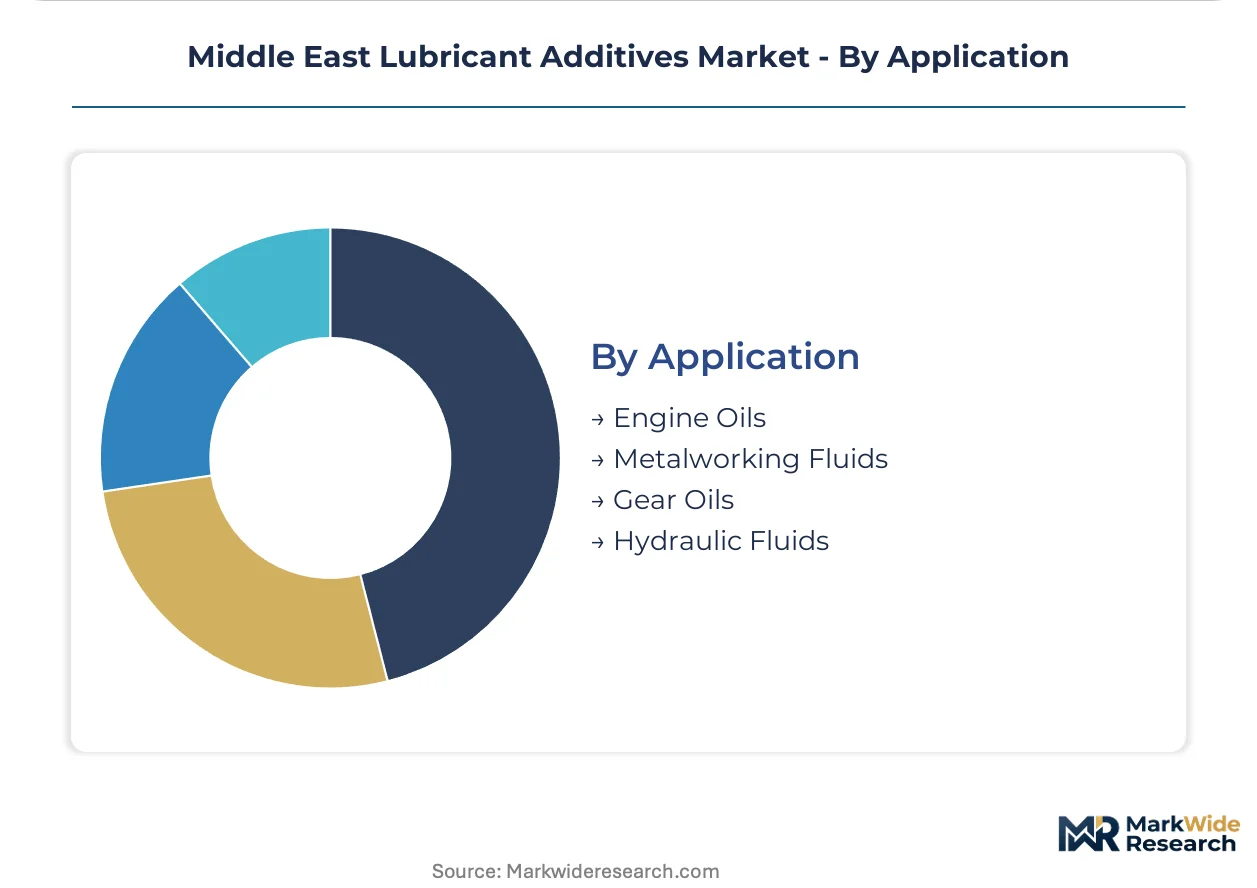
Application:
OEM certification complexity stratifies margin capture, with engine oils requiring the most extensive testing sequences and documentation.
- Engine Oils:Passenger car and heavy-duty formulations must balance emissions compatibility with deposit control across API and ACEA specifications. The segment retains the deepest margin pool due to factory-fill approval requirements.
- Hydraulic Fluids:Anti-wear and oxidation-stable packages serve construction, mining, and material handling equipment in Saudi Arabia's industrial corridor and UAE infrastructure projects.
- Gear Oils:Extreme pressure and limited-slip additives protect differentials and transmissions in high-load commercial vehicle and industrial gearbox applications.
- Metalworking Fluids:Cutting, grinding, and forming lubricants with biocide and corrosion inhibitor packages support manufacturing operations, particularly in Dubai and Abu Dhabi industrial zones.
Engine Oils absorb the largest certification investment; Hydraulic Fluids are expanding most quickly in mining and power generation accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement patterns across the Middle East lubricant additives market cluster around heavy-duty fleet operators and national oil company blenders seeking extended drain specifications. Industrial buyers in Saudi Arabia and the UAE command disproportionate volume share, while regulatory divergence between Gulf Cooperation Council states fragments formulation requirements.
Saudi Arabia
The Eastern Province industrial corridor consumes premium hydraulic and gear oil formulations for power generation and mining operations. The national petroleum regulator is tightening specifications for high-sulfur fuel compatibility, forcing additive package upgrades. Dammam-based blenders are pre-positioning certified formulations in bonded warehouses to accelerate SFDA registration timelines.
United Arab Emirates
Dubai and Abu Dhabi power generation operators are expanding purchases of synthetic additive packages for extended service intervals. MOHAP petroleum standards are consolidating with Gulf Cooperation Council labeling requirements, extending product approval documentation. Jebel Ali free zone concentration enables direct technical service deployment for mining and construction accounts.
Qatar
LNG infrastructure and marine bunkering operations in Ras Laffan Industrial City are driving cylinder lubricant demand for high-sulfur fuel compatibility. The national energy regulator is aligning with tightened Gulf Cooperation Council petroleum specifications. Industrial blenders in Doha are converting portfolios toward lower volatility additive packages for export-grade finished lubricants.
Kuwait
Refinery-linked blending operations in Al-Ahmadi are prioritizing antioxidant loadings for thermal degradation resistance in desert operating conditions. The national oil company is pursuing synthetic base oil conversion for export-grade lubricant production. Mina Al-Ahmadi port logistics are restructuring import strategies around pre-approved SFDA formulation libraries.
Oman
Mining and marine logistics operators in Sohar and Salalah are expanding consumption of extreme pressure gear oil additives. The national petroleum regulator is adopting Gulf Cooperation Council registration frameworks with lagging timelines versus Saudi and UAE implementations. Duqm Special Economic Zone industrial projects are attracting direct technical service deployment from regional formulators.
Middle East Lubricant Additives Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive additive chemistry platforms and specialized formulators with regional technical service presence. Market structure concentrates around suppliers with backward integration into dispersant manufacturing and those with direct Gulf Cooperation Council registration capabilities. Two strategic archetypes dominate: integrated multinationals supplying certified automotive and industrial packages, and regional specialists anchoring commercial accounts through on-site technical support. Competitive moves center on bonded warehouse pre-positioning in Jebel Ali and Dammam, and direct chemist deployment displacing distributor-mediated relationships.
Within the integrated multinational tier, Lubrizol Corporation and BASF SE exemplify suppliers with full passenger car licensure and specialized industrial formulation capabilities across Gulf Cooperation Council states. Afton Chemical Corp. occupies a position representing backward-integrated manufacturers with captive dispersant production and direct technical service teams stationed in Dubai and Dammam. These three companies anchor the competitive landscape by combining OEM certification depth with regional service infrastructure.
| Leading Market Players |
|---|
| Lubrizol |
| Afton Chemical Corp. |
| BASF SE |
| Chevron Oronite Company LLC |
| Evonik Industries AG |
| LANXESS |
| Infineum International |
| Croda International PLC |
| Dorf Ketal Chemicals India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Synthetic additive packages displacing mineral-based formulations are redrawing procurement geography across the Gulf Cooperation Council while compressing margin structures for non-integrated blenders. This substitution dynamic concentrates purchasing power with national oil companies and export-oriented blenders in Saudi Arabia and the UAE who command volume-based pricing leverage.
Pricing Analysis
Cost-plus contracts indexed to ethylene and propylene derivative benchmarks dominate additive procurement between integrated suppliers and national oil company blenders. Three-tier pricing structure across premium, standard, and economy levels separates API-licensed automotive packages from industrial formulations and unlicensed commodity blends. Pricing pressure stems from SFDA registration cost absorption requirements that foreign suppliers must embed in landed pricing. Fleet operators in Saudi Arabia's heavy-duty segment exhibit highest price sensitivity, while OEM factory-fill approvals command premium tolerance from lubricant marketers seeking Mercedes-Benz and Volvo certifications.
Supply Chain Analysis
Strategic stockpiling in Jebel Ali and Dammam bonded warehouses has displaced just-in-time delivery preferences as SFDA documentation timelines stretch product availability. Supply concentrates in the United States, Germany, and Singapore where Lubrizol, Afton, and BASF maintain captive dispersant manufacturing. Raw material dependencies center on polyisobutylene, alkylated phenols, and metallic detergents sourced from petrochemical complexes. Single-source vulnerability pervades ashless dispersant procurement where backward-integrated manufacturers control critical chemistry. Distribution runs through regional blending hubs in Dammam, Jebel Ali, and Doha with direct technical service teams displacing distributor intermediation for commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as API SP and ILSAC GF-6 certification bifurcation creates distinct competitive arenas for automotive and industrial specialists. Divergent Gulf Cooperation Council adoption timelines for passenger car specifications generate niche openings for agile formulators.
For Market Incumbents: Shield market position by deepening captive dispersant production capacity in Dammam and accelerating OEM factory-fill approval cycles for Caterpillar and Volvo commercial divisions. Certification investment represents the priority defensive lever against emerging regional blenders with SFDA pre-approved libraries. Channel control through direct technical service deployment in Dubai's industrial corridor anchors relationships against distributor-dependent competitors.
For New Entrants and Emerging Players: Anchor in Qatar's marine bunkering segment where high-sulfur fuel compatibility specifications are tightening ahead of full Gulf Cooperation Council harmonization. Duqm Special Economic Zone in Oman presents white-space opportunity with lagging regulatory implementation and rising mining equipment density. Go-to-market angle should emphasize rapid SFDA registration through pre-positioned formulation libraries and on-site chemist deployment for power generation accounts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors lacking captive additive chemistry platforms but holding SFDA registration capabilities and bonded warehouse infrastructure. Long-term viability over the mid-decade horizon hinges on backward integration into dispersant manufacturing or acquisition by integrated multinationals seeking Gulf Cooperation Council market access. Watch synthetic base oil conversion announcements from Saudi Aramco and ADNOC as inflection signals for additive demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dispersant Manufacturing | Captive supply of detergent chemistry eliminates procurement bottlenecks for Afton and Lubrizol in Dammam. |
| SFDA Pre-Approved Formulation Libraries | Accelerated registration timelines advantage integrated suppliers against smaller regional blenders in Saudi Arabia. |
| Direct Technical Service Deployment | On-site chemist presence in Dubai and Abu Dhabi displaces distributor models for mining and power generation accounts. |
| Bonded Warehouse Pre-Positioning | Jebel Ali and Dammam inventory buffers documentation delays from Gulf Cooperation Council labeling requirements. |
| Synthetic Additive Package Conversion | Lower volatility specifications align with national oil company export-grade lubricant strategies in UAE and Saudi Arabia. |
Research Methodology
Initial hypotheses were tested against primary input from lubricant formulators, petroleum refinery procurement leads, SFDA regulatory affairs specialists, and heavy-duty fleet maintenance directors and refined through secondary validation. Technical discussions with additive chemistry R&D directors and commercial blending plant managers in Dammam and Jebel Ali anchored supply-side intelligence. Secondary sources encompassed Gulf Cooperation Council petroleum regulator filings, customs trade data for additive imports, SEC 10-K disclosures from listed chemical conglomerates, and OEM factory-fill approval databases. Bottom-up volume builds from end-use segment consumption were triangulated against top-down market sizing from national oil company lubricant production disclosures.
Variance decomposition across product type, end-use application, source chemistry, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including heavy-duty fleet expansion and synthetic base oil conversion timelines. Modeled inputs incorporated SFDA registration pipeline data, OEM drain interval specification changes from Volvo and Mercedes-Benz, and thermal degradation loading requirements specific to Middle Eastern operating conditions.
Material uncertainties — regulatory divergence between Gulf Cooperation Council states, dispersant supply concentration disruptions, and synthetic base oil conversion pace — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline convergence and OEM factory-fill approval continuity that practitioners should keep alternative scenarios live as national petroleum regulator specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Metal Deactivators Market
Additives
Magnesium Stearate Market
Additives
Texture Modifier Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Pectin Market
Additives
Phenolic Antioxidant Market
Additives
Sorbitan Oleate Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Plastic Fillers Market
Additives
Plastic Additives Market
Additives
Global PVC Stabilizer Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Global Mold Release Agents Market
Additives
Printing Ink Additives Market
Additives
Global UV Absorbers Market
Additives
Benzoates Market