
 North America Oral Health Probiotics Market | 2026-2036
North America Oral Health Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oral Health Probiotics Market Analytics
Market Dynamics
Dental clinic procurement of professional-grade oral probiotics is collapsing as direct-to-consumer subscription models capture margin previously locked in practitioner channels. ProBiora Health leverages its dental-origin heritage to sustain credibility with hybrid professional-consumer positioning. HYPERBIOTICS anchors its growth through Amazon-centric distribution control and aggressive strain-specific marketing. Lallemand Health Solutions competes via fermentation technology leadership and private-label manufacturing scale across Canadian and US supplement brands.
Product and Technology Landscape
Oral health probiotics comprise live bacterial strains—predominantly Streptococcus salivarius K12, Lactobacillus reuteri, and Lactobacillus paracasei—delivered in formats designed to colonize the oral microbiome and suppress pathogenic biofilm formation through competitive exclusion and bacteriocin production. Microencapsulation technology dominates manufacturing investment as it protects viability through gastric transit and extends shelf stability without refrigeration dependency. Chewable tablets occupy the largest revenue pool due to adult familiarity and dosing precision, while gummies accelerate fastest among children and compliance-sensitive seniors. Dental clinics represent a concentrated margin segment despite volume concentration in retail channels, driven by professional endorsement premiums and custom strain formulations.
Regulatory Environment and Outlook
The FDA exercises primary oversight through dietary supplement GMPs and New Dietary Ingredient notification requirements, while Health Canada applies Natural Health Product regulations with explicit probiotic strain licensing. State dental boards in Texas and New York increasingly scrutinize practitioner dispensing of non-FDA-approved biotherapeutic products, creating compliance friction for clinic-channel entrants. Stakeholders must monitor whether FDA probiotic-specific guidance emerges to clarify structure-function claim boundaries, as this determination will reshape R&D investment and marketing architecture across the category.
Market Dynamics
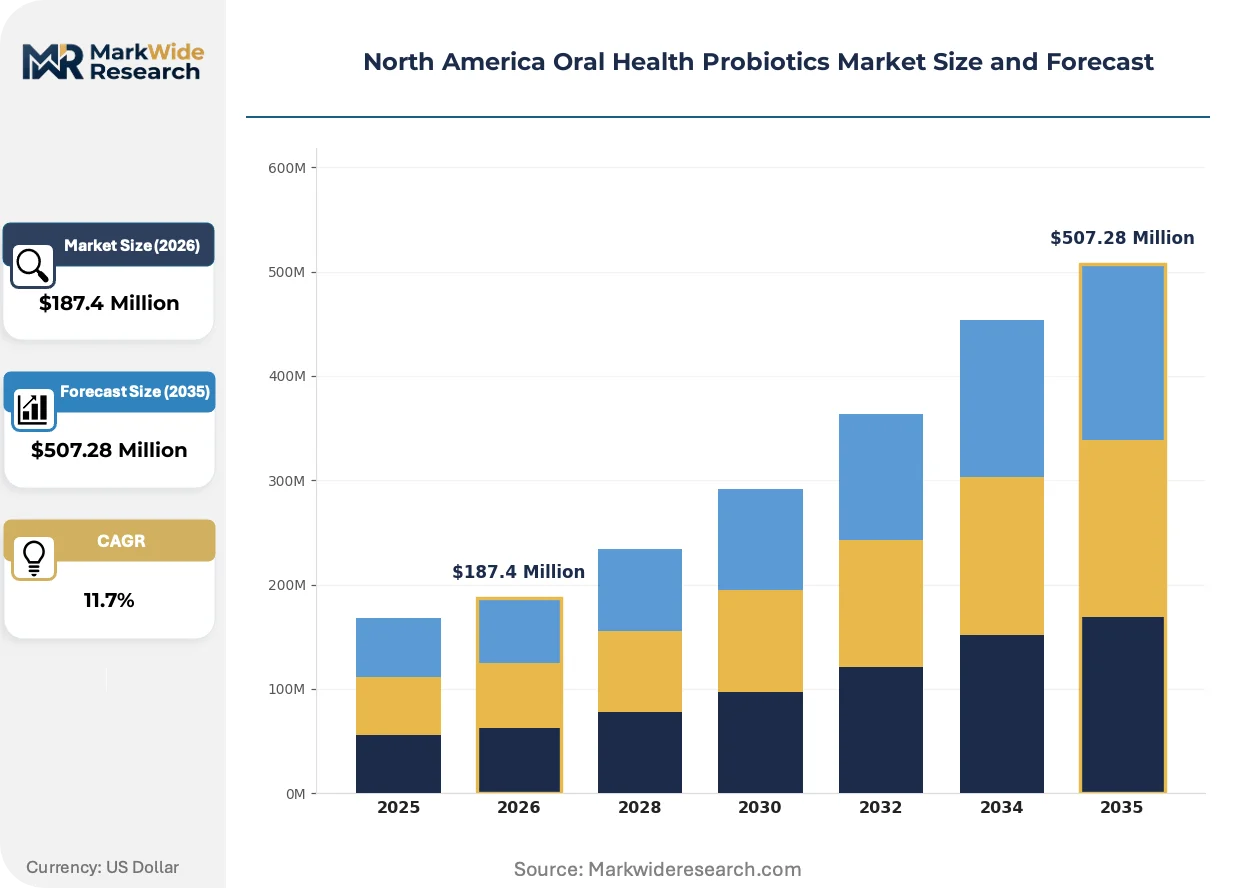
Direct-to-consumer subscription models are collapsing dental clinic procurement channels, capturing margin previously locked in practitioner dispensing while microencapsulation technology investments reshape manufacturing economics across the category.
Growth Catalysts
- Pediatric preventive dentistry:Parents in California's wellness corridors and Toronto's preventive networks seek fluoride alternatives for children, expanding the buyer base beyond traditional adult supplementation.
- FDA structure-function claim pathways:Evolving substantiation standards for probiotic health claims create clearer marketing architecture, reducing regulatory uncertainty for compliant entrants.
- Microencapsulation viability protection:Gastric transit survival technology eliminates cold-chain dependency, unlocking mass retail distribution and extending shelf stability for chewable and gummy formats.
Market Restraints
- State dental board scrutiny:Texas and New York regulators increasingly examine practitioner dispensing of non-FDA-approved biotherapeutics, creating compliance friction for clinic-channel strategies.
- Strain-specific IP concentration:Proprietary Streptococcus salivarius K12 and Lactobacillus reuteri formulations remain concentrated among limited fermentation technology holders, constraining formulation diversity.
- Professional endorsement dependency:Premium pricing in dental channels requires sustained practitioner credibility, which direct-to-consumer brands struggle to replicate without heritage positioning.
Strategic Opportunities
- Senior compliance-sensitive segments:Gummy format adoption among aging populations in Florida and Arizona retirement corridors represents underpenetrated demand for palatable daily dosing.
- Private-label manufacturing scale:Canadian and US supplement brands seek fermentation technology partnerships, creating white-label revenue streams for technology holders.
- Amazon-centric distribution control:Platform-native brands can capture search-driven purchase behavior without traditional retail slotting fee structures or professional channel margin splits.
Industry Challenges
- CFU count standardization:Colony-forming unit measurement variability across laboratories complicates label claim substantiation and competitive positioning.
- Strain viability verification:End-of-shelf-life potency testing requirements demand significant quality control infrastructure investment for emerging entrants.
- Hybrid professional-consumer positioning:Brands attempting dual-channel credibility must navigate conflicting messaging demands between clinical authority and mass-market accessibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oral Health Probiotics Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewable Tablets, Gummies, Powders, Liquids Technology: Fermentation, Microencapsulation, Freeze-Drying, Spray Drying End User: Adults, Children, Seniors, Dental Clinics Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | BioGaia AB, ProBiora Health, HYPERBIOTICS, Lallemand Health Solutions, NOW Foods, OraTicx, Church & Dwight Co., Inc., Jarrow Formulas, Inc., NatureWise, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oral Health Probiotics Market Evolving Landscape
Oral health probiotics are experiencing format innovation acceleration and channel disintermediation that together compress traditional practitioner-dependent business models while elevating platform-native competitors.
Microencapsulation technology is displacing conventional freeze-dried powder formulations as the dominant manufacturing investment. Pediatric dental practices and senior care facilities are adopting viability-protected strains at accelerated pace. This technology is displacing cold-chain infrastructure requirements, enabling pharmacy and convenience retail placement previously inaccessible to live culture products.
Health Canada's Natural Health Product strain licensing framework is tightening probiotic identity verification requirements. Manufacturers must now submit genomic sequencing data for each licensed strain, elevating documentation costs. Canadian and US brands targeting cross-border distribution are responding by consolidating supplier relationships with fermentation partners holding pre-validated strain libraries.
Subscription-based replenishment programs are capturing recurring revenue from compliance-sensitive chronic users, disrupting single-transaction retail purchasing. Dental clinic dispensing networks are losing volume to platform-direct models that offer price transparency and automated delivery. This behavioral shift concentrates most visibly in California's metropolitan wellness corridors and Toronto's integrated preventive dentistry networks.
North America Oral Health Probiotics Market Segmentation
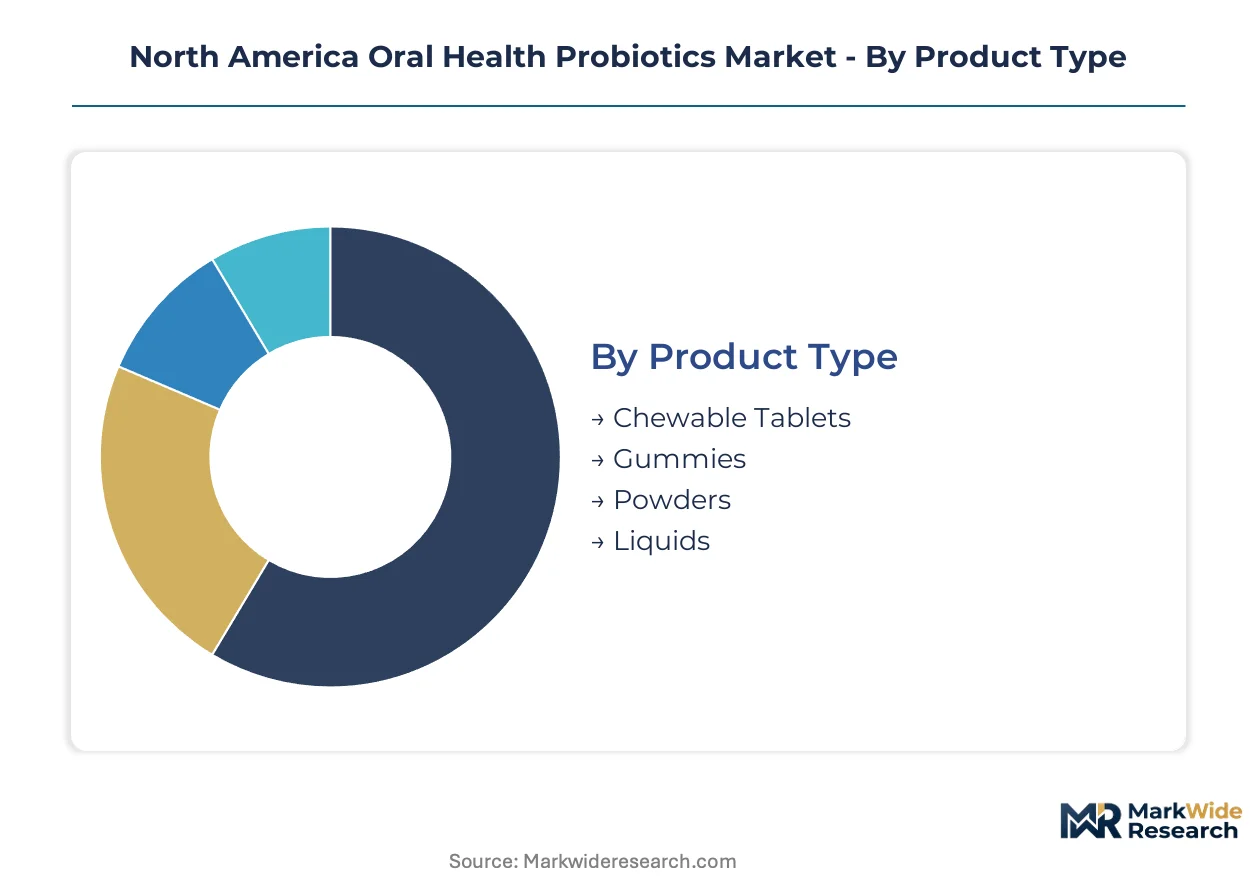
Oral health probiotics demand fragments across delivery formats, manufacturing technologies, and purchasing channels that each carry distinct margin profiles and regulatory requirements. Understanding these segment boundaries reveals where formulation investments concentrate versus where distribution scale dominates competitive positioning.
Product Type:
Chewable tablets and gummies concentrate manufacturing investment in US and Canadian facilities serving domestic retail chains, while powders and liquids flow through cross-border e-commerce channels targeting compliance-sensitive chronic users.
- Chewable Tablets:Compressed probiotic matrices with enteric coatings protect Streptococcus salivarius K12 through gastric transit. Demand concentrates in California wellness corridors and Toronto preventive dentistry networks where adult familiarity with pill formats sustains premium positioning.
- Gummies:Gelatin or pectin-based matrices incorporate flavor masking and moisture barriers to maintain Lactobacillus reuteri viability. Pediatric dental practices in Florida and Arizona retirement communities drive fastest adoption among compliance-sensitive demographics seeking palatable daily dosing.
- Powders:Sachet-dosed freeze-dried cultures target biohackers and practitioner-dispensed regimens requiring flexible titration.
- Liquids:Suspension formats with short shelf lives serve niche functional beverage integrations and clinical trial supply.
Chewable tablets hold the largest share; momentum sits with gummies.
Technology:
Fermentation and microencapsulation command higher capital intensity and captive supplier relationships, while freeze-drying and spray drying operate through more fragmented toll manufacturing networks.
- Fermentation:Controlled bioreactor cultivation of proprietary Lactobacillus paracasei strains requires strain banking infrastructure and genomic validation protocols. Lallemand Health Solutions and select Canadian biotech facilities anchor North American capacity, constraining formulation diversity for brands lacking long-term supplier contracts.
- Microencapsulation:Lipid or alginate shell deposition around live cultures eliminates cold-chain dependency and extends shelf stability. California and Quebec manufacturing investments are displacing conventional freeze-dried formulations as pharmacy and convenience retail placement becomes accessible.
- Freeze-Drying:Lyophilization preserves culture viability for bulk ingredient supply and private-label manufacturing.
- Spray Drying:Cost-efficient dehydration suits mass-market powders with shorter viability windows and lower price positioning.
Fermentation commands the dominant value share; microencapsulation is climbing the fastest.
End User:
Adults and children drive volume through retail and subscription channels, while seniors and dental clinics concentrate in professional-dispensed and Medicare-adjacent procurement pathways.
- Adults:Self-directed preventive supplementation among wellness-focused consumers in metropolitan corridors sustains the revenue base. Amazon-centric subscription models capture recurring purchases from chronic users seeking price transparency and automated replenishment.
- Children:Parents in California and Toronto seek fluoride alternatives, expanding pediatric dental care into a rapidly growing buyer segment. Gummy formats with strain-specific marketing overcome compliance barriers that limit tablet adoption.
- Seniors:Aging populations in Florida and Arizona retirement communities represent underpenetrated demand for palatable dosing formats.
- Dental Clinics:Professional endorsement premiums and custom strain formulations sustain concentrated margin despite volume migration to direct-to-consumer channels.
Adults retain the largest share; children are gaining share fastest.
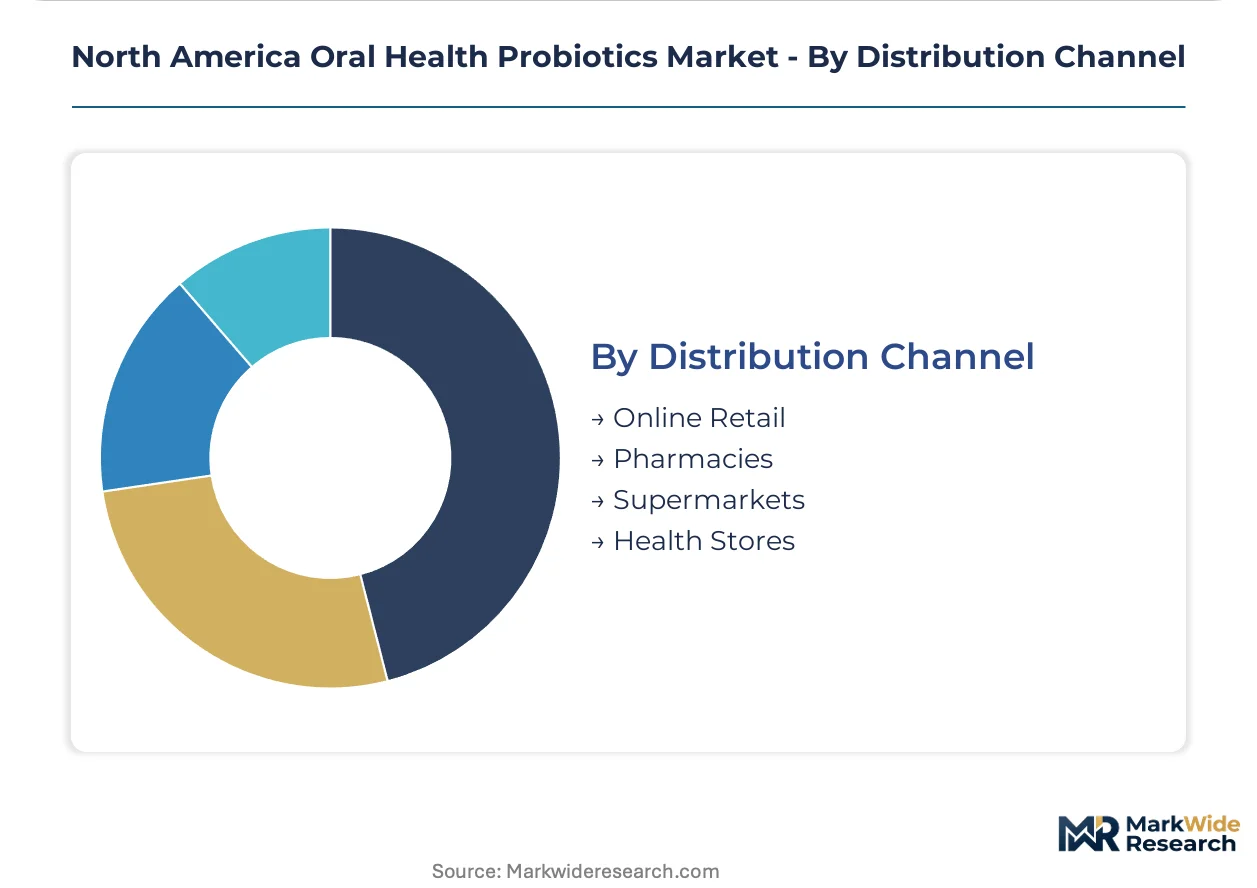
Distribution Channel:
Online retail and health stores concentrate in digitally native purchasing corridors, while pharmacies and supermarkets maintain physical presence in suburban and rural catchment areas.
- Online Retail:Platform-native brands leverage search-driven purchase behavior without traditional retail slotting fees. HYPERBIOTICS anchors growth through Amazon-centric distribution control, capturing margin previously locked in practitioner channels.
- Pharmacies:Chain and independent drugstores provide credibility signaling for first-time probiotic purchasers. Microencapsulation technology enables placement without refrigeration infrastructure, unlocking mass retail accessibility.
- Supermarkets:Grocery channel placement targets impulse and basket-stocking behavior among established supplement users.
- Health Stores:Specialty retailers serve strain-educated consumers seeking practitioner-grade formulations and staff consultation.
Online retail holds the largest share; health stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation technology suppliers and microencapsulation specialists cluster along the US-Canada corridor, with Canadian biotech infrastructure and California manufacturing investments anchoring North American supply capacity.
United States
California's metropolitan wellness corridors and Florida's retirement communities generate concentrated demand for pediatric and senior-targeted formulations. The FDA's evolving structure-function claim guidance reshapes labeling requirements for dietary supplement entrants. Texas state dental boards scrutinize practitioner dispensing of biotherapeutic products, creating compliance friction for clinic-channel strategies in Dallas and Houston markets.
Canada
Toronto's integrated preventive dentistry networks and Quebec's fermentation technology base concentrate procurement and manufacturing activity. Health Canada's Natural Health Product regulations mandate genomic sequencing data for strain licensing, elevating documentation costs for cross-border brands. Lallemand Health Solutions anchors Canadian fermentation capacity, supplying private-label manufacturing for US supplement brands.
Mexico
Mexico City Metro and Nuevo León industrial corridors absorb imported probiotic formulations through pharmacy and e-commerce channels. COFEPRIS oversight of dietary supplements applies less stringent strain verification than Health Canada or FDA frameworks, enabling faster product registration for regional brands. Northern border states facilitate cross-border fulfillment to US Hispanic consumer segments.
North America Oral Health Probiotics Market Competitive Landscape
Concentration sits with fermentation technology holders and platform-native direct-to-consumer brands, while traditional supplement manufacturers compete through retail distribution scale and private-label partnerships. The market structure reflects a bifurcation between clinical-credibility positioning and mass-market accessibility. Three archetypes dominate: dental-origin heritage brands leveraging practitioner endorsement, Amazon-centric subscription operators capturing search-driven purchase behavior, and fermentation technology suppliers controlling strain IP and manufacturing scale. Competitive moves center on hybrid professional-consumer channel strategies and microencapsulation technology licensing to unlock pharmacy placement without cold-chain infrastructure.
Within the dental-origin heritage tier, ProBiora Health occupies a position exemplifying practitioner-credibility translation into consumer markets. HYPERBIOTICS anchors the platform-native archetype through Amazon-centric distribution control. Lallemand Health Solutions represents the fermentation technology supplier category, supplying strain libraries and private-label capacity across North American supplement brands. These three entities collectively illustrate the channel and technology tensions reshaping competitive positioning.
| Leading Market Players |
|---|
| BioGaia AB |
| ProBiora Health |
| HYPERBIOTICS |
| Lallemand Health Solutions |
| NOW Foods |
| OraTicx |
| Church & Dwight Co., Inc. |
| Jarrow Formulas, Inc. |
| NatureWise |
| Others |
Value Network & Pricing Analysis
Health Canada's Natural Health Product strain licensing gates both supply qualification and price differentiation simultaneously, requiring genomic sequencing documentation that elevates fixed costs for market entry while enabling certified suppliers to command formulation premiums over unverified competitors.
Pricing Analysis
FDA dietary supplement GMPs dictate the pricing tier structure across the North American oral health probiotics market. Three-tier pricing structure across premium, standard, and economy levels separates practitioner-dispensed professional formulations from mass-market retail SKUs and private-label economy alternatives. Price differentiation rests on certification grade and brand heritage, with dental-origin positioning sustaining 40-60% premiums over platform-native competitors. Cost compression in the standard tier is intensifying because Amazon-centric subscription operators eliminate traditional retail slotting fees and professional channel margin splits. Dental clinics and wellness-focused metropolitan consumers exhibit lowest price sensitivity, while mass-market tablet purchasers in suburban pharmacy channels demonstrate highest elasticity.
Supply Chain Analysis
Port congestion along the Vancouver-Seattle corridor and container availability constraints on trans-Pacific lanes from Quebec fermentation facilities elevate inbound logistics costs for Canadian-manufactured strains entering US distribution. Geographic supply concentration centers on Canada, California, and select Midwest fermentation hubs, with Lallemand Health Solutions anchoring North American bioreactor capacity. Raw material dependencies include pharmaceutical-grade growth media, alginate and lipid encapsulation compounds, and cold-chain packaging materials. Single-source vulnerability characterizes proprietary Streptococcus salivarius K12 strain banking, where limited fermentation technology holders constrain formulation diversity. Distribution runs through hybrid direct-to-consumer subscription platforms and pharmacy retail networks, displacing traditional dental clinic procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive dynamics as Amazon's search-driven purchase infrastructure and subscription replenishment algorithms disintermediate practitioner-dependent heritage brands, creating ecosystem lock-in effects that favor data-native operators over clinical-credibility incumbents.
For Market Incumbents: Fortify hybrid professional-consumer positioning by deepening captive fermentation partnerships in Quebec and California manufacturing corridors, while investing in microencapsulation technology licensing to unlock pharmacy placement without cold-chain infrastructure. Defend margin architecture against direct-to-consumer subscription entrants by consolidating dental clinic dispensing relationships through exclusive strain formulations and automated replenishment integration. For New Entrants and Emerging Players: Differentiate on pediatric gummy format innovation targeting California wellness corridors and Florida retirement communities, where compliance-sensitive demographics seek palatable alternatives to tablet regimens. White-space concentration sits with senior care facilities and Medicare-adjacent procurement pathways. Platform-native go-to-market deployment through Amazon search optimization and influencer-driven strain education captures recurring revenue without traditional retail slotting investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation manufacturing as pharmacy and convenience retail placement demands viability-protected strain infrastructure. Long-term viability over the next decade favors fermentation technology suppliers with pre-validated genomic libraries and private-label manufacturing scale. Acquisition target archetype: Canadian biotech facilities with Health Canada strain licensing and cross-border US supplement brand relationships. Signal to watch: FDA probiotic-specific guidance emergence clarifying structure-function claim boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables pharmacy placement without refrigeration infrastructure, unlocking mass retail accessibility. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from compliance-sensitive chronic users through Amazon-centric distribution control. |
| Genomic Strain Validation Investment | Satisfies Health Canada licensing requirements and elevates documentation barriers for competitors. |
| Pediatric Gummy Format Extension | Penetrates California wellness corridors and Toronto preventive dentistry networks seeking fluoride alternatives. |
| Fermentation Capacity Expansion | Consolidates supply relationships with US supplement brands seeking private-label manufacturing partnerships. |
Research Methodology
Operator-level perspectives from dental clinic procurement managers, supplement brand product development executives, fermentation facility technical directors, and pharmacy category buyers anchored the qualitative base. Primary interviews combined with secondary validation from FDA dietary supplement enforcement reports, Health Canada Natural Health Product licensing databases, and Amazon marketplace sales analytics. Bottom-up strain volume modeling and top-down category value triangulation cross-verified segment outputs.
Sensitivity analysis framed the analytical approach across the projection horizon, with segmentation dimensions spanning delivery format, manufacturing technology, end-user demographic, and distribution channel. CAGRs derived from probiotic strain adoption curves, microencapsulation technology penetration rates, and channel shift elasticity parameters. Industry-specific inputs included genomic sequencing cost trajectories and state dental board regulatory enforcement intensity indices.
Material uncertainties — FDA probiotic-specific guidance timing, Health Canada strain licensing backlog duration, and platform algorithm changes affecting search-driven purchase behavior — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory stability and consumer subscription retention patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market