
 Poultry Probiotics Market | 2026-2036
Poultry Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Probiotics Market Analytics
Strain-identified CFU potency tiers is unwinding commoditization across the poultry probiotics space. Chr. Hansen leverages its culture collection depth to dominate high-specification layer applications. Novonesis anchors European supply through fermentation scale and regulatory dossier completeness. Kemin Industries differentiates via integrated antioxidant-probiotic premix platforms.
Poultry probiotics comprise defined live microbial cultures, typically quantified at minimum viable counts per gram, administered through feed or water to colonize the avian gastrointestinal tract and modulate immune response, nutrient metabolism, and pathogen exclusion. Lactic Acid Bacteria and Bacillus categories occupy the dominant volume positions, with Bacillus spore formers commanding margin premiums due to thermostability advantages in pelleting. Powder formulations lead current output, though liquid delivery systems for in-water application represent the fastest-expanding format segment among integrated operations.
USDA organic certification requirements and FDA veterinary feed directive enforcement shape product registration pathways and label claims for American suppliers. EFSA strain-specific QPS evaluations and EU feed additive regulation constrain market entry timelines but validate premium positioning for approved isolates. ANVISA veterinary product controls in Brazil and evolving Chinese Ministry of Agriculture GB standards for feed additives add further compliance layers. Stakeholders must weigh dossier investment against strain exclusivity duration when prioritizing development pipelines.
Market Dynamics
Strain-level differentiation is decomposing commodity pricing across poultry probiotics, as ANVISA veterinary oversight in Brazil and EFSA QPS evaluations in Europe force suppliers to invest in dossier completeness rather than undifferentiated CFU claims.
Growth Catalysts
- ANVISA veterinary oversight:Brazilian broiler integrators are expanding probiotic inclusion in starter feeds to reduce antibiotic dependency, creating pull-through demand for thermostable Bacillus formulations.
- FCR optimization protocols:European layer operations are prioritizing strain-specific Bacillus spore formers to improve feed conversion ratios in high-density housing systems.
- Starter feed reformulation:Integrated poultry operations across multiple geographies are embedding probiotics earlier in the production cycle to establish gastrointestinal colonization before pathogen exposure peaks.
Market Restraints
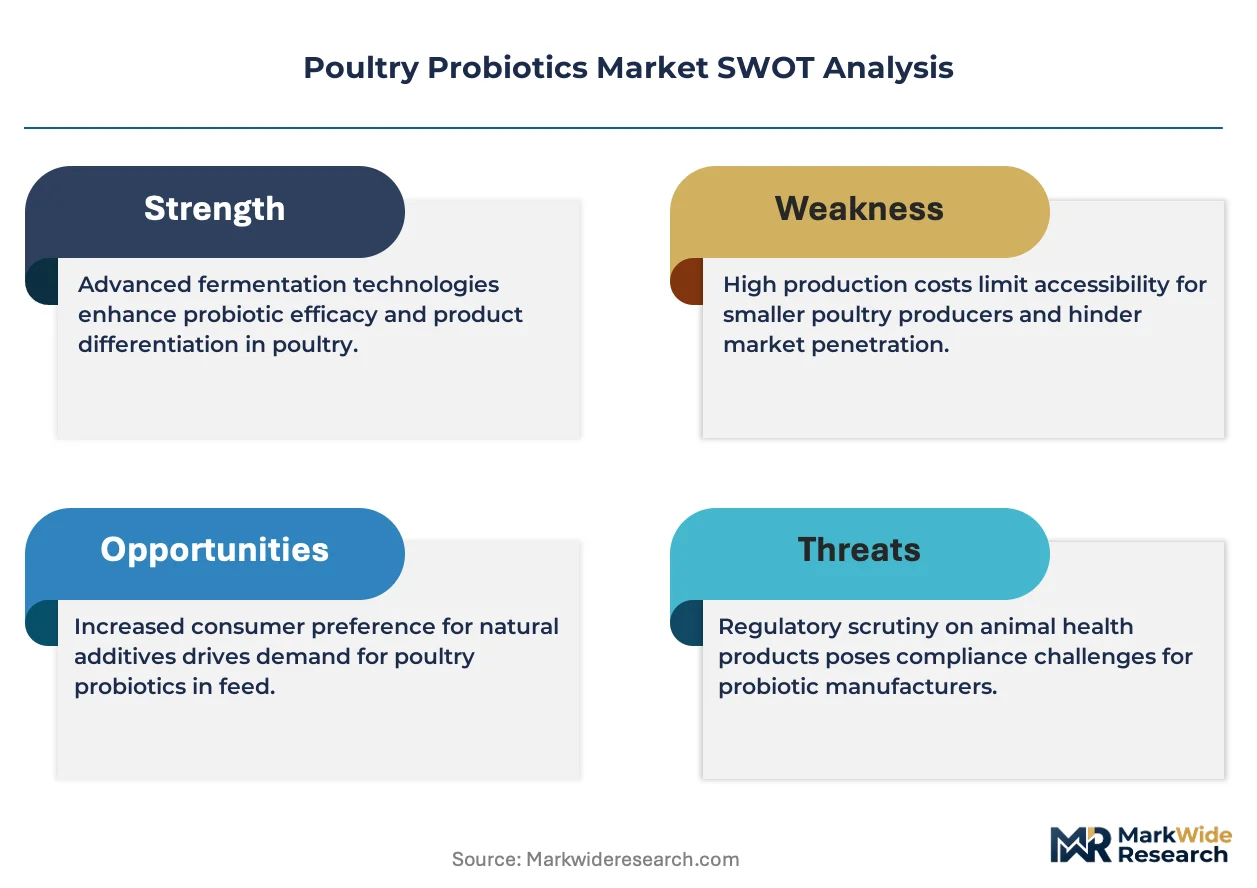
- Fermentation capacity concentration:Large-scale production of defined live microbial cultures remains concentrated among established culture collection holders, limiting new entrant supply security.
- EFSA strain-specific QPS timelines:Novel isolate approval pathways extend market entry timelines by 24-36 months, compressing exclusivity windows for proprietary strains.
- Antibiotic residual pricing:Low-cost therapeutic alternatives in markets with lax veterinary oversight continue to undercut probiotic premium positioning in price-sensitive segments.
Strategic Opportunities
- In-water liquid delivery systems:Fastest-expanding format segment among integrated operations seeking flexible administration timing independent of feed mill schedules.
- USDA organic certification pathway:Premium positioning for approved isolates meeting National Organic Program standards creates defensible margin tiers in contract poultry production.
- Antioxidant-probiotic premix convergence:Integration of oxidative stress management with microbiome modulation addresses dual physiological stressors in heat-challenged environments.
Industry Challenges
- Strain banking expertise scarcity:Qualified microbiologists capable of maintaining axenic culture collections and viability optimization through freeze-drying protocols command premium compensation.
- Pelleting thermotolerance validation:Bacillus spore formers require rigorous batch testing to confirm CFU survival through feed manufacturing temperatures exceeding 85°C.
- Cross-border dossier harmonization:Divergent regulatory requirements between FDA veterinary feed directive enforcement and EU feed additive regulation complicate multi-territory product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Probiotics Market |
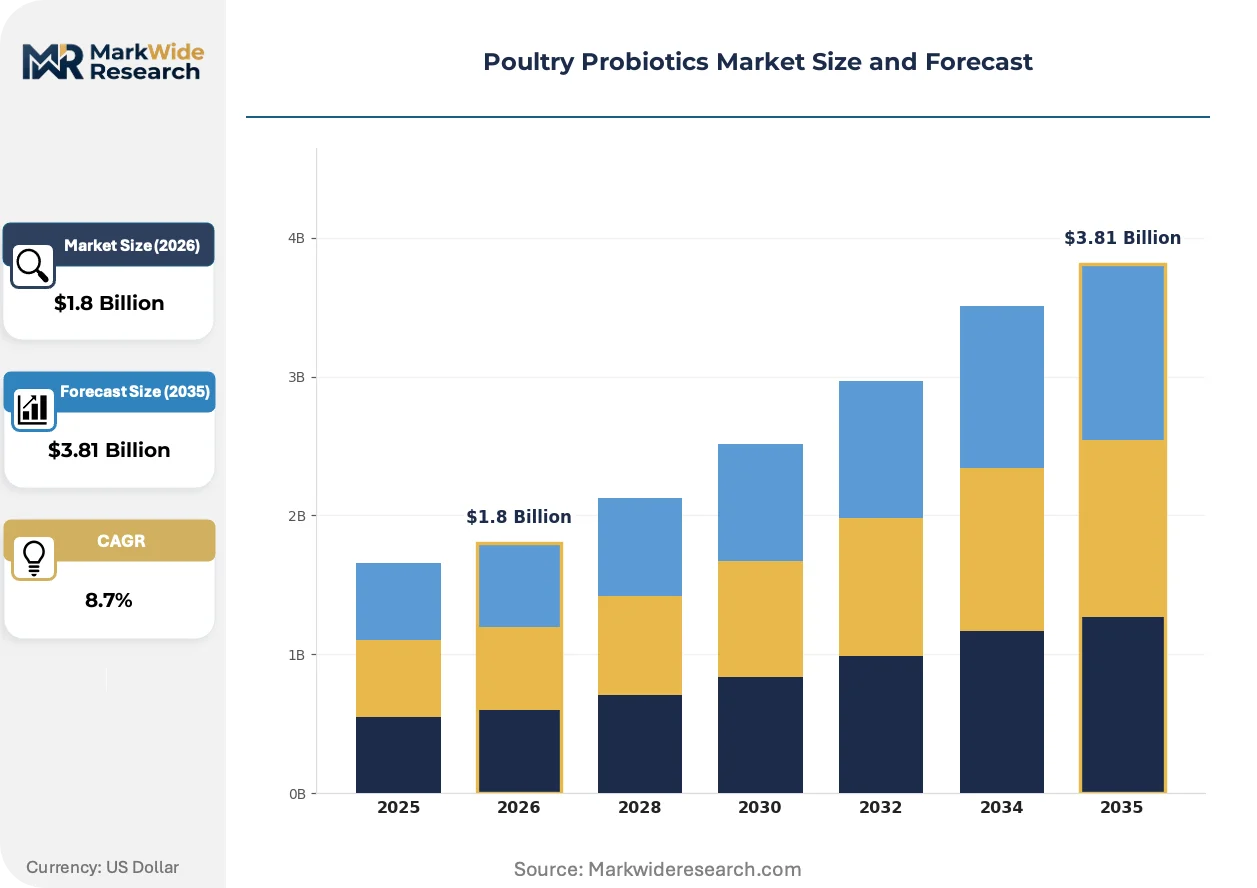
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactic Acid Bacteria, Bacillus, Yeast, Enterococcus End User: Poultry Farms, Feed Manufacturers, Veterinary Clinics, Research Institutions Application: Growth Promotion, Disease Prevention, Nutrient Absorption, Stress Reduction Form: Powder, Liquid, Granule, Pellet |
| Companies Covered | Chr. Hansen, DSM-Firmenich, Evonik Industries, Novonesis, Lallemand, Kemin Industries, Novus International, International Flavors & Fragrances, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Probiotics Market Evolving Landscape
Multi-omics characterization of avian gut microbiomes is redirecting R&D investment toward functionally annotated isolates rather than generic lactic acid bacteria blends, compressing development timelines for targeted pathogen exclusion claims.
Next-generation sequencing is decomposing the traditional "more CFU is better" formulation paradigm. Layer operations in Denmark and the Netherlands are adopting strain-typed cocktails with defined metabolic pathway annotations. This precision approach is compressing commodity premix margins while expanding premium tiers for functionally validated isolates.
EFSA's updated QPS evaluation framework is accelerating dossier requirements for novel Bacillus subtilis and B. licheniformis isolates. Feed additive manufacturers must now submit whole-genome safety assessments before market authorization. Layer operations in France and Germany are responding by consolidating supplier relationships with culture collection holders possessing deep regulatory archives.
Buying committees at integrated broiler operations are unbundling probiotic procurement from legacy feed supplier contracts. Direct sourcing relationships with fermentation specialists are displacing trader-mediated distribution in Brazil and Thailand. This disintermediation is most visible among top-ten global poultry processors seeking supply security for multi-site operations.
Poultry Probiotics Market Segmentation
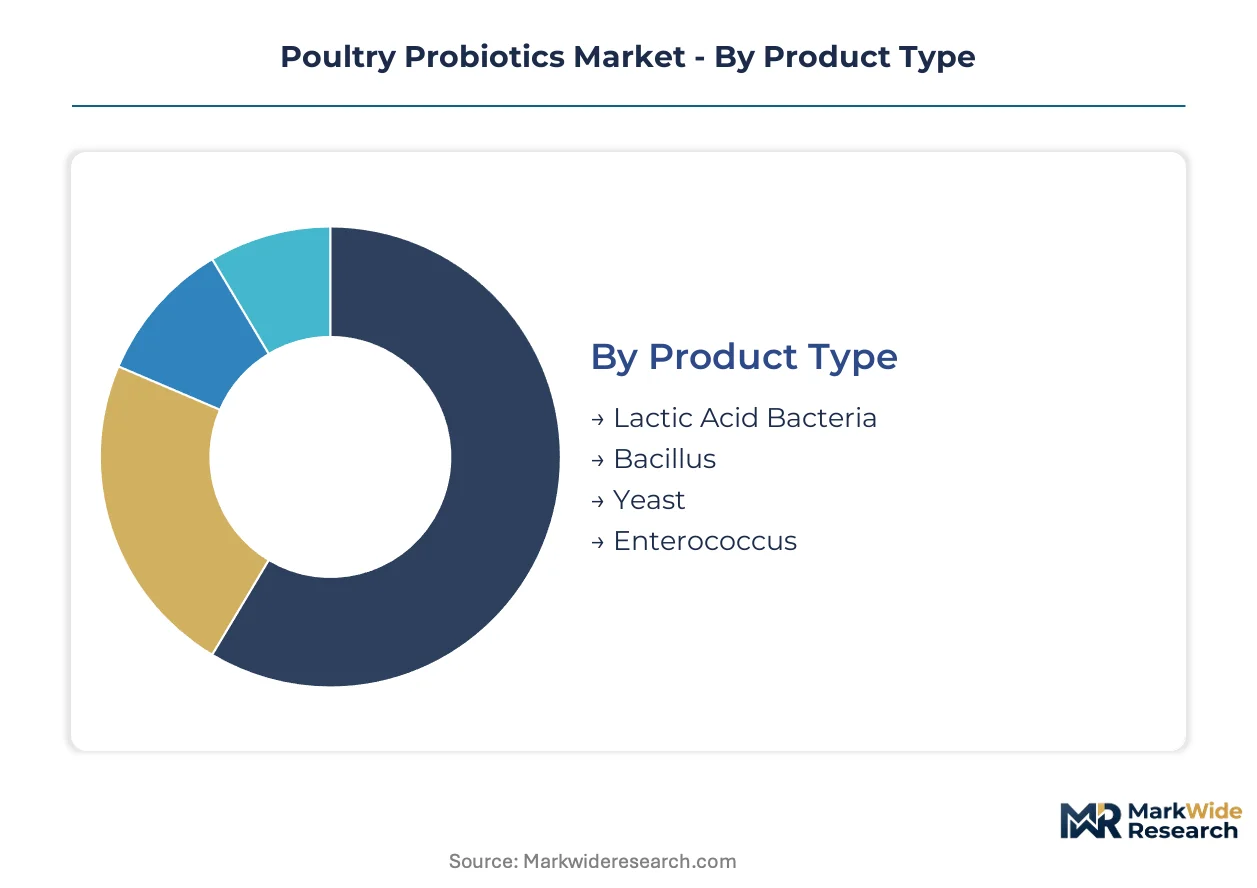
Strain-specific Bacillus spore formers command margin premiums due to thermostability advantages, while liquid delivery formats are reshaping procurement patterns among integrated operations. Segmentation reveals where dossier investment and fermentation scale translate into sustainable competitive position.
Product Type:
Margin pools concentrate in thermotolerant spore formers that survive pelleting temperatures above 85°C, with Bacillus categories capturing premium positioning over vegetative cell alternatives.
- Bacillus:Spore-forming isolates of B. subtilis and B. licheniformis deliver validated CFU survival through feed manufacturing thermal stress. European layer operations under EFSA QPS oversight prioritize strain-typed Bacillus for FCR optimization in high-density housing.
- Lactic Acid Bacteria:Defined live cultures including Lactobacillus and Pediococcus species dominate volume positions in starter feed applications. Brazilian broiler integrators expanding probiotic inclusion under ANVISA veterinary oversight drive demand for lactic acid bacteria in early-cycle gastrointestinal colonization.
- Yeast:Saccharomyces cerevisiae and related species provide beta-glucan immunomodulation alongside probiotic colonization benefits.
- Enterococcus:E. faecium isolates occupy niche positions in pathogen exclusion protocols, constrained by regulatory scrutiny in multiple jurisdictions.
The dominant share belongs to Bacillus, while Lactic Acid Bacteria is closing the gap fastest through starter feed reformulation momentum.
End User:
Procurement authority is shifting from legacy feed suppliers toward direct relationships with fermentation specialists, particularly among multi-site integrated operations.
- Feed Manufacturers:Pelleting thermotolerance validation requirements and cross-border dossier harmonization challenges define supplier selection criteria. These stakeholders balance CFU potency claims against batch-to-batch viability consistency through 85°C+ manufacturing conditions.
- Poultry Farms:Direct sourcing relationships with culture collection holders are displacing trader-mediated distribution in Brazil and Thailand. Top-ten global poultry processors seek supply security independent of feed mill schedules.
- Veterinary Clinics:In-water liquid delivery administration for targeted therapeutic intervention during stress events or disease challenge.
- Research Institutions:Multi-omics characterization of avian gut microbiomes and next-generation sequencing for functionally annotated isolate development.
Feed Manufacturers retain the largest procurement volume, though Poultry Farms are expanding their share fastest through disintermediation.
Application:
Functional claim differentiation is compressing commodity premix margins while expanding premium tiers for isolates with validated metabolic pathway annotations.
- Growth Promotion:Strain-typed cocktails with defined nutrient metabolism modulation deliver measurable weight gain improvements. Danish and Dutch layer operations adopting precision microbiome approaches prioritize growth promotion claims backed by whole-genome functional annotation.
- Disease Prevention:Pathogen exclusion through competitive colonization and bacteriocin production addresses antibiotic reduction mandates. Brazilian operations under ANVISA veterinary oversight embed disease prevention probiotics earlier in production cycles.
- Nutrient Absorption:Phytase and enzyme co-production by specific Bacillus isolates improves feed conversion efficiency.
- Stress Reduction:Oxidative stress management through antioxidant-probiotic premix convergence in heat-challenged environments.
Growth Promotion holds the leading position, while Disease Prevention is gaining share fastest under antibiotic dependency reduction protocols.
Form:
Format selection hinges on feed mill integration versus operational flexibility, with thermostability requirements favoring certain delivery mechanisms.
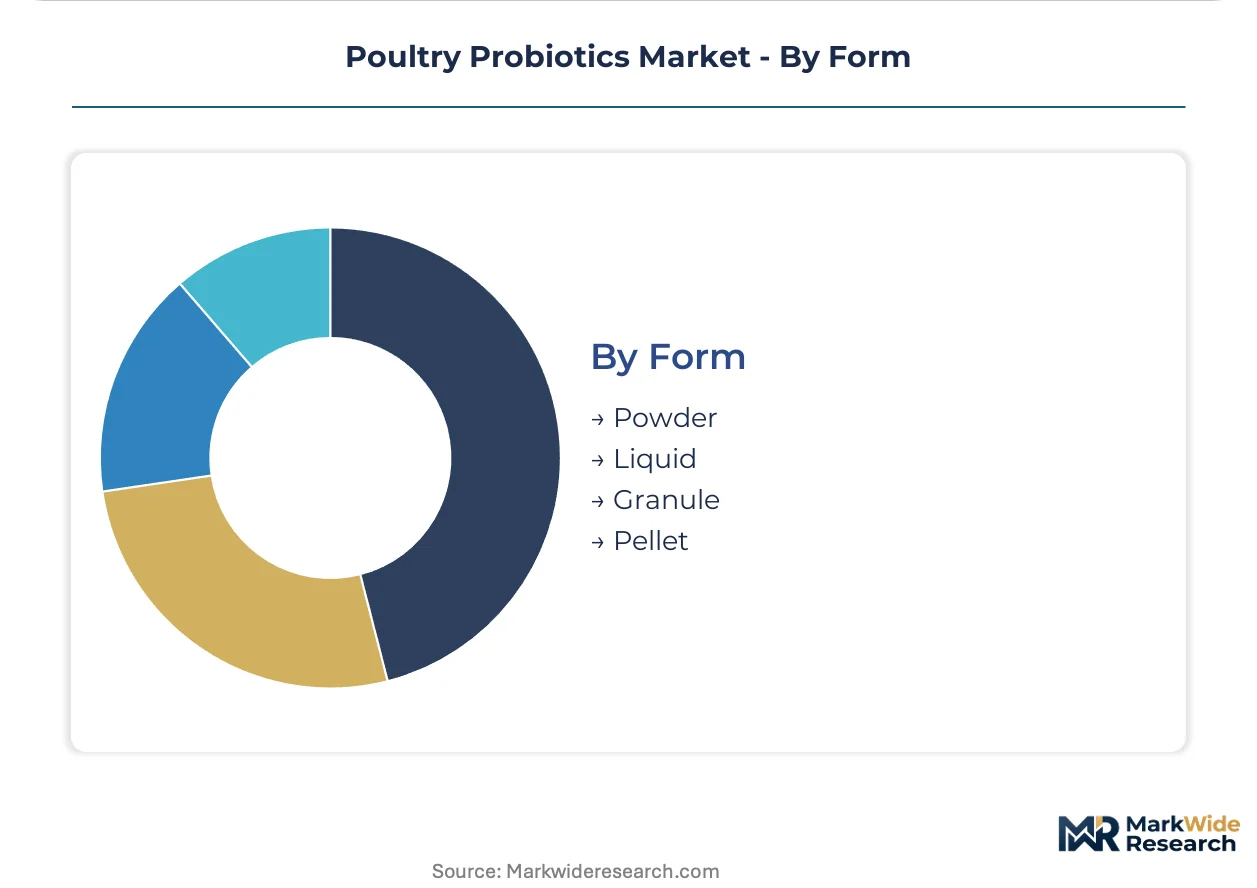
- Powder:Dominant current output format for feed mill integration, requiring rigorous Bacillus spore former validation for pelleting survival. Powder formulations lead among established European and North American operations with captive feed manufacturing.
- Liquid:Fastest-expanding segment for in-water application independent of feed mill schedules. Integrated operations across multiple geographies prioritize liquid delivery for flexible administration timing during stress events or disease challenge windows.
- Granule:Intermediate format offering dust reduction and flowability improvements for automated feed systems.
- Pellet:Direct incorporation into finished feed with embedded probiotic protection through matrix encapsulation.
Powder maintains the largest share, while Liquid is climbing the fastest through operational flexibility demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for defined live microbial cultures clusters among established culture collection holders in Denmark, the Netherlands, and Brazil. These supply nodes anchor distribution networks serving integrated poultry operations across multiple continents. Regulatory divergence between FDA veterinary feed directive enforcement, EFSA QPS evaluations, and ANVISA veterinary oversight shapes regional market entry strategies.
United States
Integrated broiler operations in the Southeast and Midwest are expanding direct sourcing relationships with fermentation specialists. FDA veterinary feed directive enforcement since 2017 has constrained antibiotic growth promoter use, creating pull-through demand for thermostable Bacillus formulations in starter feeds. The Delmarva Peninsula poultry cluster anchors East Coast probiotic demand from feed manufacturers seeking pelleting survival validation.
Brazil
ANVISA veterinary oversight is accelerating probiotic inclusion rates in starter feeds across São Paulo and Paraná broiler integrators. The country's national agricultural regulator maintains strict product registration pathways that favor established culture collection holders with complete dossier archives. Southern Brazil's integrated poultry corridor represents the fastest-expanding demand node for in-water liquid delivery systems independent of feed mill schedules.
Germany
EFSA strain-specific QPS evaluations are compressing market entry timelines for novel isolates while validating premium positioning for approved Bacillus subtilis and B. licheniformis strains. Layer operations in Lower Saxony prioritize FCR optimization through precision microbiome approaches backed by whole-genome functional annotation. The Hanover-Leipzig logistics corridor concentrates feed additive distribution serving high-density housing systems across Northern Europe.
China
Evolving GB standards for feed additives under the Ministry of Agriculture are reshaping product registration requirements for domestic and imported probiotic formulations. Yangtze River Delta integrators are embedding probiotics earlier in production cycles to establish gastrointestinal colonization before pathogen exposure peaks. Shandong Province's feed manufacturing cluster drives demand for Bacillus spore formers with validated thermotolerance through 85°C+ pelleting conditions.
Netherlands
Next-generation sequencing adoption among Dutch layer operations is decomposing the traditional high-CFU formulation paradigm in favor of strain-typed cocktails with defined metabolic pathway annotations. EFSA's updated QPS framework accelerates dossier requirements while the country's culture collection holders leverage deep regulatory archives. The Randstad logistics hub anchors European distribution for thermostable spore formers serving Danish and German contract poultry production.
Poultry Probiotics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the poultry probiotics space. Strain-level differentiation and fermentation scale concentrate among established culture collection holders with deep regulatory dossiers, while regional formulators compete on service proximity and application support. Three archetypes dominate: integrated fermentation-platform players with multi-territory approvals, specialized Bacillus spore former developers with thermostability IP, and antioxidant-probiotic premix integrators addressing dual physiological stressors. Competitive moves center on direct sourcing relationship cultivation with top-ten global poultry processors and in-water liquid delivery system format expansion.
Within the integrated fermentation-platform tier, Chr. Hansen and Novonesis occupy positions anchored by culture collection depth and regulatory archive completeness. Kemin Industries exemplifies the antioxidant-probiotic convergence archetype, representing integrated premix platforms that address oxidative stress alongside microbiome modulation. These three entities span the technology-to-application value chain without vertical integration into captive poultry operations.
| Leading Market Players |
|---|
| Chr. Hansen |
| DSM-Firmenich |
| Evonik Industries |
| Novonesis |
| Lallemand |
| Kemin Industries |
| Novus International |
| International Flavors & Fragrances |
| Alltech |
| Others |
Value Network & Pricing Analysis
Direct sourcing relationships with fermentation specialists displacing trader-mediated distribution in Brazil and Thailand simultaneously redraw procurement geography and compress margin capture for legacy intermediaries. This shift concentrates pricing power with culture collection holders possessing deep regulatory dossiers while fragmenting downstream margin pools.
Pricing Analysis
EFSA strain-specific QPS evaluations dictate the pricing tier structure across European layer operations, validating premium positioning for approved Bacillus subtilis and B. licheniformis isolates while compressing commodity premix margins. Three-tier pricing structure across premium, standard, and economy levels separates whole-genome validated strains from generic CFU claims and undifferentiated lactic acid bacteria blends. Cost compression in standard tiers is intensifying because Brazilian and Thai integrators are unbundling probiotic procurement from legacy feed supplier contracts. Poultry farms with multi-site operations show least price sensitivity due to supply security priorities, while independent feed manufacturers in price-sensitive segments exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for defined live microbial cultures extend substantially for novel isolates awaiting EFSA QPS evaluation completion, constraining just-in-time procurement flexibility. Supply concentrates in Denmark, the Netherlands, and Brazil among established culture collection holders with axenic maintenance capabilities and freeze-drying optimization expertise. Fermentation capacity draws from specialized bioreactor infrastructure, qualified microbiologist labor pools, and regulatory dossier archives. Single-source vulnerability around strain banking expertise scarcity creates concentration risk when qualified personnel command premium compensation. Distribution runs through direct relationships with top-ten global poultry processors seeking supply security independent of feed mill schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-omics characterization of avian gut microbiomes represents a technological inflection redirecting R&D investment toward functionally annotated isolates rather than generic blends, compressing development timelines and reshaping competitive moats.
For Market Incumbents: Consolidate regulatory dossier depth as the primary defensive moat against emerging fermentation specialists by accelerating whole-genome safety assessment submissions under EFSA's updated QPS framework. Expand captive fermentation capacity in Southern Brazil's integrated poultry corridor to capture ANVISA veterinary oversight-driven demand growth. Prioritize in-house production of thermotolerant Bacillus spore formers to secure pelleting survival validation capabilities.
For New Entrants and Emerging Players: Differentiate on liquid delivery system format innovation targeting integrated operations seeking flexible administration timing independent of feed mill schedules. White-space opportunities concentrate in antioxidant-probiotic premix convergence for heat-challenged environments and USDA organic certification pathway compliance for contract poultry production. The most penetrable entry point lies with mid-sized Brazilian broiler integrators expanding probiotic inclusion under ANVISA veterinary oversight. Go-to-market execution should anchor on direct sourcing relationship cultivation bypassing legacy feed supplier intermediation.
For Investors and Strategic Acquirers: The market sits at a strain-level differentiation phase that favors culture collection holders with deep regulatory archives and multi-territory approval footprints. Long-term viability over the coming decade rests on exclusive strain access and fermentation scale rather than formulation capabilities alone. Acquisition target archetype: specialized Bacillus spore former developers with validated thermostability IP and incomplete geographic dossier coverage. Monitor EFSA QPS evaluation timeline acceleration as the critical inflection signal for exclusivity window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Regulatory Dossier Expansion | EFSA QPS evaluation completeness validates premium positioning and extends exclusivity windows for proprietary isolates. |
| In-Water Liquid Delivery System Scale-Up | Flexible administration timing independent of feed mill schedules captures fastest-expanding format segment demand. |
| Direct Sourcing Relationship Cultivation | Disintermediation of trader-mediated distribution secures supply security with top-ten global poultry processors. |
| Antioxidant-Probiotic Premix Integration | Dual physiological stressor addressing in heat-challenged environments creates defensible margin tiers. |
| Fermentation Capacity Addition in Brazil | ANVISA veterinary oversight-driven demand growth anchors supply node proximity to expanding broiler integrators. |
Research Methodology
Cross-validation between primary interviews with fermentation platform executives, regulatory affairs specialists at feed additive manufacturers, procurement directors at integrated poultry operations, and technical veterinarians at broiler integrators anchors the qualitative findings. Secondary validation draws from ANVISA veterinary product registration databases, EFSA QPS evaluation records, USDA National Organic Program standards documentation, and Chinese Ministry of Agriculture GB standards filings. Bottom-up strain-level demand modeling triangulates against top-down fermentation capacity assessments across Denmark, the Netherlands, and Brazil.
Sensitivity analysis around pelleting thermotolerance validation rates and regulatory approval timeline scenarios informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user procurement authority structure, application functional claim, and delivery format preference. CAGRs derive from strain-specific adoption curve analysis weighted by geographic regulatory enforcement intensity. Industry-specific forecast inputs incorporate ANVISA veterinary oversight expansion trajectories and EFSA whole-genome safety assessment requirement implementation pacing.
Material uncertainties — novel isolate approval pathway delays, fermentation capacity concentration disruptions, antibiotic residual pricing volatility — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement continuity and strain banking expertise availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
Herbal Yeast Market