
 Infant and Kids Probiotics Market | 2026-2036
Infant and Kids Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Infant and Kids Probiotics Market Analysis
Danish contract fermentation capacity is decoupling from finished-goods packaging, creating a two-tier supply architecture. BioGaia leverages its proprietary L. reuteri strains to dominate the infant colic therapeutic segment. Culturelle anchors the North American pediatric channel through pharmacist-recommended positioning. Danone sustains broad geographic coverage with dairy-integrated probiotic delivery systems.
Infant and kids probiotics comprise live microbial preparations containing defined bacterial strains at minimum viable counts, typically formulated for gastrointestinal colonization support and immune modulation in subjects under twelve years. Manufacturing employs freeze-drying or cryoprotectant stabilization to maintain colony-forming unit integrity through shelf life. Liquid formulations lead volume in the infant cohort due to ease of administration, while chewable formats capture margin pools among preschoolers transitioning to self-directed consumption. Multi-strain products now outpace single-strain offerings as parents seek broader microbiome coverage.
The FDA's live biotherapeutic products guidance shapes clinical trial requirements and label claim substantiation for U.S. market entrants. EFSA's qualified presumption of safety framework governs strain authorization across European formulations, while China's NMPA registration pathway determines access to its cross-border channels. Stakeholders must monitor how divergent safety dossier requirements between FDA and EFSA frameworks affect portfolio rationalization and regional launch sequencing.
Market Dynamics
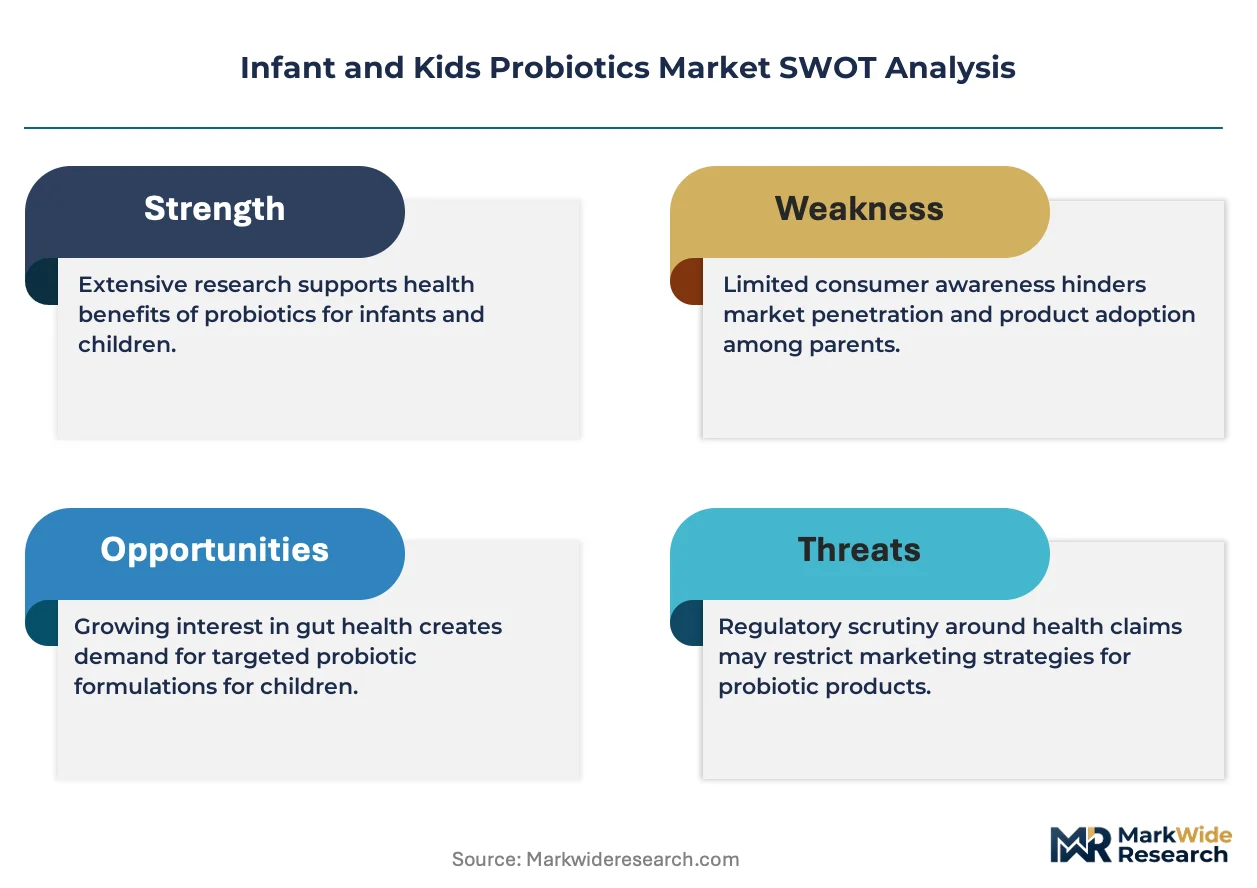
Strain-specific regulatory validation requirements are fragmenting product portfolios as manufacturers pursue parallel FDA live biotherapeutic product pathways and EFSA qualified presumption of safety dossiers.
Growth Catalysts
- EFSA Qualified Presumption of Safety:Streamlined strain authorization accelerates European formulation launches and reduces redundant toxicology studies for heritage dairy cultures.
- Pediatric clinic recommendation protocols:North American physician networks now embed multi-strain probiotics into infant colic management guidelines, creating institutional demand pull.
- Cross-border e-commerce infrastructure:Chinese urban parents source premium formulations through bonded warehouse channels, bypassing domestic registration delays.
Market Restraints
- Freeze-dry input cost volatility:Trehalose and skim milk powder prices fluctuate with dairy commodity cycles, compressing margin on stabilized formulations.
- Danish fermentation capacity concentration:Contract manufacturing clusters in Copenhagen and Aarhus create geographic supply risk for strain biomass.
- FDA-EFSA dossier divergence:Incompatible safety study designs force duplicate clinical trials, extending time-to-market by 18-24 months.
Strategic Opportunities
- Preschool chewable segment:Self-directed consumption formats for ages 3-5 remain underdeveloped relative to infant drops, offering margin expansion potential.
- Strain banking partnerships:Biorepository collaborations with academic microbiome centers enable access to novel taxa outside commercial collections.
- SAMR fast-track pathways:China's 2023 biotech registration reforms prioritize pediatric indications, reducing review timelines for imported live biotherapeutics.
Industry Challenges
- Colony-forming unit stability certification:Shelf-life validation requires accelerated aging protocols that lack harmonization between pharmacopeial methods.
- Strain identity verification: Whole-genome sequencing expertise sits primarily with contract labs, creating bottlenecks for in-house quality control expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant and Kids Probiotics Market |
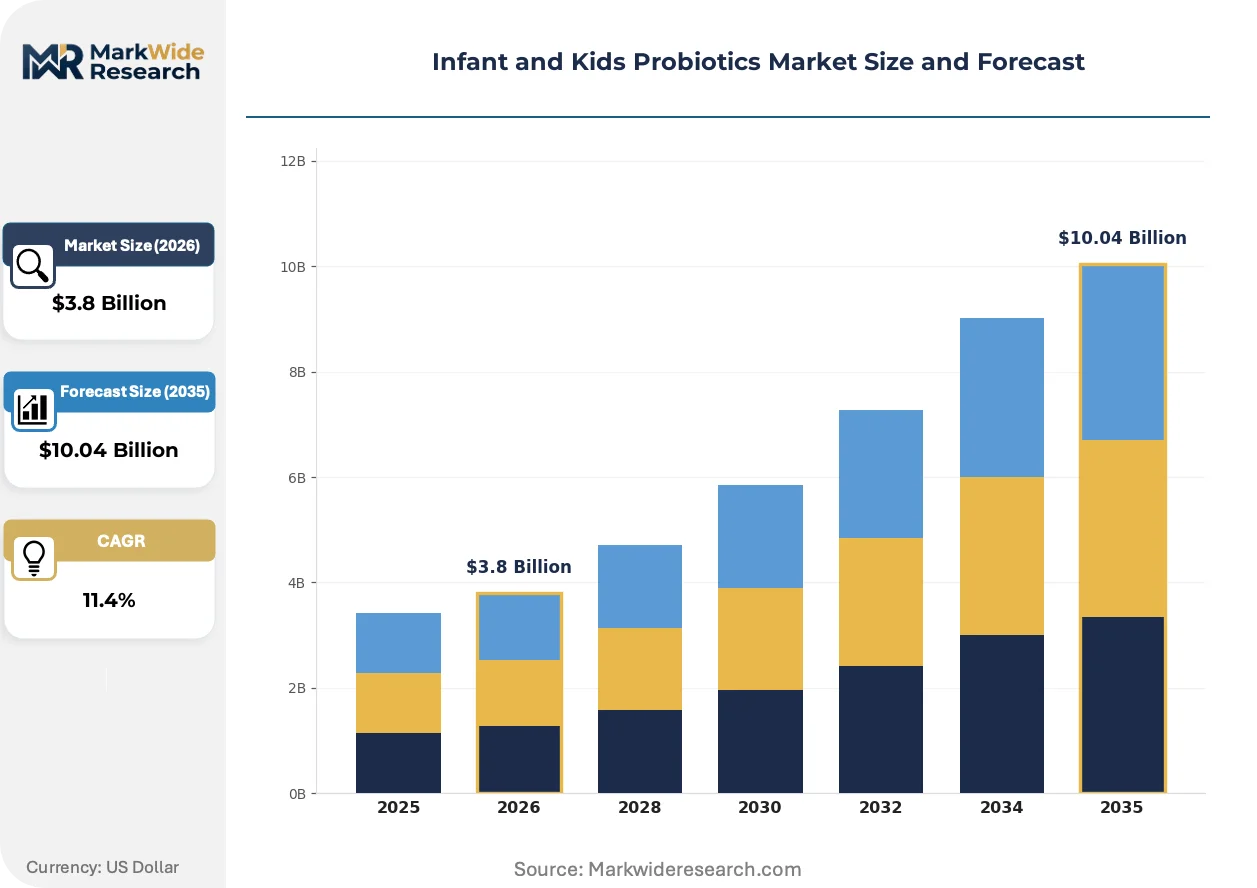
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Chewable, Capsules Distribution Channel: Online Retail, Drugstores, Supermarkets, Health Food Stores End User: Infants, Toddlers, Preschoolers, School-Aged Children Formulation: Single Strain, Multi-Strain, Organic, Non-GMO |
| Companies Covered | Garden of Life, Culturelle, BioGaia, Yakult Honsha, NOW Foods, Nestlé Health Science, Gerber Products Company, DSM-Firmenich, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant and Kids Probiotics Market Emerging Trajectories
Multi-strain formulation science is outpacing single-strain legacy products as microbiome research validates synergistic colonization effects. Manufacturing and packaging capabilities are decoupling geographically.
Microencapsulation technology is unifying cryoprotection and targeted release functions in a single processing step. Infant formula manufacturers in Germany and the Netherlands adopt these systems to integrate probiotics directly into powdered matrices without separate sachet dosing. This convergence is compressing the distinction between fortified nutrition and standalone supplement categories.
China's NMPA 2022 biotherapeutic registration reforms introduced pediatric-specific review tracks with abbreviated toxicology requirements for strains with documented human consumption history. Domestic manufacturers in Shanghai and Guangzhou accelerate dossier submissions while foreign entrants establish local strain banking partnerships to qualify. The cross-border channel faces pressure as registered domestic alternatives gain shelf space in tier-one maternity stores.
Subscription replenishment models displace pharmacy counter purchases among millennial parents in the United States and United Kingdom. Direct-to-consumer platforms capture recurring revenue through automated dosing reminders tied to developmental milestones. This channel shift concentrates customer data with platform operators, reducing brand leverage in repeat purchase decisions.
Infant and Kids Probiotics Market Segmentation
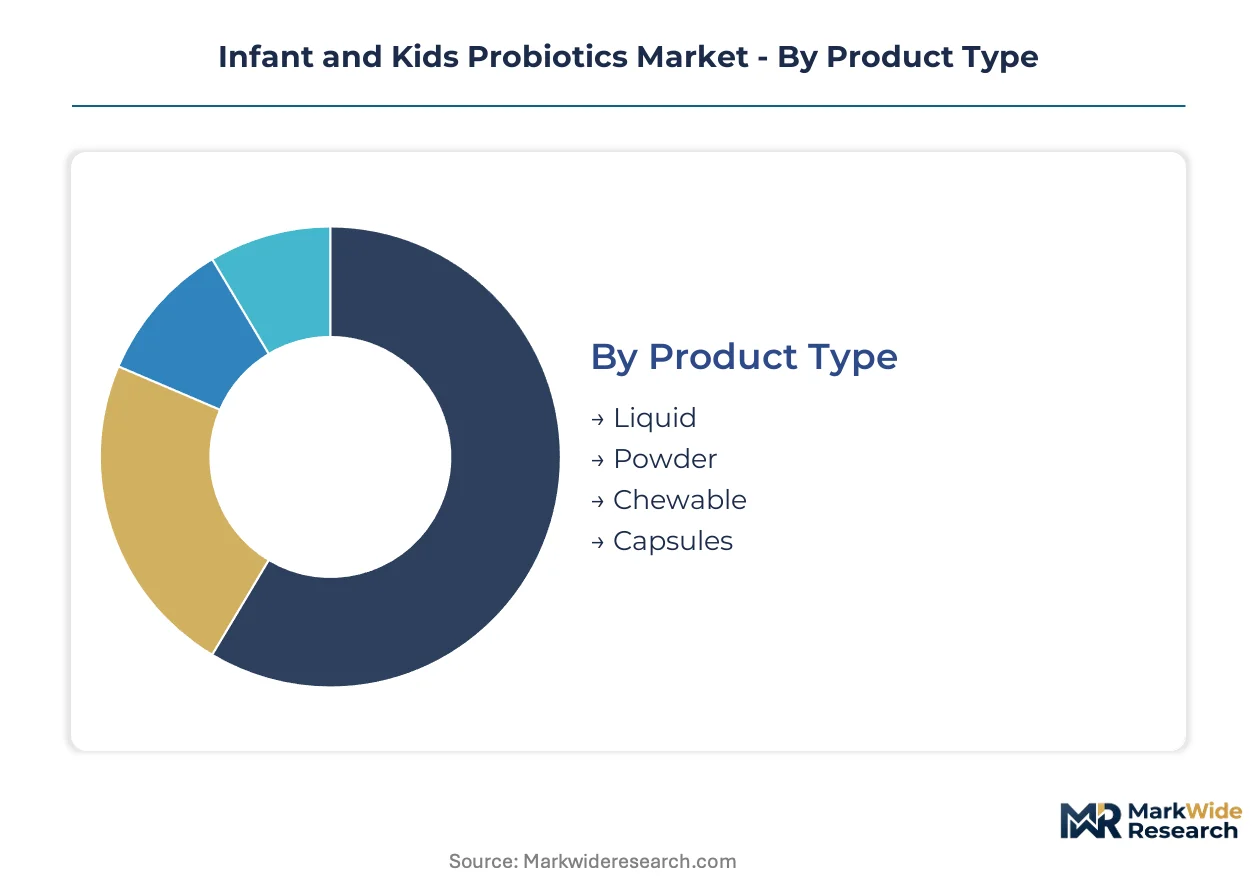
Segmentation in the infant and kids probiotics market reflects divergent administration requirements across developmental stages and the tension between standalone supplements and embedded nutrition systems. Parents select formats based on swallowing capability, taste acceptance, and integration with existing feeding routines.
Product Type:
Liquid and powder formats dominate standalone supplementation, while chewable and capsule segments serve embedded nutrition strategies targeting older children.
- Liquid:Dropper-dispensed aqueous suspensions containing cryoprotected bacterial concentrates at 10^8 to 10^10 CFU per milliliter. Demand concentrates in the United States and Germany where pediatricians recommend liquid probiotics for infant colic management during the first six months.
- Powder:Lyophilized biomass blended with maltodextrin carriers, packaged in single-serve sachets for reconstitution in milk or formula. Chinese parents source premium powders through cross-border e-commerce channels, bypassing domestic registration delays for novel strains.
- Chewable:Tablet formats incorporating flavor masking and compression-resistant strain coatings for ages two and above.
- Capsules:Hard gelatin or vegetable-based shells containing standardized CFU counts, typically reserved for school-aged children with developed swallowing reflexes.
Liquid leads volumes today; chewable is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture and customer data ownership, with digital platforms eroding pharmacy counter dominance among millennial parents.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts offering subscription replenishment tied to developmental milestones. United Kingdom and United States parents favor automated delivery for recurring purchases, concentrating customer data with platform operators rather than manufacturers.
- Drugstores:Pharmacist-assisted selection in CVS, Walgreens, and Boots locations, anchored by Culturelle and BioGaia shelf positioning. North American pharmacy chains embed probiotics into infant care aisle sets adjacent to formula and diaper categories.
- Supermarkets:Mass-market placement in Walmart, Tesco, and Carrefour baby care sections, competing for basket share with fortified yogurts.
- Health Food Stores:Specialist retailers emphasizing organic certification and strain transparency for educated parent segments.
Drugstores retain the largest transaction volume; online retail is expanding most quickly.
End User:
Developmental stage dictates strain selection, dosing precision, and regulatory classification across the pediatric spectrum.
- Infants:Subjects under twelve months requiring liquid or powder formats with documented safety in neonatal populations. Danish and Swedish pediatric clinics routinely recommend L. reuteri strains for colic and regurgitation symptoms.
- Toddlers:Children aged one to three years transitioning from breast milk or formula to solid diets, creating microbiome disruption windows. Parents in Shanghai and Beijing prioritize immune-modulating formulations during nursery enrollment periods.
- Preschoolers:Ages three to five with self-directed consumption capability and emerging dietary autonomy.
- School-Aged Children:Subjects six to twelve years facing antibiotic exposure and stress-related gastrointestinal disturbances.
Infants command premium pricing today; preschoolers show the steepest expansion trajectory.
Formulation:
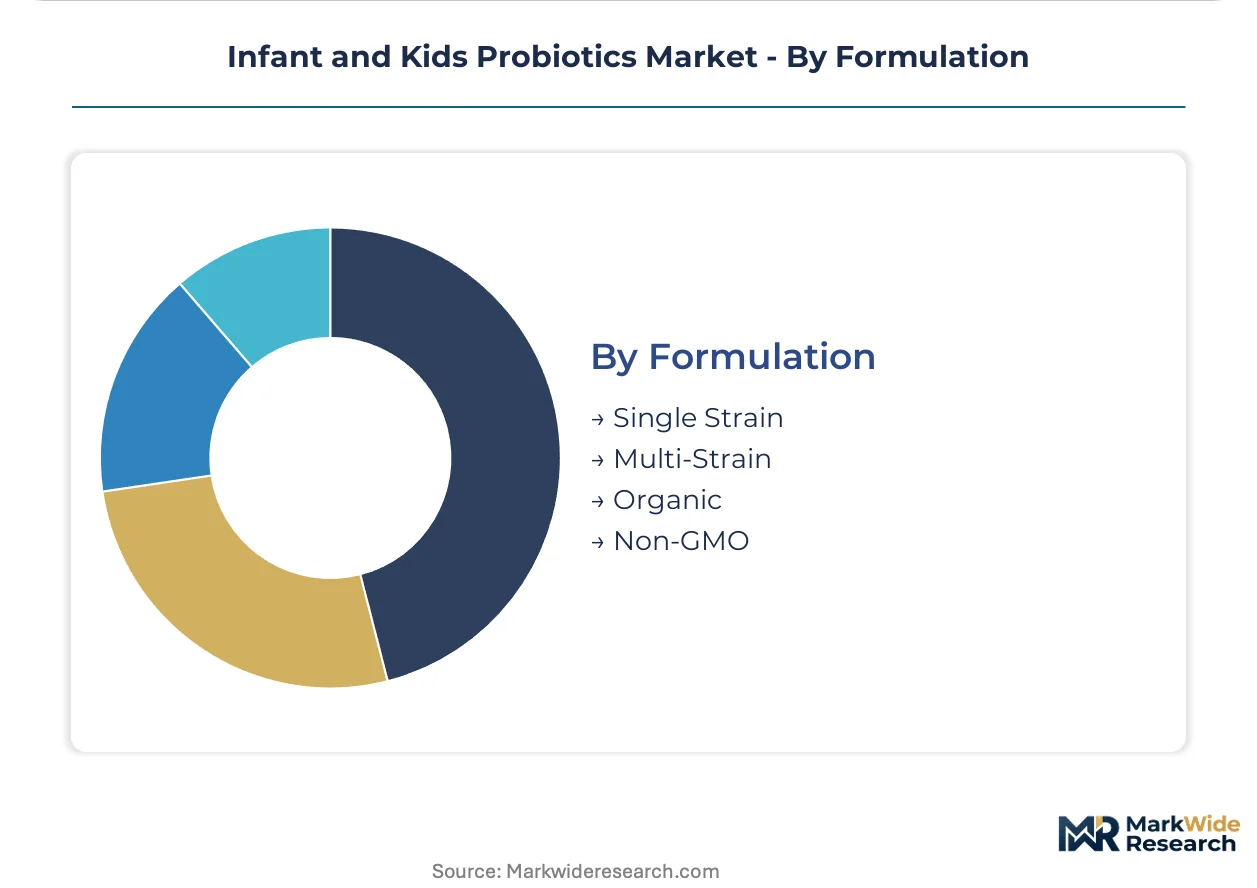
Strain architecture and certification tier determine clinical credibility and shelf positioning in an increasingly segmented parent market.
- Single Strain:Monoculture preparations leveraging documented mechanisms for specific indications such as L. rhamnosus GG for antibiotic-associated diarrhea. Heritage products face pressure from multi-strain alternatives as microbiome research validates synergistic colonization.
- Multi-Strain:Combinations of three to ten taxonomically distinct bacteria targeting broader microbiome coverage. EFSA's qualified presumption of safety framework accelerates European authorization for documented heritage combinations.
- Organic:Certified formulations using organic carriers and excipients, commanding shelf space in Whole Foods and specialist channels.
- Non-GMO:Verified absence of genetically modified ingredients in strain biomass and formulation matrices.
Multi-strain leads manufacturing output today; organic certification is climbing the fastest among premium-positioned parents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers weigh FDA live biotherapeutic product compliance costs against EFSA's streamlined qualified presumption of safety pathway. Danish fermentation clusters attract strain development investment while Chinese cross-border channels bypass domestic registration bottlenecks.
United States
Pediatric clinic recommendation protocols and pharmacist-assisted retail positioning drive institutional demand pull for multi-strain formulations. FDA's evolving live biotherapeutic products guidance shapes clinical trial designs and label claim substantiation requirements for market entrants. Greater Boston and Research Triangle Park host contract research organizations specializing in neonatal population safety studies.
Germany
Infant formula manufacturers adopt microencapsulation systems to integrate probiotics directly into powdered matrices without separate sachet dosing. EFSA's qualified presumption of safety framework accelerates strain authorization and reduces redundant toxicology studies for heritage dairy cultures. Bavaria and Baden-Württemberg concentrate dairy-integrated probiotic delivery system production.
China
Urban parents source premium formulations through bonded warehouse channels, bypassing domestic registration delays for novel strains. NMPA's 2022 biotherapeutic registration reforms introduced pediatric-specific review tracks with abbreviated toxicology requirements. Shanghai and Guangzhou manufacturers accelerate dossier submissions while foreign entrants establish local strain banking partnerships.
Denmark
Contract fermentation capacity in Copenhagen and Aarhus creates geographic supply concentration for strain biomass production. EFSA's qualified presumption of safety governance enables streamlined European formulation launches from Danish manufacturing bases. Copenhagen clusters specialize in L. reuteri strain cultivation for infant colic therapeutic applications.
Japan
Meticulous quality certification requirements and heritage consumption patterns sustain demand for documented strain safety profiles. PMDA's pediatric biotherapeutic review standards emphasize longitudinal colonization studies in Asian infant populations. Tokyo-Osaka corridor hosts specialist retailers emphasizing organic certification and strain transparency for educated parent segments.
Infant and Kids Probiotics Market Vendor Landscape
Danish and North American producers anchor one tier; Japanese and European specialists hold differentiated positions through heritage strain libraries and dairy integration capabilities. The vendor base concentrates around fermentation-anchored players and finished-goods marketers with pharmacist-channel relationships. Three archetypes dominate: proprietary strain developers with therapeutic positioning, dairy-integrated nutrition conglomerates, and direct-to-consumer platform operators. Capacity expansion and strain banking partnerships represent the dominant competitive moves as manufacturers secure novel taxa outside commercial collections.
Within the proprietary strain tier, BioGaia exemplifies therapeutic-focused positioning through specialized L. reuteri cultivation, while Culturelle occupies a position anchored in North American pharmacist-recommended retail channels. Danone sits within the dairy-integrated conglomerate archetype, leveraging broad geographic coverage through fermented product delivery systems. These three entities represent distinct strategic postures: single-strain therapeutic depth, pharmacy-channel brand equity, and nutrition-platform scale respectively.
| Leading Market Players |
|---|
| Garden of Life |
| Culturelle |
| BioGaia |
| Yakult Honsha |
| NOW Foods |
| Nestlé Health Science |
| Gerber Products Company |
| DSM-Firmenich |
| Danone |
| Others |
Supply Flow & Price Mechanics
Trehalose cryoprotectant costs cascade through Danish fermentation clusters into finished-goods pricing tiers, with biomass producers in Copenhagen and Aarhus commanding premium contract rates that compress margins for standalone supplement marketers downstream.
Pricing Analysis
Pharmacy-channel markup layers dominate infant probiotic economics, with three-tier pricing structure across premium, standard, and economy levels separating clinically validated multi-strain formulations from private-label alternatives. Price differentiation hinges on EFSA qualified presumption of safety certification and strain-specific clinical documentation, with subscription direct-to-consumer models undercutting retail shelf pricing through automated replenishment. Cost compression in powder formats is intensifying because cross-border e-commerce channels bypass domestic registration investments. Millennial parents purchasing through direct-to-consumer platforms show lowest price sensitivity, while supermarket basket-share buyers exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Danish contract fermentation capacity, where Copenhagen and Aarhus biomass production clusters feed finished-goods packagers across Germany, the United States, and China. Raw material dependencies center on trehalose cryoprotectants, skim milk powder carriers, and maltodextrin blending substrates sourced from dairy commodity markets. Supply chain risk manifests as geographic concentration exposure, with EFSA regulatory alignment offering limited alternative sourcing outside Danish EFSA-qualified facilities. Distribution runs through bonded warehouse channels for Chinese cross-border access, pharmacy chain direct delivery in North America, and dairy-integrated co-manufacturing networks across Bavaria and Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward multi-strain formulations carrying documented clinical validation and EFSA qualified presumption of safety certification as parents prioritize therapeutic credibility over price.
For Market Incumbents: Cement pharmacist-channel relationships through embedded infant care aisle positioning adjacent to formula categories, while securing backward integration into strain banking partnerships with academic microbiome centers to lock out novel taxa access for emerging competitors. Threat from direct-to-consumer subscription platforms eroding repeat purchase loyalty demands preemptive data-capture investments through automated dosing reminder systems tied to developmental milestones. For New Entrants and Emerging Players: Capture the preschool chewable segment for ages three to five, where self-directed consumption formats remain underdeveloped relative to saturated infant drops markets and margin expansion potential sits untapped. The most penetrable geography is China through SAMR fast-track pediatric registration pathways, with go-to-market execution anchored in local strain banking partnerships that qualify for abbreviated toxicology requirements. For Investors and Strategic Acquirers: Roll-up economics work for proprietary strain developers with therapeutic positioning because FDA-EFSA dossier divergence forces duplicate clinical trials that extend time-to-market by 18-24 months, creating acquisition premiums for dossier-ready assets. Long-term viability over the next decade favors fermentation-anchored players with captive biomass supply over finished-goods marketers exposed to Danish capacity concentration. The signal to watch is NMPA registration reform implementation pace, as domestic Chinese alternatives gaining tier-one maternity store shelf space will compress cross-border channel premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Partnership | Academic microbiome center collaborations unlock novel taxa outside commercial collections for proprietary formulation pipelines. |
| Microencapsulation Technology Adoption | German and Dutch infant formula manufacturers integrate cryoprotected biomass directly into powdered matrices without separate sachet dosing. |
| SAMR Fast-Track Registration | China's pediatric-specific review tracks with abbreviated toxicology requirements accelerate market entry for documented heritage strains. |
| Subscription Platform Launch | Automated replenishment tied to developmental milestones captures recurring revenue and concentrates customer data with platform operators. |
| EFSA Qualified Presumption of Safety Dossier | Streamlined European strain authorization reduces redundant toxicology studies and accelerates formulation launches against FDA pathway competitors. |
Methodological Framework
Multiple input streams — executive interviews with fermentation facility directors and finished-goods brand managers, regulatory dossier analysis from FDA and EFSA submission databases, and customs records tracking cross-border e-commerce volumes — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged contract manufacturing procurement leads at Danish biomass facilities, pharmacy chain category buyers in the United States and United Kingdom, and pediatric clinic recommendation protocol administrators. Secondary validation drew from NMPA registration filings, EFSA qualified presumption of safety opinions, neonatal population safety study publications, and bonded warehouse import manifests for Chinese cross-border channels.
Data-stream reconciliation across the analysis window applied segment-specific growth drivers to derive volume and value outputs, with modeling dimensions spanning product format (liquid, powder, chewable, capsule), distribution channel (online retail, drugstore, supermarket, health food store), end-user developmental stage (infant, toddler, preschooler, school-aged), and formulation architecture (single-strain, multi-strain, organic, non-GMO). CAGRs were computed from annualized growth rate convergence across bottom-up segment builds and top-down market sizing. Industry-specific forecast inputs included EFSA authorization timelines, NMPA reform implementation pace, and pharmacy-channel recommendation protocol adoption curves.
Regulatory framework divergence between FDA live biotherapeutic product pathways and EFSA qualified presumption of safety dossiers, freeze-dry input cost volatility in dairy commodity cycles, and cross-border e-commerce policy shifts in China are the dominant revision risks that could alter trajectory assumptions underlying projections. Forecasts reflect documented stakeholder input and secondary source triangulation rather than single-source extrapolation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Asia-Pacific Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Brewer Yeast Powder Market