
 Shelf Stable Probiotics Market | 2026-2036
Shelf Stable Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Shelf Stable Probiotics Market Analytics
Market Context with Strategic Players
Capital-intensity divergence between integrated strain developers and finished-goods marketers is rotating competitive advantage toward upstream biotech capabilities. Danone leverages its dairy heritage and fermentation infrastructure to anchor shelf-stable formats in European retail. Chr. Hansen Holding A/S specializes in proprietary strain libraries and encapsulation IP that sustains premium positioning across pharmaceutical and nutraceutical channels. Kerry Group plc competes through its taste and nutrition platform, extending probiotic integration into beverage and snack applications beyond conventional supplement formats.
Technical Definition and Structural Segments
Shelf stable probiotics comprise live microbial cultures formulated to maintain defined colony-forming unit counts at ambient temperatures, typically achieved through spray-drying, freeze-drying, or lipid microencapsulation to protect against moisture, oxygen, and thermal degradation. These formulations serve commercial purposes ranging from digestive health maintenance to immune modulation, delivered without refrigeration infrastructure across retail, clinical, and direct-to-consumer channels. Capsules and powders occupy the dominant volume positions due to manufacturing scalability and consumer dosing convenience, while liquids represent a faster-growing niche where novel stabilization technologies expand beverage applications. Online retail channels capture expanding margin pools as subscription models and telehealth referrals reshape how fitness enthusiasts and elderly populations access clinically positioned strains.
Regulatory Frame and Forward-Looking Close
The FDA oversees shelf-stable probiotic supplements under DSHEA with distinct strain-specific health claim limitations, while EFSA in Europe enforces stricter substantiation requirements that filter market entrants by clinical evidence depth. Health Canada and Australia's TGA impose additional stability-testing protocols that shape export formulation standards for multinational suppliers. Stakeholders must monitor evolving strain-specific qualification pathways as regulators in multiple jurisdictions recalibrate live microbe definitions between food, supplement, and emerging live biotherapeutic categories.
Market Dynamics
Microencapsulation technology maturation is collapsing the cold-chain infrastructure barrier that historically constrained probiotic distribution, enabling ambient-stable formulations to penetrate pharmacy, convenience retail, and direct-to-consumer channels previously inaccessible to live cultures.
Growth Catalysts
- DSHEA regulatory framework:The United States maintains a permissive dietary supplement pathway under FDA oversight that allows strain-specific health claims without pre-market approval, accelerating product launch velocity for domestic and imported formulations.
- Aging demographic gut health prioritization:Consumers over 55 in developed markets are reallocating preventive health expenditure toward microbiome-targeted interventions, creating sustained pharmacy channel pull-through for clinically positioned strains.
- Lyophilization process optimization:Advances in freeze-drying protocols and cryoprotectant formulations are extending viable cell counts at 25°C storage, reducing spoilage rates and enabling mass-market retail placement.
Market Restraints
- Strain IP concentration:Proprietary culture collections held by a limited number of European and North American biotech suppliers create licensing bottlenecks and royalty cost inflation for finished-goods manufacturers.
- EFSA health claim substantiation:European regulators enforce stringent clinical evidence requirements for digestive and immune benefit assertions, filtering market entrants and compressing permissible marketing language.
- Moisture sensitivity technical ceiling:Even advanced encapsulation cannot fully eliminate water activity degradation in tropical climates, constraining shelf-life claims and export viability to high-humidity zones.
Strategic Opportunities
- Subscription commerce channel expansion:Direct-to-consumer platforms with automated replenishment algorithms are capturing margin pools previously allocated to pharmacy intermediaries, particularly among fitness-oriented demographics.
- Live biotherapeutic regulatory reclassification:FDA and EMA pathway development for prescription-grade microbiome therapeutics creates premium pricing tiers and clinical validation requirements that favor established strain developers.
- Beverage application white space:Novel stabilization technologies enabling liquid probiotic integration into ready-to-drink formats are opening snack and functional beverage categories beyond traditional supplement delivery.
Industry Challenges
- Strain characterization skill scarcity:Qualified microbiologists capable of viability testing, genomic identification, and stability protocol development command premium compensation in a talent market constrained by academic pipeline limitations.
- cGMP certification timeline compression:Dietary supplement manufacturers face 18-24 month facility qualification periods under FDA 21 CFR Part 111, delaying market entry and consuming working capital.
- Cross-border stability documentation:Harmonizing CFU count validation across Health Canada, TGA, and ASEAN regulatory frameworks requires redundant testing protocols that inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf Stable Probiotics Market |
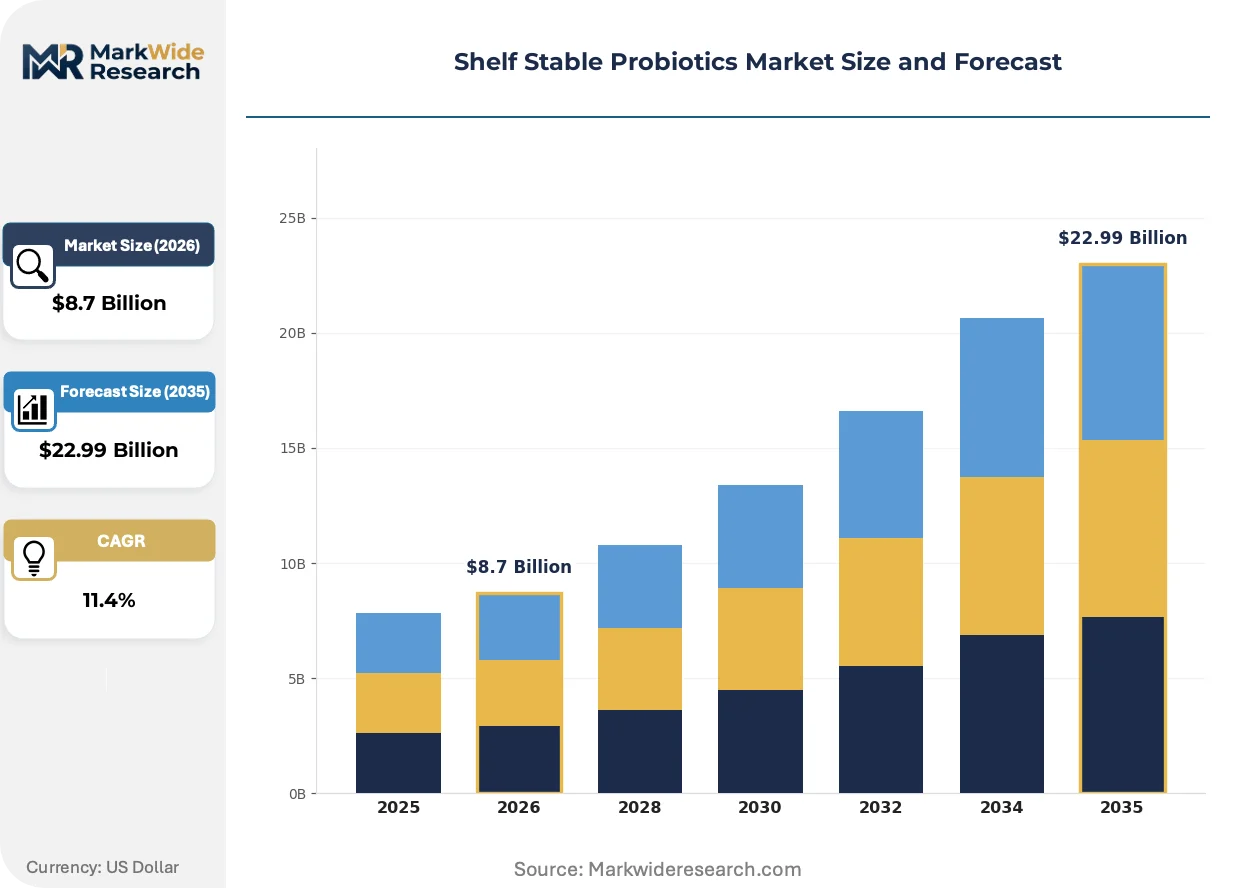
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquids End User: Retail Consumers, Healthcare Providers, Fitness Enthusiasts, Elderly Population Packaging Type: Plastic Bottles, Sachets, Blister Packs, Pouches Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Danone, Yakult Honsha Co., Ltd., Nestlé S.A., Chr. Hansen Holding A/S, DSM-Firmenich AG, Kerry Group plc, Probi AB, International Flavors & Fragrances Inc., Synlogic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf Stable Probiotics Market Evolving Landscape
Lipid-based microencapsulation systems are replacing traditional polysaccharide matrices as the dominant stabilization architecture, enabling probiotic survival in gastric environments while maintaining ambient storage viability. This technological pivot is compressing formulation cost structures and expanding addressable delivery formats.
Multi-layer lipid emulsion technology is displacing conventional alginate-gelatin encapsulation in high-volume production lines. Functional beverage manufacturers in North America and Western Europe are adopting these systems at accelerated procurement cycles. The shift is displacing legacy spray-drying equipment investments and forcing contract manufacturers to retool toward precision co-extrusion capabilities.
EFSA's 2023 guidance recalibration on gut microbiome health claims is tightening evidentiary standards for strain-specific benefits. This regulatory compression is diverting R&D expenditure toward human intervention trials and away from in-vitro screening. European pharmaceutical and nutraceutical channels are responding by consolidating supplier relationships with entities possessing established clinical dossiers.
Telehealth platform integration is restructuring how elderly and immunocompromised populations access clinically positioned probiotics. Pharmacy benefit managers and digital health providers are embedding strain recommendations into remote consultation workflows. This channel migration is most visible in United States Medicare Advantage networks and United Kingdom NHS digital-first pilot programs.
Shelf Stable Probiotics Market Segmentation
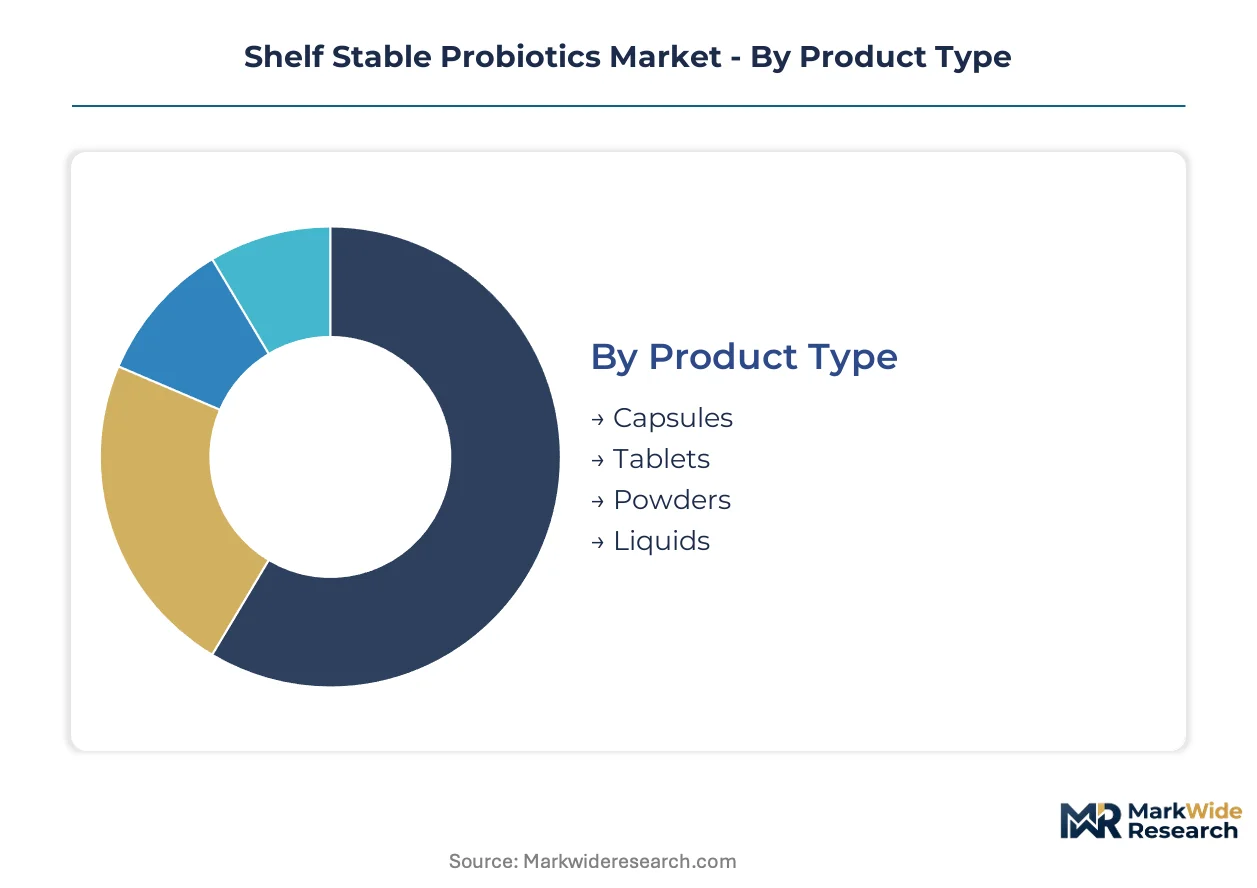
Segmentation in shelf-stable probiotics reveals how stabilization technologies align with distinct consumption contexts and regulatory pathways. Each dimension exposes different margin structures, cold-chain independence requirements, and channel access constraints that shape competitive positioning.
Product Type:
FDA's DSHEA framework treats capsules and tablets as dietary supplements with distinct labeling requirements from food-format powders and liquids, creating formulation strategy divergence across delivery systems.
- Capsules:Hard-shell gelatin or hydroxypropyl methylcellulose enclosures protect lyophilized cultures from gastric acid through enteric coating technologies. Demand concentrates among pharmacy and online retail channels serving elderly populations seeking precise CFU dosing with minimal excipient burden.
- Powders:Bulk formulations enable flexible dosing and blend compatibility with functional foods. Fitness enthusiasts and beverage manufacturers drive procurement through direct-to-consumer platforms and ingredient supply contracts, prioritizing solubility and flavor masking over portability.
- Tablets:Compressed formats with binders and disintegrants suit mass-market retail placement with extended shelf stability. Compact packaging appeals to travel-oriented consumers.
- Liquids:Novel emulsion stabilization enables ready-to-drink probiotic integration, expanding into convenience retail and foodservice channels previously inaccessible to live cultures.
Capsules handle the majority of throughput; liquids are expanding most quickly on share.
End User:
Customer archetypes diverge sharply in clinical evidence requirements, price elasticity, and channel preferences, forcing manufacturers to choose between premium positioning and mass-market scale.
- Retail Consumers:Mass-market purchasers prioritize convenience, brand recognition, and general wellness claims over strain-specific documentation. Supermarket and online retail channels dominate access.
- Healthcare Providers:Clinicians and pharmacists demand third-party stability testing, documented CFU counts at expiration, and strain-level genomic identification. This segment commands premium pricing through pharmacy and telehealth referral pathways.
- Fitness Enthusiasts:Performance-oriented consumers seek digestive optimization and immune support with subscription-based replenishment. Direct-to-consumer platforms capture this cohort through influencer partnerships and automated delivery.
- Elderly Population:Aging demographics with compromised immune function require clinically validated strains with moisture-resistant packaging. Medicare Advantage networks and NHS digital-first programs increasingly embed probiotic recommendations into remote consultation workflows.
Retail consumers generate the volume base; healthcare providers deliver the steepest margin expansion.
Packaging Type:
Moisture barrier performance and oxygen transmission rates determine viable shelf life, with tropical climate export viability hinging on material science selection.
- Plastic Bottles:High-density polyethylene and desiccant-lined containers dominate capsule and tablet formats for pharmacy and supermarket channels, offering resealability and child-resistant closure compatibility.
- Sachets:Single-serve aluminum-laminate pouches protect powder formulations from humidity during distribution. Fitness and travel segments favor portion control and portability.
- Blister Packs:Individual cavity sealing with aluminum foil backing extends stability for moisture-sensitive strains in clinical and pharmacy settings requiring unit-dose compliance tracking.
- Pouches:Flexible stand-up bags with multi-layer barrier films accommodate bulk powder formats for subscription commerce and ingredient supply to food manufacturers.
Plastic bottles command the installed base; sachets are climbing the fastest on adoption curves.
Distribution Channel:
Channel selection determines margin retention, regulatory scrutiny intensity, and consumer education burden, with digital platforms disrupting traditional pharmacy intermediation.
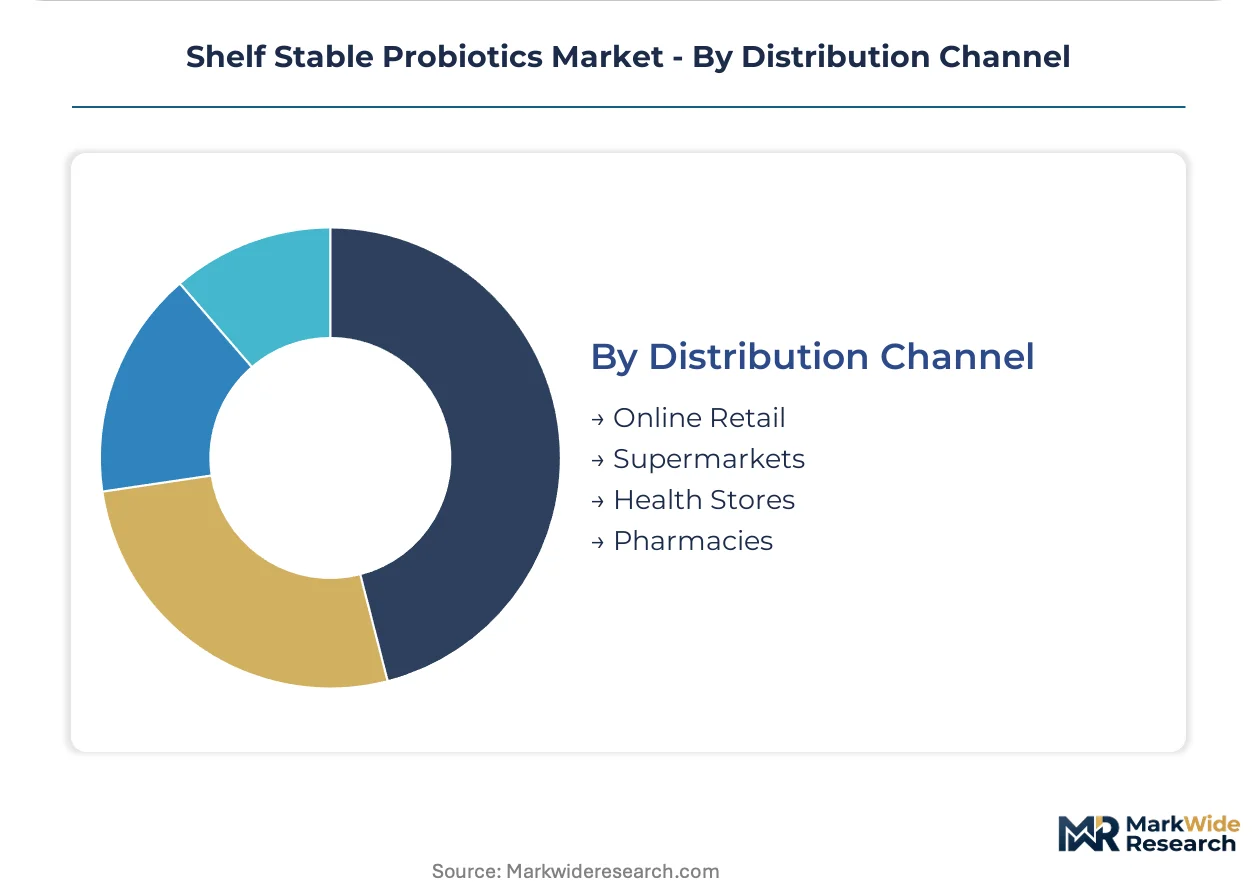
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription models, telehealth integration, and strain-specific educational content. Automated replenishment algorithms capture recurring revenue from fitness enthusiasts and elderly subscribers.
- Supermarkets:Mass-market placement requires competitive unit economics and simplified health claims compliant with FDA labeling guidance. Shelf-stable formats bypass refrigeration infrastructure constraints that limited historical probiotic distribution.
- Health Stores:Specialty retailers emphasize premium positioning, staff training, and practitioner referral networks. EFSA-compliant clinical dossiers support immune and digestive benefit assertions in European markets.
- Pharmacies:White-coat endorsement and insurance-adjacent positioning validate premium pricing for clinically positioned strains. Pharmacy benefit managers increasingly embed probiotics into preventive care protocols.
Pharmacies retain the highest trust premium; online retail is gaining share fastest through subscription lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for clinically positioned strains, while price sensitivity dominates mass-market adoption in India and Southeast Asian markets.
United States
Pharmacy channel expansion and Medicare Advantage preventive care protocols drive strain-specific procurement. FDA's DSHEA framework permits health claims without pre-market approval, accelerating launch velocity. Greater Boston and San Diego biotech clusters concentrate lyophilization R&D and contract manufacturing capacity.
Germany
EFSA-compliant clinical dossiers command premium positioning in pharmacy and practitioner channels. The country's national pharmaceutical regulator enforces stringent stability-testing protocols that shape export formulation standards. Bavaria's ingredient manufacturing belt hosts encapsulation technology providers serving Central European nutraceutical brands.
China
Domestic functional beverage manufacturers drive procurement of ambient-stable powder formats for ready-to-drink integration. SAMR's evolving live microbe classification between food and supplement categories creates regulatory navigation complexity. Yangtze River Delta contract manufacturers scale multi-layer lipid emulsion production for regional brand clients.
Japan
Aging demographics and established fermented food culture sustain pharmacy and convenience store channel penetration. METI's functional food notification system enables specific health claim approvals with documented clinical evidence. Kansai region fermentation heritage anchors strain library development and traditional-meets-ambient product innovation.
Australia
TGA's stability-testing requirements filter market entrants by validation protocol rigor, compressing permissible supplier base. Direct-to-consumer subscription models capture fitness enthusiast and elderly demographics through telehealth-integrated platforms. Sydney and Melbourne concentrate e-commerce fulfillment infrastructure for Asia-Pacific export reach.
Shelf Stable Probiotics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in shelf-stable probiotics. Danone and Nestlé leverage dairy heritage and global distribution infrastructure to anchor ambient-stable formats in retail pharmacy channels. Chr. Hansen and DSM-Firmenich occupy the proprietary strain library and encapsulation IP tier, commanding licensing premiums from finished-goods manufacturers. Competitive moves concentrate on M&A for strain collection depth and strategic partnerships with beverage formulators seeking ambient-stable liquid integration.
Among European-anchored biotech suppliers, Chr. Hansen Holding A/S and DSM-Firmenich AG exemplify the proprietary IP tier through strain library ownership and encapsulation technology positioning. Kerry Group plc represents the taste and nutrition platform archetype, extending probiotic integration beyond conventional supplement formats. These three entities occupy positions that favor upstream control over downstream brand ownership, capturing value through ingredient supply and technology licensing rather than finished-goods marketing.
| Leading Market Players |
|---|
| Danone |
| Yakult Honsha Co., Ltd. |
| Nestlé S.A. |
| Chr. Hansen Holding A/S |
| DSM-Firmenich AG |
| Kerry Group plc |
| Probi AB |
| International Flavors & Fragrances Inc. |
| Synlogic, Inc. |
| Others |
Value Network & Pricing Analysis
Lyophilization capacity utilization above 80 percent in Denmark and Germany anchors supply concentration among integrated strain developers, compressing price floors for finished-goods marketers while elevating licensing premiums for proprietary culture collections. This scale asymmetry forces contract manufacturers toward multi-year offtake commitments or captive facility investments to secure ambient-stable powder supply.
Pricing Analysis
Subscription renewal revenue and automated replenishment algorithms drive lifetime value for direct-to-consumer platforms, displacing pharmacy margin pools. Three-tier pricing structure across premium clinically validated strains, standard mass-market formulations, and economy private-label SKUs stratifies the market. Cost compression in the economy tier intensifies because Chinese contract manufacturers are scaling multi-layer lipid emulsion capacity. Healthcare providers demonstrate the lowest price sensitivity due to insurance-adjacent positioning, while retail consumers in Southeast Asia exhibit the highest elasticity.
Supply Chain Analysis
Denmark and Germany anchor proprietary strain library development and encapsulation IP production, while the United States concentrates lyophilization R&D and contract manufacturing capacity. Raw material dependencies center on cryoprotectant formulations, pharmaceutical-grade gelatin and HPMC for capsule shells, and multi-layer barrier films for moisture-resistant packaging. Single-source vulnerability in proprietary culture collections held by European biotech suppliers creates licensing bottlenecks for finished-goods manufacturers. Distribution runs through pharmacy benefit managers, direct-to-consumer platforms, and supermarket intermediaries with divergent margin retention profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified microbiologists capable of genomic identification and stability protocol development command premium compensation that constrains formulation capacity expansion. Strain characterization skill scarcity limits how quickly contract manufacturers can achieve cGMP certification under FDA 21 CFR Part 111.
For Market Incumbents: Compound proprietary strain library depth through targeted acquisition of niche culture collections, particularly those with documented clinical dossiers for immune modulation claims. Expand lyophilization capacity in Greater Boston and San Diego biotech clusters to capture pharmacy channel growth. Defensive patent filings around novel cryoprotectant formulations will raise barriers against emerging Asian contract manufacturers scaling ambient-stable liquid production. For New Entrants and Emerging Players: Telehealth-integrated subscription services represent the most penetrable white space, as Medicare Advantage networks and NHS digital-first pilot programs embed probiotic recommendations into remote consultation workflows. Target fitness enthusiast demographics through influencer partnerships and automated replenishment algorithms. A go-to-market angle emphasizing strain-level genomic transparency and third-party stability testing at expiration will differentiate against incumbent mass-market brands. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated biotech suppliers with captive encapsulation IP over finished-goods marketers facing margin compression. Long-term viability over a multi-year horizon rests on regulatory pathway development for live biotherapeutics reclassification. Acquisition target archetype: European-anchored strain developers with EFSA-compliant clinical dossiers. The signal to watch is FDA guidance on prescription-grade microbiome therapeutic qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Library Acquisition | Deepens genomic identification capabilities and blocks competitor access to clinically validated cultures. |
| Lyophilization Capacity Expansion | Captures pharmacy channel pull-through as aging demographics prioritize preventive gut health expenditure. |
| Multi-Layer Lipid Emulsion Technology Deployment | Enables probiotic survival in ready-to-drink formats previously inaccessible to live cultures. |
| Telehealth Platform Integration | Restructures elderly population access through Medicare Advantage and NHS digital-first referral workflows. |
| EFSA-Compliant Clinical Dossier Development | Filters market entrants by evidence depth and commands premium positioning in European pharmacy channels. |
Research Methodology
Cross-validation between primary interviews with strain development executives, regulatory affairs leads at FDA and EFSA, pharmacy procurement managers, and contract manufacturing technical directors anchors the qualitative findings. Secondary validation draws from FDA 21 CFR Part 111 guidance documents, EFSA health claim opinions, ClinicalTrials.gov probiotic intervention records, and customs data on cryoprotectant chemical imports. Bottom-up capacity estimates from lyophilization facility audits triangulate against top-down demand projections from pharmacy and direct-to-consumer channel assessments.
Sensitivity analysis around strain viability decay rates and regulatory reclassification timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery format, end-user archetype, packaging barrier specification, and distribution channel type, with additional granularity on clinical evidence tier for healthcare provider segments. CAGRs derive from curve-fitting historical adoption patterns against demographic shift projections and technology maturation S-cycles. Forecast inputs incorporate lyophilization yield improvements and moisture barrier film cost trajectories.
Material uncertainties — regulatory recalibration of live microbe definitions between food, supplement, and biotherapeutic categories, plus tropical climate export viability constraints from water activity degradation — sit outside the modeled envelope. Forecasts reflect assumptions about encapsulation technology diffusion rates and pharmacy benefit manager formulary inclusion timelines. Recalibration cycles align with material shifts in FDA live biotherapeutic pathway announcements and EFSA gut microbiome health claim guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Probiotic for Men Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Bifidobacterium Probiotics Market