
 United States Probiotics Market | 2026-2036
United States Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Probiotics Market Analytics
Revenue-based licensing arrangements for probiotic strain IP is reconfiguring competitive economics in the United States, lowering capital barriers for emerging entrants while concentrating margin capture with established strain banks. Danone SA leverages its captive dairy processing network to secure raw material flow for fermented probiotic beverages. Nestle SA anchors its position through pediatric nutrition science partnerships that validate infant-specific formulations. Chobani LLC differentiates via refrigerated supply chain control, ensuring live culture viability through last-mile delivery.
Probiotics comprise live microorganisms, typically bacteria or yeast at concentrations measured in colony-forming units, that confer health benefits when administered in adequate amounts, primarily through modulation of intestinal microbiota and enhancement of mucosal immune response. Capsules dominate pharmacy and health store channels due to shelf stability and precise dosing, while gummies capture younger demographics seeking palatability over clinical positioning. Online retail for dietary supplements expands fastest as subscription models reduce customer acquisition costs and improve compliance tracking among health-conscious consumers and athletes.
FDA oversight of live biotherapeutic products and USDA organic certification requirements for dairy-based applications create dual compliance pathways that shape formulation decisions and label claims. The National Institutes of Health maintains probiotic research databases that influence physician recommendation patterns and payer consideration. Stakeholders must monitor how FDA's transition of certain probiotics to biologic classification affects manufacturing standards, clinical substantiation investments, and competitive positioning across supermarket and pharmacy channels.
Market Dynamics
FDA's live biotherapeutic product classification pathway is restructuring clinical validation requirements and manufacturing standards, forcing reformulation investments across dietary supplement and functional food portfolios.
Growth Catalysts
- Immune-modulation science:NIH-funded microbiome research is validating strain-specific health claims, expanding physician recommendation patterns for pediatric and geriatric populations.
- Direct-to-consumer subscription models:California-based wellness brands deploy personalized microbiome testing to lock in recurring revenue and improve compliance tracking.
- USDA organic dairy certification:Clean-label fermented beverages capture shelf space in conventional retail as conventional yogurt growth stalls.
Market Restraints
- Strain IP concentration:European and Japanese strain banks control premium Lactobacillus and Bifidobacterium deposits, extracting licensing fees that compress emerging brand margins.
- Cold-chain infrastructure gaps:Live culture viability requirements limit distribution reach in Texas and Florida rural markets lacking refrigerated last-mile capacity.
- FDA biologic transition uncertainty:Pending classification shifts for certain probiotic strains create capital allocation paralysis among mid-tier manufacturers.
Strategic Opportunities
- Pet nutrition extension:Companion animal microbiome products remain underdeveloped relative to human applications, with veterinary channel access offering premium pricing power.
- IRA wellness incentive alignment:Preventive health tax advantages for HSA-eligible probiotic subscriptions expand employer-sponsored program penetration.
- Next-generation synbiotics:Prebiotic-probiotic combinations targeting specific metabolic pathways attract functional food partnerships beyond conventional dairy.
Industry Challenges
- Live culture stability engineering:Shelf-stable formulation expertise concentrates among contract manufacturers, creating bottleneck dependencies for direct-to-consumer brands.
- Clinical substantiation timelines:FDA-acceptable endpoint validation for live biotherapeutic claims extends development cycles beyond typical venture capital horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Probiotics Market |
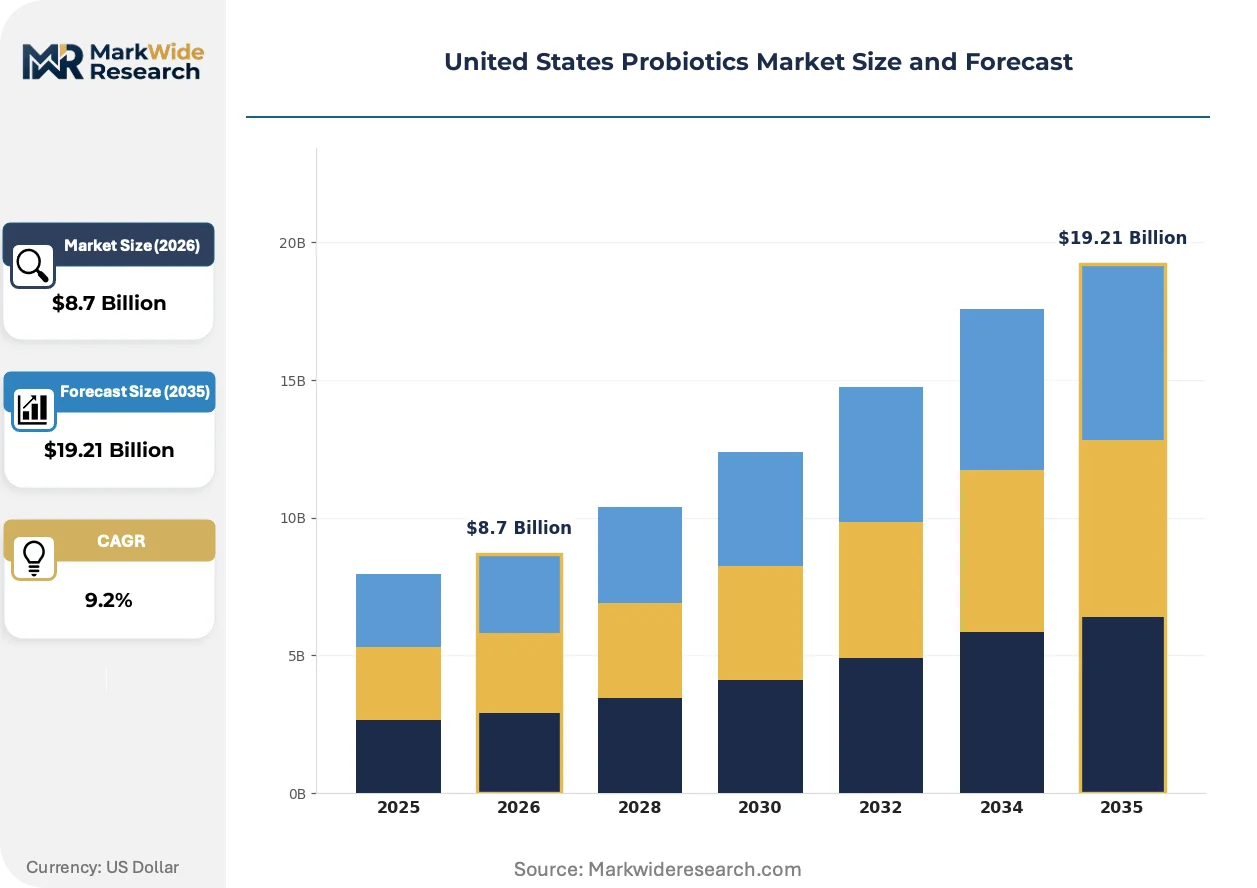
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid, Gummies Application: Dairy Products, Dietary Supplements, Non-Dairy Beverages, Infant Formulas Distribution Channel: Supermarkets, Online Retail, Health Stores, Pharmacies Customer Type: Health-Conscious Consumers, Athletes, Infants, Seniors |
| Companies Covered | Danone SA, Nestle SA, Yakult Honsha, BioGaia AB, Now Foods, General Mills Inc, Chobani LLC, Lifeway Foods Inc, PepsiCo Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Probiotics Market Evolving Landscape
Strain-specific genomic characterization is displacing generic CFU-count marketing, while delivery technology and regulatory classification frameworks undergo parallel transformation.
Multi-strain consortia with defined metagenomic profiles is migrating from academic research partnerships into commercial supplement formulations. Sports nutrition brands and metabolic health platforms adopt these precision blends fastest. The technology is migrating from boutique positioning toward mass-market functional foods as manufacturing scale economics improve.
FDA's evolving live biotherapeutic product guidance creates dual-track compliance pathways that bifurcate the industry. Strains meeting drug classification face clinical trial investments comparable to small-molecule pharmaceuticals. Dietary supplement incumbents accelerate self-affirmed GRAS submissions to preserve existing channel access and label claim flexibility.
Subscription-based microbiome testing paired with personalized strain recommendations is compressing traditional retail pharmacy purchasing. Direct-to-consumer platforms capture California and New York urban consumers first. Athletes and weight-management segments show highest retention rates as compliance data feeds back into formulation refinement.
United States Probiotics Market Segmentation
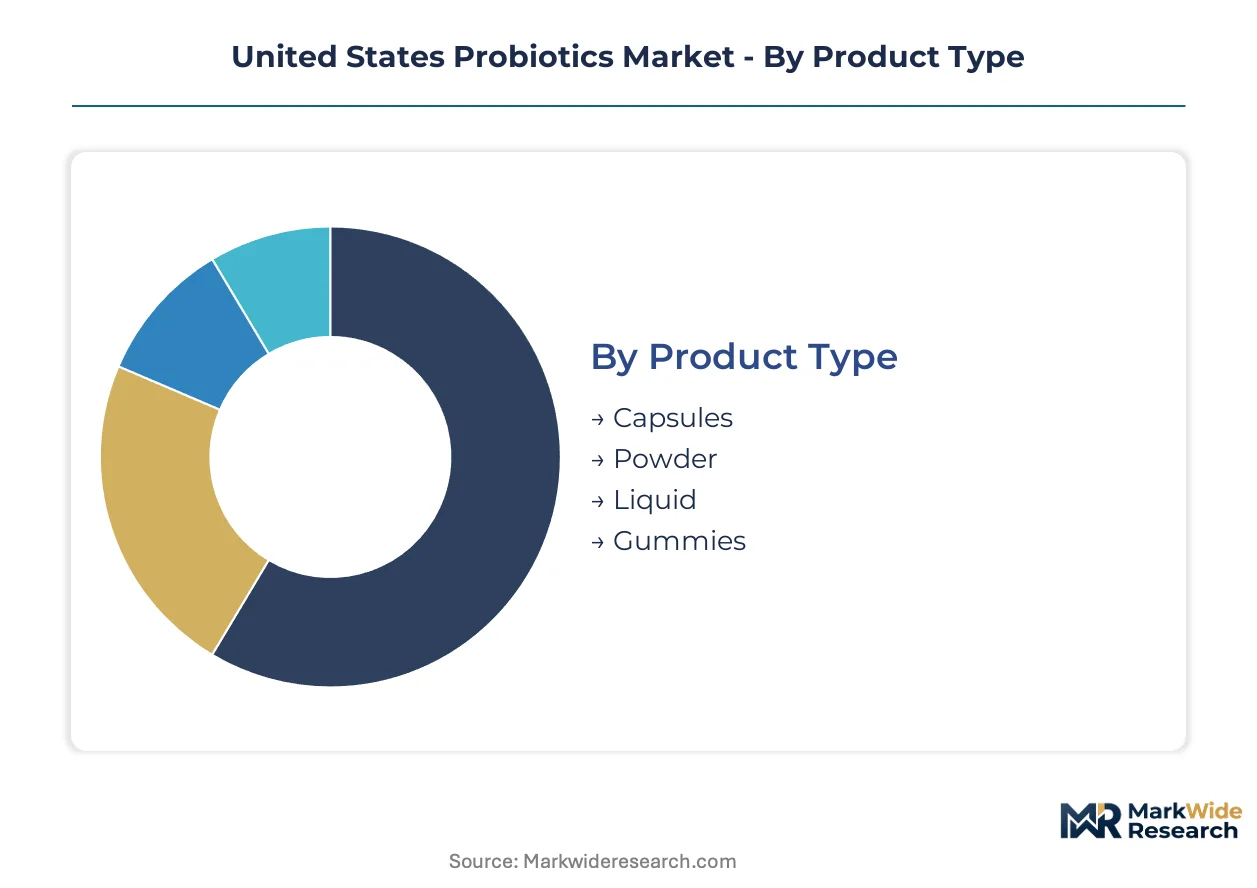
Probiotic segmentation in the United States reflects divergent supply chain requirements across delivery formats, with cold-chain sensitivity and shelf stability dictating channel economics and margin structures. Formulation choices cascade through regulatory pathways, manufacturing partnerships, and end-use positioning decisions that shape competitive returns.
Product Type:
After-sales service intensity varies sharply across probiotic delivery formats, with live culture viability guarantees and storage condition monitoring creating distinct post-purchase support obligations for refrigerated versus shelf-stable products.
- Capsules:Encapsulation technologies using enteric coatings or delayed-release polymers protect strains from gastric acid degradation. Demand concentrates in pharmacy and health store channels across California and New York, where precise dosing requirements align with clinical positioning and insurance-adjacent purchasing. Cold-chain dependency remains minimal, enabling nationwide distribution without refrigerated logistics investment.
- Gummies:Palatable chewable formats incorporate pectin or gelatin matrices with moisture-barrier packaging to maintain CFU counts. Younger demographics in urban coastal markets drive adoption, trading clinical credibility for compliance convenience in daily wellness routines. Manufacturing complexity sits with flavor masking and texture stability rather than live culture protection engineering.
- Powder:Bulk formats allow flexible dosing and blend customization for functional food integration.
- Liquid:Fermented beverages and drinkable shots require continuous cold-chain maintenance from production through consumption.
Capsules holds the largest share; momentum sits with gummies.
Application:
Margin structures diverge across application segments based on regulatory scrutiny intensity, with FDA live biotherapeutic product pathways imposing clinical trial costs that reshape competitive economics for drug-classified strains versus dietary supplement positioning.
- Dietary Supplements:Strain-specific formulations targeting immune modulation and digestive health dominate retail shelf space. California-based direct-to-consumer brands accelerate subscription penetration, using personalized microbiome testing to lock in recurring revenue and reduce customer acquisition costs. Self-affirmed GRAS submissions preserve channel flexibility against pending FDA classification shifts.
- Dairy Products:Fermented yogurts and kefirs leverage captive dairy processing networks for raw material security. USDA organic certification requirements shape label claims and sourcing decisions, with clean-label positioning capturing conventional retail expansion as conventional yogurt growth stalls. Live culture viability through refrigerated last-mile delivery anchors competitive differentiation.
- Non-Dairy Beverages:Plant-based fermented alternatives target lactose-intolerant and vegan consumer segments.
- Infant Formulas:Pediatric nutrition science partnerships validate strain-specific formulations for early-life microbiome establishment.
Dietary Supplements holds the largest share; Dietary Supplements also claims the steepest expansion trajectory.
Distribution Channel:
Customer acquisition economics vary by channel based on subscription model viability and compliance tracking infrastructure, with digital-native platforms capturing lifetime value through data feedback loops that traditional retail cannot replicate.
- Online Retail:Direct-to-consumer platforms deploy personalized microbiome testing and algorithmic strain matching to improve retention. Athletes and weight-management segments show highest subscription persistence as usage data feeds formulation refinement. Customer acquisition costs compress through referral programs and influencer partnerships concentrated in California wellness clusters.
- Supermarkets:Mass-market penetration requires shelf-stable formulations and mainstream health claims. Conventional retailers expand refrigerated sections for fermented beverages, though live culture viability constraints limit distribution reach in rural Texas and Florida markets lacking cold-chain infrastructure.
- Health Stores:Specialty retailers emphasize clinical credibility and practitioner recommendations.
- Pharmacies:Professional channel access depends on physician recommendation patterns influenced by NIH research database citations.
Supermarkets holds the largest share; momentum sits with Online Retail.
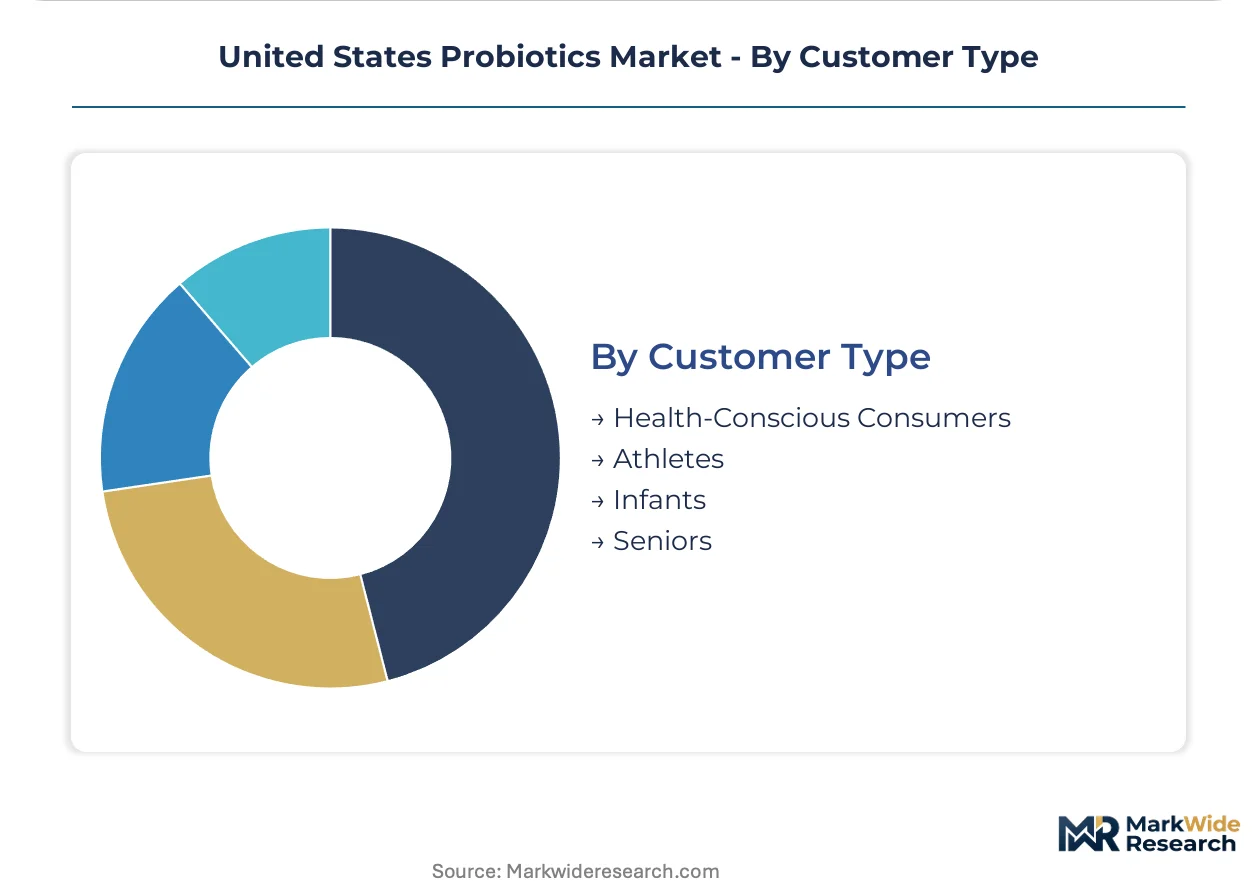
Customer Type:
Price sensitivity and clinical evidence requirements segment the consumer base, with HSA-eligible positioning and employer-sponsored programs expanding access for preventive health motivated purchasers.
- Health-Conscious Consumers:General wellness seekers prioritize gut health and immune function in daily supplementation routines. Subscription models capture this segment through convenience and compliance tracking, with California and New York urban concentrations driving initial platform scaling.
- Athletes:Sports nutrition brands adopt multi-strain consortia with defined metagenomic profiles fastest among customer segments. Recovery and performance optimization claims attract premium pricing, with usage data feeding back into precision blend refinement.
- Infants:Pediatric-specific formulations require stringent safety validation and strain selection for early microbiome development.
- Seniors:Geriatric populations respond to immune-modulation science validating strain-specific health claims.
Health-Conscious Consumers holds the largest share; momentum sits with Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers concentrate in coastal metropolitan areas, while athletes and pediatric populations drive specialized demand pockets. Cold-chain infrastructure gaps and direct-to-consumer platform density create divergent competitive economics across sub-regional markets.
California
Functional food innovation clusters and subscription wellness brands dominate demand generation in Los Angeles and San Francisco Bay Area metros. FDA live biotherapeutic product guidance shapes formulation investments by local startups seeking to preserve dietary supplement channel access. Precision microbiome testing services concentrate in San Diego and Silicon Valley, feeding data into personalized strain recommendation algorithms.
New York Metro
Pharmacy channel penetration and health store density support clinical-positioned capsule formats in Manhattan and Brooklyn markets. NIH probiotic research database citations influence physician recommendation patterns across academic medical centers. Gummy format adoption accelerates among younger demographics in urban cores seeking palatability over traditional supplement positioning.
Texas
Live culture viability requirements constrain refrigerated last-mile distribution reach in Dallas-Fort Worth and Houston exurbs lacking cold-chain infrastructure. USDA organic dairy certification supports fermented beverage expansion in Austin wellness corridors. Mass-market supermarket penetration favors shelf-stable formulations in San Antonio and rural corridor markets.
Florida
Geriatric population density in Miami-Dade and Palm Beach counties drives immune-modulation product demand validated by NIH-funded microbiome research. Cold-chain gaps limit refrigerated probiotic beverage distribution in Orlando and Tampa Bay suburban markets. Direct-to-consumer subscription platforms capture coastal retiree segments through compliance tracking and recurring delivery models.
Pacific Northwest
Clean-label fermented alternatives and plant-based non-dairy applications find early adoption in Portland and Seattle urban markets. Sports nutrition brands deploy multi-strain consortia targeting recovery and performance optimization among athlete populations. Regional dairy processing networks support organic kefir and yogurt expansion into conventional retail channels.
United States Probiotics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across bifurcated regulatory pathways. The market structure consolidates around dairy-integrated conglomerates, direct-to-consumer wellness platforms, and strain-specialist licensors. Three archetypes dominate: captive supply network operators, subscription-data platform builders, and clinical-validation-focused biotherapeutic developers. Competitive moves concentrate on refrigerated last-mile infrastructure acquisition and self-affirmed GRAS submission acceleration.
Within the dairy-integrated tier, Danone SA and Nestle SA exemplify multinational conglomerates leveraging captive processing networks. Chobani LLC occupies a position as a refrigerated supply chain specialist. These three companies represent divergent strategic anchors: Danone SA illustrates multinational beverage diversification, Nestle SA anchors pediatric nutrition science partnerships, and Chobani LLC exemplifies regional cold-chain control.
| Leading Market Players |
|---|
| Danone SA |
| Nestle SA |
| Yakult Honsha |
| BioGaia AB |
| Now Foods |
| General Mills Inc |
| Chobani LLC |
| Lifeway Foods Inc |
| PepsiCo Inc |
| Others |
Value Network & Pricing Analysis
FDA live biotherapeutic product classification uncertainty determines both tiered pricing spreads across strain grades and supply chain investment patterns as manufacturers hedge against dual compliance pathways.
Pricing Analysis
Cost-plus contracts with dairy commodity indexation anchor fermented beverage pricing, while strain licensing fees from European and Japanese banks compress emerging brand margins. Three-tier pricing structure across premium clinical-grade, standard dietary supplement, and economy private-label levels separates validated live biotherapeutic strains from self-affirmed GRAS formulations. Pricing pressure stems from cold-chain infrastructure gaps that limit distribution reach and force margin absorption. Direct-to-consumer subscription buyers show lowest price sensitivity; mass-market supermarket purchasers exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized live culture processors in California, Wisconsin, and upstate New York holding shelf-stable formulation expertise. Raw material dependencies center on premium Lactobacillus and Bifidobacterium strain deposits, enteric coating polymers, and USDA-certified organic dairy inputs. Single-source vulnerability from European strain bank licensing creates supply chain risk for domestic brands lacking captive deposits. Distribution runs through refrigerated last-mile networks for live culture products and ambient logistics for encapsulated formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postbiotic and synbiotic substitutes threaten incumbent positioning as consumers shift toward non-viable microbial derivatives with simpler supply chains and lower price points.
For Market Incumbents: Build refrigerated last-mile infrastructure moats through third-party logistics partnerships in Texas and Florida cold-chain gap markets. Accelerate self-affirmed GRAS submissions to preserve dietary supplement channel access against FDA biologic reclassification. Secure exclusive strain licensing arrangements with Japanese and European banks to defend margin position from royalty compression. For New Entrants and Emerging Players: Rural Texas and Florida markets lacking refrigerated distribution capacity offer underpenetrated white-space for shelf-stable powder and capsule formats. Pet nutrition veterinary channels remain underserved relative to human applications, permitting premium pricing capture. Partner with precision microbiome testing platforms to embed algorithmic strain matching into subscription customer acquisition. For Investors and Strategic Acquirers: FDA's pending live biotherapeutic product guidance reshapes the acquisition landscape by bifurcating target valuations between drug-classified and dietary supplement-positioned assets. Clinical-validation-focused biotherapeutic developers with completed Phase II endpoints offer long-term viability through the biologics pathway. Watch NIH microbiome research funding allocation shifts as signal for physician recommendation pattern inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Refrigerated last-mile acquisition in Texas and Florida unlocks live culture beverage distribution expansion. |
| Self-Affirmed GRAS Submission Acceleration | Preserved dietary supplement channel access defends against FDA biologic reclassification uncertainty. |
| Precision Microbiome Testing Integration | Algorithmic strain matching improves subscription retention among California and New York urban consumers. |
| Pediatric Nutrition Science Partnership | Infant-specific formulation validation anchors premium positioning in pharmacy and health store channels. |
| Pet Nutrition Veterinary Channel Entry | Companion animal microbiome products capture underserved premium pricing in professional veterinary settings. |
Research Methodology
A spread of perspectives from probiotic product development executives, regulatory affairs specialists at FDA-focused firms, refrigerated supply chain logistics directors, and direct-to-consumer wellness brand operators converged on the working assumptions. Secondary validation drew from FDA live biotherapeutic product guidance documents, NIH microbiome research database citations, USDA organic certification records, and retail channel audit data. Bottom-up strain-level demand modeling and top-down category value triangulation anchored the analytical framework.
Demand-supply-balance modeling across the projection horizon integrated dietary supplement versus functional food application splits, cold-chain versus shelf-stable delivery format economics, and online retail versus supermarket channel dynamics. CAGRs derived from segment-level growth rate reconciliation with macroeconomic health expenditure trends. Strain-specific clinical validation timelines and FDA classification pathway probabilities served as key forecast inputs.
Practitioners should monitor FDA live biotherapeutic product guidance finalization, NIH microbiome research funding allocations, and refrigerated logistics infrastructure investment announcements for early signals. Forecasts reflect assumptions about regulatory classification stability and cold-chain expansion rates. Quarterly review of physician recommendation pattern surveys and strain licensing fee trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
United States Feed Probiotics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market