
 Asia-Pacific Probiotics Market | 2026-2036
Asia-Pacific Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Probiotics Market Analysis
Subscription-based replenishment programs is rebalancing how probiotics reach households across the Asia-Pacific, converting one-time buyers into recurring revenue streams. Yakult Honsha Co., Ltd. leverages its home-delivery network to sustain daily consumption habits in Japanese and Korean urban centers. Danone S.A. competes through pharmacy partnerships that anchor clinical credibility for its adult-targeted formulations. Chr. Hansen Holding A/S differentiates by supplying strain libraries to regional contract manufacturers, controlling upstream ingredient quality.
Asia-Pacific probiotics comprise live microbial cultures, typically Lactobacillus and Bifidobacterium species at minimum viable counts of 10^6 to 10^9 CFU per serving, manufactured through controlled fermentation, freeze-drying, and microencapsulation to ensure gastric survival and shelf stability; these organisms colonize the human gut microbiome to modulate immune response, enhance nutrient absorption, and inhibit pathogenic growth. Functional foods and beverages occupy the largest margin pool due to their integration into daily dietary routines, while dietary supplements in capsule and powder forms represent the fastest-growing form category as athletes and seniors seek targeted strain combinations. Online retail channels now capture the most dynamic volume growth, though pharmacies retain higher trust premiums for infant and senior end users.
Australia's TGA, Japan's Ministry of Health Labour and Welfare under FOSHU, and India's FSSAI collectively enforce strain-specific safety documentation, label claim substantiation, and manufacturing facility audits that determine which products secure market authorization. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established dossiers and local regulatory expertise. Stakeholders must monitor evolving strain-level approval pathways and channel-specific positioning requirements as consumer sophistication and enforcement stringency both intensify.
Market Dynamics
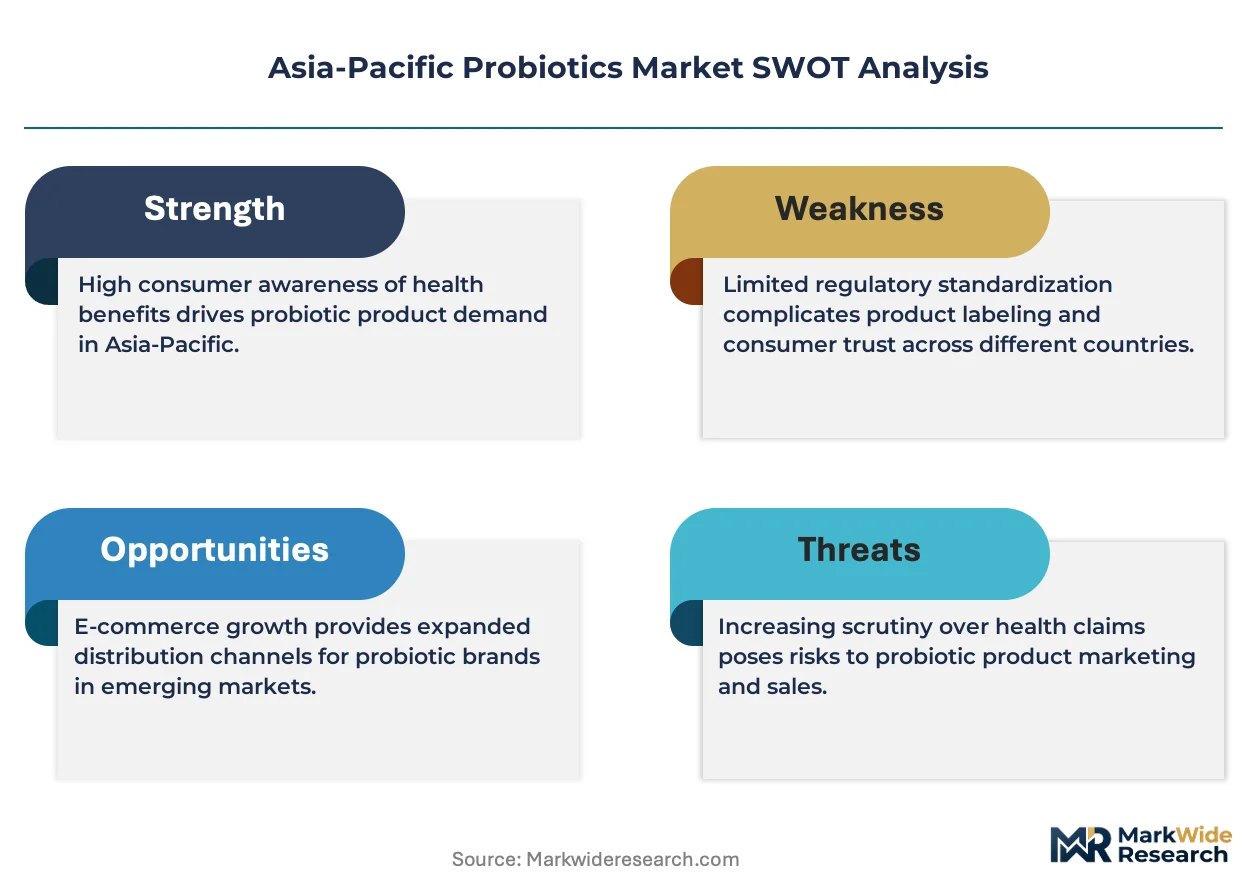
Japan's FOSHU regulatory framework is accelerating strain-level substantiation requirements across the Asia-Pacific, forcing manufacturers to rebuild dossiers around clinically validated endpoints rather than generic health claims. This structural shift elevates compliance costs while rewarding incumbents with established biobanks and local regulatory expertise.
Growth Catalysts
- Strain-Specific Approval Pathways:Japan's Ministry of Health Labour and Welfare under FOSHU and Australia's TGA now recognize documented immune and gut-health endpoints, creating authorized positioning for clinically validated formulations in pharmacy channels.
- Metropolitan Pharmacy Expansion:Tier-one Chinese cities and Indian metropolitan nutrition markets are anchoring probiotic distribution through pharmacy retail, where trust premiums for infant and senior end users sustain higher margin capture.
- Freeze-Drying and Microencapsulation:Controlled fermentation followed by advanced drying technologies is extending shelf stability and gastric survival rates, enabling functional food integration into daily dietary routines across temperature-variable supply chains.
Market Restraints
- Strain Library Concentration:Upstream control over characterized Lactobacillus and Bifidobacterium repositories concentrates among a limited set of European and North American suppliers, creating dependency risk for Asia-Pacific contract manufacturers.
- Temperature-Controlled Logistics Costs:Cold chain requirements for maintaining 10^6 to 10^9 CFU viability through last-mile delivery in tropical Southeast Asian climates impose structural cost premiums that compress mass-market penetration.
- Regulatory Fragmentation:Divergent strain approval timelines between Japan's PMDA, Australia's TGA, and India's FSSAI force parallel dossier development, duplicating compliance expenditure without harmonized mutual recognition.
Strategic Opportunities
- Subscription Replenishment Models:Daily consumption habits in Japanese and Korean urban centers support home-delivery network economics, converting one-time buyers into recurring revenue streams with predictable inventory planning.
- Senior Nutrition Formulations:India's aging demographic and China's pension system expansion create demand for targeted strain combinations addressing nutrient absorption and immune modulation in capsule and powder formats.
- Online Retail Channel Capture:E-commerce platforms are capturing the most dynamic volume growth across Chinese and Indian markets, enabling direct-to-consumer education that bypasses traditional pharmacy gatekeepers.
Industry Challenges
- Microbiome Scientist Scarcity:The intersection of fermentation engineering, clinical trial design, and regulatory dossier preparation requires specialized talent pools that remain concentrated in European and North American research clusters.
- Label Claim Substantiation Timelines:India's FSSAI and Australia's TGA both mandate facility audits and strain-specific safety documentation that extend product launch cycles by 18-36 months beyond formulation completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Probiotics Market |
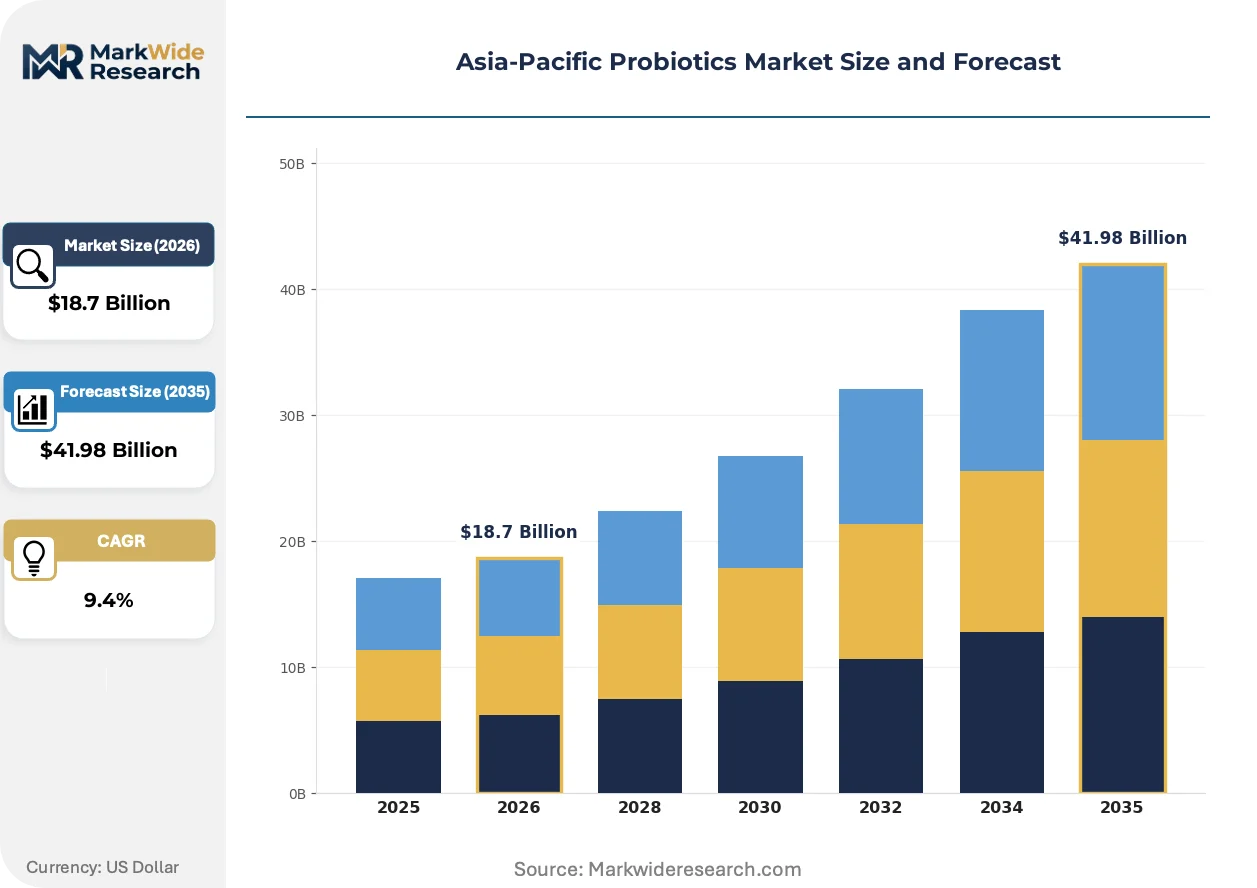
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Supplements, Dietary Supplements, Functional Foods, Beverages End User: Adults, Infants, Seniors, Athletes Form: Pills, Powders, Liquids, Capsules Sales Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Chr. Hansen Holding A/S, Probi AB, Yakult Honsha Co., Ltd., Morinaga Milk Industry Co., Ltd., DuPont Nutrition & Biosciences, Danone S.A., Kerry Group, Archer Daniels Midland Company, Nestlé S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Probiotics Market Emerging Trajectories
Microencapsulation technologies and direct-to-consumer distribution models are converging to reshape how live microbial cultures reach end users across diverse temperature and regulatory environments.
Advanced microencapsulation using alginate and protein-based coatings is protecting Lactobacillus and Bifidobacterium species through gastric transit, extending shelf stability without refrigeration. Functional food manufacturers in Thailand and Vietnam are adopting these materials at accelerating rates. This protection layer is decentralizing production location decisions, enabling fermentation facilities in non-traditional geographies previously excluded by cold chain limitations.
Japan's FOSHU framework is tightening evidentiary standards for gut-health and immune claims, requiring human intervention studies with defined biomarker endpoints. Manufacturers must now commission original clinical research rather than relying on published literature. Adult-targeted formulations seeking pharmacy positioning face the steepest compliance burden, with several applicants withdrawing generic claims rather than funding substantiation trials.
Chinese consumers are migrating from occasional supplement purchases toward habitual functional food integration, with yogurt and fermented beverages displacing capsules as the primary delivery format. This behavioral pivot favors domestic dairy processors with established cold chain networks over import-dependent supplement brands. Tier-two and tier-three cities are exhibiting the fastest consumption-pattern shift, though per-capita spending remains below Shanghai and Beijing benchmarks.
Asia-Pacific Probiotics Market Segmentation
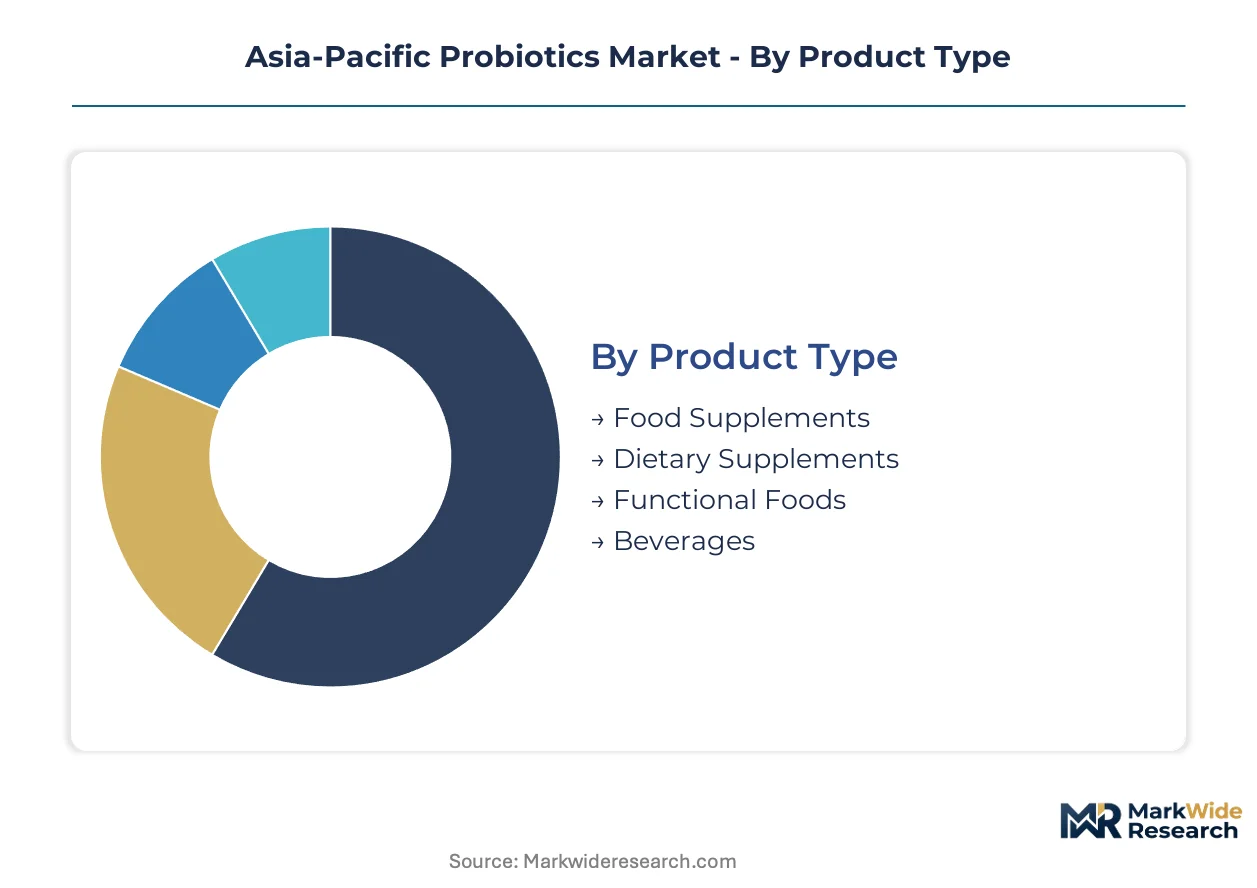
Asia-Pacific probiotics span multiple delivery formats and consumption contexts, each demanding distinct manufacturing capabilities, regulatory dossiers, and channel strategies. Segmentation reveals where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Customization intensity varies sharply across this category, from mass-market formulations requiring minimal strain documentation to clinically validated products demanding full FOSHU dossiers.
- Functional Foods:Fermented dairy, fortified snacks, and probiotic-enriched staples integrate live cultures at 10^6 to 10^9 CFU per serving through controlled fermentation. Japanese and Korean households sustain daily consumption via yogurt and fermented beverages, anchoring the largest margin pool through habitual purchase patterns.
- Dietary Supplements:Capsule and powder formats deliver targeted strain combinations with gastric survival claims. Athletes and seniors in China's tier-one cities and Indian metropolitan markets drive the steepest expansion trajectory as pharmacy channels credential clinical positioning.
- Food Supplements:Fortified conventional foods with lower viable counts serve price-sensitive entry segments across Southeast Asian mass retail.
- Beverages:Ready-to-drink fermented products leverage established cold chain networks in Thailand and Vietnam for on-the-go consumption occasions.
Leading the category by volume: Functional Foods. Growing fastest: Dietary Supplements.
End User:
Life-stage targeting determines strain selection, dosage precision, and channel placement across divergent trust and compliance requirements.
- Adults:Working-age consumers in Chinese urban centers seek digestive comfort and immune modulation through daily functional food integration. Subscription replenishment models capture recurring revenue as consumption shifts from occasional supplement use to habitual dietary inclusion.
- Seniors:Nutrient absorption and immune support formulations address India's aging demographic and China's pension system expansion. Pharmacy channels command premium positioning through clinical credibility and strain-specific substantiation under TGA and FOSHU frameworks.
- Infants:Colic and gut-development products require stringent safety documentation and pediatrician endorsement, concentrating demand in Japan and Australia's regulated pharmacy environments.
- Athletes:Performance-oriented strain combinations for recovery and gut integrity attract direct-to-consumer online purchases with education-heavy marketing.
Adult segments dominate current volume. Senior formulations are climbing the fastest as demographic shifts accelerate across China and India.
Form:
Manufacturing complexity and stability requirements create distinct competitive moats across physical delivery mechanisms.
- Capsules:Enteric-coated and microencapsulated formats protect Lactobacillus and Bifidobacterium through gastric transit, enabling shelf-stable distribution without refrigeration. Australian TGA listing requirements and Japan's FOSHU framework favor this format for clinical claims.
- Powders:Sachet and bulk formats allow flexible dosing and functional food integration, gaining traction in Indian and Chinese direct-to-consumer channels where mixing into beverages suits local consumption habits.
- Pills:Compressed tablet formats sacrifice some viability for convenience and portability, serving Southeast Asian markets with limited cold chain infrastructure.
- Liquids:Traditional fermented beverages and ready-to-drink shots depend on intact cold chains, concentrating production near consumption hubs in Japan and Korea.
Capsules lead pharmacy positioning by margin. Powders are expanding most quickly through e-commerce penetration.
Sales Channel:
Trust architecture and purchase frequency diverge sharply across physical and digital touchpoints, reshaping go-to-market economics.
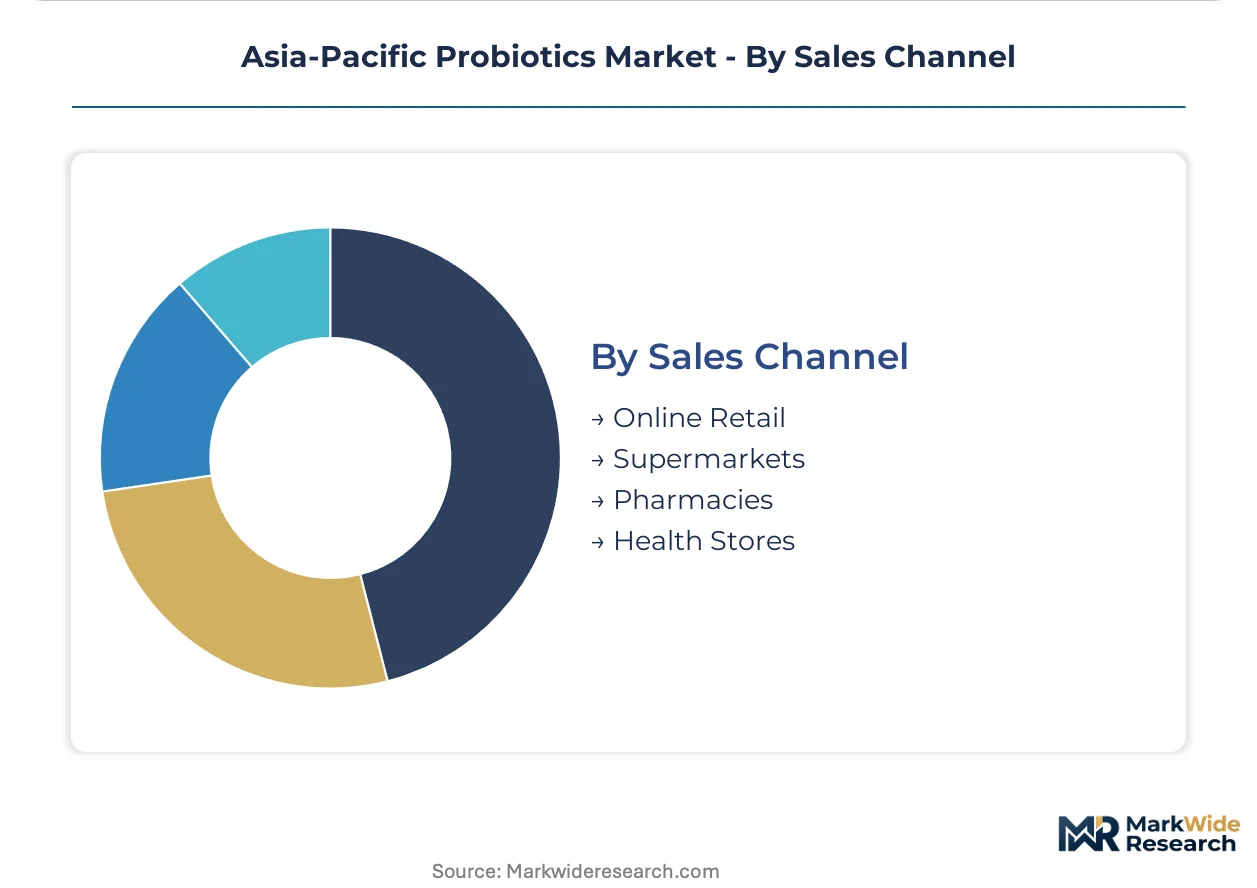
- Pharmacies:Clinical endorsement and strain-specific documentation under Japan's Ministry of Health Labour and Welfare and Australia's TGA sustain premium pricing for infant and senior formulations. Chinese tier-one city pharmacy expansion anchors trust-sensitive segments.
- Online Retail:Direct-to-consumer platforms bypass traditional gatekeepers, enabling education-intensive marketing for athlete and adult segments across Chinese and Indian markets. Dynamic volume growth concentrates here despite lower per-transaction trust premiums.
- Supermarkets:Mass-market functional foods and beverages leverage established FMCG distribution, with Japanese and Korean home-delivery networks sustaining daily consumption habits.
- Health Stores:Specialty retailers serve enthusiast segments seeking niche strain combinations, concentrated in Australian urban centers and Japanese metropolitan areas.
Pharmacies command the highest margin capture. Online retail channels are gaining share fastest as digital infrastructure matures across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors Asia-Pacific probiotic consumption through its dense pharmacy networks and subscription delivery infrastructure. Tier-one Chinese cities and Indian metropolitan nutrition markets concentrate demand growth. Regulatory frameworks in Japan, Australia, and India shape formulation standards and market access pathways across the region.
China
Pharmacy expansion in Beijing and Guangzhou drives clinical credibility for senior-targeted formulations. China's SAMR enforces strain-specific safety documentation and label claim substantiation for functional foods. Yangtze River Delta dairy processors integrate domestic fermentation capacity to displace import-dependent supplement brands.
Japan
Daily consumption habits sustain home-delivery economics for fermented beverages in Tokyo and Osaka metropolitan corridors. Japan's Ministry of Health Labour and Welfare under FOSHU mandates human intervention studies with defined biomarker endpoints. Kanto region biobanks supply characterized Lactobacillus repositories to regional contract manufacturers.
India
Aging demographics in Mumbai and Delhi-NCR create demand for nutrient absorption formulations in capsule and powder formats. India's FSSAI mandates facility audits and strain-specific safety documentation extending product launch cycles. Maharashtra and Gujarat pharmaceutical clusters develop pediatrician-endorsed infant gut-development products.
Australia
Metropolitan health stores in Sydney and Melbourne serve enthusiast segments seeking niche strain combinations. Australia's TGA listing requirements favor enteric-coated formats for clinical claims. Queensland fermentation facilities adopt microencapsulation technologies to extend shelf stability without refrigeration.
South Korea
Urban consumption patterns in Seoul Capital Area support subscription replenishment models for daily functional food integration. MFDS recognizes documented immune and gut-health endpoints for pharmacy channel positioning. Busan-Ulsan manufacturing corridors supply freeze-dried cultures to Southeast Asian markets.
Asia-Pacific Probiotics Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across Asia-Pacific probiotic supply chains. Strain library ownership concentrates among European and North American incumbents with established biobanks. Three archetypes dominate: upstream ingredient suppliers controlling fermentation capacity, consumer-facing brands anchoring pharmacy and home-delivery channels, and regional contract manufacturers assembling finished formulations. Competitive moves center on strategic partnerships for strain access and geographic expansion into tier-two Chinese cities.
Among upstream specialists, Chr. Hansen Holding A/S and Probi AB occupy positions as strain library custodians supplying regional fabricators. Yakult Honsha Co., Ltd. exemplifies the integrated brand model through its home-delivery network economics. These three represent distinct strategic postures: ingredient control, manufacturing scale, and direct consumer access.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Probi AB |
| Yakult Honsha Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| DuPont Nutrition & Biosciences |
| Danone S.A. |
| Kerry Group |
| Archer Daniels Midland Company |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Pharmacy procurement managers in China's tier-one cities and Indian metropolitan markets anchor the dominant value-based pricing model, where clinical credibility under TGA and FOSHU frameworks commands substantial premiums over mass-market functional foods. Subscription replenishment programs in Japanese and Korean urban centers convert daily consumption habits into predictable recurring revenue streams that insulate upstream suppliers from spot-price volatility.
Pricing Analysis
Clinical outcome pricing tied to immune and gut-health endpoints anchors the premium tier, with FOSHU-substantiated formulations capturing margin multiples above generic supplements. Price differentiation rests on certification grade under Japan's Ministry of Health Labour and Welfare and Australia's TGA versus economy-tier mass retail products. Cost compression in Southeast Asian mass markets is intensifying because tropical cold chain requirements impose structural viability premiums. Senior and infant end users in pharmacy channels exhibit the lowest price sensitivity, while price-conscious athletes and working-age adults in online retail drive volume at thinner margins.
Supply Chain Analysis
Refrigerated freight costs across Southeast Asian last-mile networks consume disproportionate working capital, forcing manufacturers to cluster production near consumption hubs. Supply concentration centers on Denmark and France for characterized Lactobacillus and Bifidobacterium strain libraries, Japan and South Korea for freeze-drying capacity, and China and India for regional fermentation scale. Raw material dependencies include specialized culture media, alginate microencapsulation coatings, and pharmaceutical-grade excipients. Single-source vulnerability in European strain repositories threatens regional contract manufacturers. Distribution runs through pharmacy partnerships in regulated markets and direct-to-consumer platforms in digital-first geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain library scarcity among Asia-Pacific contract manufacturers props pricing power for upstream suppliers with established biobanks, constraining finished-product margin expansion despite volume growth. Capacity bottlenecks in qualified fermentation facilities and regulatory dossier preparation talent sustain incumbent advantages.
For Market Incumbents: Deepen strain-level substantiation investments under FOSHU and TGA frameworks to fortify pharmacy channel positioning against emerging direct-to-consumer brands. Expand captive fermentation capacity in Busan-Ulsan and Queensland corridors to reduce dependency on European culture shipments. Prioritize microencapsulation technology licensing to Southeast Asian contract manufacturers seeking shelf-stable formulation capabilities. For New Entrants and Emerging Players: The mid-tier price gap between premium FOSHU-certified formulations and economy mass-market products offers white-space entry in Chinese tier-two cities and Indian secondary metros. Target athlete and working-age adult segments through education-intensive online retail where clinical credentialing requirements remain less stringent. Deploy powder sachet formats suited to local beverage-mixing consumption habits as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors regional contract manufacturers with established regulatory dossiers and local fermentation assets. Long-term viability hinges on backward integration into strain characterization capabilities or exclusive licensing arrangements with European biobanks. Watch for inflection signals in India's FSSAI approval timelines and China's SAMR enforcement patterns as indicators of regulatory barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Secures upstream control over characterized Lactobacillus repositories from Danish and French suppliers. |
| FOSHU Dossier Investment | Enables pharmacy channel positioning under Japan's Ministry of Health Labour and Welfare substantiation requirements. |
| Microencapsulation Licensing | Extends shelf stability without refrigeration across Thailand and Vietnam temperature-variable supply chains. |
| Subscription Platform Buildout | Converts one-time buyers into recurring revenue streams in Seoul Capital Area and Tokyo metropolitan corridors. |
| Tier-Two City Expansion | Captures consumption-pattern shifts in Chinese secondary markets below Shanghai and Beijing benchmarks. |
Methodological Framework
Multi-period observation of strain approval timelines, pharmacy channel expansion rates, and subscription program adoption anchored the trend analysis, supplemented by interviews with fermentation engineering directors, regulatory affairs leads at probiotic manufacturers, pharmacy procurement managers in Chinese tier-one cities, and pediatric nutrition specialists. Secondary validation drew from FOSHU submission databases, TGA listing records, FSSAI facility audit disclosures, and customs import data for live culture shipments. Bottom-up volume modeling across product types, end-user segments, and sales channels triangulated against top-down market sizing from regional dairy processor capacity disclosures.
Input-output matrices mapped fermentation capacity, cold chain infrastructure density, and regulatory approval probabilities across the projection horizon. Segmentation dimensions modeled included product type, end-user life stage, physical form, and channel architecture, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from fitted growth curves incorporating demographic aging trajectories, pharmacy network expansion plans, and e-commerce penetration rates. Strain-level substantiation investment cycles and microencapsulation technology adoption curves served as industry-specific forecast inputs.
Inputs from regulatory filing databases and pharmaceutical cluster development plans were available through the study window; gaps in real-time subscription program churn data and contract manufacturing capacity utilization introduce uncertainty bands around channel shift assumptions. Forecasts reflect documented assumptions about FOSHU evidentiary standard stability and cold chain cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Women Probiotic Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Infant and Kids Probiotics Market