
 Psychobiotic Supplements Market | 2026-2036
Psychobiotic Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Psychobiotic Supplements Market Analytics
The EU Nutrition and Health Claims Regulation is consolidating credibility thresholds for live culture supplements across European markets. Lallemand Health Solutions leverages its Montreal-based strain library to anchor North American supply. Novonesis competes through its Danish fermentation heritage and human clinical trial infrastructure. Probi AB specializes in Nordic-origin Lactobacillus strains for mood-targeted formulations.
Psychobiotic supplements contain live microorganisms or microbial substrates that modulate the gut-brain axis through vagus nerve signaling, neurotransmitter precursor synthesis, and short-chain fatty acid production, typically delivered at minimum viable counts exceeding one billion CFU per serving. Probiotics dominate current revenue as established strain portfolios command premium positioning, while synbiotics represent the fastest-expanding category as formulators combine targeted probiotics with precision prebiotic fibers to enhance colonization efficacy. Gummies are gaining share among younger demographics seeking palatable alternatives to pills, though powders retain margin strength in clinical and wellness center channels where dosing flexibility matters.
FDA oversight of dietary supplement Good Manufacturing Practices and EFSA health claim authorization processes shape market access thresholds, with both agencies scrutinishing live count stability and strain identity verification. Japan's Consumer Affairs Agency and FOSHU framework provide additional regulatory benchmarks for cognitive and mood benefit substantiation. Stakeholders must monitor evolving strain-specific clinical evidence requirements that will determine which formulations retain shelf positioning as substantiation standards tighten.
Market Dynamics
Strain-specific clinical substantiation requirements from EFSA and FDA are compressing formulation portfolios as manufacturers face escalating evidence thresholds for shelf positioning. This regulatory tightening is filtering out unsupported SKUs while rewarding suppliers with human trial infrastructure.
Growth Catalysts
- EFSA Health Claim Authorization:The EU's consolidated credibility thresholds for live culture supplements are consolidating market share among validated suppliers. Wellness centers across Germany and France now require documented strain efficacy for protocol inclusion.
- Vagus Nerve Research Funding:Expanded government-backed gut-brain axis studies in Japan and the United States are generating clinical endpoints that manufacturers can reference for consumer education and practitioner outreach.
- Synbiotic Formulation Advances:Precision prebiotic-probiotic combinations are improving colonization rates in mood-targeted applications, opening new prescription-adjacent channels where efficacy documentation matters more than price.
Market Restraints
- Live Culture Stability Costs:Cold chain requirements for CFU preservation through shelf life add 15-25% to finished goods logistics versus standard supplements, compressing margins in mass retail channels.
- Strain Library Concentration:Proprietary Lactobacillus and Bifidobacterium deposits remain concentrated among three North American and European culture houses, creating supply vulnerability for independent formulators.
- Placebo Response Variability:High baseline variability in subjective mood endpoints complicates trial design and inflates study costs beyond what mid-tier manufacturers can sustain.
Strategic Opportunities
- FOSHU Framework Alignment:Japan's regulatory pathway for Foods for Specified Health Uses offers a template for cognitive benefit claims that other Asian markets are adopting, creating first-mover positioning for compliant suppliers.
- Direct-to-Practitioner Channels:Functional medicine clinics and integrative psychiatry practices represent underpenetrated distribution where clinical data resonates more than consumer marketing spend.
- Postbiotic Ingredient Pivot:Heat-inactivated microbial substrates and fermentation-derived metabolites bypass live count stability challenges while retaining gut-brain signaling properties, opening formulation flexibility.
Industry Challenges
- Microbiome Analytical Talent Scarcity:Shortage of professionals trained in both bioinformatics and nutritional science slows R&D pipeline velocity and inflates compensation costs for specialized roles.
- Cross-Border Labeling Fragmentation:Divergent strain nomenclature requirements between FDA, EFSA, and Japan's Consumer Affairs Agency force SKU proliferation and inventory complexity for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psychobiotic Supplements Market |
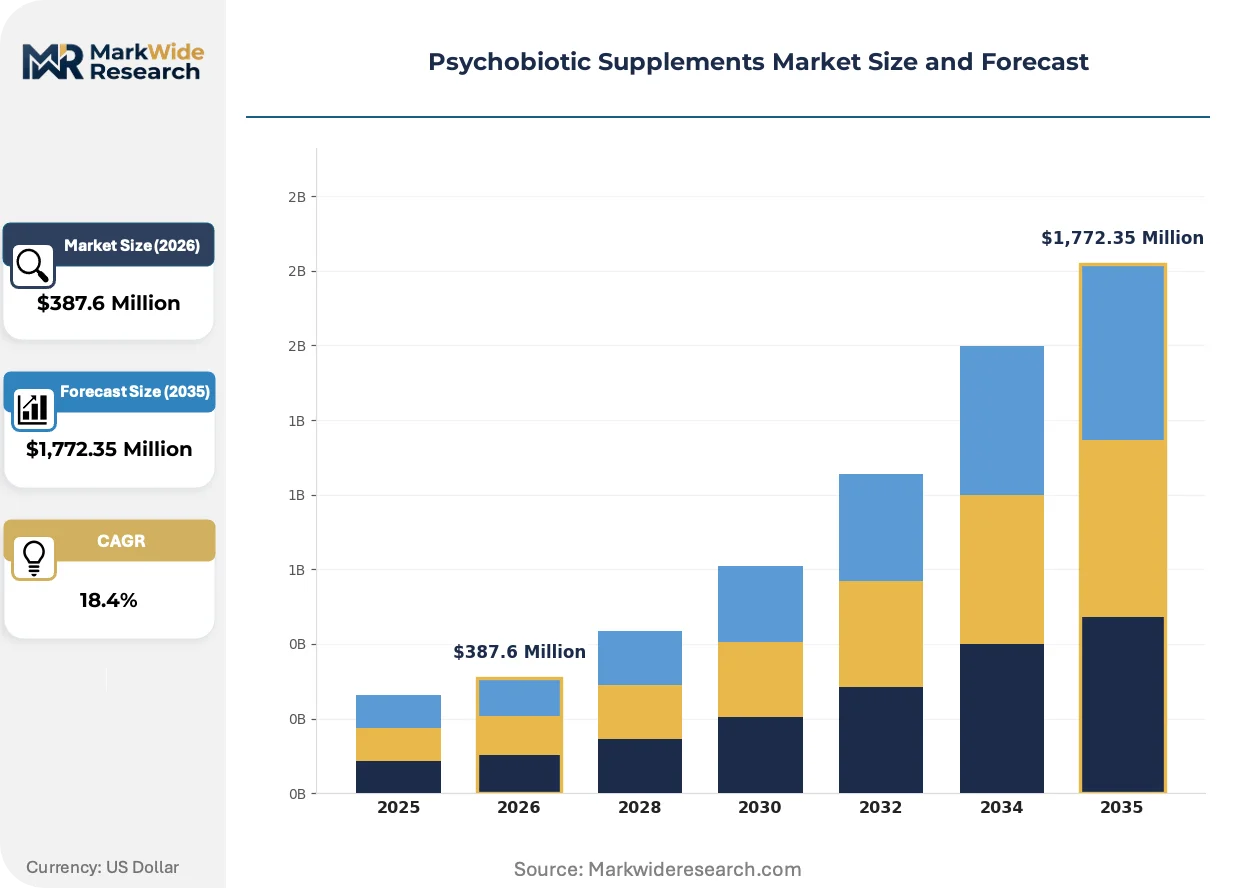
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Fermented Foods Application: Mood Enhancement, Anxiety Reduction, Stress Relief, Cognitive Function Delivery Mode: Pills, Powders, Gummies, Liquids End User: Individual Consumers, Healthcare Providers, Wellness Centers, Pharmacies |
| Companies Covered | Lallemand Health Solutions, Bened Biomedical Co., Ltd., Life Extension, Lifted Naturals, ADM (Archer Daniels Midland), Novonesis (Chr. Hansen Holding A/S), Probi AB, Optibac Probiotics, Microbiome Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psychobiotic Supplements Market Evolving Landscape
Delivery format innovation and regulatory science investments are bifurcating competitive position between clinical-grade suppliers and consumer-facing brands. Technology convergence is compressing development cycles while raising evidence bars.
Microencapsulation technologies using alginate and lipid matrices are modularizing probiotic protection against gastric acid and moisture exposure. Gummy and soft-chew manufacturers in the United States and Germany are adopting these systems to achieve viable counts without refrigeration, enabling shelf placement in conventional supplement aisles previously closed to live cultures.
EFSA's 2023-2024 guidance consolidation on live culture health claims is forcing reformulation toward strains with existing positive opinions. Manufacturers serving European markets are retiring unsupported SKUs and redirecting R&D budgets toward human intervention studies rather than mechanistic or in-vitro evidence packages.
Subscription-based replenishment models are displacing one-time retail purchases among millennial and Gen-Z demographics seeking continuity in stress management protocols. Direct-to-consumer platforms in California and Tokyo are bundling microbiome testing with personalized psychobiotic regimens, capturing lifetime value through data-driven retention rather than transaction margin.
Psychobiotic Supplements Market Segmentation
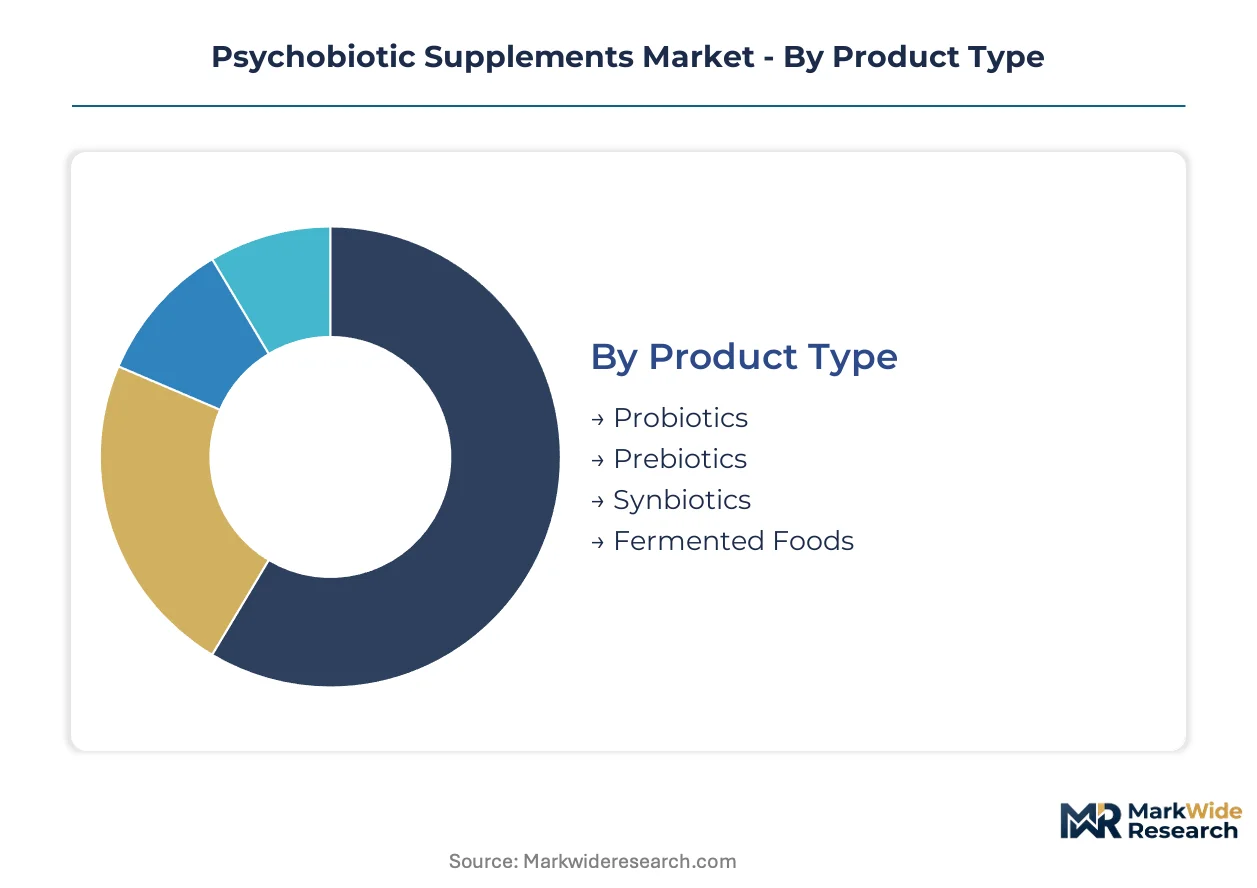
Psychobiotic supplements segment across multiple functional dimensions that determine formulation priorities, regulatory pathways, and channel economics. Each category reflects distinct technical requirements and end-user expectations that shape supplier R&D allocation and commercial positioning.
Product Type:
Integration depth varies sharply across this category, with standalone live cultures dominating current revenue while embedded multi-ingredient systems capture emerging demand.
- Probiotics:Live microbial strains delivered at minimum one billion CFU per serving, typically Lactobacillus and Bifidobacterium species with documented gut-brain axis activity. Demand concentrates in clinical and wellness center channels across the United States and Germany where strain-specific substantiation requirements from FDA and EFSA filter out unsupported formulations.
- Synbiotics:Precision combinations of targeted probiotics with prebiotic fibers designed to enhance colonization efficacy in mood-targeted applications. These embedded systems are expanding most quickly as formulators combine live cultures with resistant starches and oligosaccharides to improve survival through gastric transit and accelerate short-chain fatty acid production.
- Prebiotics:Non-digestible substrates that selectively nourish beneficial gut microbiota, including inulin, fructooligosaccharides, and galactooligosaccharides.
- Fermented Foods:Traditional and novel food matrices delivering psychobiotic benefits through live cultures in kefir, kimchi, kombucha, and specialized yogurt formats.
Probiotics lead volumes today; synbiotics are gaining share fastest.
Application:
Cost tier differentiation separates premium clinical-grade formulations from mass-market positioning, with substantiation depth determining pricing power.
- Mood Enhancement:Formulations targeting depressive symptom reduction and emotional regulation through serotonin precursor synthesis and vagus nerve modulation. These command premium pricing in direct-to-practitioner channels where clinical data outweighs consumer marketing spend.
- Stress Relief:Products addressing cortisol regulation and HPA axis modulation, often bundled with adaptogenic ingredients. Demand concentrates in subscription-based replenishment models among millennial demographics in California and Tokyo seeking continuity in stress management protocols.
- Anxiety Reduction:Strains selected for GABA receptor interaction and anxiolytic signaling pathways, requiring precise dosing documentation.
- Cognitive Function:Formulations targeting memory, attention, and executive function through microbiome-metabolite-brain pathways, with Japan's FOSHU framework providing regulatory templates for cognitive benefit claims.
Mood enhancement leads volumes today; stress relief is climbing the fastest.
Delivery Mode:
Customer type segmentation separates clinical flexibility requirements from palatability-driven consumer preferences, with format choice determining shelf placement and margin structure.
- Pills:Standard capsules and tablets with enteric coatings protecting live cultures from gastric acid exposure. These dominate pharmacy and healthcare provider channels where dosing precision and portability matter most.
- Gummies:Palatable soft-chew formats incorporating microencapsulation technologies using alginate and lipid matrices to achieve viable counts without refrigeration. Younger demographics in the United States and Germany are displacing one-time retail purchases with these formats in conventional supplement aisles.
- Powders:Dosing-flexible formats retaining margin strength in clinical and wellness center channels where practitioners customize serving sizes.
- Liquids:Ready-to-drink formulations and drops, often targeting pediatric or geriatric populations with swallowing difficulties.
Pills lead volumes today; gummies are expanding most quickly.
End User:
Maturity stage separates established consumer retail from emerging professional channels, with evidence requirements determining market access thresholds.
- Individual Consumers:Direct purchasers through retail, e-commerce, and subscription platforms seeking self-directed stress and mood management. This segment drives volume in mass-market channels where palatability and price sensitivity dominate purchase decisions.
- Healthcare Providers:Functional medicine clinics and integrative psychiatry practices requiring documented strain efficacy for protocol inclusion. These underpenetrated channels represent high-margin opportunities where clinical data resonates more than consumer marketing expenditure.
- Wellness Centers:Spas, retreats, and corporate wellness programs across North America and Europe expanding psychobiotic programming for stress management protocols.
- Pharmacies:Retail and clinical pharmacy channels where pharmacist recommendation influences selection and regulatory compliance requirements are most stringent.
Individual consumers lead volumes today; healthcare providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psychobiotic supplements trace their commercial origins to early 2000s academic research in Japan and subsequent strain development programs in Denmark and Canada. These foundational efforts established the clinical validation frameworks now governing market access across major jurisdictions.
United States
Functional medicine clinics in California and New York Metro drive practitioner-channel demand for documented strain efficacy. FDA's dietary supplement Good Manufacturing Practices enforcement shapes cold chain logistics and live count stability standards. Greater Boston hosts microbiome research clusters translating vagus nerve studies into commercial endpoints.
Germany
Wellness centers in Bavaria and North Rhine-Westphalia require EFSA-compliant substantiation for stress management protocol inclusion. EFSA health claim authorization processes filter unsupported SKUs from pharmacy shelves. Frankfurt's fermentation technology corridor supplies precision prebiotic-probiotic combinations to European formulators.
Japan
Consumer Affairs Agency FOSHU framework anchors cognitive benefit claim templates adopted across Asian markets. METI-funded gut-brain axis research generates clinical endpoints manufacturers reference for mood-targeted formulations. Tokyo's direct-to-consumer platforms bundle microbiome testing with personalized psychobiotic regimens.
Canada
Health Canada oversight of natural health products shapes strain identity verification requirements for cross-border suppliers. Montreal-based culture houses leverage proximity to U.S. distribution networks while maintaining distinct regulatory compliance protocols. Ontario's integrative psychiatry practices represent underpenetrated high-margin channels.
United Kingdom
London's subscription wellness platforms displace one-time retail purchases among millennial demographics seeking continuity in stress management. MHRA alignment with EFSA credibility thresholds consolidates market share among validated European suppliers. Cambridge bioinformatics clusters address microbiome analytical talent scarcity slowing R&D velocity elsewhere.
Psychobiotic Supplements Market Competitive Landscape
Capital-heavy fermentation specialists compete with asset-light formulation brands for shelf positioning and practitioner mindshare. Three North American and European culture houses control proprietary Lactobacillus and Bifidobacterium deposits, creating supply concentration that independent formulators navigate through strategic partnerships. Tiered competitive archetypes separate clinical-grade suppliers with human trial infrastructure from consumer-facing brands prioritizing palatability innovation. Dominant competitive moves include EFSA-guided SKU rationalization and direct-to-practitioner channel expansion.
Within the strain-library tier, Lallemand Health Solutions anchors North American supply through its Montreal-based culture collection, while Novonesis occupies a position leveraging Danish fermentation heritage. Probi AB exemplifies Nordic-origin specialization for mood-targeted applications. These entities represent the evidence-generation infrastructure filtering market access as regulatory substantiation requirements tighten.
| Leading Market Players |
|---|
| Lallemand Health Solutions |
| Bened Biomedical Co., Ltd. |
| Life Extension |
| Lifted Naturals |
| ADM (Archer Daniels Midland) |
| Novonesis (Chr. Hansen Holding A/S) |
| Probi AB |
| Optibac Probiotics |
| Microbiome Labs |
| Others |
Value Network & Pricing Analysis
EFSA's consolidated credibility thresholds for live culture health claims gate qualified supply and premium-tier pricing access, as manufacturers without human trial infrastructure face SKU rationalization while validated suppliers command clinical-grade positioning in wellness center and pharmacy channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade formulations with documented strain efficacy from mass-market alternatives. Price differentiation hinges on EFSA/FDA authorization status and cold chain certification tier. Pricing pressure stems from live culture stability costs compressing margins in mass retail. Individual consumers in subscription channels exhibit lowest price sensitivity; independent formulators sourcing from culture houses face highest.
Supply Chain Analysis
Strain library certification and EFSA positive opinion status gate supplier qualification, filtering independent formulators toward strategic partnerships. Proprietary Lactobacillus and Bifidobacterium deposits concentrate in Denmark, Canada, and Sweden. Raw material dependencies span fermentation media, cryoprotectants, and precision prebiotic fibers. Single-source vulnerability from three dominant culture houses creates supply risk. Distribution runs through direct-to-practitioner channels, wellness center protocols, and pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as demand shifts toward premium formulations with EFSA-authorized strain substantiation, rewarding suppliers with human clinical trial infrastructure and filtering out unsupported SKUs.
For Market Incumbents: Cement market position by deepening backward integration into proprietary strain libraries and expanding direct-to-practitioner channel control. Threats from synbiotic formulation specialists with precision prebiotic capabilities require defensive R&D investment in colonization efficacy documentation. EFSA-guided SKU rationalization is the critical lever for shelf positioning retention.
For New Entrants and Emerging Players: Functional medicine clinics represent the most penetrable channel partner type for white-space entry, given underpenetration relative to consumer retail saturation. Target stress relief applications in subscription-based models among millennial demographics. Go-to-market angle: bundle microbiome testing with personalized regimens to capture lifetime value through data-driven retention.
For Investors and Strategic Acquirers: Roll-up economics work for fermentation specialists with human trial infrastructure because regulatory substantiation requirements are compressing formulation portfolios toward validated suppliers. Long-term viability favors clinical-grade suppliers over palatability-focused consumer brands. Signal to watch: EFSA positive opinion issuance rates as inflection indicator for shelf positioning consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Authorization Investment | Human clinical trial infrastructure filters market access as credibility thresholds tighten across European markets. |
| Synbiotic Formulation Development | Precision prebiotic-probiotic combinations improve colonization rates and open prescription-adjacent channels. |
| Direct-to-Practitioner Channel Expansion | Functional medicine clinics and integrative psychiatry practices represent high-margin underpenetrated distribution. |
| Postbiotic Ingredient Pivot | Heat-inactivated microbial substrates bypass live count stability challenges while retaining gut-brain signaling properties. |
| Microbiome Testing Bundle Launch | Direct-to-consumer platforms in California and Tokyo capture lifetime value through data-driven personalization. |
Research Methodology
Multiple input streams — primary interviews with fermentation technologists, regulatory affairs specialists, and wellness center protocol directors; secondary validation through EFSA guidance documents, FDA GMP enforcement records, and FOSHU registration databases; plus customs trade data on live culture imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, delivery mode, and end-user dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectories anchored to EFSA authorization timelines and vagus nerve research funding patterns. Industry-specific forecast inputs included strain-specific clinical trial publication rates and wellness center protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA health claim authorization delays and cold chain logistics cost trajectories. A model refresh is warranted upon material change in regulatory substantiation standards or culture house supply consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Anti-Diarrheal Supplements Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market