
 United Arab Emirates Transformer Market | 2026-2036
United Arab Emirates Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Transformer Market Analytics
Modular substation bundling is expanding across UAE utility procurement, letting buyers configure transformer-switchgear combinations rather than sourcing discrete units. Eurogulf Transformer FZE leverages its Fujairah manufacturing footprint to anchor regional delivery timelines for oil-immersed units. Schneider Electric differentiates through digital monitoring integration in its dry-type portfolio. ABB Ltd sustains technology leadership in gas-insulated transformer designs for space-constrained offshore installations.
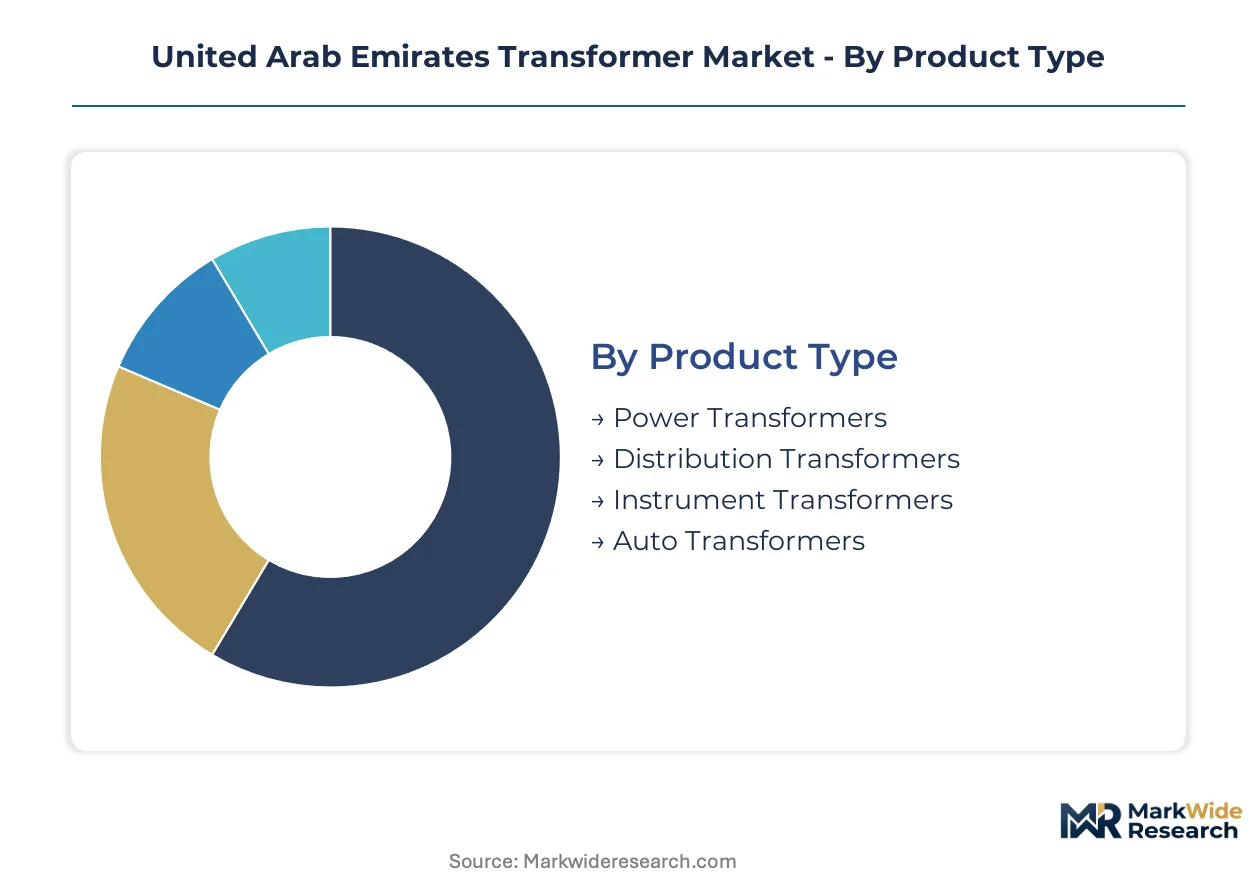
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 Hz or 60 Hz with voltage ratings spanning 11 kV to 400 kV in utility applications. Its core function is to step up voltage for efficient long-distance transmission or step down voltage for safe distribution to end-use equipment. Power transformers command the largest revenue share due to grid expansion and renewable integration projects across the Emirates. Distribution transformers represent the fastest-growing category as smart city deployments and district cooling networks multiply secondary substations. Dry-type technology is gaining share in commercial and residential installations where fire safety and indoor placement restrictions limit oil-immersed alternatives.
MOHAP enforces electrical equipment safety standards that mandate third-party certification for transformers installed in healthcare and public infrastructure projects. SEBI's infrastructure investment guidelines indirectly channel capital toward power sector assets including transmission and distribution equipment. The Emirates Authority for Standardization and Metrology (ESMA) administers ECAS conformity schemes that control market access for imported transformer units. Stakeholders must monitor evolving efficiency tier requirements and localization incentives as federal industrial strategy tightens supply chain criteria for critical electrical infrastructure.
Market Dynamics
Modular substation bundling is compressing procurement cycles across UAE utilities, forcing transformer manufacturers to integrate switchgear capabilities or cede share to packaged solution providers.
Growth Catalysts
- Al Dhafra Solar Park expansion:Utility-scale photovoltaic clusters in Abu Dhabi are procuring high-capacity power transformers for grid interconnection, creating sustained demand for 400 kV class units.
- ESMA ECAS conformity enforcement:The Emirates Authority for Standardization and Metrology's tightened import certification is filtering low-efficiency units and elevating procurement standards for grid-connected assets.
- Dry-type technology migration:Fire safety codes in Dubai's high-rise commercial districts are displacing oil-immersed alternatives in indoor substations, expanding addressable market for cast-resin designs.
Market Restraints
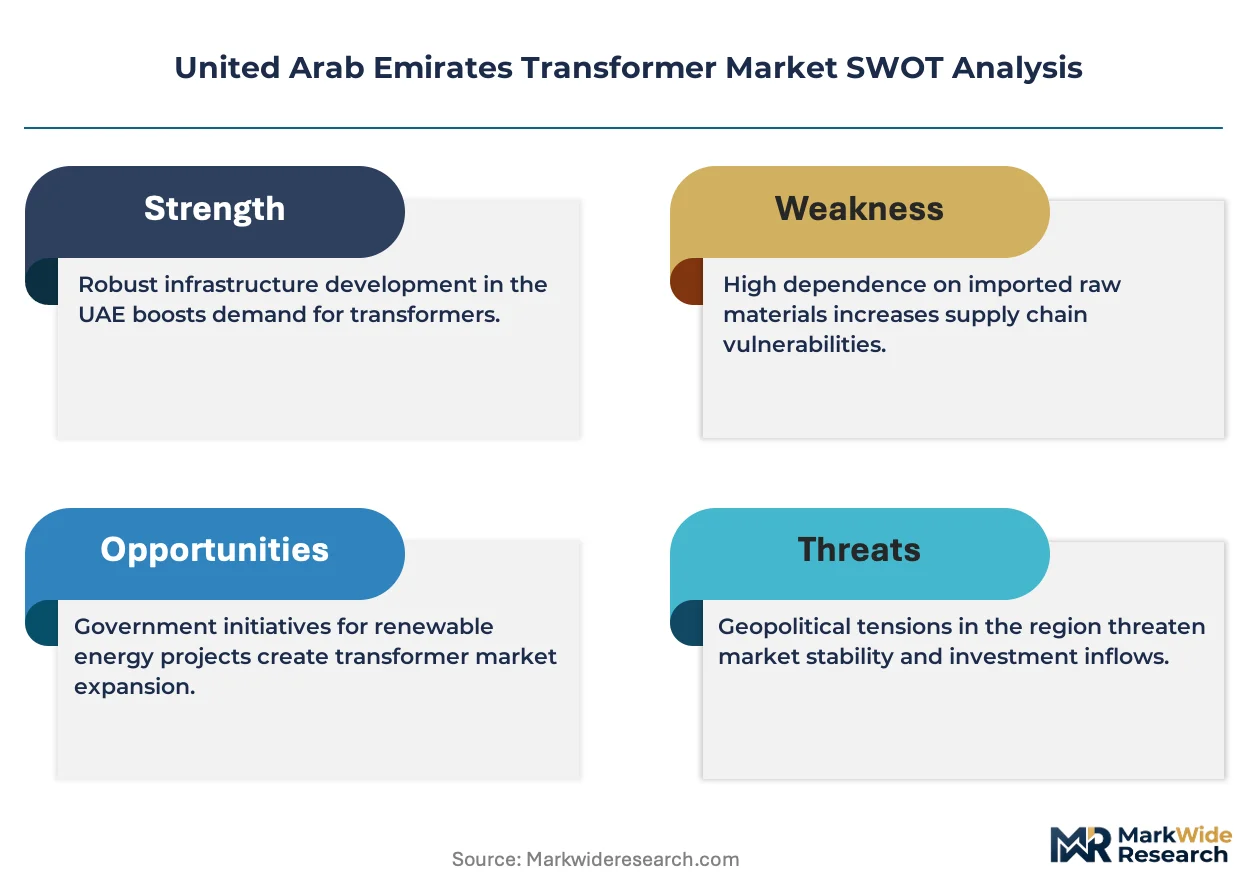
- Grain-oriented electrical steel concentration:Core material supply concentrates among Japanese and European mills, exposing UAE manufacturers to input cost volatility and currency fluctuation risk.
- MOHAP certification timeline:Healthcare infrastructure projects face 14-18 week approval cycles for transformer installations, compressing project delivery windows and elevating working capital requirements.
- Gas-insulated transformer cost premium:Space-constrained offshore oil platforms require SF6-based designs that command 2.5-3x pricing versus conventional alternatives, limiting addressable volume.
Strategic Opportunities
- Ras Al Khaimah industrial zone electrification:New manufacturing clusters outside Abu Dhabi and Dubai present underpenetrated demand for medium-voltage distribution transformers.
- Digital twin integration:Convergence of transformer monitoring hardware with predictive analytics platforms creates recurring revenue streams from asset performance management contracts.
- NEOM cross-border linkage:Saudi Arabia's giga-project transmission interconnection with UAE grid infrastructure will require specialized high-voltage converter transformers.
Industry Challenges
- Specialized winding technician scarcity:Precision coil manufacturing for 400 kV units requires skills concentrated among aging European and Japanese workforces, constraining local production scaling.
- Legacy SCADA integration complexity:Smart transformer deployments must interface with decades-old distribution management systems in Dubai DEWA and Abu Dhabi TAQA networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Transformer Market |
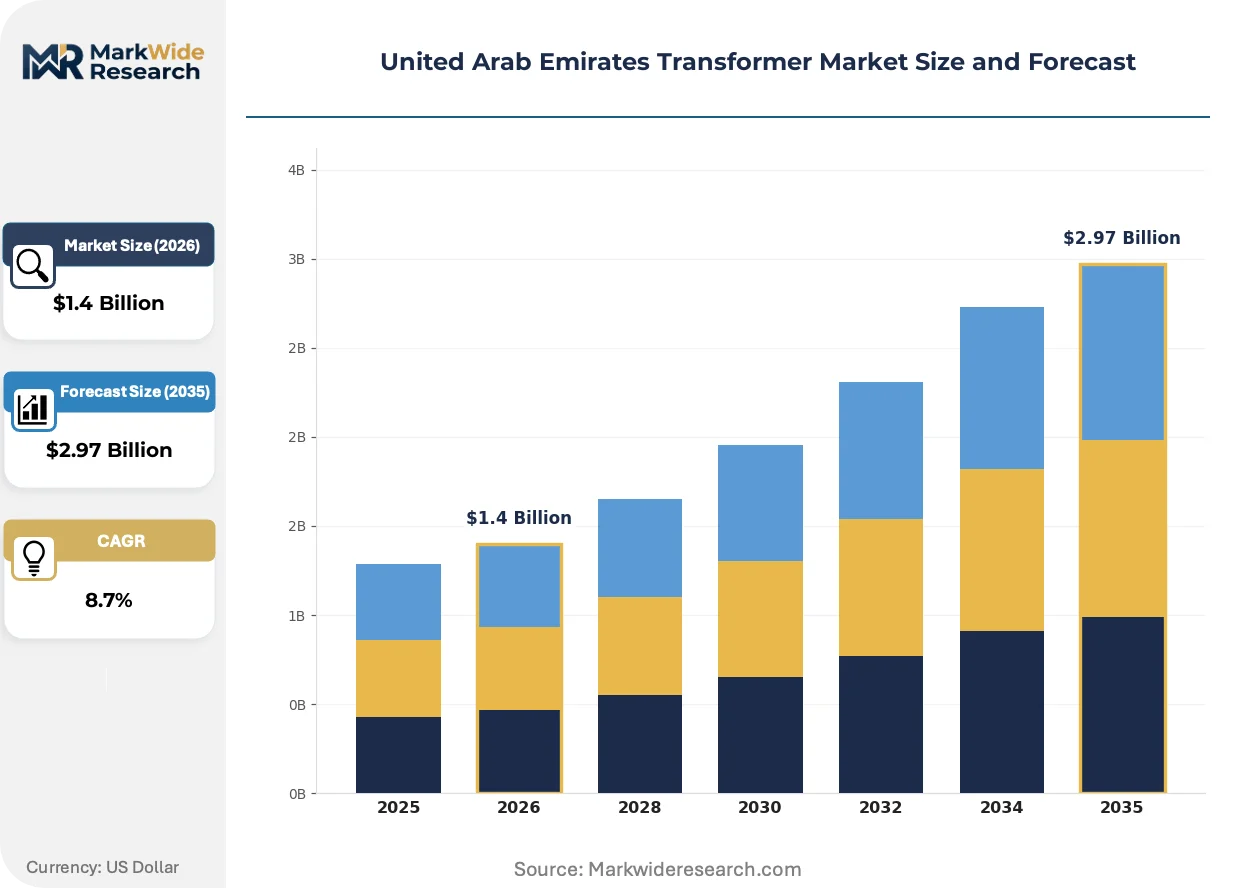
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformers, Distribution Transformers, Instrument Transformers, Auto Transformers End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offshore, Substation, Mobile Technology: Dry-Type, Oil-Immersed, Gas-Insulated, Others |
| Companies Covered | Eurogulf Transformer FZE, ABB Ltd, Emirates Transformer & Switchgear Ltd. (ETS), Schneider Electric, Siemens AG, Gulf Transformers Co. LLC (GTC), Federal Power Transformers LLC, General Electric Company, Crux Transformers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Transformer Market Evolving Landscape
Transformer architecture is fragmenting into configurable subsystems, with digital monitoring layers becoming standard rather than premium specifications across UAE procurement.
Plug-and-play modular substation designs are modularizing field deployment for Dubai's district cooling networks and commercial developments. Developers are specifying pre-tested transformer-switchgear skids that slash commissioning time from weeks to days. This modularity is compressing vendor margins on discrete component sales while expanding system integration revenue pools.
MOHAP's updated electrical equipment safety standards are mandating third-party witnessed testing for all healthcare facility transformers. The regulation is elevating documentation burdens and extending pre-delivery lead times. Manufacturers are responding by pre-certifying product families and maintaining UAE-based testing partnerships.
Long-term service agreements are displacing transactional spare parts sales among Abu Dhabi industrial buyers. Asset owners are contracting 15-year performance guarantees covering oil analysis, tap-changer maintenance, and emergency replacement. This shift is most visible in downstream oil and gas facilities where unplanned outage costs exceed equipment replacement value.
United Arab Emirates Transformer Market Segmentation
Transformer procurement across the Emirates fragments sharply by application environment and technical specification. Buyers configure voltage ratings, cooling methods, and enclosure standards against site-specific constraints ranging from Dubai high-rise basements to offshore oil platforms.
Product Type:
Capital intensity and replacement cycles separate procurement behavior across transformer classes.
- Power Transformers:High-voltage units rated 100 MVA and above handle bulk transmission interconnection for utility-scale solar parks and grid backbone reinforcement. Abu Dhabi's Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park expansions are procuring 400 kV class units with forced oil-directed air cooling systems.
- Distribution Transformers:Medium-voltage step-down units from 11 kV to 33 kV feed secondary substations across Dubai's district cooling networks and Sharjah industrial corridors. Smart city deployments are multiplying pad-mounted and vault-style installations in dense commercial districts.
- Instrument Transformers:Current and voltage sensing devices provide metering and protection inputs for SCADA integration in DEWA and TAQA distribution networks.
- Auto Transformers:Single-winding voltage conversion units serve limited applications where electrical isolation is not required, primarily in railway electrification studies for Etihad Rail expansion phases.
Power transformers dominate installed value today; distribution transformers are climbing the fastest as secondary substation deployment accelerates.
End User:
Procurement sophistication and maintenance contracting terms diverge sharply by buyer sophistication and outage cost exposure.
- Utilities:DEWA, TAQA, and Emirates Water and Electricity Company specify fully monitored assets with 30-year design lives and integrated digital condition monitoring. Bulk procurement frameworks favor manufacturers with local testing partnerships and ECAS pre-certification.
- Industrial:Downstream oil and gas facilities in Ruwais and Jebel Ali contract 15-year performance guarantees covering predictive maintenance and emergency replacement. Unplanned outage costs exceeding equipment replacement value drive premium specifications.
- Commercial:Dubai high-rise developers prioritize dry-type units for basement substations where fire codes prohibit oil-immersed alternatives. Pre-tested modular skids compress commissioning schedules from weeks to days.
- Residential:Master-planned communities in Dubai South and Sharjah's Aljada district specify compact pad-mounted transformers with integrated ring-main units for underground distribution loops.
Utilities anchor procurement volume currently; industrial buyers are expanding fastest through long-term service contract conversion.
Installation:
Site constraints and mobility requirements dictate enclosure standards and cooling system selection.
- Onshore:Fixed installations in industrial zones and urban substations employ conventional radiators or dry-type natural air convection. Fujairah manufacturing footprints anchor delivery timelines for oil-immersed units.
- Offshore:Space-constrained oil platforms require gas-insulated SF6 designs with 2.5-3x cost premiums versus conventional alternatives. ABB Ltd maintains technology leadership in compact offshore-rated enclosures.
- Substation:Purpose-built transformer bays in greenfield utility substations accommodate large power units with dedicated fire suppression and oil containment systems.
- Mobile:Skid-mounted and trailer-mounted units serve temporary construction power and emergency grid restoration for utility maintenance windows.
Onshore installations hold the largest installed base; offshore specifications are expanding most quickly with new platform electrification projects.
Technology:
Cooling medium selection hinges on fire safety codes, indoor placement restrictions, and maintenance access constraints.
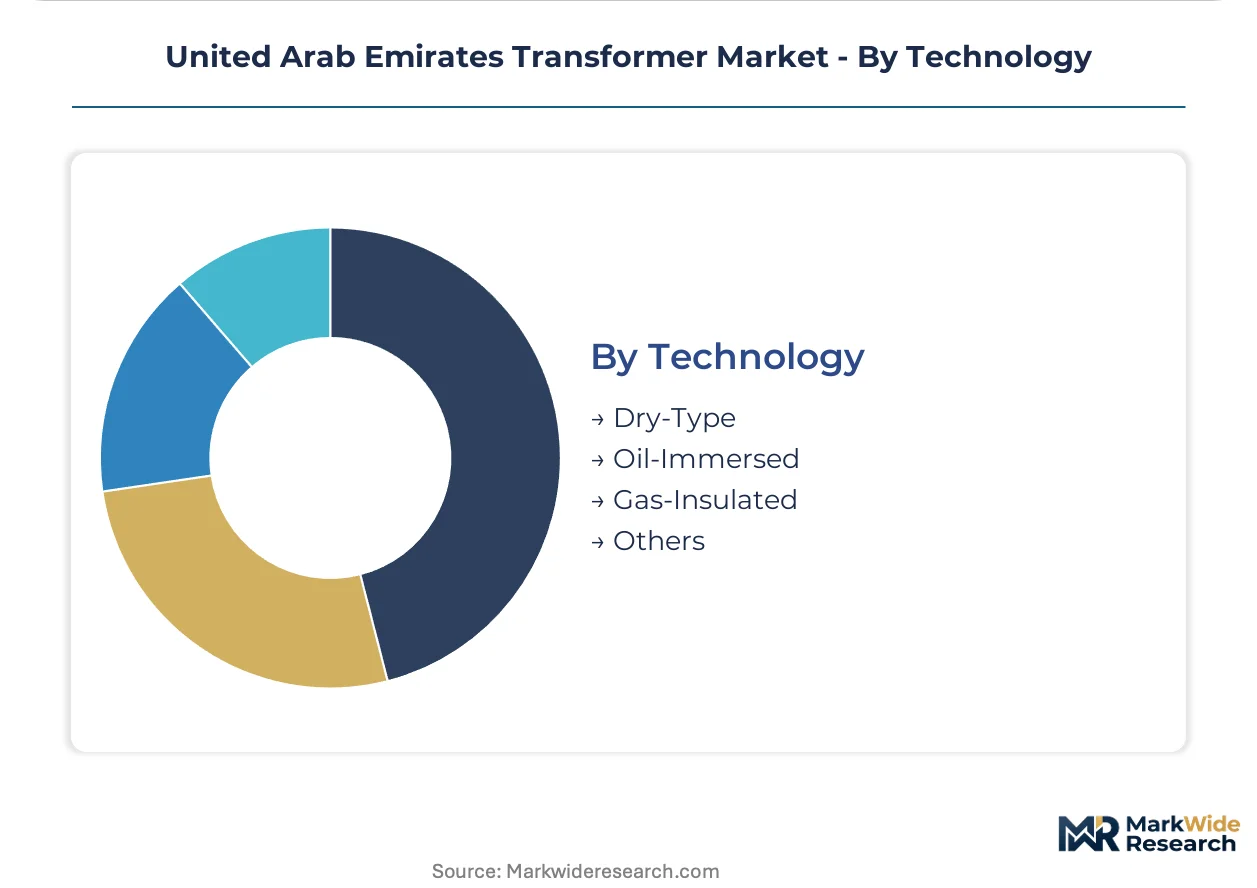
- Dry-Type:Cast-resin or vacuum-pressure-impregnated designs eliminate flammable oil for indoor commercial installations. Dubai Municipality fire codes are displacing oil-immersed alternatives in high-rise basement substations.
- Oil-Immersed:Mineral oil or ester fluid designs dominate utility-scale power transmission for superior thermal performance and overload capacity. Eurogulf Transformer FZE leverages Fujairah production for regional delivery reliability.
- Gas-Insulated:SF6 or fluoronitrile-based designs compress footprint for offshore platforms and dense urban substations where real estate constraints override cost premiums.
- Others:Emerging solid-state and superconducting prototypes remain experimental for UAE grid applications, with limited demonstration projects under federal research funding.
Oil-immersed technology leads installed capacity today; dry-type designs are gaining share fastest as commercial fire codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE transformer industry traces its manufacturing roots to Fujairah's industrial corridor, where coastal access and port infrastructure enabled material import for oil-immersed unit production. Federal industrial strategy subsequently channeled investment toward electrical equipment localization, creating a domestic supply base serving GCC grid expansion.
Dubai
Dubai Electricity and Water Authority's smart grid investments are multiplying secondary substation deployments across district cooling networks. Dubai Municipality fire codes mandate dry-type units for high-rise basement installations, displacing oil-immersed alternatives in commercial developments. Mohammed bin Rashid Al Maktoum Solar Park procurement is anchoring demand for 400 kV class power transformers.
Abu Dhabi
Al Dhafra Solar Park expansion is sustaining procurement of high-capacity grid interconnection transformers for utility-scale photovoltaic clusters. Emirates Authority for Standardization and Metrology administers ECAS conformity schemes controlling market access for imported units. Ruwais downstream oil and gas facilities are contracting 15-year performance guarantees covering predictive maintenance.
Sharjah
Industrial corridor electrification across Sharjah's manufacturing zones is expanding medium-voltage distribution transformer installations. Federal efficiency tier requirements are filtering low-specification imports from Asian suppliers. Hamriyah Free Zone concentration of fabrication facilities is shortening delivery timelines for pad-mounted units.
Northern Emirates
Ras Al Khaimah industrial zone development is creating underpenetrated demand for medium-voltage infrastructure outside the Abu Dhabi-Dubai axis. MOHAP certification timelines for healthcare facility transformers are compressing project delivery windows. Fujairah's manufacturing footprint anchors regional production capacity for oil-immersed designs.
United Arab Emirates Transformer Market Competitive Landscape
The competitive structure tilts toward integrated system providers capable of bundling transformer-switchgear combinations. Vendor positioning fragments across three tiers: multinational technology leaders with digital monitoring portfolios, regional manufacturers leveraging domestic production footprints, and specialized fabricators serving niche voltage classes. Strategic moves center on modular substation packaging and long-term service contract conversion.
Among UAE-based manufacturers, Eurogulf Transformer FZE and Emirates Transformer & Switchgear Ltd. exemplify the regional production archetype, anchoring delivery reliability through Fujairah and domestic manufacturing assets. ABB Ltd occupies a position within the technology leadership tier, represented in gas-insulated designs for space-constrained applications. These three entities collectively illustrate the market's segmentation across geographic anchoring versus technical specialization strategies.
| Leading Market Players |
|---|
| Eurogulf Transformer FZE |
| ABB Ltd |
| Emirates Transformer & Switchgear Ltd. (ETS) |
| Schneider Electric |
| Siemens AG |
| Gulf Transformers Co. LLC (GTC) |
| Federal Power Transformers LLC |
| General Electric Company |
| Crux Transformers |
| Others |
Value Network & Pricing Analysis
Dry-type transformer manufacturing migration toward cast-resin designs is simultaneously elevating factory automation requirements and concentrating component sourcing among specialized European resin suppliers. This technology shift compresses margins for conventional oil-immersed producers while rewarding manufacturers with backward integration into core materials.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs UAE procurement, with differentiation driven by ECAS certification tier and after-sales service bundling. Pricing pressure stems from Asian import competition in the economy tier, where buyers prioritize lowest first cost over lifecycle efficiency. Industrial oil and gas facilities exhibit lowest price sensitivity due to outage cost exposure, while commercial developers in Dubai high-rises drive hardest bargain on dry-type units.
Supply Chain Analysis
Specialized winding technician scarcity in Japan and Germany constrains local production scaling for 400 kV class units, forcing UAE manufacturers to import precision coil assemblies. Grain-oriented electrical steel draws from Japanese and European mills, while copper winding wire sources from Chinese and South Korean smelters. Single-source vulnerability in core steel exposes manufacturers to currency fluctuation risk. Distribution runs through Fujairah manufacturing hubs serving GCC utility procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE transformer market reads as a late-cycle quality story, with utility procurement shifting toward 30-year design life specifications and integrated digital monitoring that commands sustained pricing premiums.
For Market Incumbents: Hedge against modular substation bundling by acquiring switchgear integration capabilities or partnering with packaged solution providers. Defensive moves should prioritize ECAS pre-certification investment to compress approval timelines, while local testing partnerships anchor delivery reliability against emerging regional competitors.
For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer lower-friction entry than conventional EPC channel relationships. White-space targets include Ras Al Khaimah industrial zone electrification and NEOM cross-border converter transformer demand. Ras Al Khaimah presents most penetrable geography due to limited incumbent service infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional manufacturers lacking digital monitoring portfolios but possessing Fujairah production assets. Long-term viability favors targets with 15-year service contract backlogs and healthcare sector MOHAP certification relationships. Watch Al Dhafra Solar Park phase announcements as inflection signal for 400 kV procurement volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel | Captive grain-oriented electrical steel supply insulates margin from Japanese mill pricing volatility. |
| Digital Twin Platform Development | Predictive analytics integration creates recurring revenue from DEWA and TAQA asset performance contracts. |
| ECAS Certification Pre-Investment | Pre-certified product families compress 14-18 week MOHAP timelines to secure healthcare project awards. |
| Modular Substation Partnership | Switchgear bundling capability preserves share against packaged solution providers in Dubai district cooling. |
| Ras Al Khaimah Service Hub Establishment | Proximity to underpenetrated industrial zones captures medium-voltage distribution transformer growth outside Abu Dhabi-Dubai axis. |
Research Methodology
Bottom-up utility and industrial procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with DEWA planning officers, TAQA grid operators, EPC contractors, transformer plant managers, and healthcare facility engineers combined with secondary validation from ESMA ECAS registration databases, customs import records, federal industrial strategy filings, and project development announcements. Triangulation across stakeholder inputs and documentary sources anchors volume estimates.
Input-output matrices map transformer class demand against voltage rating, cooling technology, and end-user sophistication across the projection horizon. Segmentation dimensions include product type, installation environment, technology category, and buyer archetype. CAGRs derive from regression analysis of historical procurement patterns adjusted for named project pipelines. Forecast inputs incorporate Al Dhafra Solar Park expansion phases and MOHAP regulatory timeline evolution.
The model assumes a particular technology adoption path; alternative pathways for solid-state transformer commercialization would alter the outlook. Forecasts reflect documented assumptions regarding ESMA enforcement intensity and federal localization incentive durability. Material deviation in grain-oriented steel pricing or MOHAP certification timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Canada Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
North America Transformer Market
Transformers
India Power Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Global Transformer Market
Transformers
Transformer Core Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Locomotive Traction Transformer Market
Transformers
Transformer Bobbin Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Middle East and Africa Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
US Oil Filled Distribution Transformer Market