
 Air Cooled Transformer Market | 2026-2036
Air Cooled Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cooled Transformer Market Insights
The capital-intensity divergence between integrated OEMs and component assemblers is rotating competitive advantage toward firms with in-house core lamination and winding capabilities. Schneider Electric leverages its global manufacturing footprint to sustain pricing power across utility-scale installations. ABB anchors its position through IEC-certified design platforms that dominate European renewable interconnection projects. Siemens Energy differentiates via high-voltage dry-type expertise for offshore wind converter stations.
An air cooled transformer is a static electromagnetic device that transfers electrical energy between circuits through inductively coupled windings, typically rated between 50 kVA and 30 MVA for dry-type configurations, relying on ambient airflow or forced ventilation rather than liquid dielectrics for thermal management. Its primary purpose is voltage step-up or step-down in commercial buildings, industrial plants, and renewable generation sites where fire safety and environmental containment preclude oil-filled alternatives. Three phase units capture the dominant share of utility and heavy industrial procurement due to higher power density and balanced load handling. Air forced cooling technology is expanding fastest in data center and cryptocurrency mining applications where compact footprint and continuous duty cycles override acoustic constraints. Indoor installations retain margin premiums in urban commercial retrofits where space restrictions and fire codes limit outdoor pad-mounted alternatives.
IEEE C57.12.01 and IEC 60076-11 establish thermal class, insulation system, and short-circuit withstand benchmarks that determine product eligibility for North American and European utility tenders. EPA efficiency mandates and EU Ecodesign regulations are tightening no-load loss limits, compelling manufacturers to redesign core geometries and adopt advanced grain-oriented silicon steel. China's GB standards and NMPA certification requirements shape domestic procurement protocols for rail and infrastructure applications. Stakeholders must monitor evolving efficiency tier thresholds and carbon-border adjustment mechanisms to anticipate sourcing and certification investments.
Market Dynamics
Amorphous metal core technology is compressing traditional grain-oriented silicon steel economics as IEEE and IEC efficiency mandates tighten no-load loss thresholds across utility procurement specifications.
Growth Catalysts
- Data center power density:Hyperscale operators in the United States and Germany are specifying three-phase dry-type units above 10 MVA to support AI training cluster loads. Forced air cooling configurations are displacing liquid alternatives in retrofit-constrained facilities.
- EU Ecodesign Directive:Tier 2 loss requirements coming into force are compelling European utilities to accelerate transformer replacement cycles. Premium efficiency ratings now gate access to public tender frameworks.
- Offshore wind converter stations:High-voltage dry-type expertise is capturing interconnection contracts as developers phase out oil-filled units for fire-safety compliance. Siemens Energy and ABB are anchoring this transition.
Market Restraints
- Grain-oriented silicon steel supply:Japanese and South Korean mill concentration creates input cost volatility when electrical steel spot markets tighten. Transformer OEMs lack pricing power to pass through surcharges.
- Amorphous ribbon production:Hitachi Metals and limited Chinese suppliers control metastable alloy feedstock. Capacity constraints are elongating lead times for ultra-low-loss core designs.
- Acoustic emission limits:IEC 60076-10 sound level requirements restrict forced-air cooling deployment in urban commercial zones. Fan noise mitigation adds cost without performance benefit.
Strategic Opportunities
- India rail electrification:Indian Railways' 35 kV traction substation expansion is specifying cast-resin dry-type units for tunnel safety. BIS certification requirements favor domestic-foreign joint ventures.
- Behind-the-meter solar:Commercial building owners are procuring pad-mounted air-cooled step-up transformers for rooftop PV interconnection. NEC 2023 rapid shutdown rules are accelerating this specification.
- Digital twin integration:Thermal modeling software from ANSYS and Siemens is converging with transformer monitoring hardware. Predictive maintenance contracts are creating recurring revenue pools.
Industry Challenges
- Winding technician scarcity:Precision coil winding for high-voltage dry-type insulation systems requires multi-year apprenticeship. North American and European vocational pipelines are failing to replenish retiring specialists.
- IEC 60076-11 type testing:Short-circuit withstand and thermal shock certification cycles extend 18-24 months. Design validation bottlenecks are delaying product launches for emerging market tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cooled Transformer Market |
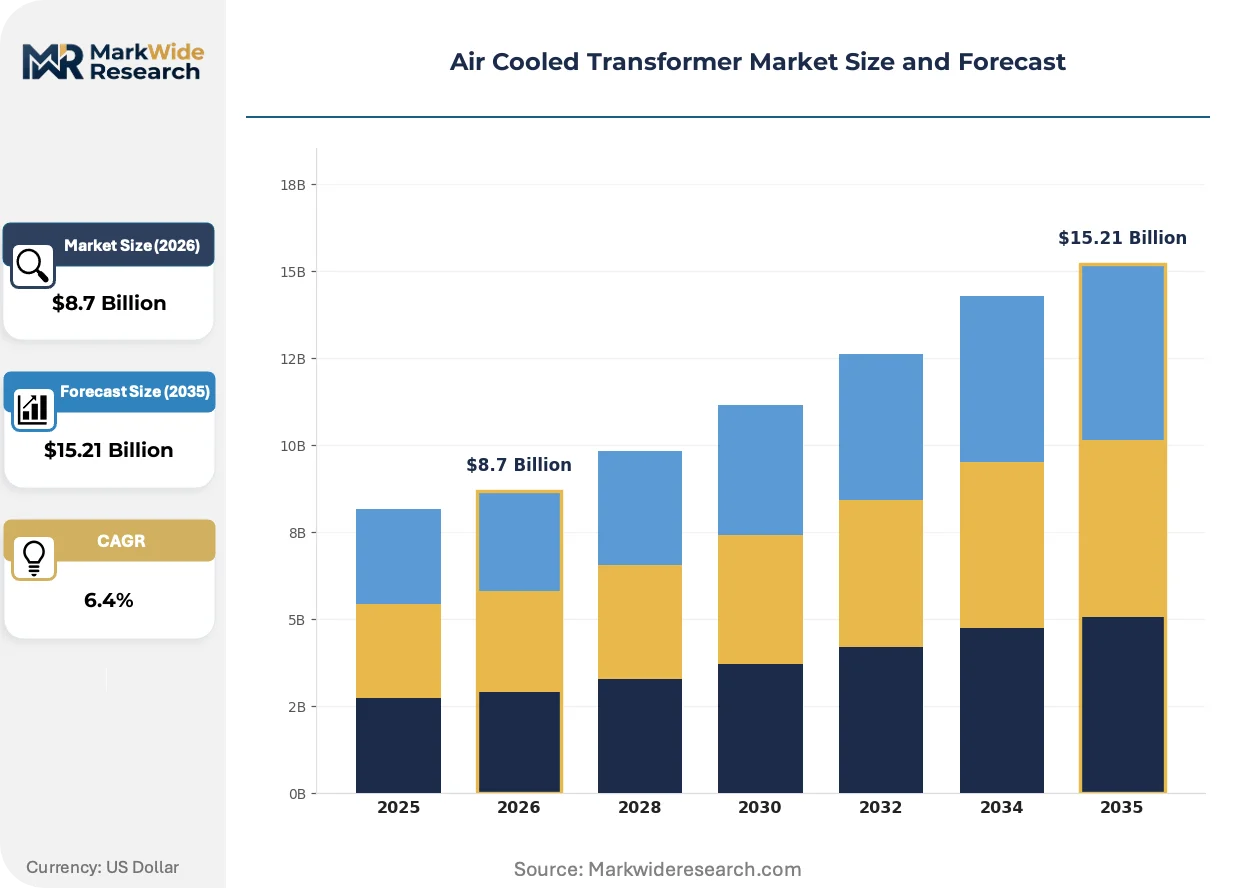
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Auto Transformer, Isolation Transformer End User: Industrial, Commercial, Power Generation, Manufacturing Installation Type: Indoor, Outdoor, Ground-mounted, Wall-mounted Cooling Technology: Air Natural, Air Forced, Hybrid, Passive |
| Companies Covered | Schneider Electric, ABB, Siemens Energy, Hitachi Energy, Eaton, Mitsubishi Electric, GE Vernova, Hammond Power Solutions, Jinpan International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cooled Transformer Market Trends and Innovations
Core material substitution, regulatory loss-tier compression, and buyer procurement centralization are restructuring competitive advantage around in-house lamination capability and certified design platforms rather than assembly scale.
Amorphous alloy ribbon cores are displacing conventional grain-oriented silicon steel in distribution transformers rated below 2.5 MVA. European utilities facing EU Ecodesign Tier 2 mandates are specifying these units for urban substation retrofits where fire codes prohibit oil-filled alternatives. The technology is displacing mid-tier OEMs lacking vacuum annealing furnace infrastructure or metallurgical partnerships.
EPA efficiency mandates under the Energy Policy Act are tightening no-load loss limits for medium-voltage distribution transformers sold into US utility fleets. Manufacturers are redesigning core geometries and adopting step-lap construction to maintain eligibility for federally funded grid modernization programs. Investor-owned utilities in California and Texas are accelerating procurement ahead of anticipated rule finalization.
Consolidated procurement by hyperscale data center operators is compressing vendor diversity and unbundling aftermarket service contracts. Meta and Microsoft are specifying 10-year thermal performance guarantees with penalty clauses, forcing OEMs to retain residual risk rather than channel partners. This concentration is most visible in Northern Virginia and Frankfurt cloud campus developments where single projects exceed 100 MVA aggregate demand.
Air Cooled Transformer Market Segmentation
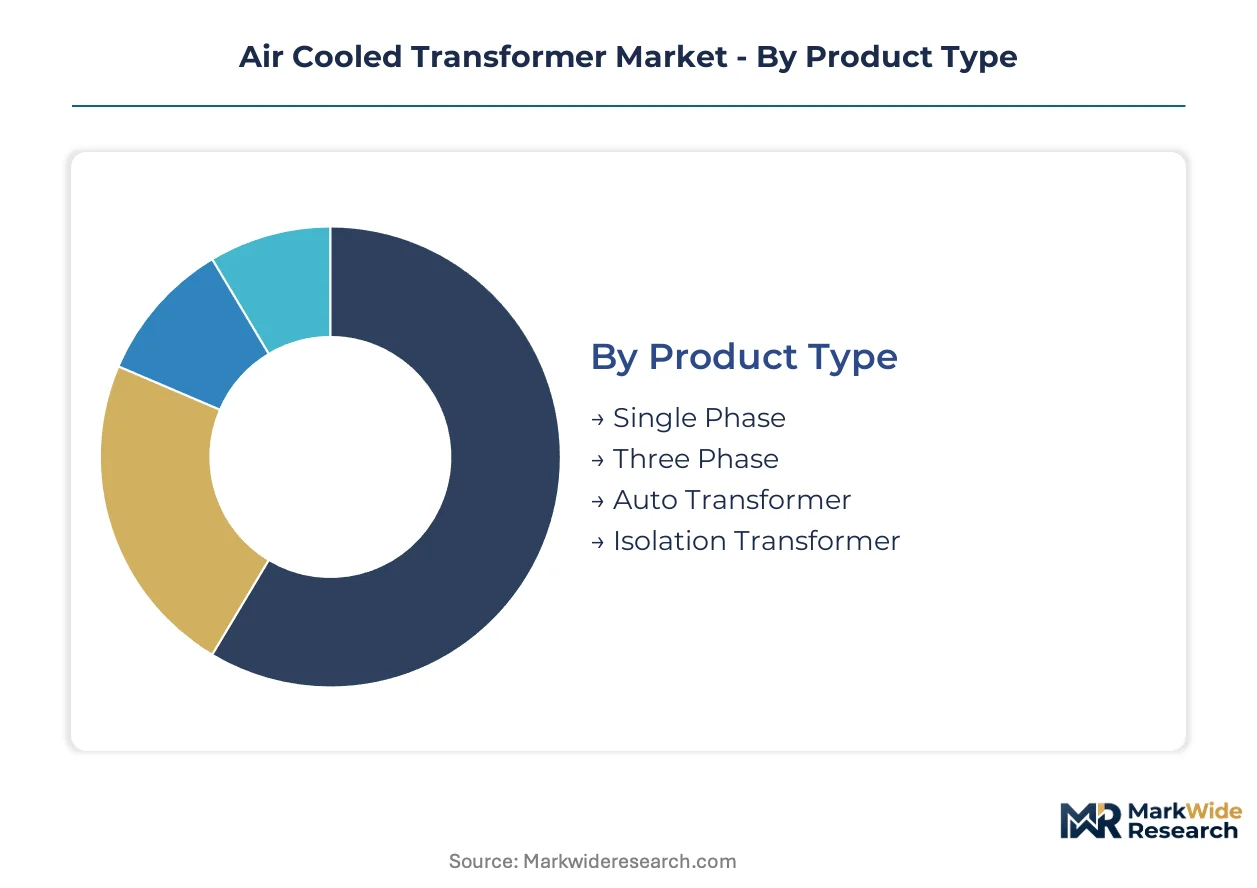
Air cooled transformer procurement patterns diverge sharply across product architectures, end-use environments, and thermal management approaches. Understanding these splits reveals where margin concentration and volume expansion are concentrating for OEMs and component suppliers.
Product Type:
Domestic procurement dominates single-phase and auto transformer categories, while three-phase and isolation units drive export-led revenue for manufacturers with IEC and IEEE dual certification.
- Three Phase:Engineered for balanced load handling across 10-30 MVA ratings with delta-wye winding configurations. Hyperscale data center operators in Northern Virginia and Frankfurt specify these units for AI cluster power distribution, prioritizing compact footprint over acoustic constraints.
- Single Phase:Rated typically 50-500 kVA for light commercial and residential distribution. Rural electrification programs in India and Southeast Asian infrastructure projects sustain volume demand for pad-mounted variants.
- Auto Transformer:Delivers voltage transformation through shared winding sections, reducing copper mass by 30-50% versus conventional designs. European rail electrification and North American utility voltage conversion applications specify these for cost-sensitive installations.
- Isolation Transformer:Provides galvanic separation between primary and secondary circuits with dedicated windings. Medical facility upgrades and semiconductor fabrication cleanrooms in Germany, Japan, and the United States require these for harmonic mitigation and equipment protection.
Three phase units command the established base. The steepest expansion runs through isolation transformers.
End User:
Cost tier stratification separates premium-specification power generation buyers from price-sensitive manufacturing procurement, with commercial and industrial segments occupying the contested middle ground.
- Industrial:Heavy manufacturing and process industries specify 1-10 MVA dry-type units for motor drives and furnace loads. Petrochemical complexes in Texas and Rotterdam mandate these for fire-code compliance in hazardous zones.
- Power Generation:Renewable developers and utility-scale solar farms procure step-up transformers rated 5-25 MVA for grid interconnection. Offshore wind converter stations in the North Sea and Taiwan Strait are phasing out oil-filled alternatives.
- Commercial:Office complexes, retail centers, and healthcare facilities specify 500 kVA-3 MVA units for building distribution. Urban fire codes in London, Singapore, and New York City preclude liquid-filled options in high-rise basements.
- Manufacturing:Discrete assembly and light industrial plants prioritize capital efficiency over thermal performance. Mexican maquiladora operations and Vietnamese export manufacturing zones drive volume procurement of standard-efficiency units.
Industrial applications anchor current revenue. Power generation is expanding most quickly.
Installation Type:
Volume concentration favors outdoor ground-mounted configurations, while margin premiums attach to indoor and wall-mounted variants where space constraints and fire codes limit competitive alternatives.
- Outdoor:Pad-mounted and ground-level installations dominate utility-scale deployment. Suburban substation retrofits in California, Texas, and Queensland specify these for accessibility and thermal dissipation.
- Indoor:Enclosed installations in basements, mechanical rooms, and dedicated electrical vaults command 15-25% price premiums. Tokyo, Hong Kong, and Manhattan high-rises require these where outdoor footprint is unavailable.
- Ground-mounted:Concrete pad or skid-based foundations for 1-15 MVA units. Solar farm developers in Spain, Chile, and South Africa standardize on these for rapid deployment and maintenance access.
- Wall-mounted:Compact 50-300 kVA units for space-constrained commercial retrofits. European urban building renovations and Japanese commercial density zones specify these where floor space carries opportunity cost.
Outdoor configurations hold volume leadership. Wall-mounted designs are gaining share fastest.
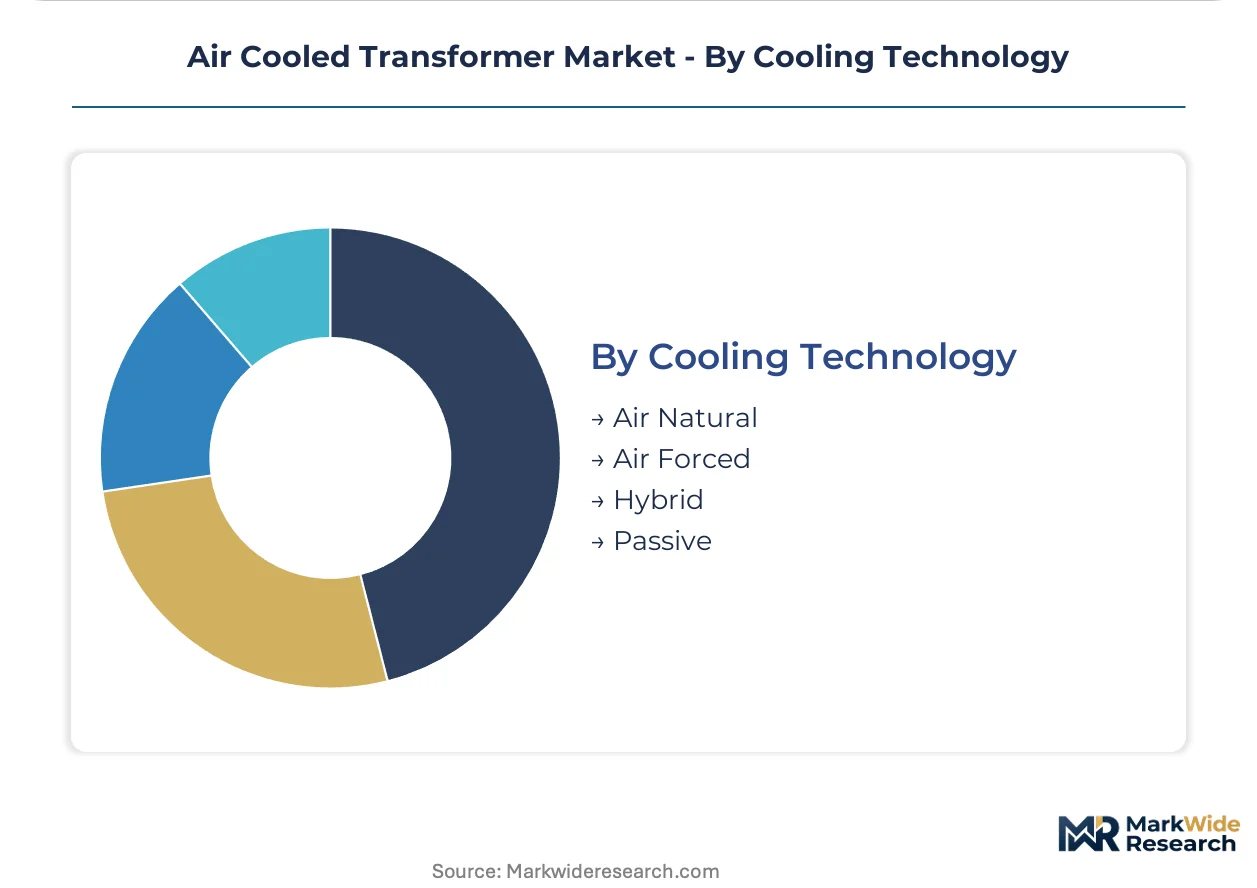
Cooling Technology:
Application maturity separates established air natural designs from emerging hybrid architectures, with customer type determining whether acoustic tolerance or continuous duty cycles dominate specification.
- Air Forced:Fan-assisted ventilation enables 30-40% power density increases over natural convection. Cryptocurrency mining facilities in Kazakhstan, Iceland, and Texas specify these for 24/7 operation despite noise penalties.
- Air Natural:Passive thermal management through radiators and convection currents. European utilities facing EU Ecodesign mandates and urban noise restrictions specify these for distribution substations.
- Hybrid:Combines passive base loading with forced ventilation for peak demand periods. Data center operators in Singapore and Amsterdam deploy these to balance efficiency targets against transient AI training loads.
- Passive:Zero-moving-part designs relying on optimized core geometry and enlarged surface area. Remote telecommunications installations in Australia and Canada specify these for maintenance access limitations.
Air natural cooling retains the installed base. Air forced configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for air cooled transformers varies sharply by geography. German utilities absorb 20-30% premiums for EU Ecodesign Tier 2 compliance, while Indian rail procurement prioritizes capital efficiency over loss reduction. Chinese state grid tenders balance domestic content rules against amorphous core performance thresholds.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are specifying three-phase dry-type units above 10 MVA for AI cluster power distribution. EPA efficiency mandates under the Energy Policy Act are tightening no-load loss limits for medium-voltage distribution transformers. California investor-owned utilities are accelerating procurement ahead of anticipated rule finalization.
Germany
Offshore wind converter stations in the North Sea are phasing out oil-filled alternatives for fire-safety compliance. EU Ecodesign Directive Tier 2 loss requirements are compelling utilities to accelerate transformer replacement cycles. Frankfurt cloud campus developments are driving concentrated demand for 10-year thermal performance guarantees.
China
State Grid Corporation tenders for 35 kV traction substations are specifying cast-resin dry-type units for rail electrification safety. GB standards and NMPA certification requirements shape domestic procurement protocols. Yangtze River Delta manufacturing clusters are scaling amorphous ribbon core production for ultra-low-loss distribution units.
India
Indian Railways' electrification expansion is specifying dry-type transformers for tunnel safety applications. BIS certification requirements favor domestic-foreign joint ventures for technical compliance. Maharashtra and Gujarat industrial corridors are procuring standard-efficiency units for manufacturing zone power distribution.
Japan
Tokyo high-rise commercial retrofits command 15-25% price premiums for indoor installations where fire codes prohibit liquid-filled options. METI efficiency guidelines are pushing building owners toward advanced grain-oriented silicon steel designs. Osaka-Kobe manufacturing clusters maintain precision winding capabilities for high-voltage insulation systems.
Air Cooled Transformer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the air cooled transformer market. Integrated OEMs with in-house core lamination capabilities capture premium pricing on utility-scale installations, while component assemblers compete on delivery speed for standard-efficiency commercial units. The competitive terrain separates into three strategic archetypes: full-stack manufacturers with certified design platforms, regional specialists with winding expertise, and scale-driven producers serving price-sensitive infrastructure tenders. Dominant competitive moves include backward integration into electrical steel supply chains and technology licensing partnerships for amorphous core production.
Among European-integrated energy technology groups, ABB, Siemens Energy, and Schneider Electric exemplify the full-stack archetype with IEC-certified design platforms. ABB represents the renewable interconnection specialist position, Siemens Energy anchors high-voltage dry-type expertise for offshore applications, and Schneider Electric occupies the global manufacturing footprint tier sustaining pricing power across utility-scale deployments.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens Energy |
| Hitachi Energy |
| Eaton |
| Mitsubishi Electric |
| GE Vernova |
| Hammond Power Solutions |
| Jinpan International |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign Directive Tier 2 loss requirements and IEEE C57.12.01 thermal class certifications simultaneously gate supplier qualification and stratify price tiers across utility procurement frameworks. OEMs lacking IEC-certified design platforms or in-house amorphous core lamination capabilities face exclusion from premium tender categories, compressing their addressable market to standard-efficiency commercial segments.
Pricing Analysis
Extended thermal performance guarantees and predictive maintenance service contracts drive lifetime value capture for integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified utility-scale suppliers from regional assemblers serving price-sensitive infrastructure tenders. Cost compression in standard-efficiency distribution units is intensifying because Chinese state grid tenders prioritize capital efficiency over loss reduction. Manufacturing procurement in Mexican maquiladora zones and Vietnamese export zones exhibits highest price sensitivity, while German offshore wind converter station developers absorb premiums for fire-safety compliance.
Supply Chain Analysis
Japan and South Korea anchor grain-oriented silicon steel production for transformer core lamination, with Chinese Yangtze River Delta clusters scaling amorphous ribbon feedstock capacity. Electrical steel draws from concentrated mill capacity, copper winding wire sources from Chilean and Indonesian smelter output, and cast-resin insulation systems hinge on German and Japanese specialty chemical suppliers. Single-source vulnerability runs through Hitachi Metals-controlled metastable alloy feedstock for ultra-low-loss cores. Distribution runs through direct utility procurement teams, EPC contractor specifications, and OEM-authorized service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amorphous metal core substitution and EPA efficiency mandate tightening constitute a dual inflection compressing traditional grain-oriented silicon steel economics and rotating competitive advantage toward metallurgical partnerships.
For Market Incumbents: Consolidate backward integration into electrical steel supply chains and vacuum annealing furnace infrastructure to defend margin position against emerging Chinese amorphous ribbon producers. Anchor certification investment in IEC 60076-11 type testing platforms to maintain eligibility for European renewable interconnection tenders as Tier 2 mandates accelerate replacement cycles. For New Entrants and Emerging Players: BIS certification fast-tracks for Indian Railways traction substation tenders open white-space access for domestic-foreign joint ventures. Target wall-mounted 50-300 kVA commercial retrofits in Tokyo, Hong Kong, and Manhattan high-rises where space constraints limit incumbent scale advantages. Pursue digital twin integration partnerships with thermal modeling software providers to differentiate predictive maintenance offerings. For Investors and Strategic Acquirers: EU Ecodesign Tier 2 implementation reshapes the acquisition landscape toward OEMs with certified design platforms and in-house lamination capabilities rather than assembly-scale players. Long-term viability centers on residual risk retention through 10-year thermal performance guarantees. Target acquisition archetype: mid-cap specialists with precision winding expertise and vacant amorphous core partnerships. Monitor EPA rule finalization timing as inflection indicator for US utility procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel Supply | Captive grain-oriented silicon steel and amorphous ribbon production insulates Hitachi Metals-dependent OEMs from feedstock volatility. |
| IEC 60076-11 Certification Investment | Type testing platform ownership gates access to European offshore wind and utility-scale renewable interconnection tenders. |
| Digital Twin Platform Partnership | ANSYS and Siemens thermal modeling integration creates recurring predictive maintenance revenue pools with data center operators. |
| Domestic-Foreign Joint Venture Formation | BIS certification compliance unlocks Indian Railways electrification expansion and tunnel safety specification access. |
| Amorphous Core Production Licensing | Metallurgical partnerships with Yangtze River Delta ribbon producers compress lead times for EU Ecodesign Tier 2 compliant units. |
Research Methodology
A spread of perspectives from utility procurement officers, transformer OEM engineering directors, EPC contractor specification leads, and electrical steel mill sales managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through IEC and IEEE standards documentation, EPA regulatory filings, EU Ecodesign Directive implementation guidance, and State Grid Corporation tender announcements. Customs trade data for grain-oriented silicon steel and amorphous alloy ribbon shipments provided input cost calibration. Bottom-up unit economics triangulated against top-down utility capex forecasts.
Segmentation dimensions modeled span cooling technology architecture, installation environment constraints, voltage rating tiers, and end-use application intensity across the projection horizon. Analytical framework approach incorporates product substitution elasticity between air natural and air forced configurations, regulatory loss-tier compression timelines, and buyer procurement centralization patterns. CAGRs derive from installed base replacement cycles, renewable interconnection project pipelines, and data center power density trajectories. Hyperscale operator aggregate demand forecasting and amorphous core capacity expansion schedules constitute industry-specific inputs.
Underlying assumptions cover efficiency mandate implementation pacing, electrical steel spot market stability, and winding technician apprenticeship pipeline replenishment, with deviation risk concentrated in tariff exposure for Japanese and South Korean mill imports and amorphous ribbon production bottlenecks. Recalibration cycles align with material shifts in EPA rule finalization, EU Ecodesign tier transitions, and hyperscale data center campus development announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Transformer Market
Transformers
Smart Transformer Market
Transformers
North America Power Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Latin America Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Global Transformer Market
Transformers
Middle East and Africa Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Oil Filled Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Locomotive Traction Transformer Market
Transformers
Distribution Transformer Market
Transformers
Traction Transformer Market