
 Sweden Solar Energy Market | 2026-2036
Sweden Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Solar Energy Market Analytics
Utility-grade efficiency standards are redrawing procurement criteria for Swedish solar developers. Midsummer AB specializes in lightweight thin-film manufacturing for building-integrated applications. Vattenfall AB anchors large-scale project development through its integrated utility platform. Soltech Energy Sweden AB dominates commercial rooftop segments with specialized mounting systems for Nordic weather loads.
Sweden solar energy encompasses photovoltaic conversion systems, thermal collectors, and integrated storage architectures designed to capture and distribute solar radiation within a high-latitude climate characterized by significant seasonal irradiance variation. Crystalline silicon modules with temperature coefficients below minus 0.35 percent per degree Celsius perform optimally in Sweden's cooler operating conditions. Photovoltaic panels command the primary product category, while energy storage solutions represent the fastest-expanding segment as grid-balancing requirements intensify. The residential end-user category sustains steady deployment, though utility-scale installations concentrate margin pools through long-term power purchase agreements.
The Swedish Energy Agency and the National Electrical Safety Board shape equipment certification and grid interconnection protocols for all solar installations. EU Green Deal compliance requirements and Sweden's integrated national energy and climate plan mandate renewable expansion trajectories that directly influence project finance availability. Stakeholders must monitor forthcoming revisions to building code energy performance standards and municipal zoning reforms that will determine distributed generation deployment velocity.
Market Dynamics
Swedish municipalities are redrawing procurement protocols for distributed solar generation. The EU Green Deal's renewable mandates are compressing permitting timelines while the Swedish Energy Agency accelerates grid interconnection standards for building-integrated systems.
Growth Catalysts
- EU Green Deal compliance mandates:Sweden's integrated national energy and climate plan requires municipal buildings to meet escalating renewable thresholds. Public procurement volumes are expanding across county administrative boards.
- Building-integrated photovoltaics:Thin-film manufacturing advances are enabling rooftop deployment on structurally constrained public structures. Mounting system innovations address Nordic snow load requirements.
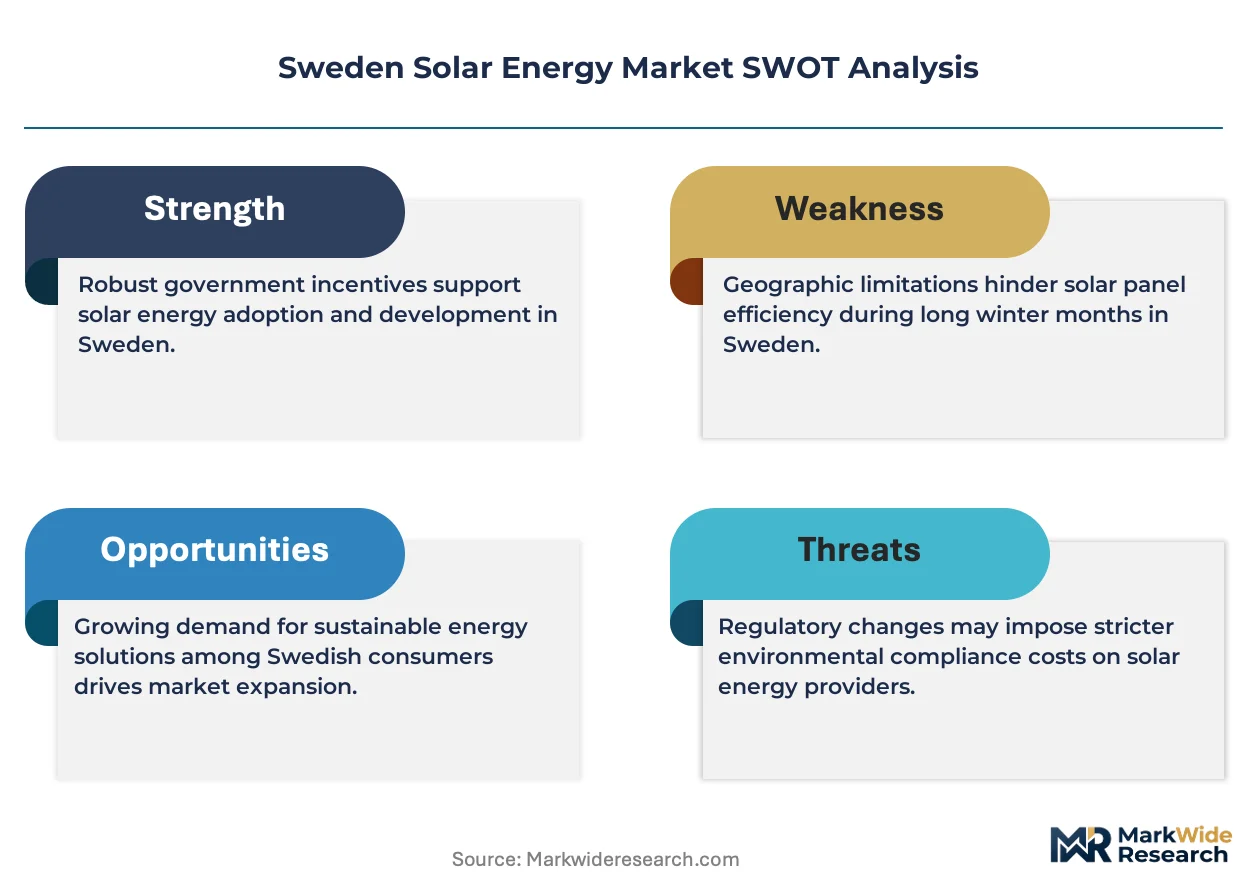
- Southern county irradiation concentration:Skåne and Blekinge counties deliver superior capacity factors that shorten commercial payback periods. Developer pipelines concentrate in these high-irradiation zones.
Market Restraints
- Polysilicon input cost volatility:Crystalline silicon module production depends on polysilicon refining capacity concentrated in Asian manufacturing hubs. Price swings compress developer margins on fixed-price municipal contracts.
- Seasonal irradiation asymmetry:Sweden's high-latitude location creates extreme winter generation troughs. Battery storage capex requirements escalate to maintain grid export commitments.
- Grid interconnection queuing:The Swedish Energy Agency's certification protocols create procedural friction for distributed generation projects. Queue delays extend project development cycles.
Strategic Opportunities
- Agricultural land dual-use deployment:Agrivoltaic configurations on southern Swedish farmland enable simultaneous crop cultivation and energy generation. The Swedish Board of Agriculture is piloting zoning exemptions for these installations.
- Energy storage convergence:Lithium-ion battery systems paired with rooftop arrays are capturing ancillary service revenue streams. Grid-balancing contracts through Svenska kraftnät create new value pools.
- Industrial heat electrification:Solar thermal collectors integrated with district heating networks are displacing biomass in municipal systems. Växjö and Linköping utilities are expanding procurement for these hybrid configurations.
Industry Challenges
- Electrical installer certification bottlenecks:The National Electrical Safety Board's qualification requirements for grid-tied systems exceed current training pipeline capacity. Contractor scarcity extends project commissioning timelines.
- Legacy building structural assessments:Municipal building portfolios require individualized load-bearing evaluations before rooftop installation. Assessment backlogs delay procurement execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Solar Energy Market |
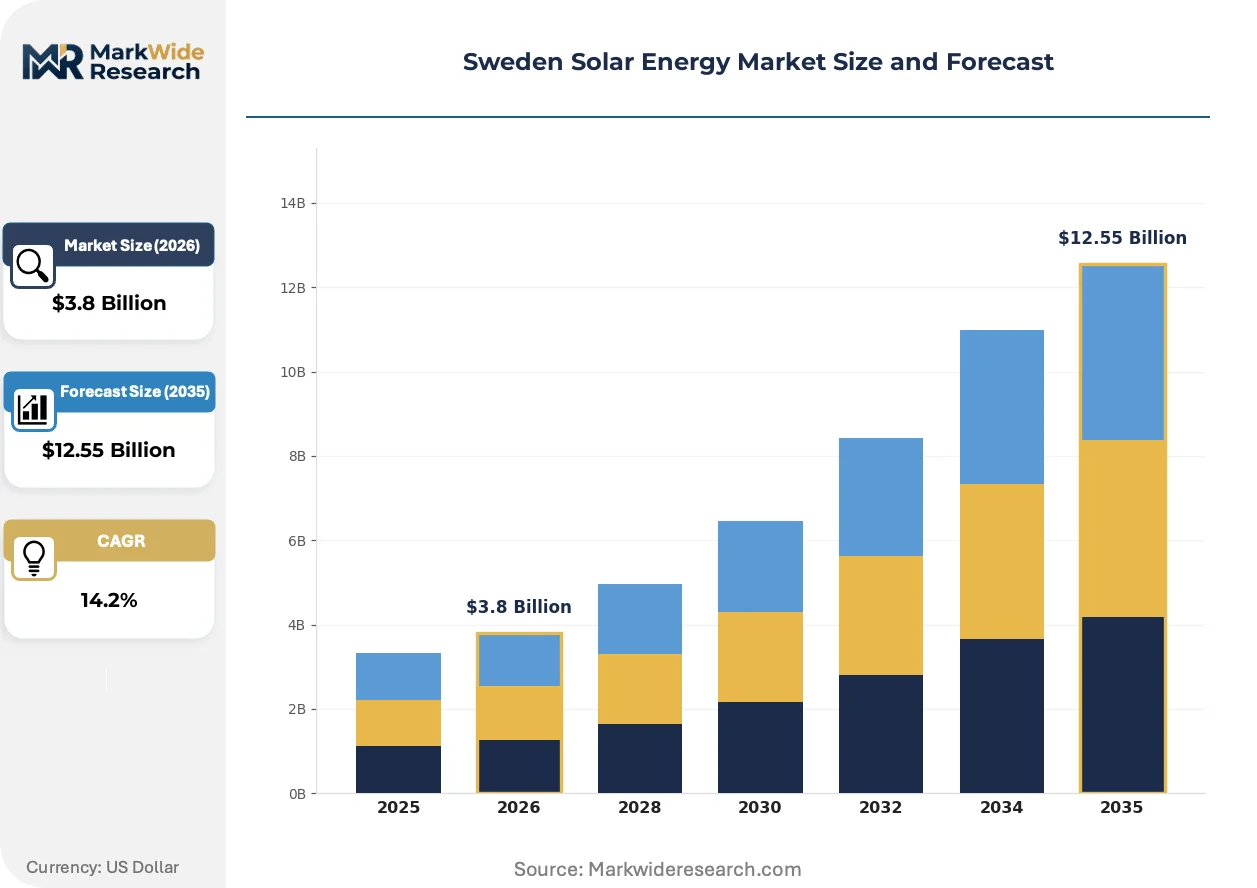
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Mounting Systems, Energy Storage Solutions End User: Residential, Commercial, Industrial, Utility Installation Type: Grid-Connected, Off-Grid, Hybrid, Rooftop Service Type: Consultation, Installation, Maintenance, Financing |
| Companies Covered | Alight AB, Soltech Energy Sweden AB, Vattenfall AB, Eneo Solutions AB, Midsummer AB, Svea Solar AB, S-Solar AB, InnoVentum AB, Exeger Sweden AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Solar Energy Market Evolving Landscape
Technology trajectories in Swedish solar are splitting between utility-scale efficiency optimization and building-integrated form factor innovation. Regulatory pressure and procurement evolution are simultaneously reshaping competitive requirements.
Bifurcation is separating crystalline silicon modules from thin-film alternatives in Swedish project development. Utility-scale developers prioritize high-efficiency monocrystalline panels for ground-mounted installations in southern counties. Building-integrated specialists are capturing municipal rooftop segments where weight constraints and aesthetic requirements dominate procurement criteria. The technology stack is bifurcating into two distinct supply chains with non-overlapping vendor bases and certification pathways.
Sweden's national climate action plan is mandating renewable expansion trajectories that directly shape project finance availability. The EU Green Deal's building performance standards are accelerating municipal energy retrofit requirements. Commercial property owners in Stockholm and Gothenburg are responding by bundling solar installations with envelope insulation upgrades to meet consolidated compliance deadlines.
Municipal procurement is consolidating vendor relationships through framework agreements rather than individual project tenders. County administrative boards in Skåne and Västra Götaland are pre-qualifying installation contractors for multi-year delivery schedules. This aggregation is compressing supplier margins while transferring performance risk to EPC contractors through output-guarantee clauses.
Sweden Solar Energy Market Segmentation
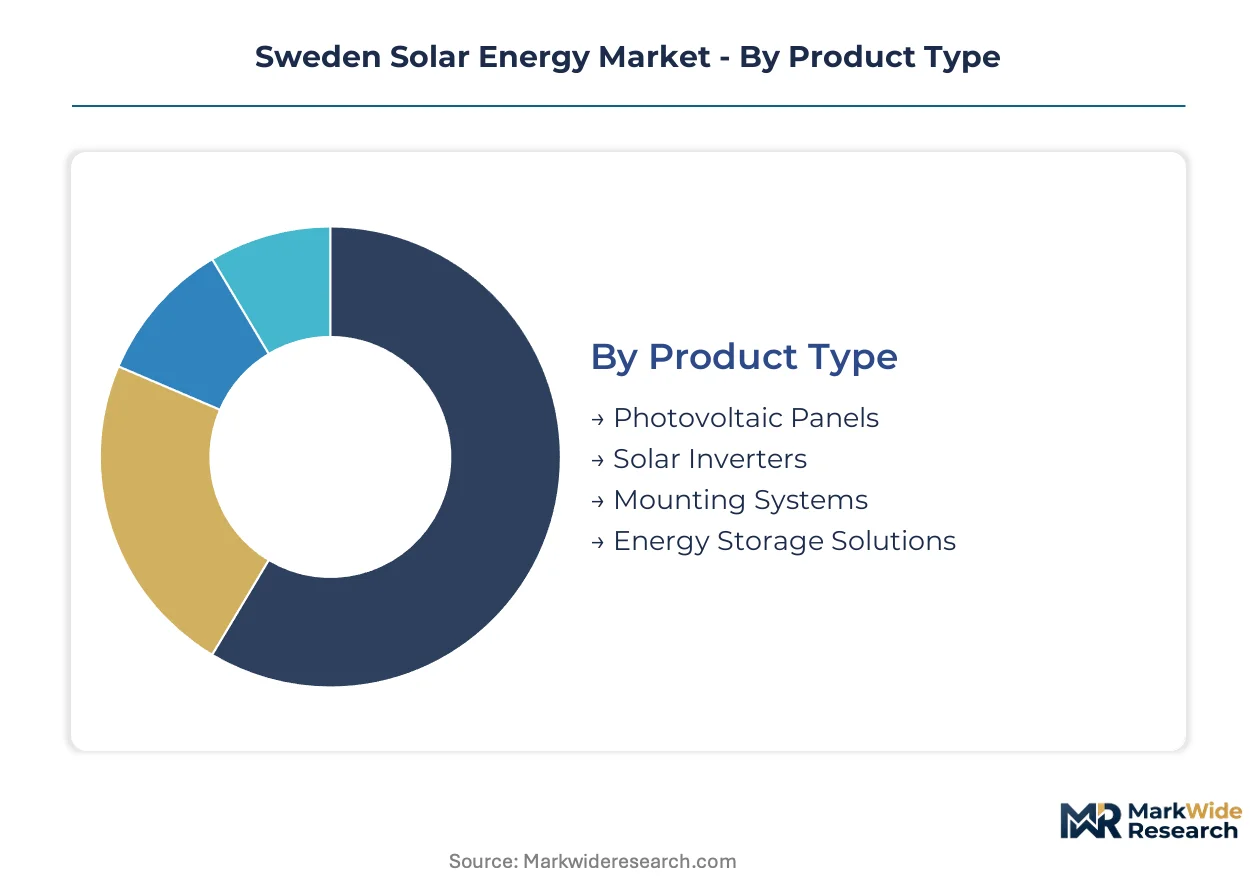
Segmentation in the Swedish solar energy market reveals how technology choices and customer economics diverge across latitude-dependent irradiation patterns and building-stock constraints. Procurement patterns in Skåne and Blekinge counties differ sharply from northern regions, while municipal framework agreements reshape competitive dynamics within each segment.
Product Type:
Margin pools concentrate in integrated system architectures where hardware-software coupling creates switching costs and recurring revenue attachments.
- Photovoltaic Panels:Crystalline silicon modules with sub-minus 0.35 percent per degree Celsius temperature coefficients dominate utility-scale procurement in southern counties. The Swedish Energy Agency's certification protocols favor established suppliers with Nordic climate testing documentation.
- Energy Storage Solutions:Lithium-ion battery systems paired with rooftop arrays capture ancillary service contracts through Svenska kraftnät. Grid-balancing revenue streams are expanding fastest in Stockholm and Gothenburg commercial districts where export commitments require winter buffer capacity.
- Solar Inverters:String inverters and power optimizers for distributed generation must meet the National Electrical Safety Board's grid interconnection standards.
- Mounting Systems:Specialized racking for snow load requirements and building-integrated thin-film applications addresses structurally constrained municipal rooftops.
Photovoltaic panels command the dominant revenue share, while energy storage solutions are climbing the fastest as grid-balancing requirements intensify.
End User:
Customer type determines project scale economics and financing structure availability, with utility-scale aggregators capturing margin through long-term power purchase agreement origination.
- Utility:Large-scale ground-mounted installations in Skåne and Blekinge leverage superior capacity factors to underwrite 15-25 year offtake contracts. Vattenfall AB's integrated platform anchors development pipelines through proprietary site origination and grid access rights.
- Commercial:Property owners in Stockholm and Gothenburg bundle rooftop solar with envelope insulation upgrades to meet consolidated EU Green Deal compliance deadlines. Soltech Energy Sweden AB dominates this segment with Nordic weather-load mounting systems.
- Residential:Steady deployment persists across owner-occupied housing stock, constrained by installer certification bottlenecks.
- Industrial:Manufacturing facilities pursue solar thermal integration with district heating networks to displace biomass inputs.
Utility-scale installations concentrate margin pools through long-term contract structures, while commercial deployment is expanding most quickly under municipal procurement acceleration.
Installation Type:
Interconnection architecture shapes capital efficiency and regulatory exposure, with grid-tied systems accessing preferential financing through Swedish Energy Agency programs.
- Grid-Connected:Dominant configuration for utility and commercial segments, requiring National Electrical Safety Board certification and Swedish Energy Agency interconnection queue clearance. Queue delays currently extend project development cycles.
- Rooftop:Municipal building portfolios drive procurement volume through county administrative board framework agreements. Individual load-bearing assessments create assessment backlogs that delay execution.
- Hybrid:Battery-coupled systems enabling grid export commitment fulfillment during winter generation troughs.
- Off-Grid:Limited to remote rural properties and agricultural operations outside distribution network coverage.
Grid-connected systems hold the dominant deployment share, while rooftop installations are gaining share fastest under municipal procurement consolidation.
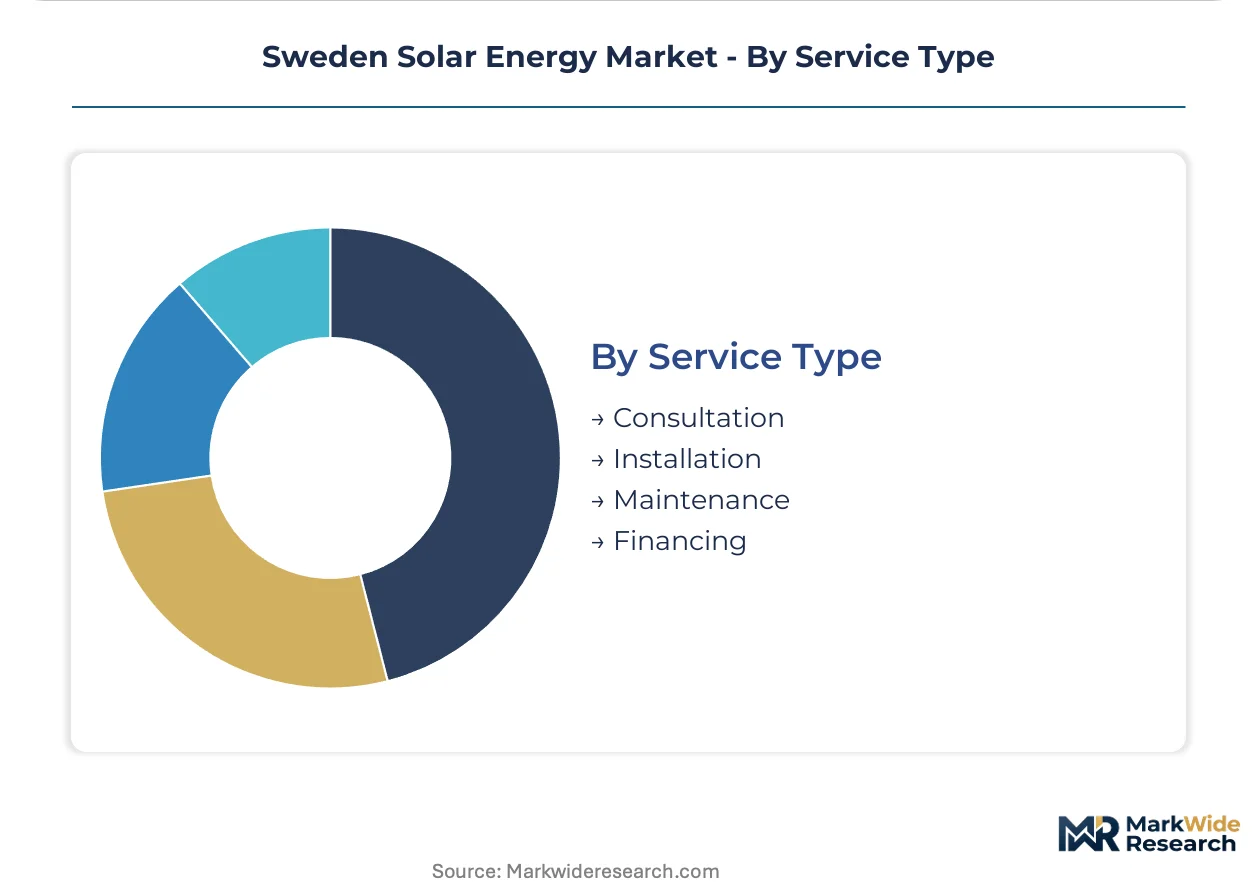
Service Type:
Value capture is migrating downstream from hardware supply toward lifecycle service bundling, particularly in municipal framework agreements with multi-year performance guarantees.
- Installation:Electrical contractor scarcity under National Electrical Safety Board qualification requirements extends commissioning timelines. County administrative boards in Skåne and Västra Götaland are pre-qualifying contractors for aggregated delivery schedules.
- Financing:Project finance availability ties directly to Sweden's national climate action plan renewable expansion trajectories. EU Green Deal compliance mandates shape credit enhancement structures for municipal building portfolios.
- Consultation:Structural assessment and irradiation modeling services precede procurement execution.
- Maintenance:Output-guarantee clauses in framework agreements transfer performance risk to EPC contractors.
Installation services command the dominant value share, while financing services are expanding most quickly as capital structures complexify under green mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for solar deployment varies sharply across Swedish counties. Skåne and Blekinge buyers prioritize irradiation-driven returns, while northern municipalities emphasize policy compliance over payback speed.
Skåne County
Commercial developers concentrate pipeline activity in Malmö and Lund where capacity factors exceed national averages. The Swedish Energy Agency's streamlined interconnection protocols for southern counties accelerate project commissioning. Agricultural land dual-use pilots near Kristianstad are testing agrivoltaic zoning exemptions under the Swedish Board of Agriculture framework.
Blekinge County
Industrial facilities in Karlskrona and Karlshamn pursue solar thermal integration with municipal district heating networks. EU Green Deal building performance standards mandate renewable thresholds for public structures by 2030. County administrative boards are pre-qualifying installation contractors through multi-year framework agreements.
Västra Götaland County
Gothenburg's commercial property owners bundle rooftop installations with envelope insulation upgrades to meet consolidated compliance deadlines. The National Electrical Safety Board's grid interconnection standards create procedural friction that extends development cycles. Soltech Energy Sweden AB anchors supplier relationships through specialized Nordic weather-load mounting systems.
Stockholm County
Energy storage deployment concentrates in Stockholm's commercial districts where grid-balancing contracts through Svenska kraftnät create ancillary service revenue streams. Municipal building portfolios require individualized structural assessments that delay procurement execution. Vattenfall AB leverages integrated utility platform advantages for large-scale project origination.
Småland Region
Växjö and Linköping utilities expand procurement for solar thermal collectors displacing biomass in district heating systems. Installer certification bottlenecks under National Electrical Safety Board requirements exceed current training pipeline capacity. Thin-film manufacturing specialists including Midsummer AB target building-integrated applications on structurally constrained public rooftops.
Sweden Solar Energy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Swedish solar value chain. The market structure bifurcates between utility-scale efficiency optimizers and building-integrated form factor innovators. Three strategic archetypes dominate: integrated utility platforms with proprietary site origination, specialized mounting system fabricators for Nordic climate loads, and thin-film manufacturers targeting weight-constrained applications. Competitive moves concentrate on framework agreement aggregation with county administrative boards and multi-year performance guarantee structures that transfer output risk to EPC contractors.
Among Stockholm-based integrated utilities, Vattenfall AB occupies a position anchoring large-scale development through captive grid access rights. Soltech Energy Sweden AB and Midsummer AB represent contrasting technology archetypes: the former exemplifies specialized hardware suppliers capturing commercial rooftop share through climate-adapted mounting systems, while the latter sits within the thin-film tier addressing building-integrated procurement criteria where aesthetic and structural constraints dominate vendor selection.
| Leading Market Players |
|---|
| Alight AB |
| Soltech Energy Sweden AB |
| Vattenfall AB |
| Eneo Solutions AB |
| Midsummer AB |
| Svea Solar AB |
| S-Solar AB |
| InnoVentum AB |
| Exeger Sweden AB |
| Others |
Value Network & Pricing Analysis
Polysilicon refining capacity utilization in Asian manufacturing hubs concentrates cost leverage among crystalline silicon module suppliers, compressing developer margins on fixed-price municipal contracts while establishing price floors for Nordic climate-certified equipment tiers. Scale advantages in wafer production cascade through the value chain, amplifying procurement power for utility-scale aggregators and squeezing specialized thin-film fabricators serving weight-constrained building-integrated segments.
Pricing Analysis
EU Green Deal compliance mandates dictate the pricing tier structure across Swedish solar procurement, separating premium-certified crystalline silicon modules from standard-tier alternatives through Swedish Energy Agency documentation requirements. Price differentiation hinges on Nordic climate testing certification and volume scale under county administrative board framework agreements. Cost compression in standard-tier crystalline silicon runs through polysilicon input volatility, while municipal buyers exhibit lowest price sensitivity due to compliance-driven procurement deadlines.
Supply Chain Analysis
Container availability fluctuations on Asia-North Europe trade lanes introduce inbound logistics cost variability for module imports, amplifying working capital requirements for Swedish distributors. Manufacturing concentrates in China, Vietnam, and Malaysia for crystalline silicon cells and modules, while lithium-ion battery systems draw from South Korean and Chinese cell production. Single-source vulnerability in polysilicon refining creates tariff exposure through potential trade remedy actions. Distribution runs through specialized Nordic climate equipment distributors with Swedish Energy Agency certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish solar energy operates as a regulatory-moat market where EU Green Deal entrenchment and municipal framework agreement switching costs protect incumbent positioning. The Swedish Energy Agency's certification protocols and county administrative board pre-qualification requirements create structural barriers that compound over multi-year delivery schedules.
For Market Incumbents: Compound framework agreement coverage with county administrative boards in Skåne and Västra Götaland to lock out emerging EPC competitors. Deepen captive supply relationships with Nordic climate-certified module suppliers before polysilicon volatility triggers margin compression. Prioritize output-guarantee clause standardization that transfers winter generation trough performance risk to contractor balance sheets. For New Entrants and Emerging Players: Swedish Energy Agency certification fast-tracks for thin-film building-integrated applications offer the most penetrable entry vector, as structural load constraints disqualify conventional crystalline silicon competitors. Target municipal rooftop segments in Stockholm and Gothenburg where aesthetic requirements and weight limitations dominate procurement criteria. Pursue agrivoltaic pilot partnerships with the Swedish Board of Agriculture to establish zoning exemption precedent before regulatory clarity hardens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated utility platforms with proprietary grid access rights and captive site origination capabilities over pure-play hardware suppliers. Long-term viability rests on regulatory entrenchment depth rather than manufacturing scale advantages. Monitor Swedish Energy Agency interconnection queue clearance velocity as the inflection signal for distributed generation deployment capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Consolidation | County administrative board aggregation transfers performance risk to EPC contractors through multi-year output guarantees. |
| Building-Integrated Certification Investment | Swedish Energy Agency protocols for thin-film applications create non-overlapping vendor bases from utility-scale competitors. |
| Agrivoltaic Zoning Pilot Expansion | Swedish Board of Agriculture exemptions enable dual-use deployment on southern farmland with superior irradiation profiles. |
| Energy Storage Convergence | Svenska kraftnät grid-balancing contracts capture ancillary service revenue streams in Stockholm commercial districts. |
| Installer Certification Pipeline Development | National Electrical Safety Board qualification expansion addresses contractor scarcity extending project commissioning timelines. |
Research Methodology
Desk research of EU regulatory filings, Swedish Energy Agency interconnection databases, and municipal procurement records preceded structured interviews with utility planning officers, EPC project developers, county administrative board procurement leads, and thin-film manufacturing specialists. Primary fieldwork with grid operators and distribution channel partners validated secondary data on deployment velocity and technology adoption patterns. Bottom-up installation volume aggregation triangulated against top-down national climate plan trajectory assessments.
Variance decomposition across technology type, end-user segment, installation architecture, and regional irradiation profile shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled include product category, customer scale tier, interconnection configuration, and service bundling intensity. CAGRs derived from unit economics analysis incorporating named capacity factor differentials and municipal procurement pipeline visibility. Forecast inputs incorporated Swedish Energy Agency certification queue dynamics and county-level zoning reform momentum.
Decision-makers should treat outputs as directional under sustained EU Green Deal compliance enforcement and stable polysilicon supply conditions; material deviation in either assumption would warrant model refresh. Specific risk factors include abrupt tariff imposition on Asian module imports and accelerated interconnection standard revisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Argentina Solar Energy Market