
 Sweden Renewable Energy Market | 2026-2036
Sweden Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Renewable Energy Market Analytics
Aftermarket service revenue from offshore wind turbine maintenance is reshaping margin distribution across the value chain. Vattenfall AB anchors the Nordic offshore pipeline with proprietary vessel logistics and grid interconnection expertise. OX2 AB specializes in development-to-divestiture models that transfer operational assets to infrastructure funds. Statkraft AS leverages its Norwegian hydropower balance sheet to finance Swedish wind expansion.
Sweden renewable energy encompasses electricity and heat generation from solar photovoltaic, onshore and offshore wind, biomass combustion, and run-of-river hydropower systems with typical turbine capacities ranging from 1.5 MW to 8 MW. These installations displace fossil-fired generation in district heating, industrial process heat, and baseload power while integrating with Nordic synchronous grid frequency requirements. Hydropower retains the dominant installed base and provides regulating power for wind intermittency, whereas offshore wind claims the fastest development queue as seabed leases multiply in the Baltic Sea. Solar photovoltaic segments occupy distributed rooftop niches in southern counties where irradiation exceeds 950 kWh per square meter annually.
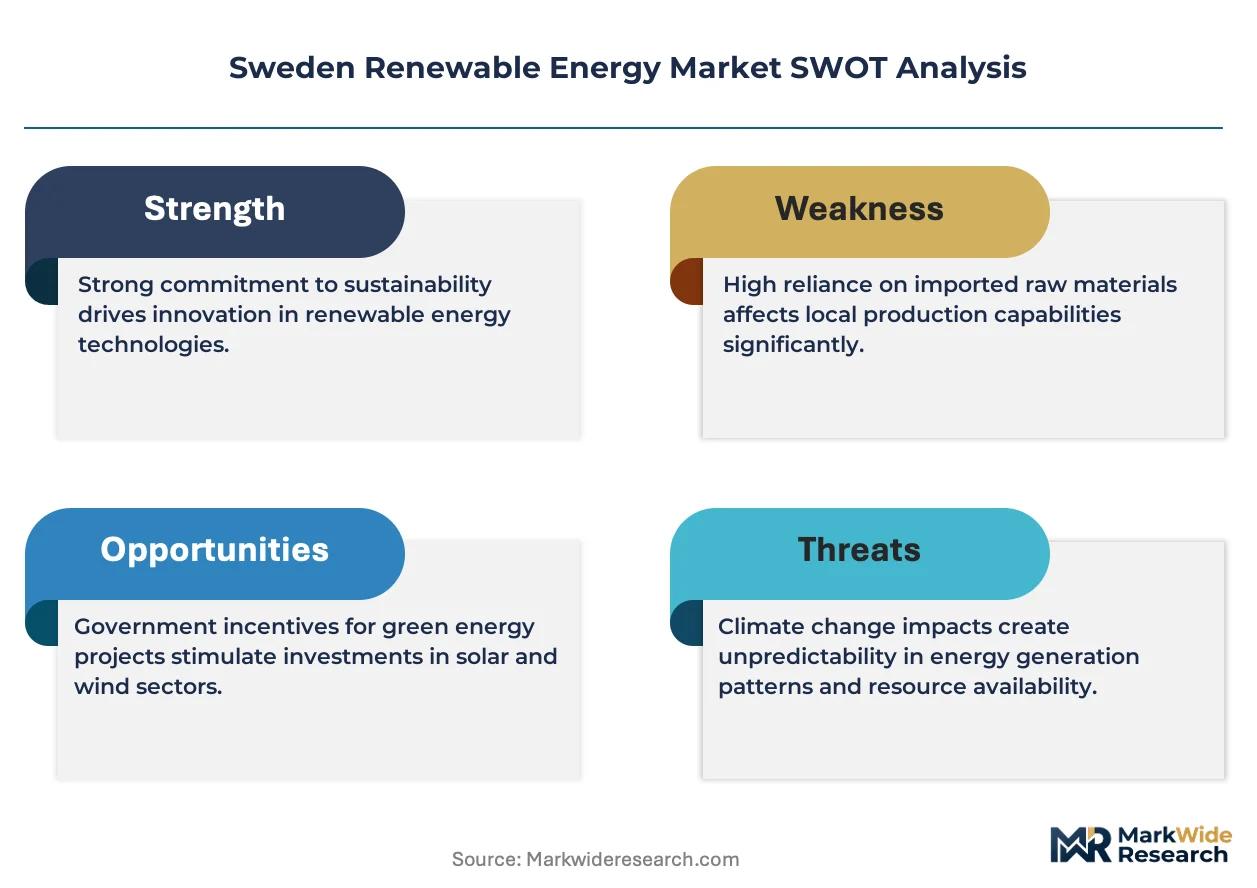
The Swedish Energy Agency implements auction mechanisms under the Electricity Certificate System, while the Environmental Protection Agency enforces habitat assessment rules for wind project permitting. EU Green Deal alignment pressures national carbon accounting toward stricter Scope 2 disclosure for corporate offtakers. Stakeholders must monitor grid reinforcement timelines and municipal veto rights that determine project realization speed.
Market Dynamics
Offshore wind permitting acceleration under Sweden's Green Industry Leap is compressing project development cycles while municipal veto rights create uneven approval velocities across county boundaries.
Growth Catalysts
- EU Green Deal alignment:Corporate Scope 2 disclosure mandates pressure Swedish industrial offtakers toward renewable power purchase agreements. Steel and cement producers in Norrland seek baseload contracts.
- Biomass supply integration:Stockholm's district heating network absorbs increasing volumes of forestry residue. CHP plants retrofit for higher efficiency.
- Onshore wind clustering:Luleå and Piteå host expanding turbine arrays. Grid reinforcement timelines determine absorption capacity.
Market Restraints
- Grid interconnection queues:Svenska Kraftnät reinforcement schedules lag generation capacity additions. Bottlenecks concentrate in northern transmission corridors.
- Seabed lease scarcity:Swedish Maritime Administration parcel allocation limits Baltic Sea development density. Competing marine interests constrain site availability.
- Geothermal drilling costs:Deep borehole expenses in Gothenburg district heating expansion strain municipal finance capacity. Exploration risk transfers to developers.
Strategic Opportunities
- Power-to-X deployment:Norrland wind clusters feed hydrogen electrolysis for industrial feedstock. Steel decarbonization creates anchor demand.
- Floating offshore foundations:Deeper Baltic waters beyond fixed-bottom viability open to novel substructure designs. Demonstration projects attract technology suppliers.
- Behind-the-meter solar:Southern counties with 950+ kWh per square meter irradiation host commercial rooftop installations. Manufacturing facilities self-supply peak demand.
Industry Challenges
- Marine habitat assessment timelines:Swedish Environmental Protection Agency permitting requires seasonal bird and bat surveys. Seasonal restrictions compress viable construction windows.
- Specialized vessel availability:Heavy-lift jack-up units for turbine installation command premium day rates. Nordic fleet capacity constraints affect project scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Renewable Energy Market |
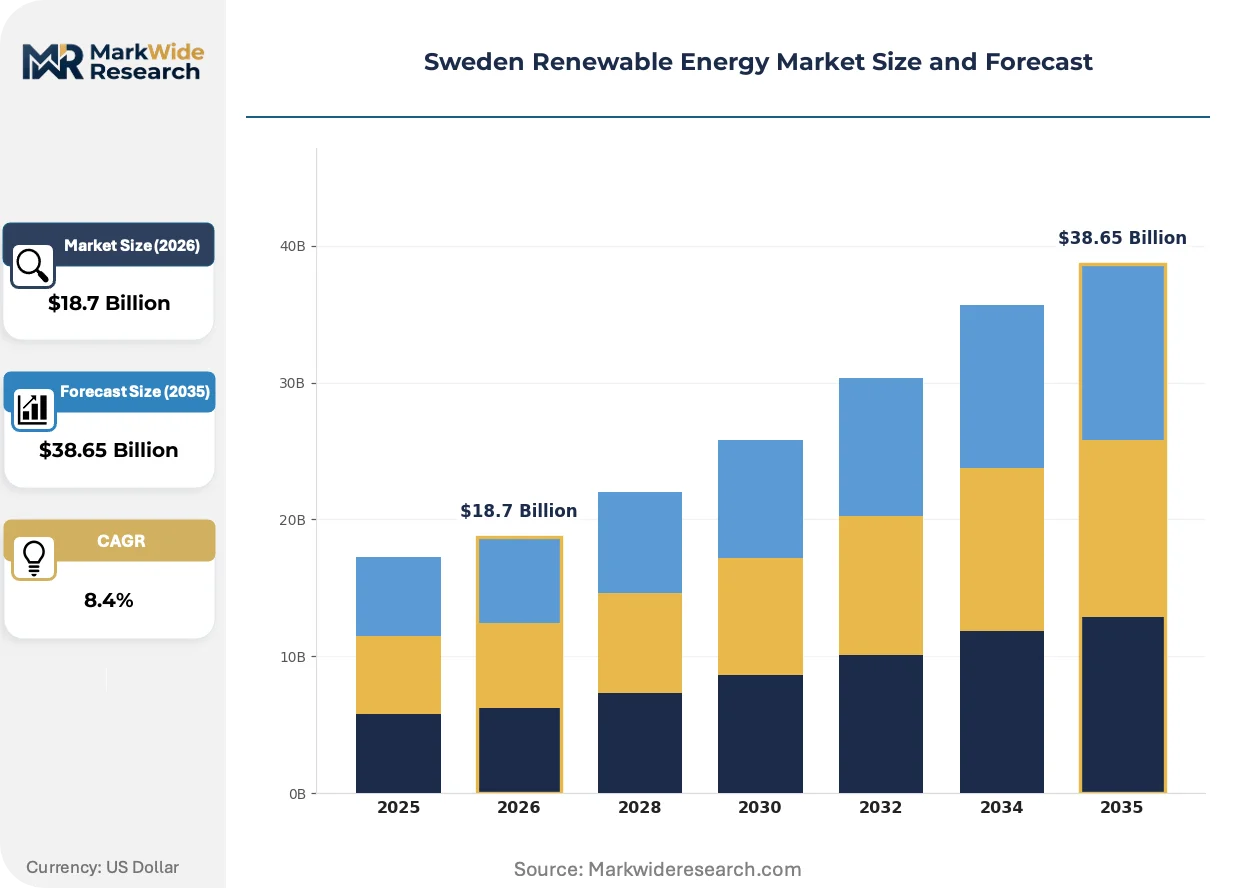
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Biomass, Hydropower End User: Residential, Commercial, Industrial, Government Technology: Photovoltaic, Onshore Wind, Offshore Wind, Bioenergy Installation Type: Grid-Connected, Off-Grid, Hybrid, Community-Based |
| Companies Covered | Uniper SE, Orrön Energy, Vattenfall AB, Neoen Company, BayWa r.e. GmbH, Fortum Oyj, OX2 AB, Mainstream Renewable Power, Statkraft AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Renewable Energy Market Evolving Landscape
Digitalization of grid operations and turbine monitoring systems is compressing maintenance response times while predictive analytics reshape asset management economics across the Swedish renewable fleet.
Digital twin technology is virtualizing offshore wind farm operations by creating real-time structural and performance replicas of turbine systems. Vattenfall and OX2 deploy these models for fatigue monitoring and component replacement scheduling. The technology is virtualizing traditional calendar-based maintenance into condition-driven intervention protocols.
Sweden's Electricity Certificate System auction mechanisms now incorporate hourly price signals rather than annual baseload contracts. The Swedish Energy Agency redesigned procurement to favor flexibility-capable technologies. Hydropower operators and battery developers capture premium pricing for regulating power services.
Industrial offtakers in pulp and paper are consolidating procurement through multi-year direct power purchase agreements rather than utility intermediation. Skoghall and Östrand mills negotiate directly with wind developers for 10-15 year supply contracts. This disintermediation concentrates buyer power while compressing developer margins.
Sweden Renewable Energy Market Segmentation
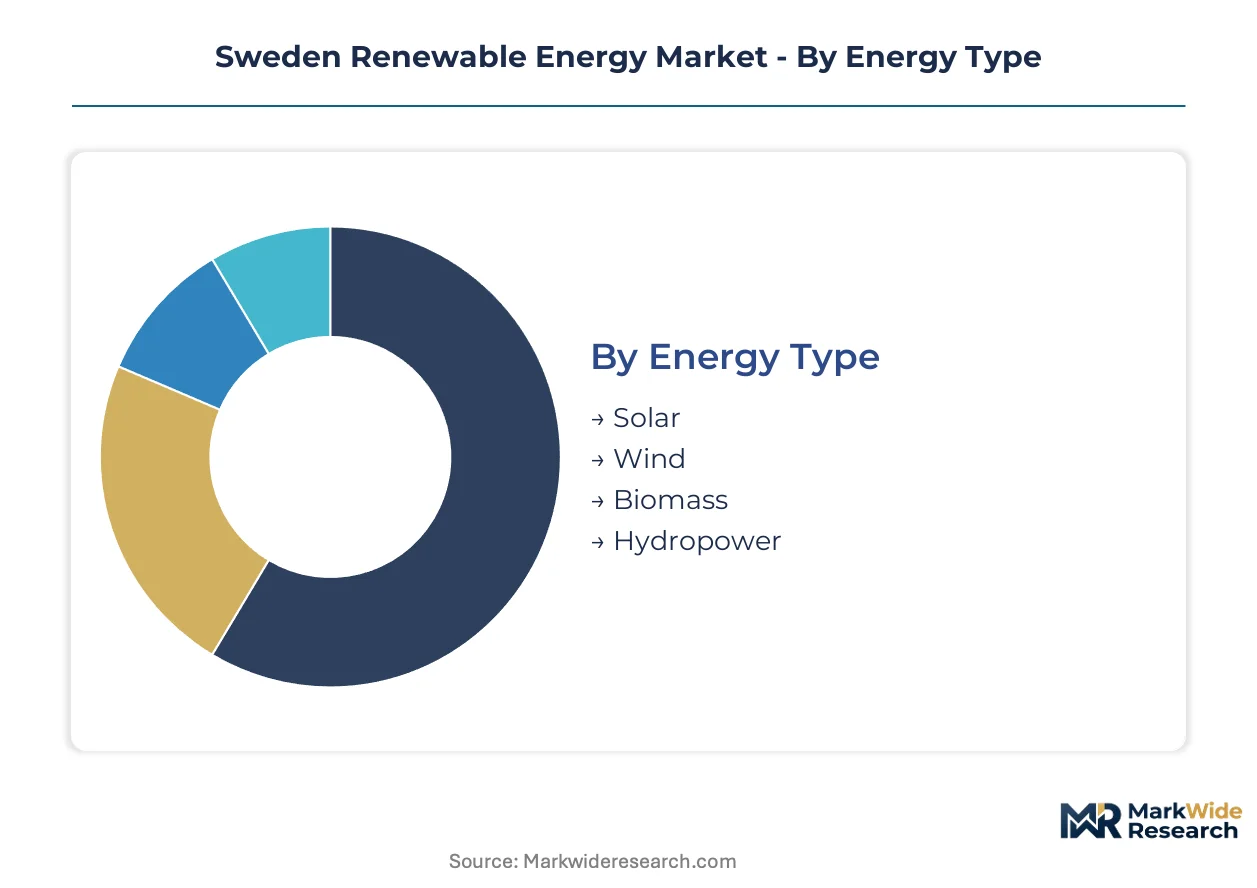
Sweden's renewable energy market fragments across generation technologies, customer archetypes, and grid integration models. Each segmentation axis reveals distinct investment intensities, permitting pathways, and offtake contracting structures that shape developer strategy.
Energy Type:
Sweden's generation mix spans baseload, intermittent, and dispatchable resources serving district heating networks and Nordic grid balancing.
- Wind:Turbine arrays in Norrland and Baltic Sea zones deliver bulk power for industrial decarbonization. Luleå and Piteå clusters absorb transmission capacity expansions while seabed leases constrain Baltic development density.
- Hydropower:Run-of-river installations with 1.5-8 MW turbine capacities provide regulating power for wind intermittency. Swedish Energy Agency auction redesign favors flexibility-capable assets with premium pricing for frequency control.
- Solar:Distributed rooftop systems concentrate in southern counties where annual irradiation exceeds 950 kWh per square meter. Manufacturing facilities self-supply peak demand behind the meter.
- Biomass:Forestry residue combustion feeds Stockholm and Gothenburg district heating networks. CHP plant retrofits improve thermal efficiency for municipal heat contracts.
Established volume favors hydropower; emerging adoption favors wind.
End User:
Customer scale determines contract duration, credit risk profiles, and direct procurement sophistication across the Swedish market.
- Industrial:Steel and cement producers in Norrland negotiate 10-15 year direct power purchase agreements for baseload supply. Skoghall and Östrand mills disintermediate utility offtake to concentrate buyer power.
- Commercial:Manufacturing facilities deploy behind-the-meter solar to hedge peak pricing exposure. Southern county irradiation profiles support rooftop economics without subsidy dependency.
- Residential:Distributed photovoltaic adoption concentrates in owner-occupied single-family housing. Municipal veto rights and grid connection queues slow suburban deployment.
- Government:Public sector procurement aggregates demand across municipal and county administrative boundaries. Swedish Environmental Protection Agency habitat assessments constrain site selection for publicly owned projects.
Contract duration extends longest for industrial offtake; installation velocity runs highest in commercial self-supply.
Technology:
Technology choice locks in capital intensity, maintenance protocols, and revenue exposure to hourly price signals.
- Offshore Wind:Fixed-bottom and floating substructure designs target deeper Baltic waters beyond seabed lease constraints. Heavy-lift jack-up vessel availability commands premium day rates that compress project scheduling.
- Photovoltaic:Silicon-based modules dominate distributed applications with standardized balance-of-system components. Digital twin deployment remains limited compared to turbine assets.
- Onshore Wind:Hub heights and rotor diameters expand to capture Norrland wind resource profiles. Grid reinforcement timelines determine absorption capacity in northern transmission corridors.
- Bioenergy:Combustion and gasification pathways process forestry residue for combined heat and power output. Stockholm's district heating network anchors demand volume with long-term fuel supply contracts.
Capital intensity peaks with offshore wind; operational maturity concentrates in bioenergy.
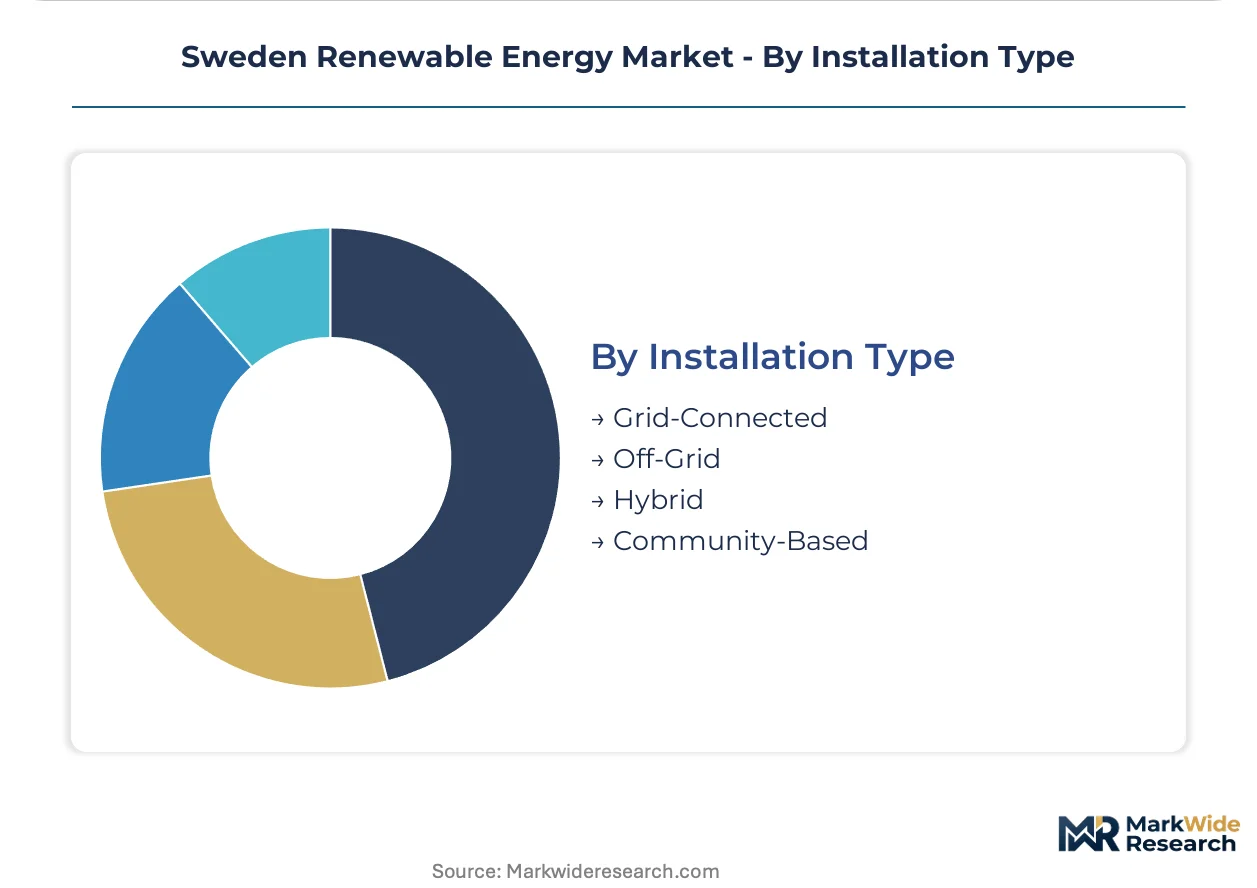
Installation Type:
Grid integration architecture shapes permitting complexity, financing structures, and community acceptance dynamics.
- Grid-Connected:Utility-scale projects queue for Svenska Kraftnät reinforcement schedules that lag generation additions. Bottlenecks concentrate in northern corridors serving Norrland wind clusters.
- Community-Based:Cooperative ownership models aggregate residential capital for shared solar and wind assets. Municipal participation rights vary across county boundaries.
- Hybrid:Wind-solar-battery configurations optimize capacity factor and grid service revenue. Swedish Energy Agency hourly price signals reward flexibility-capable installations.
- Off-Grid:Remote industrial sites and island installations displace diesel generation. Limited addressable market constrains specialist supplier economics.
Permitting velocity favors community-based models; revenue optimization favors hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish industrial buyers in Norrland show the least price elasticity for baseload renewable contracts, while southern commercial solar adopters exhibit acute sensitivity to payback periods and grid connection costs.
Norrland
Steel decarbonization and hydrogen electrolysis anchor demand for wind-derived power in Sweden's northernmost region. The Swedish Energy Agency's Electricity Certificate System auctions favor flexibility-capable assets with premium pricing for frequency regulation. Luleå and Piteå host expanding onshore wind clusters where grid reinforcement timelines determine absorption capacity.
Svealand
Stockholm's district heating network drives biomass and geothermal integration for municipal heat contracts. The Environmental Protection Agency enforces habitat assessment rules that compress viable construction windows for new projects. The capital region concentrates service providers and engineering consultancies supporting nationwide project development.
Götaland
Manufacturing facilities in southern counties deploy behind-the-meter solar where annual irradiation exceeds 950 kWh per square meter. EU Green Deal Scope 2 disclosure mandates pressure industrial offtakers toward direct power purchase agreements. Gothenburg's district heating expansion strains municipal finance capacity with deep borehole exploration costs.
Baltic Sea Offshore Zones
Seabed lease allocation from the Swedish Maritime Administration constrains development density despite accelerating permitting under the Green Industry Leap. Heavy-lift jack-up vessel availability commands premium day rates that compress project scheduling. Floating foundation demonstration projects attract technology suppliers for deeper waters beyond fixed-bottom viability.
Sweden Renewable Energy Market Competitive Landscape
Capability concentration sits with integrated utilities possessing proprietary grid interconnection expertise; scale advantage sits with specialized developers executing development-to-divestiture models. The market structures around three tiers: state-backed incumbents with balance sheet capacity, independent developers with project origination speed, and infrastructure funds acquiring operational assets. Strategic archetypes include vertical integrators controlling vessel logistics, platform specialists monetizing permitting acceleration, and financial buyers seeking yield-stable cash flows. Competitive moves center on portfolio diversification into Power-to-X value chains and strategic partnerships securing seabed lease access.
Within the Nordic integrated utility tier, Vattenfall AB and Statkraft AS exemplify contrasting approaches to Swedish market participation. Vattenfall anchors offshore pipeline development through captive grid expertise and proprietary logistics infrastructure. Statkraft leverages Norwegian hydropower balance sheet strength to finance wind expansion south of its domestic border. Among independent developers, OX2 AB occupies a position exemplifying the development-to-divestiture archetype, transferring operational assets to infrastructure funds upon reaching commercial operation.
| Leading Market Players |
|---|
| Uniper SE |
| Orrön Energy |
| Vattenfall AB |
| Neoen Company |
| BayWa r.e. GmbH |
| Fortum Oyj |
| OX2 AB |
| Mainstream Renewable Power |
| Statkraft AS |
| Others |
Value Network & Pricing Analysis
Norrland wind clusters anchor capacity expansion for industrial offtake, concentrating supply-side leverage among developers with secured grid interconnection agreements and long-term power purchase contracts. This geographic concentration translates into asymmetric pricing power where steel and cement producers absorb baseload premiums while commercial solar adopters in southern counties face acute payback sensitivity.
Pricing Analysis
Aftermarket service revenue from offshore wind turbine maintenance drives lifetime value capture across the Swedish fleet. Project developers structure pricing around long-term offtake contracts with industrial buyers, differentiating through grid balancing capability and habitat permitting velocity. Pricing pressure stems from municipal veto rights that compress viable development windows and extend approval timelines. Steel producers in Norrland exhibit the least price elasticity for baseload renewable contracts, while manufacturing facilities deploying behind-the-meter solar in Götaland show acute sensitivity to grid connection costs and irradiation-dependent payback periods.
Supply Chain Analysis
Heavy-lift jack-up vessel operators in Denmark, Germany, and the Netherlands hold concentrated capacity for Baltic Sea turbine installation. Swedish offshore wind development draws from specialized steel fabrication in Poland, blade manufacturing in Spain, and power electronics from Germany. Single-source vulnerability runs through Nordic vessel availability where premium day rates compress project scheduling. Distribution runs through utility procurement desks and direct corporate power purchase agreements with industrial offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's renewable energy market rewards developers with proprietary grid interconnection expertise and penalizes entrants lacking habitat assessment capabilities or municipal relationship networks. The scarcity of heavy-lift installation vessels and qualified environmental surveyors creates durable capability gaps that shape competitive outcomes.
For Market Incumbents: Insulate offshore pipeline value by securing multi-year vessel charter agreements before competitors lock Nordic fleet capacity. Develop in-house environmental assessment capabilities to compress Swedish Environmental Protection Agency permitting timelines and defend margin position against development-to-divestiture specialists transferring assets to infrastructure funds. For New Entrants and Emerging Players: Establish a beachhead in behind-the-meter commercial solar across southern counties where irradiation profiles support economics without subsidy dependency. Target manufacturing facilities seeking peak demand self-supply through direct equipment procurement rather than utility intermediation, leveraging standardized balance-of-system components for rapid deployment velocity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors infrastructure funds acquiring operational wind assets with contracted revenue streams and established grid connections. Long-term viability hinges on portfolio exposure to Power-to-X value chains where hydrogen electrolysis creates anchor demand from steel decarbonization. Monitor Svenska Kraftnät reinforcement schedule announcements as inflection indicators for absorption capacity constraints in northern transmission corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Green Industry Leap acceleration compresses permitting timelines for Baltic Sea seabed leases. |
| Power Purchase Agreement Execution | Direct 10-15 year contracts with Skoghall and Östrand mills disintermediate utility offtake. |
| Grid Interconnection Partnership | Proprietary relationships with Svenska Kraftnät secure absorption capacity in Norrland corridors. |
| Floating Foundation Technology Licensing | Deeper Baltic waters beyond fixed-bottom viability attract demonstration project investment. |
| Green Certification Program Alignment | EU Green Deal Scope 2 disclosure mandates pressure corporate procurement toward verified renewable supply. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation. Bottom-up capacity and demand estimates triangulated with top-down regulatory flow analysis. Secondary sources included Swedish Energy Agency auction records, Svenska Kraftnät transmission expansion filings, EU Green Deal implementation directives, and Nordic synchronous grid frequency requirement documentation.
Demand-supply balance modeling anchored the forecast framework across the projection horizon. Segmentation dimensions spanned generation technology, end-user scale, grid integration architecture, and regional regulatory cluster. CAGRs derived from capacity addition pipelines, retirement schedules, and hourly price signal evolution under the Electricity Certificate System redesign. Forecast inputs incorporated seabed lease allocation timelines and municipal veto right variation across county boundaries.
Stress conditions across vessel availability constraints, grid reinforcement delays, and habitat assessment seasonal restrictions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding permitting acceleration under the Green Industry Leap and industrial offtake contract tenor preferences. Quarterly review of Svenska Kraftnät corridor expansion announcements and Swedish Maritime Administration lease allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Autoclave Market
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Solar EPC Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Israel Renewable Energy Market