
 Substation Testing Equipment Market | 2026-2036
Substation Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Substation Testing Equipment Market Analytics
Utility procurement consolidation is rebalancing vendor relationships across the substation testing equipment landscape. ABB Ltd. leverages its integrated digital substation portfolio to secure multi-year framework agreements with consolidated buyers. Siemens AG anchors its position through deep domain expertise in protection relay testing systems. Megger Group Limited specializes in portable insulation resistance solutions that serve fragmented maintenance contractor networks.
Substation testing equipment encompasses diagnostic instruments used to verify electrical integrity, timing accuracy, and insulation performance within high-voltage infrastructure, typically operating across voltage classes from distribution-level 4 kV through transmission-grade 765 kV with measurement precision demands of ±0.1% or tighter. These instruments prevent catastrophic failures by detecting incipient faults in transformers, circuit breakers, and protection relays before operational degradation cascades into grid outages. Transformer testing equipment commands the largest revenue pool given asset longevity requirements and scheduled maintenance cycles, while automated test systems represent the fastest-expanding technology segment as utilities pursue labor reduction and repeatability. Digital test instruments are displacing analog equivalents in new procurement specifications, though legacy analog equipment persists in budget-constrained emerging markets.
IEC 61850 compliance mandates from the International Electrotechnical Commission and regional grid codes enforced by FERC in the United States and CEI in Italy are elevating product certification requirements and tightening market access for non-compliant suppliers. IEEE C57.152 transformer maintenance standards and NETA acceptance testing specifications further define performance benchmarks that shape R&D investment priorities. Stakeholders must monitor the divergence between digital-native testing platforms and legacy asset bases as interoperability requirements intensify and procurement specifications harden around unified data architectures.
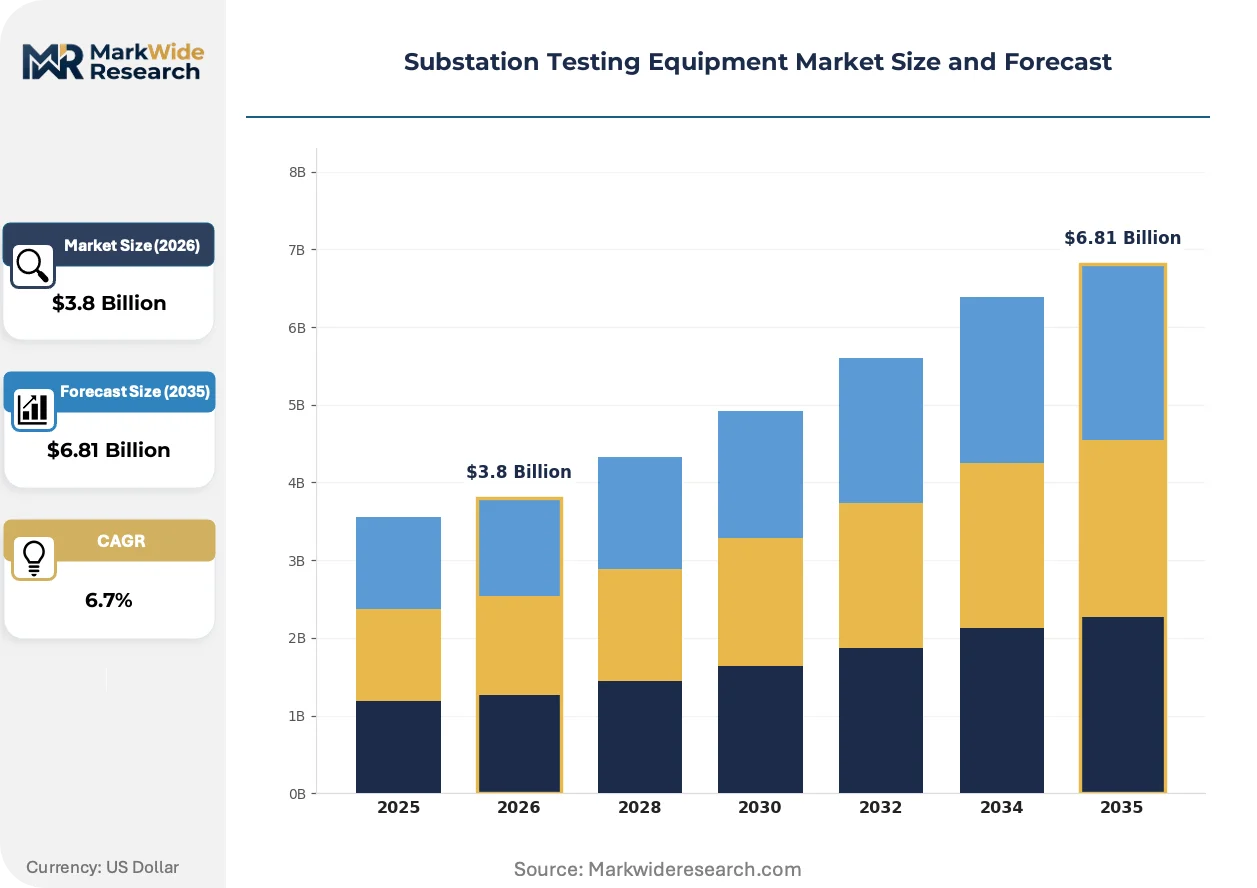
Market Dynamics
Grid digitalization programs across transmission utilities are compressing replacement cycles for analog testing instruments while elevating demand for IEC 61850-compliant diagnostic platforms that interface with intelligent electronic devices.
Growth Catalysts
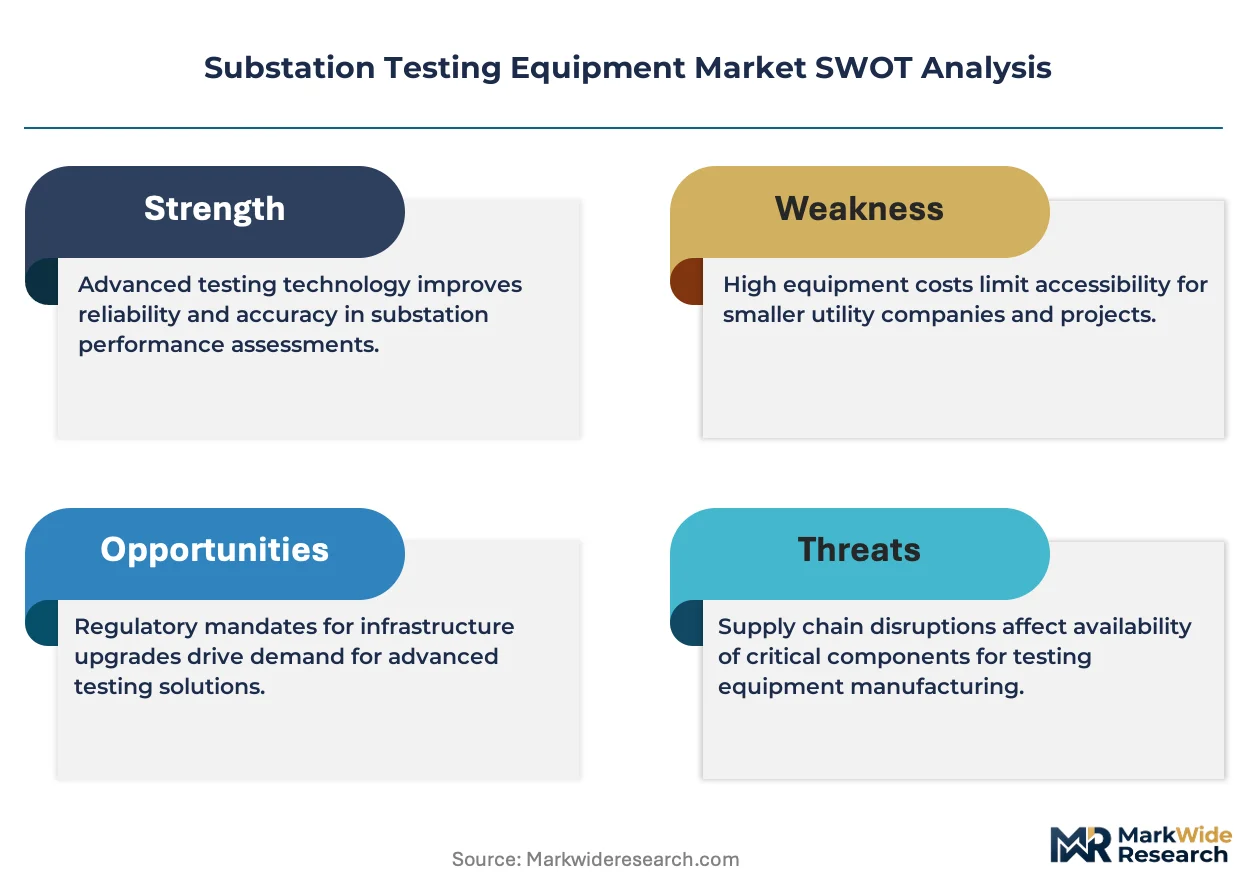
- Grid Modernization Mandates:FERC Order 2222 in the United States accelerates distributed energy resource integration, requiring upgraded protection relay testing protocols at substation interconnection points.
- Transformer Fleet Aging:North American utilities face replacement waves for assets installed during the 1960s-1970s buildout, driving scheduled diagnostic testing for insulation integrity and turns ratio verification.
- Digital Twin Deployment:Real-time asset modeling requires continuous sensor validation, expanding demand for automated test systems that feed calibrated data into predictive maintenance algorithms.
Market Restraints
- Copper and Rare Earth Input Volatility:Testing instrument enclosures and precision winding components face cost pressure from commodity price swings in Chilean copper and Chinese-processed rare earth magnets.
- Certification Timeline Friction:IEC 61850 Edition 2.1 compliance testing extends product launch cycles by 8-14 months for smaller manufacturers lacking accredited laboratory partnerships.
- Used Equipment Arbitrage:Refurbished analog insulation testers from decommissioned European utilities flood secondary markets in Southeast Asia, depressing new equipment pricing power.
Strategic Opportunities
- Offshore Wind Interconnection:Germany's North Sea expansion and China's coastal buildout create demand for marine-grade testing systems resistant to salt corrosion and humidity cycling.
- Utility-Scale Storage Integration:Battery energy storage systems require specialized protection verification, opening segments for hybrid AC/DC test equipment manufacturers.
- Skills-Based Distribution:Online certification platforms enable direct-to-technician sales bypassing traditional distributor markups in fragmented maintenance contractor networks.
Industry Challenges
- Field Technician Shortage:Experienced relay testing specialists retire faster than vocational programs in the United States and Germany can replace them, degrading service quality.
- Legacy Asset Interoperability:Serial communication protocols in pre-2000 protection relays resist integration with modern Ethernet-based test sets, forcing dual-inventory maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Substation Testing Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformer Testing Equipment, Circuit Breaker Test Sets, Insulation Resistance Testers, Relay Test Equipment Technology: Smart Testing Devices, Analog Test Equipment, Digital Test Instruments, Automated Test Systems End User: Utilities, Industrial Plants, Research Laboratories, Maintenance Contractors Deployment: On-site Testing, Laboratory Testing, Remote Monitoring, Portable Solutions |
| Companies Covered | General Electric, Eaton plc., ABB Ltd., Emerson Electric, Schweitzer Engineering Laboratories, Siemens AG, Honeywell International Inc., Megger Group Limited, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Substation Testing Equipment Market Evolving Landscape
Diagnostic instrumentation is converging with software-defined measurement architectures, compressing hardware replacement cycles while expanding recurring revenue streams through subscription-based calibration and analytics services.
Automated test systems with integrated IEC 61850 client functionality are overtaking manual benchtop instruments in utility procurement specifications. Transmission operators in China and Germany now require automated breaker timing sequences that eliminate human transcription errors. This shift is compressing margins for manufacturers lacking software development capabilities while rewarding vendors with integrated digital substation portfolios.
The European Union's F-Gas Regulation is phasing down sulfur hexafluoride (SF6) emissions from switchgear, forcing test equipment suppliers to adapt gas handling and leakage detection protocols. Manufacturers must certify instruments for handling alternative insulation mediums including fluoronitrile mixtures and vacuum interrupters. German TSOs and Italian distribution utilities are earliest adopters, rewriting maintenance specifications to address new gas properties and decomposition byproducts.
Consolidated procurement frameworks among merged utilities are unbundling after-sales service from equipment sales. Large buyers in the United States now negotiate separate multi-year calibration contracts with third-party metrology labs rather than captive vendor service departments. This fragmentation is visible most acutely among investor-owned utilities in Texas and California, where procurement autonomy has shifted to centralized corporate engineering functions.
Substation Testing Equipment Market Segmentation
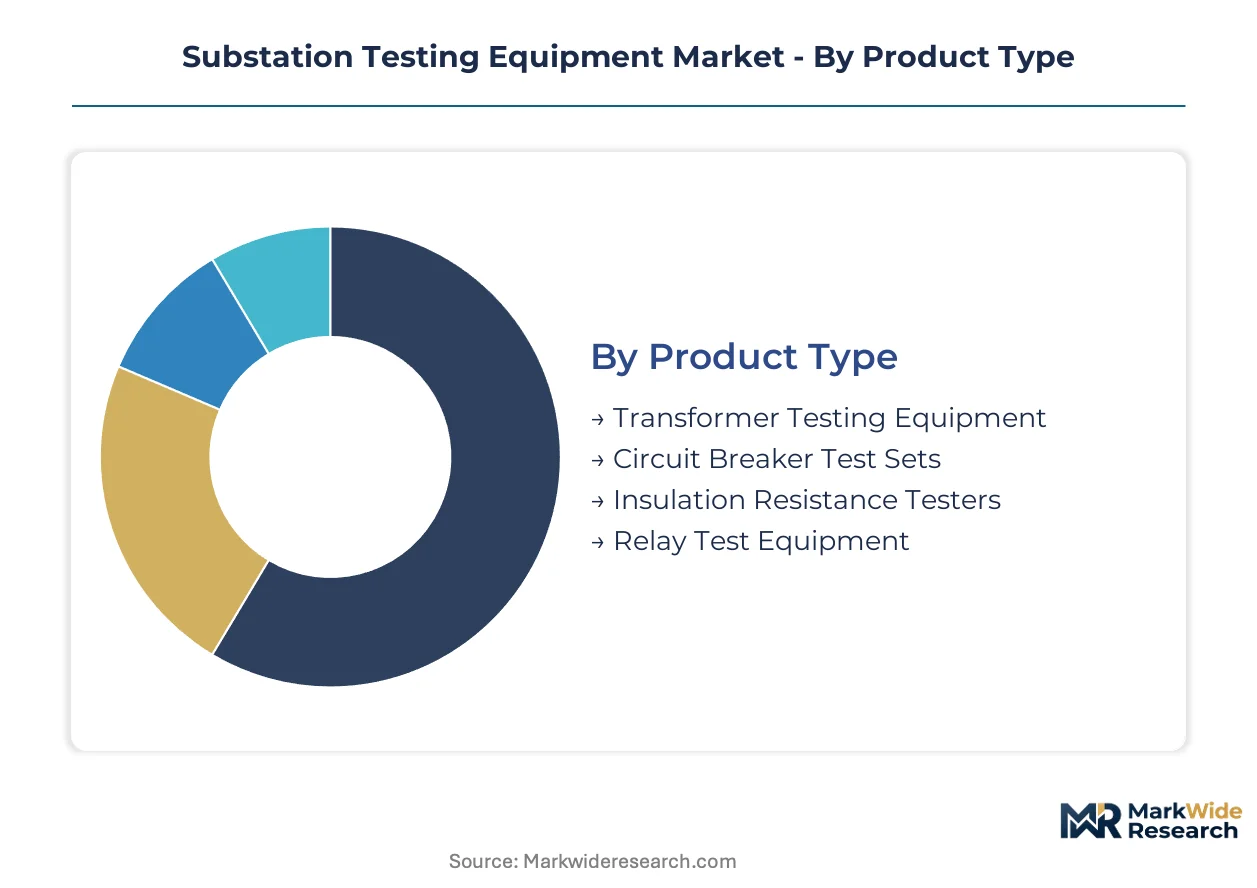
Equipment segmentation in substation testing reflects divergent procurement patterns between centralized utility engineering departments and fragmented contractor networks. Technology tiers and deployment models carry distinct margin profiles that reshape vendor go-to-market strategies across voltage classes and geographic markets.
Product Type:
Technical specification hierarchies separate scheduled maintenance protocols from condition-based monitoring applications.
- Transformer Testing Equipment:Instruments verify turns ratio, winding resistance, and dissolved gas analysis for assets spanning distribution through extra-high-voltage classes. Demand concentrates among North American utilities facing 1960s-1970s fleet replacement waves where insulation integrity validation prevents catastrophic failure. IEC 61850 integration requirements are elevating procurement specifications for automated tap-changer verification systems.
- Circuit Breaker Test Sets:Timing analyzers and motion recorders validate mechanical operation and contact wear in SF6 and vacuum interrupter technologies. German transmission system operators are driving adoption of marine-grade variants for North Sea offshore wind interconnection points where salt corrosion resistance is mandatory. F-Gas Regulation compliance is forcing adaptation of gas handling protocols for alternative insulation mediums.
- Insulation Resistance Testers:Portable megohmmeters serve fragmented maintenance contractor networks with 5 kV through 15 kV output ranges. Megger Group Limited anchors this segment through distributor relationships in emerging markets.
- Relay Test Equipment:Protection relay test sets verify overcurrent, distance, and differential schemes with ±0.1% timing precision. Siemens AG maintains position through deep domain expertise in microprocessor-based relay validation.
Mature deployment sits with Transformer Testing Equipment. Newer deployment is concentrated in Circuit Breaker Test Sets.
Technology:
Cost tier stratification separates digital-native platforms from legacy analog inventories in procurement specifications.
- Automated Test Systems:Software-defined architectures eliminate human transcription errors through integrated IEC 61850 client functionality and automated sequence execution. Chinese and German transmission operators now mandate these systems for breaker timing verification. Subscription-based calibration services are expanding recurring revenue streams beyond hardware replacement cycles.
- Digital Test Instruments:Microprocessor-based measurement platforms with Ethernet connectivity displace analog equivalents in utility procurement specifications. United States investor-owned utilities in Texas and California are consolidating procurement frameworks around unified data architectures that resist serial protocol legacy assets.
- Smart Testing Devices:Cloud-connected instruments feed calibrated data into predictive maintenance algorithms for digital twin deployment. Real-time asset modeling demands continuous sensor validation that manual benchtop instruments cannot deliver.
- Analog Test Equipment:Electromechanical measurement platforms persist in budget-constrained emerging markets and secondary equipment arbitrage channels. Refurbished units from decommissioned European utilities flood Southeast Asian markets.
Volume concentration favors Digital Test Instruments. Margin expansion concentrates in Automated Test Systems.
End User:
Customer type determines procurement autonomy versus centralized engineering control in equipment specification.
- Utilities:Vertically integrated transmission and distribution operators with consolidated procurement frameworks negotiate multi-year framework agreements. FERC Order 2222 mandates are accelerating protection relay testing protocol upgrades at distributed energy resource interconnection points.
- Maintenance Contractors:Fragmented field service networks purchase portable solutions through distributor channels with skills-based certification requirements. Online training platforms are enabling direct-to-technician sales bypassing traditional markup structures.
- Industrial Plants:Cogeneration and heavy manufacturing facilities maintain captive substation assets requiring periodic diagnostic verification. Scheduled maintenance cycles align with production downtime windows rather than grid reliability mandates.
- Research Laboratories:University and national laboratory facilities support standards development and forensic failure analysis with precision reference-grade instrumentation. IEEE C57.152 and NETA specifications originate from this user tier.
Procurement scale concentrates with Utilities. Specification influence resides with Research Laboratories.
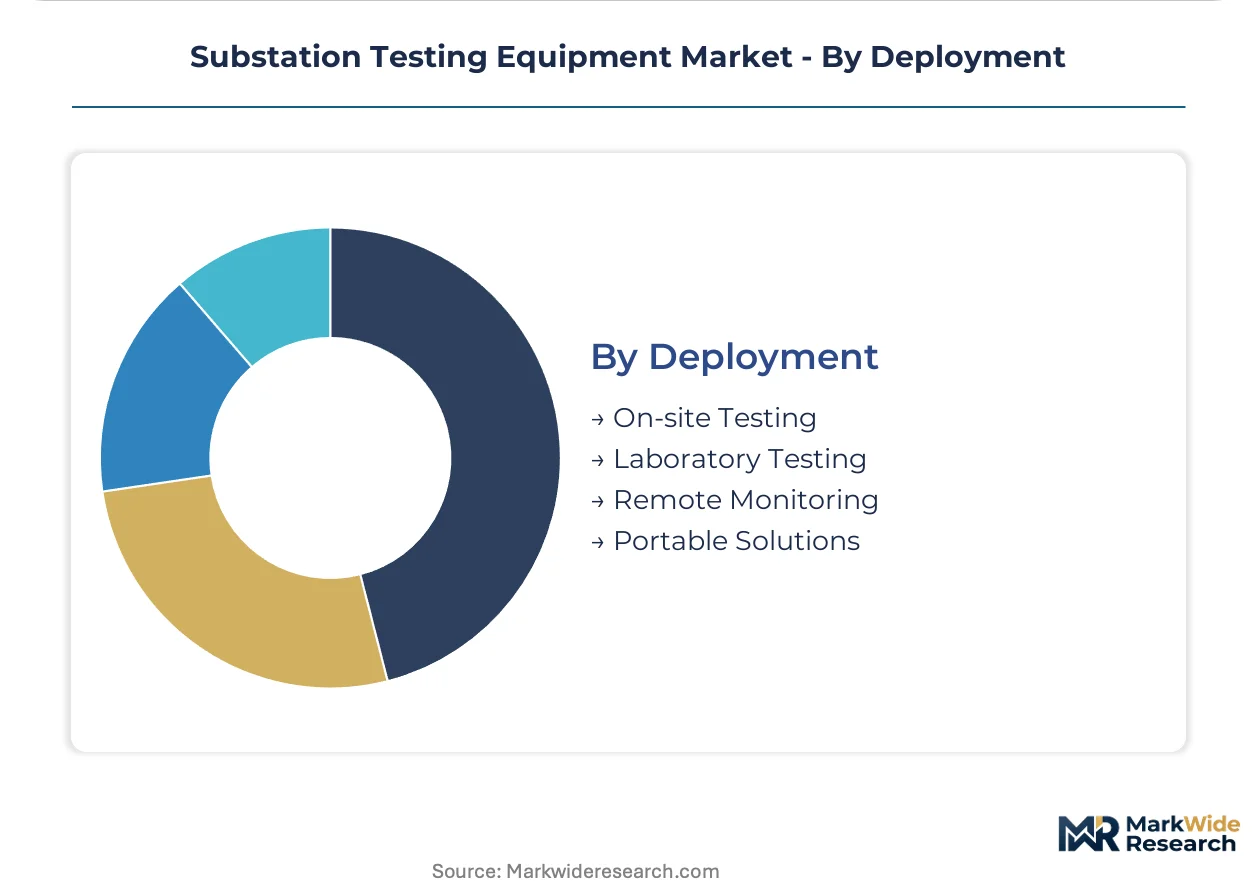
Deployment:
Application context separates field-portable requirements from controlled laboratory environments.
- On-site Testing:Mobile test sets with battery operation and ruggedized enclosures serve energized substation environments where asset removal is economically prohibitive. Field technician shortages in the United States and Germany are degrading service quality and elevating demand for automated systems.
- Portable Solutions:Lightweight instruments under 15 kg enable single-technician deployment for distribution-level verification. Maintenance contractor networks favor these units for travel efficiency across dispersed asset bases.
- Remote Monitoring:Permanently installed sensors with cellular or fiber backhaul support continuous condition assessment without site visits. Digital twin deployment is expanding this segment for critical transmission assets.
- Laboratory Testing:Climate-controlled facilities with precision reference standards support factory acceptance testing and forensic analysis. Factory floor space constraints are limiting expansion of high-voltage test bays.
Operational necessity anchors On-site Testing. Investment growth flows to Remote Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility grid modernization investments concentrate in the United States, China, and Germany, where transmission operators deploy IEC 61850-compliant diagnostic platforms at scale. FERC mandates, dual carbon targets, and the EU Green Deal are reshaping procurement specifications across these priority markets.
United States
FERC Order 2222 mandates distributed energy resource integration, forcing protection relay testing upgrades at interconnection points. Investor-owned utilities in Texas and California consolidate procurement through centralized corporate engineering functions. The Pacific Northwest hosts advanced digital twin pilot programs for continuous sensor validation.
China
Dual carbon goals accelerate offshore wind buildout along coastal provinces, creating demand for marine-grade testing systems. MIIT standards enforce domestic certification requirements that favor local supply chains. The Yangtze River Delta clusters transmission automation manufacturing with integrated diagnostic platform production.
Germany
The EU F-Gas Regulation phases down SF6 emissions, forcing test equipment adaptation for alternative insulation mediums. Transmission system operators rewrite North Sea interconnection specifications for salt-corrosion-resistant instruments. Bavaria anchors industrial demand through heavy manufacturing and cogeneration facility networks.
India
CEA grid codes mandate protection system verification for renewable energy zones under construction. State transmission utilities in Maharashtra and Gujarat deploy portable diagnostic sets through fragmented maintenance contractor networks. The National Smart Grid Mission elevates procurement specifications for automated test sequences.
Japan
METI energy security priorities drive transformer fleet diagnostic intensity for aging 1960s-1970s infrastructure. Utility consolidation around Tokyo Electric and Chubu Electric compresses vendor relationships toward framework agreements. Kansai region industrial plants maintain captive substation assets requiring periodic verification cycles.
Substation Testing Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined measurement architectures and subscription calibration services. The vendor base stratifies across integrated digital substation portfolios, portable insulation specialists, and protection relay domain experts. Strategic archetypes include hardware-centric incumbents, software-native challengers, and regional maintenance service integrators. Competitive moves center on multi-year framework agreement negotiations and third-party metrology lab partnerships that unbundle after-sales service from equipment sales.
Among diversified industrial conglomerates, General Electric and Siemens AG occupy positions representing integrated infrastructure portfolio breadth. ABB Ltd. exemplifies the digital substation specialist archetype with unified data architecture offerings. Megger Group Limited anchors the portable diagnostic segment through distributor channel relationships. These three entities represent distinct competitive vectors: scale-driven platform integration, automation software depth, and fragmented network accessibility.
| Leading Market Players |
|---|
| General Electric |
| Eaton plc. |
| ABB Ltd. |
| Emerson Electric |
| Schweitzer Engineering Laboratories |
| Siemens AG |
| Honeywell International Inc. |
| Megger Group Limited |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Software-defined measurement architectures are compressing hardware replacement cycles while simultaneously concentrating production among vendors with captive calibration service networks, tightening margin structures for analog-equipment specialists and elevating pricing power for integrated digital platform providers.
Pricing Analysis
Volume concentration favors portable insulation testers serving fragmented maintenance contractor networks, while margin expansion concentrates in automated test systems with integrated IEC 61850 client functionality. Price differentiation hinges on certification tier—FERC-compliant protection relay test sets command substantial premiums over baseline models—and after-sales service bundling, with unbundled calibration contracts depressing vendor pricing power among consolidated US utilities. Cost compression in the analog segment is intensifying because refurbished European equipment floods Southeast Asian secondary markets. Maintenance contractors exhibit highest price sensitivity, whereas transmission utilities with centralized procurement frameworks prioritize interoperability over unit cost.
Supply Chain Analysis
Freight cost volatility from Red Sea disruptions and Panama Canal constraints is elevating landed costs for precision winding components sourced from German and Japanese specialty manufacturers. Component production draws from China for rare earth magnets, Chile for copper enclosures, and Germany for precision reference standards. Supply chain vulnerability centers on single-source dependency for IEC 61850 Edition 2.1 compliance testing at accredited laboratories, extending product launch cycles. Distribution runs through authorized distributor networks for portable equipment and direct framework agreements for utility-scale automated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accredited laboratory capacity for IEC 61850 compliance testing operates as the binding constraint, propping pricing power for vendors with established certification partnerships and extending lead times for smaller manufacturers.
For Market Incumbents: Anticipate margin compression from software-native challengers by accelerating backward integration into calibration service networks and securing exclusive third-party metrology lab partnerships that unbundle after-sales support from equipment sales. Deepen certification investment in F-Gas Regulation-compliant gas handling protocols for alternative insulation mediums to defend position against emerging entrants targeting European transmission operators. For New Entrants and Emerging Players: Fragmented maintenance contractor networks in India and Southeast Asia represent the most penetrable buyer archetype, with direct-to-technician sales through online certification platforms bypassing traditional distributor markups. Target marine-grade testing systems for offshore wind interconnection points in China's coastal provinces and Germany's North Sea expansion, where salt corrosion resistance specifications remain undersupplied by incumbent portfolios. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined measurement specialists given digital twin deployment accelerating demand for automated test sequences with subscription-based calibration services. Long-term viability favors vendors with unified data architecture capabilities bridging legacy serial protocol assets and modern Ethernet-based platforms. Watch for inflection when consolidated US utilities mandate IEC 61850 client functionality as a baseline procurement specification, eliminating analog-equipment arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Metrology Partnership | Unbundles calibration revenue from hardware sales for Texas and California utilities. |
| Marine-Grade Product Certification | Opens North Sea and Chinese offshore wind interconnection specifications to new suppliers. |
| Direct-to-Technician Platform Launch | Bypasses distributor markups in India's fragmented maintenance contractor networks. |
| F-Gas Compliance Protocol Development | Secures German TSO and Italian utility procurement specifications for alternative gas handling. |
| Digital Twin Integration Investment | Feeds calibrated sensor data into predictive maintenance algorithms for transmission operators. |
Research Methodology
Multi-period observation of utility procurement specification evolution and IEC 61850 adoption rates anchored the trend analysis, supplemented by interviews with substation engineering directors, protection relay specialists, maintenance contractor operations managers, and third-party metrology lab technical leads. Secondary validation drew from FERC orders, IEEE standards documentation, CEA grid code filings, and EIA transmission investment data. Bottom-up equipment shipment analysis and top-down utility capital expenditure triangulation cross-checked volume estimates.
Segment-weighting approaches applied differential growth assumptions across voltage classes, deployment models, and technology tiers, with automated test systems receiving higher weighting coefficients reflecting utility labor reduction priorities. CAGRs were derived from installed base replacement cycle compression and digital twin deployment penetration curves. Forecast inputs incorporated transformer fleet aging demographics, offshore wind interconnection timelines, and rare earth magnet price volatility indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IEC 61850 Edition 3.0 revision timing and F-Gas Regulation enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
AC-DC Controller Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Marine Switchboard Market