
 Global Large Power Transformers Market | 2026-2036
Global Large Power Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Large Power Transformers Market Intelligence
A divergence in capital allocation for advanced manufacturing versus bespoke engineering is redrawing the competitive landscape. Siemens Energy leverages its scale in automated production for large-scale transmission network projects. In contrast, Virginia Transformer Corporation specializes in customized solutions for specific industrial applications in North America. Hitachi Energy competes by integrating smart grid technologies and digital monitoring services into its high-voltage offerings, targeting utility modernization.
A large power transformer is a static electrical device that transfers high-voltage energy, typically rated above 100 MVA, between transmission and distribution circuits. These units use oil-immersed or gas-insulated systems to manage extreme thermal and electrical stresses. In terms of application, renewable integration projects are creating new demand patterns for transformers capable of handling intermittent loads. Oil-immersed units remain the dominant product type for transmission networks, while dry-type transformers gain share in industrial plants due to safety regulations.
Global standards from the IEC, such as IEC 60076, define performance and testing protocols for power transformers. In the United States, the EPA regulates the use of dielectric fluids, while the EU's RoHS directive restricts hazardous materials in manufacturing. Navigating these varied and evolving efficiency and material standards is becoming a central challenge for equipment manufacturers and procurement teams.
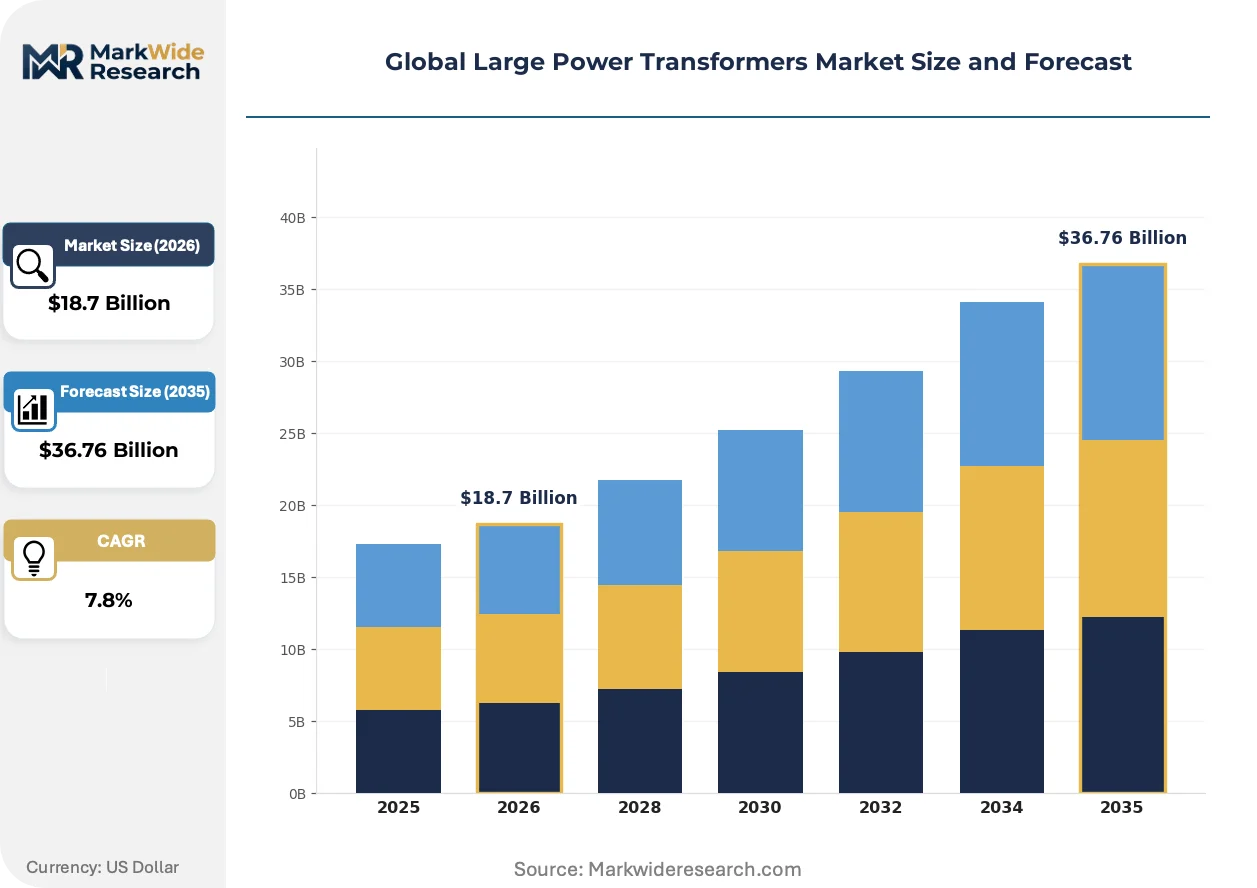
Market Dynamics
The central dynamic is the grid's modernization imperative, driven by renewable energy integration, clashing with the extremely long asset lifecycles and high capital cost of large power transformers, forcing utilities to balance replacement cycles against new capacity investments.
Growth Catalysts
- Grid Modernization Policies:The EU Green Deal and similar initiatives in North America accelerate the replacement of aging transformers with more efficient models capable of supporting decentralized renewable energy sources and bidirectional power flows.
- National Grid Expansion:Large-scale infrastructure projects, particularly India's push to connect its entire population and support industrial growth, create concentrated demand for new high-voltage transmission equipment to expand national grid capacity.
- Renewable Energy Integration:The proliferation of large wind and solar farms necessitates new substations and transformers specifically designed to manage the variable and intermittent power output characteristic of these sources.
Market Restraints
- Input Material Volatility:Price fluctuations and supply chain constraints for critical raw materials like grain-oriented electrical steel (GOES) and copper directly impact manufacturing costs and lead times for transformer producers.
- Logistical Complexity:The immense size and weight of large power transformers create significant transportation challenges, requiring specialized vehicles, route planning, and heavy-lift equipment, which adds substantial cost and project risk.
- Long Production Cycles:The bespoke engineering and manufacturing process for a single large power transformer can take many months, creating long lead times that can delay critical energy infrastructure projects.
Strategic Opportunities
- Biodegradable Dielectric Fluids:Developing and marketing transformers that use ester-based, biodegradable insulating fluids offers a path to capture share with environmentally conscious utilities and comply with stricter EPA and ECHA regulations.
- Data Center Power Infrastructure:The exponential growth of data centers creates a significant opportunity for high-reliability, custom-engineered transformers designed to support the unique power quality and uptime requirements of these facilities.
- Digital Monitoring Services:Integrating advanced sensors for dissolved gas analysis, temperature, and partial discharge monitoring creates new recurring revenue streams from digital services and predictive maintenance for utility customers.
Industry Challenges
- Skilled Workforce Scarcity:A persistent shortage of high-voltage engineers, winding specialists, and testing technicians hinders production capacity and elevates labor costs for manufacturers across North America and Europe. *Compliance Fragmentation: Manufacturers must navigate a complex and evolving web of international and national standards, including IEC 60076 for performance, EU RoHS for materials, and varied national energy efficiency mandates.
- High Capital Investment:Establishing or upgrading manufacturing facilities with the necessary core-cutting machinery, high-bay winding halls, and impulse testing laboratories requires substantial upfront capital investment, creating high barriers to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Large Power Transformers Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Immersed, Dry-Type, Gas-Insulated, Cast Resin, Resin Impregnated, Vapor Phase Application: Transmission Networks, Distribution Systems, Renewable Integration, Industrial Plants, Data Centers, Railways End User: Power Generation, Transmission Operators, Distribution Utilities, Renewable Project Developers, Heavy Industries, Telecom Networks Technology: High Voltage, Medium Voltage, Low Loss, Smart Transformers, Temperature Monitoring, Load Tap Changers |
| Companies Covered | ABB, Schneider Electric, Siemens Energy, Virginia Transformer Corporation, Toshiba, General Electric, Mitsubishi Electric, WEG Transformers, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Large Power Transformers Market Strategic Shifts & Innovations
The evolution of large power transformers is defined by the integration of digital intelligence and advancements in material science. These shifts are making assets more resilient, efficient, and responsive to the dynamic demands of modern electrical grids.
Solid-state transformer (SST) technology utilizes power electronics to provide precise voltage and frequency control. Adoption is currently focused in specialized applications such as electric vehicle fast-charging networks and renewable energy research facilities. For grid-scale transmission, this technology is miniaturizing the physical footprint needed for DC integration points and advanced power flow control systems.
Regulatory mandates for energy efficiency are compelling design innovation across the industry. The EU's Ecodesign Directive, along with Department of Energy standards in the United States, sets strict limits on transformer energy losses. This forces manufacturers in the dominant oil-immersed segment to adopt higher-grade materials, such as amorphous steel for cores, to meet performance tiers.
Utility buying behavior is evolving from a focus on initial purchase price to a total cost of ownership (TCO) evaluation. This procurement model considers the capitalized cost of a transformer's lifetime energy losses alongside its upfront price and projected maintenance. The shift is most pronounced in European and North American markets, favoring suppliers that can provide certified performance data and integrated asset health monitoring.
Global Large Power Transformers Market Segmentation
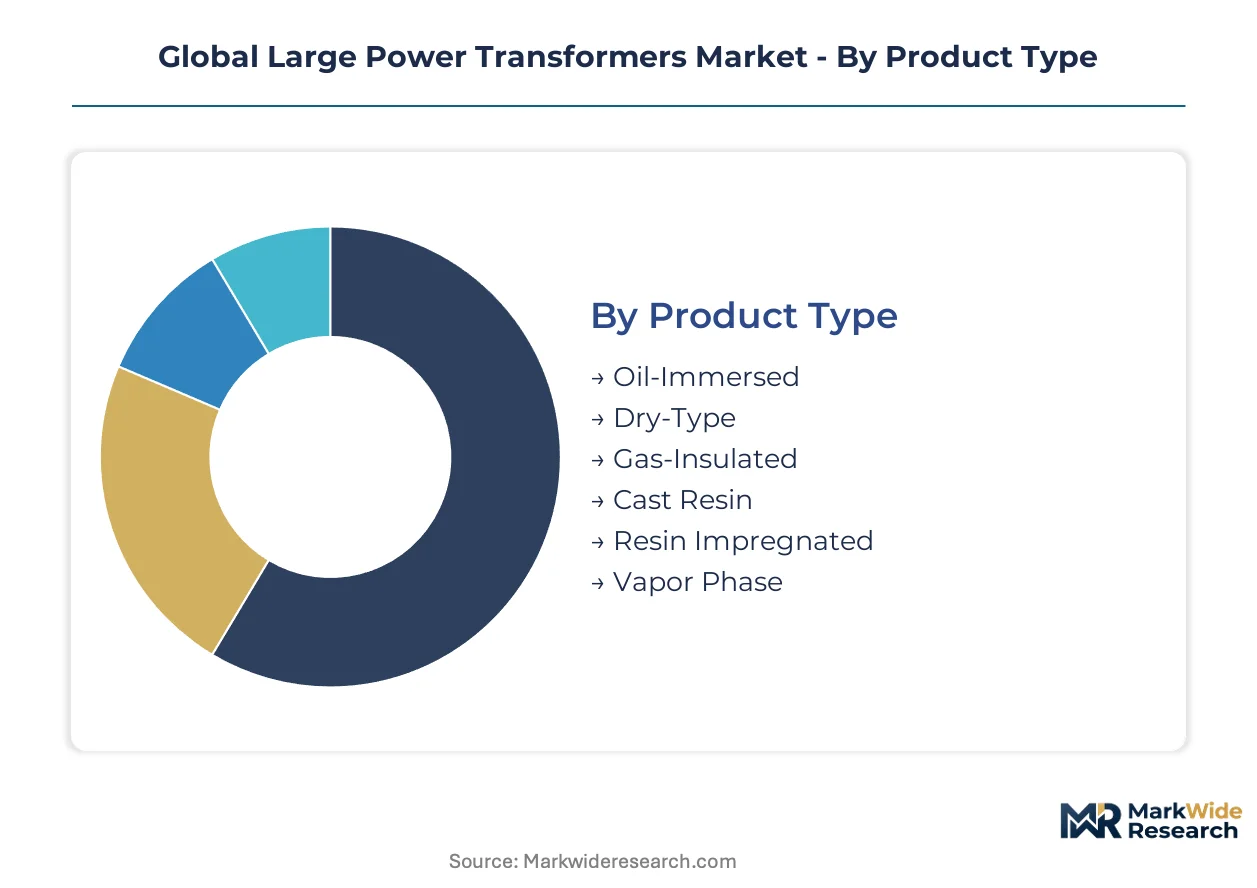
Understanding the segmentation of the global large power transformers market reveals how specialized engineering addresses diverse energy infrastructure needs. This analysis highlights the distinct technical requirements and commercial drivers influencing each product type, application, end-user, and technology segment. Precise market categorization assists manufacturers in aligning production capabilities with evolving demand patterns across various energy sectors.
Product Type:
The product type segmentation differentiates transformers by their insulating and cooling mediums, which impacts their suitability for various environments and performance demands, with market presence varying significantly by region.
- Oil-Immersed:These units utilize mineral oil or synthetic ester fluids for both insulation and cooling, offering high dielectric strength and efficient heat dissipation. Demand is concentrating in India and other developing economies for new transmission network buildouts, driven by their cost-effectiveness and proven reliability.
- Dry-Type:These transformers use air or solid insulating materials, eliminating the risk of oil leaks and fire hazards, making them safer for indoor installations. Growth is accelerating in industrial plants and commercial buildings across Europe and North America due to stricter fire safety regulations and environmental mandates.
- Gas-Insulated:Sulfur hexafluoride (SF6) or alternative gases provide insulation, allowing for compact designs suitable for space-constrained urban substations.
- Cast Resin:Coils are encapsulated in epoxy resin, providing robust protection against humidity and contamination, often used in harsh industrial environments.
- Resin Impregnated:These units feature coils impregnated with resin under vacuum, enhancing their mechanical strength and resistance to short-circuit forces.
- Vapor Phase:Utilizing a dielectric fluid in a vapor state for cooling, these transformers offer superior heat transfer efficiency for specialized high-power applications.
Oil-Immersed units hold the largest share; momentum sits with Dry-Type transformers.
Application:
Application segments delineate where large power transformers are deployed, reflecting the specific electrical grid functions and industrial processes they support.
- Transmission Networks:These applications involve stepping up voltage for long-distance power transfer from generation sources to regional substations, minimizing energy losses. Procurement is shifting towards higher voltage classes and greater efficiency models in countries like the United States for grid hardening initiatives.
- Renewable Integration:Transformers in this segment connect intermittent renewable energy sources, such as large wind and solar farms, to the main grid, requiring specialized designs for variable load management. Demand is expanding most quickly in Germany and Spain, driven by ambitious national renewable energy targets.
- Distribution Systems:Transformers step down high transmission voltages to lower levels suitable for local distribution to homes and businesses.
- Industrial Plants:These units supply stable, high-power electricity to heavy manufacturing facilities, chemical plants, and metal processing operations.
- Data Centers:Custom-engineered transformers provide reliable power infrastructure for data centers, ensuring power quality and redundancy for critical IT loads.
- Railways:Specialized transformers power railway electrification systems, supporting both AC and DC traction networks.
Transmission Networks represent the dominant application area, with Renewable Integration applications experiencing the steepest expansion trajectory.
End User:
The end-user segmentation identifies the primary entities purchasing and operating large power transformers, each with distinct procurement criteria and operational requirements.
- Transmission Operators:These entities manage and maintain the high-voltage electricity transmission infrastructure, prioritizing reliability, efficiency, and grid stability. Utilities across North America are investing in advanced transformers to enhance grid resilience against extreme weather events.
- Renewable Project Developers:Companies developing wind, solar, and other renewable energy projects require transformers to connect their generation facilities to the existing grid. Developers in Australia are increasingly seeking compact, modular transformer solutions for remote utility-scale projects.
- Power Generation:Transformers are used at power plants to step up generated electricity to transmission voltage levels.
- Distribution Utilities:These organizations are responsible for delivering electricity from substations to end-consumers, focusing on local grid optimization and service continuity.
- Heavy Industries:Large industrial consumers, such as mining and steel production, purchase transformers for their internal power distribution needs.
- Telecom Networks:Specialized transformers support the power infrastructure for large-scale telecom facilities and data communication hubs.
Transmission Operators constitute the largest customer base, while Renewable Project Developers are gaining share fastest.
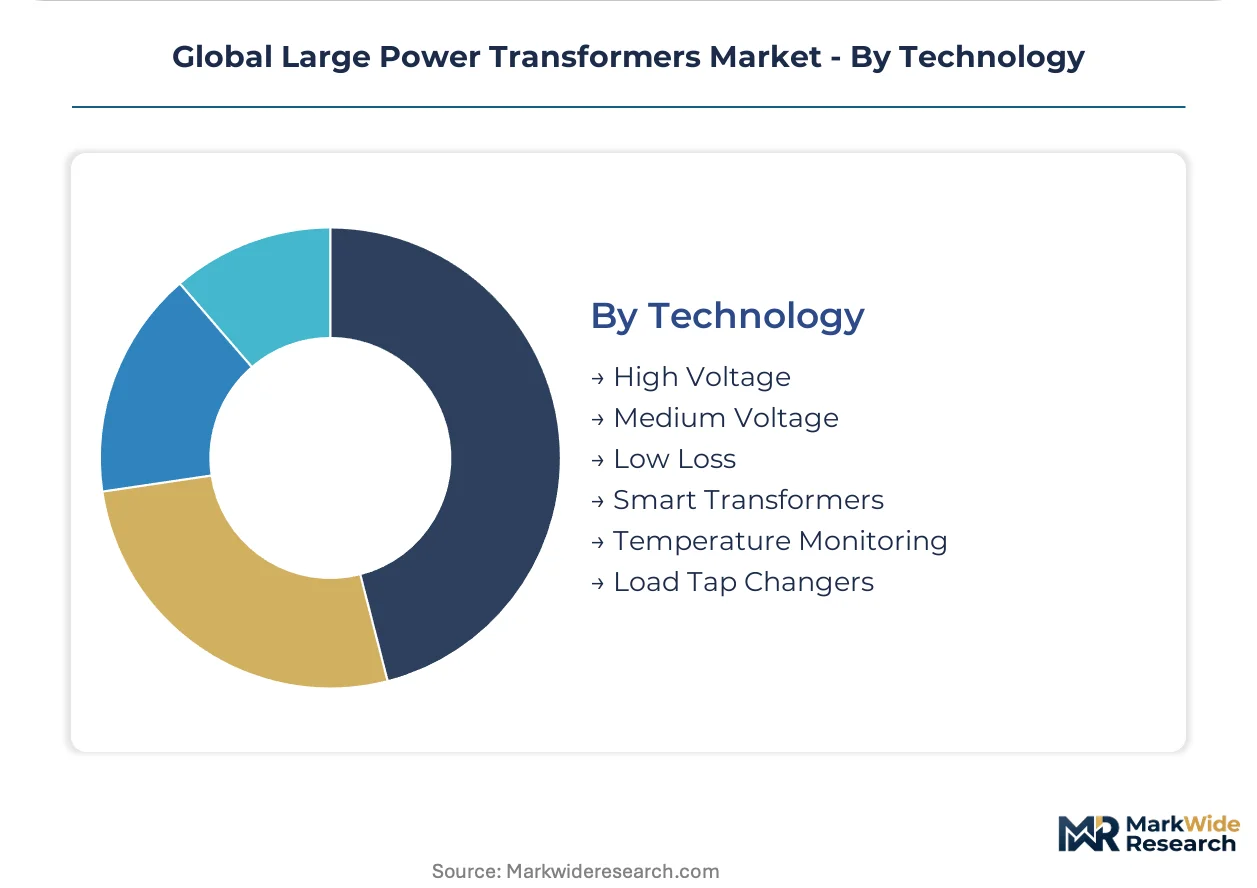
Technology:
Technology segmentation categorizes transformers by their design sophistication and integrated features, reflecting advancements in efficiency, monitoring, and control capabilities.
- High Voltage:Transformers designed for very high transmission voltages, typically above 230 kV, handling immense power capacities for inter-regional grid connections. Demand for these units is concentrating in Brazil for its extensive hydroelectric power transmission.
- Smart Transformers:These units integrate sensors, communication modules, and control algorithms for real-time monitoring, fault detection, and intelligent grid management. Utilities in the Nordic countries are implementing smart transformers to optimize decentralized energy flows and integrate distributed generation.
- Medium Voltage:Transformers operating at voltages typically between 1 kV and 36 kV, used in distribution networks and industrial applications.
- Low Loss:Designs emphasizing minimal energy dissipation during operation, achieved through advanced core materials like amorphous steel and optimized winding configurations.
- Temperature Monitoring:Transformers equipped with advanced thermal sensors and diagnostic systems to prevent overheating and predict potential failures.
- Load Tap Changers:Devices that adjust the turns ratio of a transformer under load, enabling voltage regulation to maintain stable power delivery.
High Voltage technology forms the foundational segment, with Smart Transformers demonstrating significant innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident between established markets like the United States and rapidly developing economies such as India. Demand patterns for large power transformers reflect localized grid modernization initiatives and the pace of renewable energy integration. Each region presents distinct procurement criteria influenced by regulatory frameworks and infrastructure development priorities.
India
National grid expansion projects and industrial growth drive significant demand for new transmission network buildouts. The PLI scheme supports domestic manufacturing capabilities for critical power infrastructure components. Concentrated demand for high-voltage transmission equipment is evident in states like Maharashtra and Gujarat, supporting new industrial corridors and urban centers.
United States
Grid hardening initiatives and the replacement of aging infrastructure create demand for higher voltage classes and greater efficiency models. Department of Energy standards set strict limits on transformer energy losses, compelling design innovation. Utilities across the Pacific Northwest and Texas are prioritizing advanced transformers to enhance grid resilience against extreme weather events and integrate new generation sources.
Germany
Ambitious national renewable energy targets necessitate specialized transformers for connecting large wind and solar farms to the main grid. The EU's Ecodesign Directive mandates stringent energy efficiency requirements for power transformers, influencing procurement decisions. Utilities in Bavaria and North Rhine-Westphalia are implementing smart transformers to optimize decentralized energy flows and integrate distributed generation.
Brazil
Extensive hydroelectric power transmission and the expansion of its national grid concentrate demand for very high voltage transformers. The country's energy regulator, ANEEL, guides investments in transmission infrastructure to ensure stable power delivery. Large-scale projects in the Amazon basin and southern regions are driving procurement of high-capacity units for inter-regional grid connections.
France
The EU Green Deal and national energy transition policies accelerate the replacement of older units with more efficient models capable of supporting decentralized renewable energy sources. The country's grid operator, RTE, focuses on enhancing grid stability and integrating intermittent power. Investments in advanced transformer technology are visible in regions like Brittany and Occitanie, supporting offshore wind and solar developments.
Global Large Power Transformers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. The competitive landscape for large power transformers is characterized by a blend of global conglomerates leveraging scale and specialized manufacturers focusing on niche applications. Strategic archetypes include integrated energy solution providers, bespoke engineering firms, and digital-first innovators. Dominant competitive moves include strategic partnerships for grid projects and continuous investment in materials science research.
Archetype-first, global integrated energy solution providers like Siemens Energy leverage their significant scale in automated production for large-scale transmission network projects. Virginia Transformer Corporation, a North American specialist, exemplifies the bespoke engineering archetype, focusing on customized solutions for specific industrial applications. Hitachi Energy represents the digital-first innovators, integrating smart grid technologies and advanced digital monitoring services into its high-voltage offerings for utility modernization.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens Energy |
| Virginia Transformer Corporation |
| Toshiba |
| General Electric |
| Mitsubishi Electric |
| WEG Transformers |
| Hitachi Energy |
| Others |
Cost & Logistics Intelligence
The EU's Ecodesign Directive, alongside other national efficiency mandates, gates both supply qualification and price differentiation across the large power transformers market. This regulatory framework compels manufacturers to invest in advanced materials and designs, directly impacting production costs and pricing strategies. Such stringent standards ensure that only compliant and high-performing units enter regulated markets, creating a barrier for suppliers.
Pricing Analysis
Configured-to-order pricing dominates for specialized large power transformers, reflecting the bespoke engineering required for specific grid applications. Price differentiation stems from customization levels and certified performance tiers, particularly those meeting Department of Energy standards in the United States. Pricing softness reflects input material volatility for grain-oriented electrical steel and copper, which impacts manufacturing costs. Utilities in developing economies often exhibit higher price sensitivity compared to those in European markets focused on total cost of ownership.
Supply Chain Analysis
Logistical challenges, including specialized vehicle requirements and route planning for immense transformer units, directly influence inbound costs. Supply concentration for critical components like GOES and copper centers in a few global regions, creating dependencies. Raw material dependencies on grain-oriented electrical steel and copper introduce commodity price volatility as a structural risk. Distribution runs through direct sales channels to utilities and project developers, often supported by specialized heavy-haul logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat story, primarily due to the regulatory entrenchment of existing technologies and the high capital cost of manufacturing. Established players benefit from long-standing utility relationships and deep technical expertise. This structural advantage protects market share against disruptive new entrants.
For Market Incumbents:
Shield market share by deepening vertical integration into advanced material production, such as amorphous steel, to mitigate input material volatility. Expand digital monitoring services to offer predictive maintenance, creating recurring revenue streams and enhancing customer switching costs. This strategy counters the threat of new entrants offering lower-cost, less-integrated solutions. Invest in certification processes for biodegradable dielectric fluids to comply with evolving environmental regulations.
For New Entrants and Emerging Players:
Differentiate on specialized applications like data center power infrastructure, which demands high reliability and custom engineering. Target industrial plants and renewable project developers in Europe with compact, dry-type transformer solutions, capitalizing on stricter fire safety regulations. A go-to-market angle focusing on modular, rapidly deployable units for remote utility-scale projects can penetrate underserved segments in Australia. This approach avoids direct competition with incumbents in traditional transmission networks.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with vertically integrated mid-cap specialists, offering stable cash flows within a long-term infrastructure market. The long-term viability of this sector is underpinned by global grid modernization and renewable energy integration initiatives. Target acquisition profiles include firms with strong intellectual property in smart grid technologies or advanced material science. The accelerating adoption of digital monitoring services by utilities serves as a key inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Amorphous Steel Production | This secures supply chains for high-efficiency transformer cores, meeting stringent energy loss regulations. |
| Expand Digital Monitoring Service Offerings | This creates recurring revenue and enhances asset uptime for utility customers, improving grid reliability. |
| Develop Biodegradable Dielectric Fluid Solutions | This ensures compliance with evolving environmental mandates from the EPA and ECHA, attracting environmentally conscious buyers. |
| Form Partnerships for Grid Expansion Projects | This enables access to new markets like India and Brazil, leveraging local expertise for large-scale infrastructure buildouts. |
| Acquire Specialist in Solid-State Transformer Technology | This integrates advanced power electronics for precise voltage control, positioning for future grid modernization needs. |
Research Approach
The analysis maps product types like oil-immersed and dry-type, alongside applications such as transmission networks and renewable integration, each validated through primary interviews. Industry stakeholders included utility planning officers, renewable project developers, EPC contractors, and industrial plant engineers. Secondary data sources comprised regulatory filings from the EPA and ANEEL, industry association reports from IEC, and national energy agency data from EIA and IEA. The study integrated both bottom-up and top-down triangulation for robust market sizing.
Outputs were validated for consistency against external benchmarks and integrated historical trends with future projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from an assessment of market drivers, restraints, and competitive intensity. Grid modernization spending and renewable energy capacity additions served as key forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of a stable regulatory environment and predictable raw material supply; material deviation would warrant model refresh. Geopolitical instability affecting global supply chains or unforeseen technological disruption represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
Middle East Distribution Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
HVDC Converter Transformers Market
Transformers
United States Dry-Type Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Canada Transformer Market
Transformers
Transformer Bobbin Market
Transformers
Current Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Transformer Core Market
Transformers
Locomotive Traction Transformer Market
Transformers
Amorphous Core Transformers Market
Transformers
Asia-Pacific Transformer Market