
 Saudi Arabia Transformer Market | 2026-2036
Saudi Arabia Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Transformer Market Analytics
Specialized transformer winding technician availability is collapsing across the Eastern Province, forcing manufacturers to triple apprenticeship intake at Jubail and Dammam facilities. Saudi Transformers Company leverages in-house copper winding capabilities to sustain delivery schedules for utility-scale orders. Siemens Energy anchors its Gulf supply chain through a Riyadh-based engineering center that controls regional specification compliance. ABB Electrical Industries differentiates via dry-type transformer specialization for indoor commercial installations in Neom and Red Sea Project sites.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 Hz or 60 Hz with voltage ratings spanning 11 kV to 400 kV depending on application. Its core comprises laminated silicon steel to minimize eddy current losses, while windings use copper or aluminum conductors insulated with oil-impregnated paper or cast resin. Power transformers dominate capital allocation due to gigaproject transmission requirements, while distribution transformers represent the highest unit volume segment serving residential expansion across secondary cities. Smart transformers are gaining specification share as grid digitalization mandates from the Saudi Electricity Company integrate IoT-enabled monitoring for predictive maintenance protocols.
SASO efficiency standards and SFDA electrical safety regulations govern transformer import certification, compelling manufacturers to submit thermal performance testing from accredited Gulf laboratories. The Saudi Building Code enforces fire-safety specifications that favor dry-type units for indoor commercial and mining applications over traditional oil-immersed designs. Stakeholders must monitor how gigaproject developers balance first-cost procurement against lifecycle efficiency gains as SASO tightens minimum performance standards.
Market Dynamics
SASO efficiency mandates and SFDA electrical safety regulations are compressing replacement cycles across Saudi Arabia's installed transformer base while gigaproject developers demand higher-capacity units with integrated digital monitoring capabilities.
Growth Catalysts
- Grid Modernization Mandates:Saudi Electricity Company procurement specifications now require IoT-enabled monitoring for predictive maintenance protocols across high-voltage transmission infrastructure.
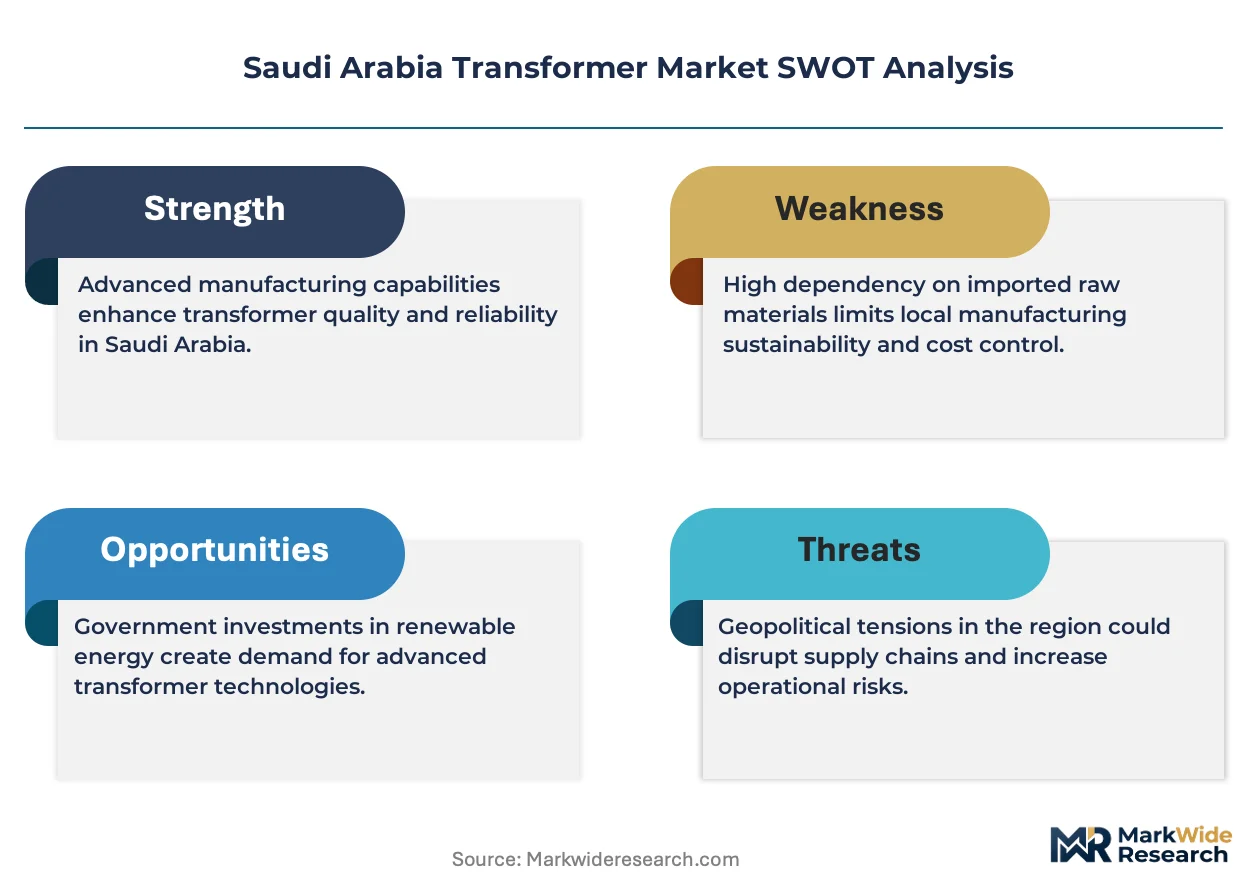
- Gigaproject Electrification:Neom, Red Sea Project, and Qiddiya developments are commissioning substation infrastructure that demands specialized dry-type transformers for indoor commercial installations.
- Copper Winding Localization:Eastern Province manufacturing clusters are expanding in-house conductor production capabilities to reduce import dependency for utility-scale orders.
Market Restraints
- Silicon Steel Input Volatility:Laminated core material costs fluctuate with global metallurgical-grade silicon supply constraints, pressuring transformer OEM margins.
- Winding Technician Scarcity:Specialized electromagnetic coil fabrication skills have collapsed across Jubail and Dammam industrial zones, forcing apprenticeship program expansion.
- Oil-Immersed Design Restrictions:Saudi Building Code fire-safety specifications now favor cast-resin dry-type units for indoor mining and commercial applications, eliminating traditional mineral-oil alternatives.
Strategic Opportunities
- Smart Transformer Specification Share:Grid digitalization protocols from the Saudi Electricity Company create white space for vendors offering integrated temperature, load, and dissolved-gas monitoring systems.
- Secondary City Distribution Networks:Residential expansion across Tabuk, Hail, and Jazan requires high-volume procurement of 11 kV distribution transformers with enhanced efficiency ratings.
- Gulf Laboratory Accreditation Services:Thermal performance testing demand from manufacturers seeking SASO import certification supports third-party validation business models.
Industry Challenges
- SFDA Certification Timelines:Electrical safety documentation requirements for imported transformer assemblies extend procurement lead times for non-domestic manufacturers.
- Legacy Grid Integration Complexity:Smart transformer deployments must interface with existing SCADA infrastructure that lacks standardized communication protocols across Saudi Electricity Company regional divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Transformer Market |
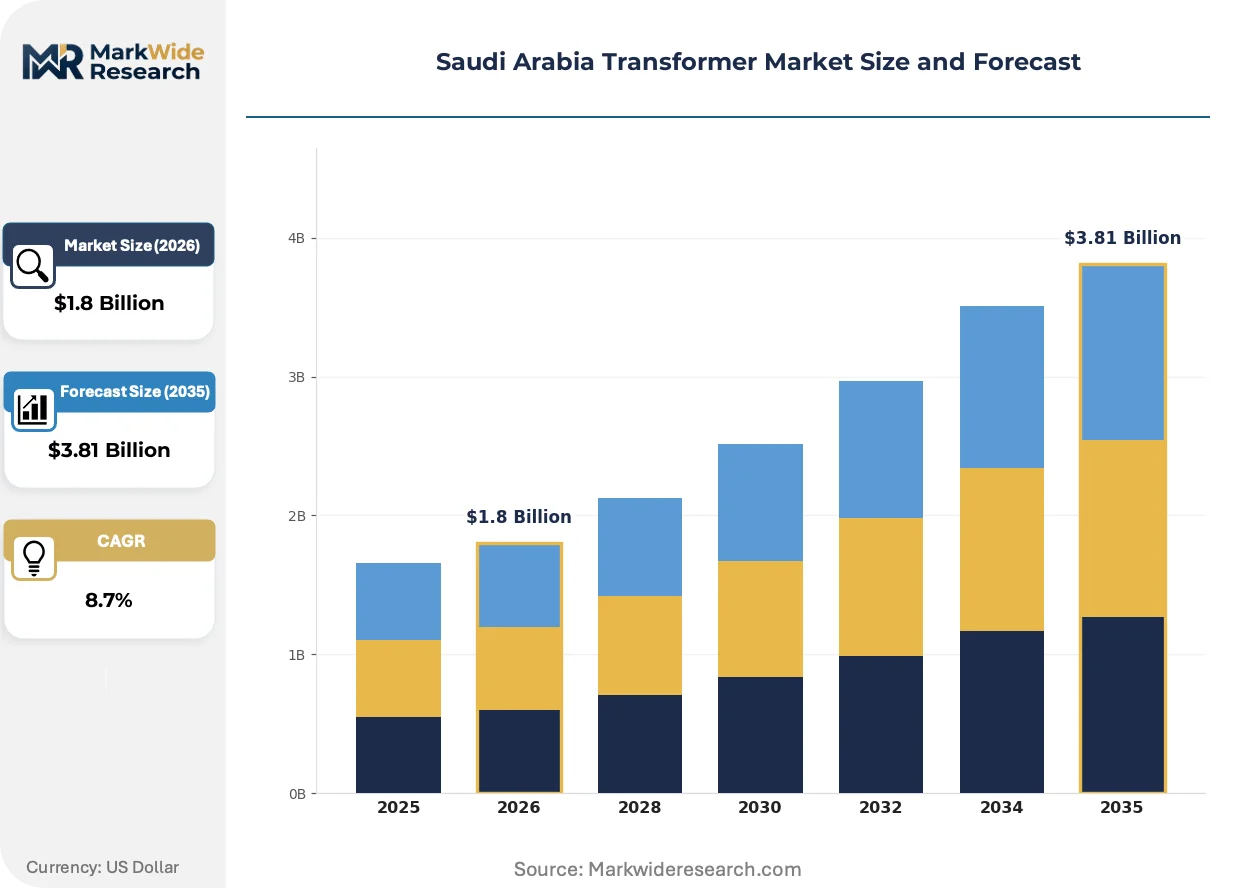
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformers, Distribution Transformers, Isolation Transformers, Instrument Transformers Application: Power Generation, Industrial Applications, Renewable Energy, Commercial Use Technology: Dry Type, Oil Immersed, Smart Transformers, High Voltage End User: Utilities, Manufacturing, Construction, Mining |
| Companies Covered | General Electric, Saudi Transformers Company, Siemens Energy, Electric Industries Company, Alfanar Group, ABB Electrical Industries, Hitachi Energy, United Transformers Electric Company, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Transformer Market Evolving Landscape
Digital monitoring integration and cast-resin insulation technologies are displacing conventional transformer architectures across Saudi Arabia's utility and commercial procurement channels.
Cast-resin dry-type transformer technology is fragmenting procurement specifications for indoor installations across Neom and Red Sea Project sites. Gigaproject developers now mandate epoxy-resin vacuum-cast windings for fire-safety compliance in underground substations and high-rise commercial towers. This insulation shift is fragmenting vendor competitive positions, as traditional oil-immersed specialists must retool manufacturing lines or exit premium commercial segments.
SFDA electrical safety regulations now require thermal performance testing documentation from accredited Gulf laboratories for all transformer import certifications. Manufacturers face expanded compliance costs for documentation preparation and third-party validation. Dry-type transformer categories experience the most stringent documentation scrutiny due to their deployment in occupied commercial structures.
Specification-driven procurement now dominates utility-scale transformer acquisition across Riyadh and Eastern Province load centers. Saudi Electricity Company engineering teams issue performance-based tenders that prioritize lifecycle efficiency over first-cost metrics. This behavioral shift compresses supplier margins while rewarding manufacturers with documented mean-time-between-failure data and regional service infrastructure.
Saudi Arabia Transformer Market Segmentation
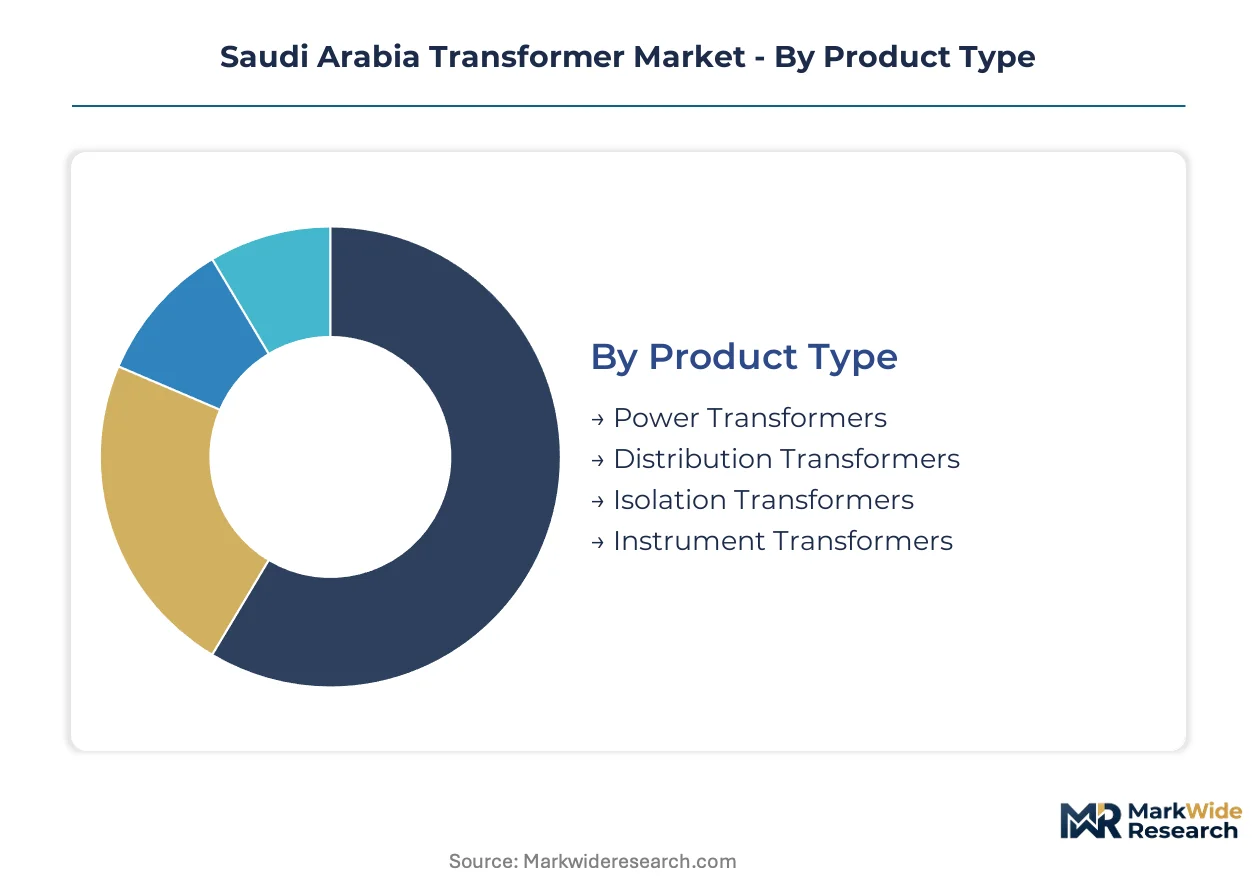
Transformer procurement patterns in Saudi Arabia diverge sharply between utility-scale transmission infrastructure and distributed commercial installations. Understanding these segment boundaries clarifies where SASO efficiency mandates and gigaproject specifications create divergent competitive requirements.
Product Type:
Power transformers serve almost exclusively domestic demand tied to Saudi Electricity Company grid expansion, while distribution and isolation units face growing export competition from Gulf manufacturing clusters.
- Power Transformers:These high-capacity units handle voltage conversion from 132 kV to 400 kV across transmission networks. Demand concentrates in Riyadh and Eastern Province substations where Saudi Electricity Company is modernizing aging infrastructure under grid digitalization mandates.
- Distribution Transformers:Operating at 11 kV to 33 kV ratings, these units step power down for end-user delivery. Secondary cities including Tabuk, Hail, and Jazan are driving procurement volume as residential expansion accelerates across the kingdom's peripheral urban centers.
- Isolation Transformers:Galvanic separation units protect sensitive industrial equipment from electrical noise and ground loops. Manufacturing facilities in Jubail Industrial City specify these for process control systems requiring clean power delivery.
- Instrument Transformers:Current and voltage sensing units enable metering and protection relay functions. Smart grid deployments across SEC regional divisions are expanding specification share for precision-class units with digital output interfaces.
Power transformers command the established base. The steepest expansion runs through distribution transformers serving secondary city electrification.
Application:
Industrial and power generation applications dominate capital deployment, while renewable energy integration is reshaping technical specifications for variable-load tolerance.
- Power Generation:Bulk energy conversion infrastructure serving combined-cycle and solar thermal plants. Taqa and ACWA Power project pipelines in the Eastern Province are specifying large-frame units with enhanced cyclic loading capability.
- Industrial Applications:Process power conditioning for petrochemical, steel, and cement operations. Jubail and Yanbu industrial cities require explosion-proof designs and specialized cooling systems for harsh coastal environments.
- Renewable Energy:Grid-interconnection and step-up functions for solar and wind installations. NEOM's renewable energy cluster is driving demand for power electronic-interfaced transformers with bidirectional power flow capability.
- Commercial Use:Building-level distribution and HVAC power supply. Red Sea Project hospitality developments are mandating dry-type units with low noise signatures and fire-safety certification under Saudi Building Code.
Industrial applications anchor current procurement value. Renewable energy integration is gaining share fastest as the kingdom diversifies generation mix.
Technology:
Technology selection splits between established oil-immersed designs for outdoor utility installations and emerging dry-type architectures for indoor commercial compliance.
- Dry Type:Cast-resin or vacuum-pressure-impregnated insulation eliminates flammable liquids. NEOM underground substations and high-rise towers in Riyadh Financial District specify these for fire-safety compliance.
- Oil Immersed:Mineral oil or ester fluid provides dielectric insulation and thermal transfer. Traditional utility substations across SEC's Central Operating Area continue specifying these for cost efficiency and proven field performance.
- Smart Transformers:IoT-enabled monitoring integrates temperature, load, and dissolved-gas analysis. SEC's predictive maintenance protocols are making digital connectivity a tender requirement for transmission-class units.
- High Voltage:Specialized designs exceeding 220 kV for long-distance transmission. The kingdom's east-west power corridor expansion is creating demand for ultra-high-voltage units with low-loss core materials.
Oil-immersed technology retains the installed base. Smart transformer capabilities are climbing the fastest as grid digitalization mandates harden.
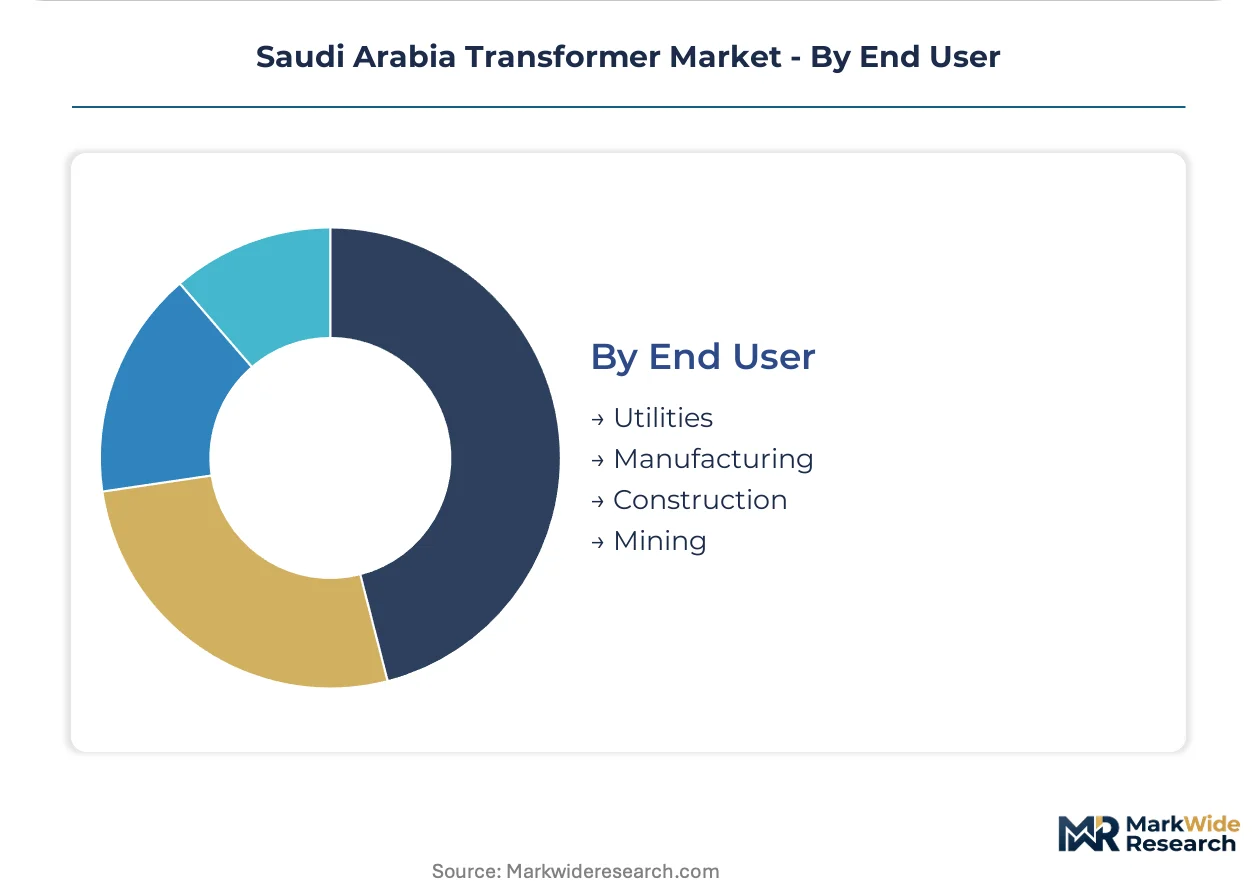
End User:
Utility procurement follows centralized tender processes with lifecycle efficiency weighting, while mining and construction buyers prioritize rapid delivery and site-specific adaptation.
- Utilities:Saudi Electricity Company dominates through centralized procurement with specification-driven, performance-based tenders. SEC engineering teams prioritize documented mean-time-between-failure data over first-cost metrics.
- Manufacturing:Process industries requiring power quality and continuity assurance. SABIC affiliate complexes specify custom-designed units with redundant cooling and on-load tap changing for voltage regulation.
- Construction:Temporary and permanent electrification for gigaproject sites. NEOM contractors face compressed installation schedules that favor modular, skid-mounted transformer substations with plug-and-play commissioning.
- Mining:Harsh-environment power distribution for phosphate and bauxite extraction. Ma'aden operations in the Northern Border Region require dust-sealed enclosures and extended temperature range ratings.
Utilities command the established base. Construction end-use is expanding most quickly amid gigaproject execution timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA electrical safety regulations and SASO efficiency mandates anchor procurement patterns across Saudi Arabia's transformer market. Sub-regional demand concentrates in four distinct load centers shaped by gigaproject execution, industrial clustering, and grid modernization priorities.
Riyadh
Saudi Electricity Company transmission upgrades and the Riyadh Financial District's high-rise commercial towers drive demand for smart transformers with IoT-enabled monitoring. SASO minimum performance standards compress replacement cycles across aging substation infrastructure. The Central Operating Area hosts concentrated procurement for 132 kV to 400 kV power transformers serving the capital's expanding metropolitan footprint.
Eastern Province
Jubail and Dammam industrial cities require explosion-proof transformer designs for petrochemical and steel operations in harsh coastal environments. Specialized winding technician scarcity has forced manufacturers to triple apprenticeship intake at local fabrication facilities. The region's copper winding localization push reduces import dependency for utility-scale orders serving SABIC affiliate complexes.
Western Region
Jeddah and Makkah load centers face distribution transformer procurement pressure from residential expansion and religious tourism infrastructure. Secondary city electrification across Tabuk and Hail extends 11 kV network requirements. The Saudi Building Code enforces fire-safety specifications that favor dry-type units for indoor commercial installations over traditional oil-immersed alternatives.
NEOM Northwest
The gigaproject's renewable energy cluster drives demand for power electronic-interfaced transformers with bidirectional power flow capability. Underground substations and high-rise towers mandate epoxy-resin vacuum-cast windings for fire-safety compliance. Modular, skid-mounted transformer substations with plug-and-play commissioning address compressed installation schedules for NEOM contractors.
Saudi Arabia Transformer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Saudi Arabia's transformer market. The upper tier comprises multinational energy technology conglomerates with regional engineering centers and documented mean-time-between-failure data. The specialist tier includes domestic fabricators with in-house copper winding capabilities and dry-type specialization for indoor commercial segments. Two strategic archetypes dominate: integrated technology providers controlling Gulf supply chains through Riyadh-based compliance centers, and localization-focused manufacturers expanding Eastern Province production capacity. Competitive moves concentrate on strategic partnerships for smart grid integration and portfolio diversification into cast-resin insulation technologies.
Within the integrated technology tier, Siemens Energy anchors Gulf supply chain coordination through Riyadh-based engineering centers managing regional specification compliance. ABB Electrical Industries exemplifies dry-type transformer specialization for indoor commercial installations at Neom and Red Sea Project sites. Saudi Transformers Company occupies a position among domestic fabricators leveraging in-house copper winding capabilities to sustain delivery schedules for utility-scale orders. These three entities represent distinct competitive positioning vectors: multinational supply chain control, premium commercial segment specialization, and localization-driven manufacturing scale.
| Leading Market Players |
|---|
| General Electric |
| Saudi Transformers Company |
| Siemens Energy |
| Electric Industries Company |
| Alfanar Group |
| ABB Electrical Industries |
| Hitachi Energy |
| United Transformers Electric Company |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Cast-resin insulation substitution for mineral-oil designs simultaneously redraws procurement geography toward Eastern Province manufacturing clusters and compresses margin structures for traditional oil-immersed specialists. This material transition forces buyers to absorb premium pricing for fire-safety compliance while rewarding domestic fabricators with localized vacuum-casting capabilities.
Pricing Analysis
Riyadh commands a 15-20% premium over Eastern Province delivery points for equivalent 132 kV power transformer specifications due to inland logistics costs and concentrated SEC procurement. Three-tier pricing structure across premium smart-monitored, standard dry-type, and economy oil-immersed tiers dominates utility tenders. Price differentiation hinges on SASO efficiency certification tier and after-sales service bundling. Cost compression in standard dry-type units is intensifying because Jubail manufacturers are expanding captive copper winding capacity. Construction end-users exhibit highest price sensitivity due to gigaproject budget constraints, while SEC procurement teams prioritize lifecycle efficiency over first-cost metrics.
Supply Chain Analysis
China and India anchor global silicon steel lamination supply for Saudi transformer OEMs, while Germany and Japan provide precision winding machinery and epoxy resin formulations. Raw material dependencies center on metallurgical-grade silicon, electrolytic copper, and vacuum-cast epoxy compounds. Single-source vulnerability concentrates in high-grade grain-oriented silicon steel where Chinese producers control 70% of seaborne trade. Distribution runs through Jeddah and Dammam industrial ports for inbound materials, with finished transformer logistics coordinated via SEC regional warehouses in Riyadh and the Eastern Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's transformer market is navigating a cyclical upswing driven by gigaproject execution timelines compressing procurement windows and forcing capacity expansion across domestic fabrication facilities.
For Market Incumbents: Consolidate winding technician training pipelines through expanded Jubail and Dammam apprenticeship programs to defend against capability scarcity eroding delivery schedules. Lock in long-term copper supply agreements with Gulf smelters to offset commodity volatility pressuring transformer OEM margins. Secure SASO pre-certification for smart transformer portfolios before efficiency mandates harden in SEC tender specifications. For New Entrants and Emerging Players: Anchor in secondary city distribution transformer procurement where Tabuk, Hail, and Jazan electrification programs face supply gaps from incumbent capacity constraints. Target 11 kV dry-type specifications for commercial mining applications where Saudi Building Code fire-safety requirements are displacing oil-immersed alternatives. Pursue joint venture structures with established Gulf laboratory networks to accelerate SFDA thermal performance certification timelines. For Investors and Strategic Acquirers: SASO efficiency mandate tightening reshapes the acquisition landscape toward targets with documented mean-time-between-failure data and regional service infrastructure. Long-term viability favors vertically integrated fabricators with in-house copper winding and cast-resin casting capabilities over pure assembly operations. Monitor SEC predictive maintenance protocol adoption rates as the signal indicating smart transformer specification share inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Winding Localization | Eastern Province captive production reduces import dependency for utility-scale SEC orders. |
| Smart Transformer Certification | IoT-enabled monitoring integration secures preferential positioning in SEC transmission tenders. |
| Cast-Resin Capacity Expansion | Vacuum-casting line investments capture Neom and Red Sea Project commercial specifications. |
| Gulf Laboratory Partnership | Accredited thermal testing capabilities accelerate SFDA import certification for non-domestic manufacturers. |
| Winding Technician Apprenticeship | Tripled training intake at Jubail facilities addresses specialized coil fabrication skill collapse. |
Research Methodology
Operator-level perspectives from SEC grid planning officers, transformer OEM procurement directors, Jubail industrial facility maintenance heads, and gigaproject EPC contractors anchored the qualitative base. Primary interview insights triangulated against SASO regulatory filings, SEC capital expenditure disclosures, Saudi Customs transformer import records, and Gulf laboratory accreditation databases. Bottom-up unit demand modeling across voltage classes and top-down macro validation against gigaproject electrification budgets reinforced analytical rigor.
Sensitivity analysis tested forecast robustness across silicon steel price volatility scenarios and SFDA certification timeline variations. Segmentation dimensions spanned product type, voltage rating tier, cooling method, end-user category, and regional load center. CAGRs derived from installed base replacement cycles, gigaproject commissioning schedules, and efficiency mandate compliance deadlines. Industry-specific inputs included SEC predictive maintenance protocol adoption curves and copper winding localization progress indicators.
Material uncertainties — commodity price spikes, regulatory enforcement intensity variations, and gigaproject timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions about SASO standard implementation consistency and SEC procurement specification evolution. Recalibration cycles align with material shifts in silicon steel trade flows and SFDA certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Middle-East Smart Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Transformer Core Market
Transformers
South America Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
United States Power Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Green Power Transformers Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Europe Telecom Transformers Market
Transformers
United Arab Emirates Transformer Market
Transformers
Uninhibited Transformer Oil Market
Transformers
North America Power Transformer Market
Transformers
Distribution Transformer Market
Transformers
Oil Filled Transformer Market