
 Hydroelectric Cells Market | 2026-2036
Hydroelectric Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroelectric Cells Market Foresight
The gap between premium high-head installations and commodity run-of-river projects is expanding. GE Renewable Energy leverages its digital turbine controls to dominate premium efficiency segments. Voith GmbH anchors European refurbishment demand with precision-engineered runner replacements. Sinohydro Corporation Limited competes on turnkey delivery scale across Belt and Road corridors.
Hydroelectric cells harness kinetic water energy through electrochemical or turbine-based conversion systems, typically operating at 50–60 Hz grid frequency with head pressures ranging from 5 to 500 meters. These installations serve baseload power generation, grid stabilization, and pumped storage arbitrage. Pumped storage technology leads capital deployment due to its dual-mode revenue stacking, while modular systems represent the fastest-growing segment as remote industrial offtakers seek captive supply. Run-of-river applications retain mature economics but face margin compression from seasonal flow variability.
China's MIIT enforces GB efficiency standards that gate market access for imported turbine assemblies. The EU Green Deal and F-Gas Regulation constrain hydraulic fluid chemistries in European installations. India's CEA mandates pumped storage obligations for interstate transmission licensees. Stakeholders must monitor how evolving grid interconnection codes in each jurisdiction reshape equipment certification timelines and project finance structures.
Market Dynamics
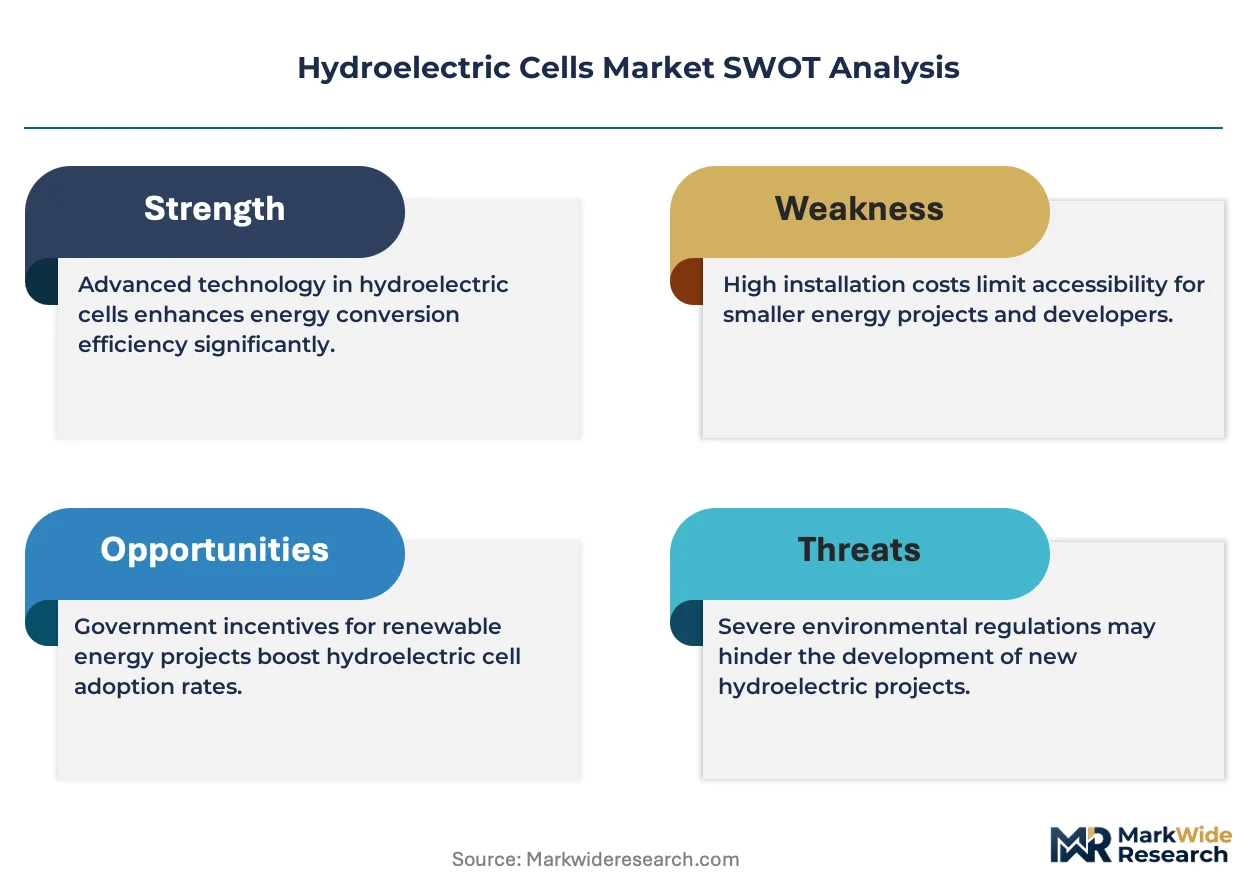
Modular turbine architectures are compressing deployment timelines from years to months, enabling utilities and industrial offtakers to bypass traditional dam infrastructure and capture run-of-river resources previously deemed uneconomical.
Growth Catalysts
- China's MIIT Efficiency Mandates:GB standards for turbine assemblies create guaranteed procurement volumes for domestic and compliant foreign suppliers, locking in multi-year equipment orders.
- Pumped Storage Arbitrage Revenue:Grid operators in deregulated power markets stack frequency regulation payments with peak shaving contracts, improving project IRRs.
- Belt and Road Infrastructure Financing:Development banks prioritize turnkey hydroelectric installations in emerging economies, reducing offtaker capital requirements.
Market Restraints
- Steel and Rare Earth Input Volatility:Permanent magnet generators depend on neodymium supply concentrated in Chinese processing facilities, exposing turbine OEMs to price swings.
- Seasonal Flow Variability:Run-of-river installations without reservoir buffering face output degradation during dry months, undermining power purchase agreement bankability.
- F-Gas Hydraulic Fluid Constraints:The EU F-Gas Regulation phases down high-GWP chemistries used in turbine lubrication systems, forcing reformulation costs.
Strategic Opportunities
- Retrofit of Aging European Infrastructure:Germany's KBA and grid operators prioritize runner replacements over greenfield dams, creating refurbishment demand.
- Hybrid Solar-Hydro Microgrids:Remote Indonesian and Philippine islands combine photovoltaic daytime generation with turbine evening dispatch, reducing diesel dependence.
- India's CEA Pumped Storage Obligations:Interstate transmission licensees must procure storage capacity, mandating equipment procurement through 2030.
Industry Challenges
- Turbine Blade Metallurgy Expertise Gap:Precision casting of corrosion-resistant alloys requires skills concentrated in Austrian and Swiss engineering clusters, constraining workforce scaling.
- Grid Interconnection Certification Delays:Evolving IEC standards for distributed generation create timeline uncertainty for modular system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroelectric Cells Market |
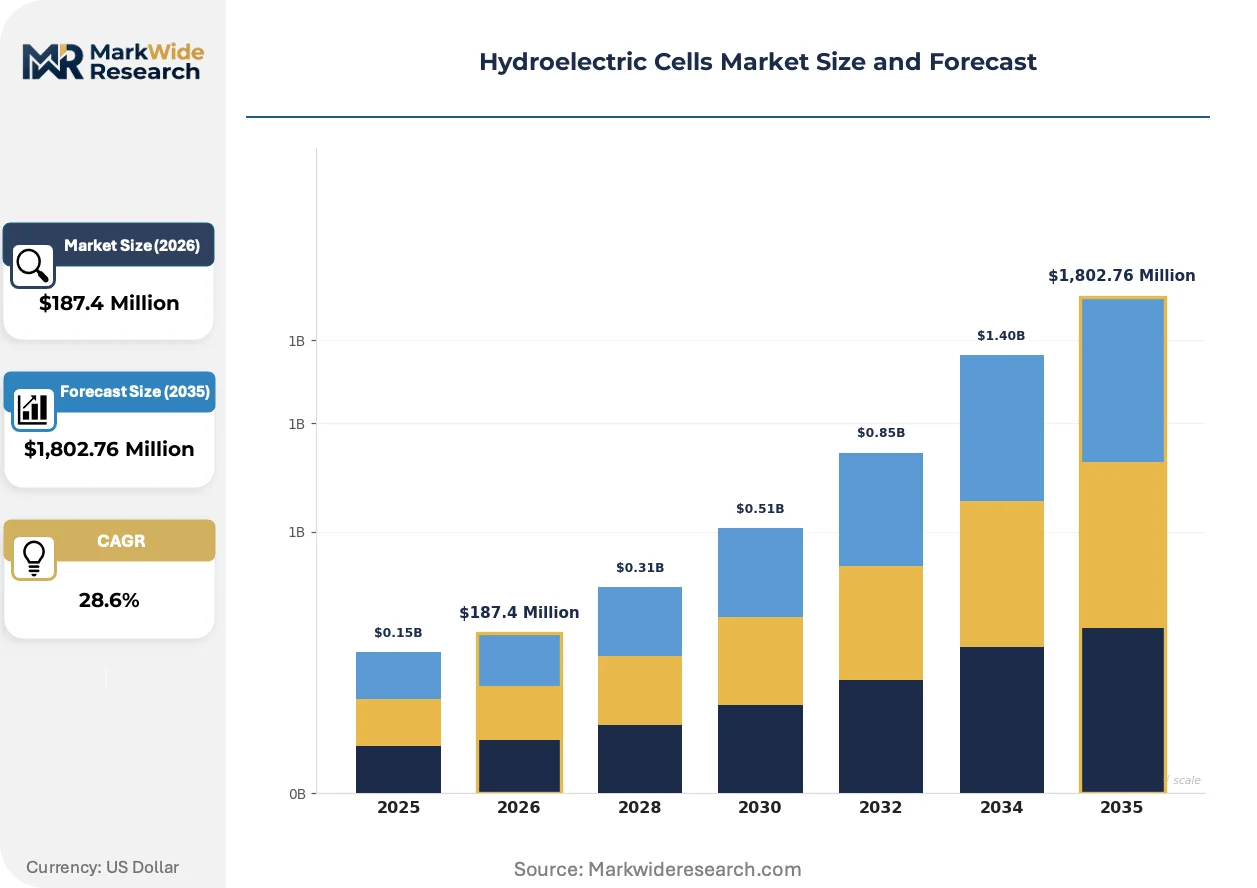
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic Turbines, Pumped Storage, Run-of-River, Modular Systems End User: Utilities, Industrial Facilities, Municipalities, Commercial Installations Application: Power Generation, Energy Storage, Water Management, Flood Control Installation: Onshore, Offshore, Hybrid Systems, Retrofitting |
| Companies Covered | IHI Corporation, China Three Gorges Corporation, GE Renewable Energy, Tata Power Company Limited, ABB Ltd., Sinohydro Corporation Limited, China Hydroelectric Corporation, Voith GmbH, Andritz AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroelectric Cells Market Shifts & Advancements
Digital twin technology and predictive maintenance platforms are rewiring how operators manage turbine fleets, shifting capital allocation from reactive repairs to lifecycle optimization contracts.
Variable-speed generator technology with full power conversion is electrifying grid integration capabilities for low-head installations. Remote mining operations in Chile and Peru adopt these systems to stabilize captive microgrids. The technology is electrifying previously stranded hydro resources by eliminating synchronous speed constraints.
The EU Green Deal's taxonomy alignment requirements now govern equipment financing eligibility for European hydroelectric projects. Banks and institutional lenders screen turbine suppliers against sustainability criteria. German and Austrian refurbishment projects face compressed supplier qualification timelines as lenders tighten ESG due diligence.
Industrial offtakers in Brazil and Southeast Asia now contract directly with equipment vendors for energy-as-a-service arrangements, bypassing traditional utility intermediaries. Aluminum smelters and data centers negotiate long-term fixed rates in exchange offtake guarantees. This pattern concentrates procurement power among energy-intensive manufacturers with balance sheet capacity.
Hydroelectric Cells Market Segmentation
Technology differentiation in hydroelectric cells determines capital intensity, grid integration complexity, and revenue stability. Equipment suppliers structure product portfolios around head pressure ranges and dispatch flexibility rather than generic power ratings.
Technology:
Premium efficiency installations command higher margins but face longer development timelines, while volume deployment concentrates in standardized configurations that compress manufacturing costs.
- Hydraulic Turbines:Conventional reaction and impulse turbine designs operate across 5–500 meter head ranges with synchronous generator coupling. Demand concentrates in China's state-backed refurbishment programs where MIIT efficiency mandates drive runner replacement cycles.
- Pumped Storage:Dual-mode systems combine generation with reversible pumping capability for grid-scale arbitrage. European utilities in Germany and Switzerland prioritize these installations to capture frequency regulation payments under evolving grid codes.
- Run-of-River:Diversion-based systems without reservoir buffering suit consistent flow regimes. Seasonal variability constrains power purchase agreement tenors in drought-prone regions.
- Modular Systems:Containerized turbine packages enable rapid deployment at sub-10MW scale. Remote industrial offtakers in Chilean mining districts and Indonesian islands adopt these for captive microgrids.
Mature deployment sits with hydraulic turbines. Newer deployment is concentrated in modular systems.
End User:
Customer type shapes procurement scale, financing structure, and equipment customization requirements across the value chain.
- Utilities:Grid-scale operators procure multi-hundred-megawatt installations with 30-year asset horizons. China's provincial power corporations dominate procurement volume through state planning mechanisms.
- Industrial Facilities:Aluminum smelters, data centers, and mining operations negotiate energy-as-a-service contracts directly with equipment vendors. Brazilian manufacturing clusters increasingly bypass utility intermediaries for price certainty.
- Municipalities:Local water authorities integrate small-scale generation into existing dam infrastructure for revenue diversification. European cities prioritize refurbishment over greenfield development.
- Commercial Installations:Campus-scale microgrids serve universities, hospitals, and retail complexes. Southeast Asian commercial developments combine solar daytime generation with turbine evening dispatch.
Procurement scale peaks with utilities. Direct vendor contracting is expanding fastest among industrial facilities.
Application:
Functional use case determines equipment specification, revenue stacking potential, and regulatory treatment.
- Power Generation:Baseload and peaking capacity provision remains the dominant revenue model. India's CEA mandates pumped storage obligations for interstate transmission licensees, embedding procurement demand.
- Energy Storage:Reversible turbine-pump configurations enable diurnal arbitrage and grid stabilization services. Deregulated European markets stack multiple revenue streams.
- Water Management:Multi-purpose dams integrate generation with irrigation and potable supply. China's South-North Water Transfer project corridors concentrate integrated infrastructure.
- Flood Control:Reservoir-based systems provide seasonal flow regulation alongside power output. US Army Corps of Engineers installations prioritize this dual function.
Revenue concentration rests with power generation. Energy storage is climbing the fastest as grid flexibility premiums expand.
Installation:
Site configuration dictates civil engineering intensity, environmental permitting complexity, and equipment delivery logistics.
- Onshore:Conventional dam and diversion structures on riverine systems. Belt and Road corridors in Pakistan and Laos concentrate greenfield construction.
- Offshore:Tidal and marine current installations in coastal waters. Limited deployment concentrates in demonstration projects.
- Hybrid Systems:Integrated solar-hydro or wind-hydro configurations optimize capacity factors. Philippine island microgrids combine photovoltaic arrays with run-of-river evening dispatch.
- Retrofitting:Runner and generator upgrades at existing dam sites. Germany's KBA prioritizes efficiency improvements over new construction.
Civil works intensity peaks with onshore greenfield. Retrofitting is gaining share fastest as European infrastructure ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global turbine manufacturing capacity, with precision casting clusters in Shanghai and Hangzhou supplying runner assemblies to domestic refurbishment programs and Belt and Road export corridors.
China
Provincial power corporations in Sichuan and Yunnan drive procurement volumes through state planning mechanisms that prioritize pumped storage integration. MIIT enforces GB efficiency standards that gate market access for imported turbine assemblies, favoring domestic and compliant foreign suppliers. The South-North Water Transfer project corridors concentrate multi-purpose dam infrastructure combining generation with irrigation and potable supply.
Germany
Grid operators in Bavaria and Baden-Württemberg prioritize runner replacements over greenfield development, creating sustained refurbishment demand. KBA efficiency mandates and grid interconnection codes reshape equipment certification timelines for distributed generation assets. The Rhine-Main industrial cluster hosts precision engineering workshops specializing in corrosion-resistant alloy casting for turbine blade metallurgy.
United States
FERC licensing reforms accelerate deployment timelines for run-of-river installations on federal waterways, particularly in the Pacific Northwest. The US Army Corps of Engineers prioritizes flood control dual-function reservoirs alongside power output in the Tennessee Valley and Columbia River systems. Remote mining operations in Nevada and Arizona adopt modular turbine packages for captive microgrids.
India
Interstate transmission licensees face CEA-mandated pumped storage obligations through 2030, embedding guaranteed equipment procurement demand. Himalayan run-of-river corridors in Himachal Pradesh and Uttarakhand attract developer interest despite seasonal flow variability challenges. Western Ghats industrial clusters in Maharashtra negotiate energy-as-a-service contracts directly with equipment vendors for price certainty.
Brazil
Aluminum smelters in the Amazon basin and manufacturing clusters in São Paulo state bypass utility intermediaries for long-term fixed-rate contracts. ANEEL regulatory frameworks support distributed generation interconnection for industrial self-supply arrangements. The Itaipu corridor exemplifies binational infrastructure financing models that reduce offtaker capital requirements through development bank participation.
Hydroelectric Cells Market Competitive Landscape
Premium-margin players sit above commodity-margin players across efficiency certification tiers and digital integration depth. The vendor base stratifies between precision-engineered runner specialists, turnkey infrastructure contractors, and modular system integrators. Three archetypes dominate: European refurbishment specialists leveraging legacy metallurgy expertise, Chinese state-linked entities capturing domestic procurement mandates, and diversified industrial conglomerates bundling turbine supply with grid infrastructure. Consolidation pressures concentrate among mid-scale fabricators lacking captive rare earth magnet supply or digital control platform differentiation.
Among diversified industrial conglomerates, GE Renewable Energy and ABB Ltd. exemplify premium-tier positioning through digital turbine control integration. Voith GmbH and Andritz AG occupy the European specialist archetype, anchoring refurbishment demand with precision casting capabilities concentrated in Alpine engineering clusters. Sinohydro Corporation Limited represents the turnkey infrastructure contractor model, competing on Belt and Road delivery scale across emerging economy corridors.
| Leading Market Players |
|---|
| IHI Corporation |
| China Three Gorges Corporation |
| GE Renewable Energy |
| Tata Power Company Limited |
| ABB Ltd. |
| Sinohydro Corporation Limited |
| China Hydroelectric Corporation |
| Voith GmbH |
| Andritz AG |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating low-GWP hydraulic fluid formulations, forcing OEMs to absorb reformulation costs or forfeit European procurement eligibility. Buyers with sustainability-linked financing requirements now screen turbine suppliers against taxonomy alignment criteria, bifurcating the vendor base between certified premium providers and excluded commodity fabricators.
Pricing Analysis
Energy-as-a-service contracts anchor value-based pricing, with aluminum smelters and data centers trading offtake guarantees for long-term rate certainty. Price differentiation rests on MIIT GB efficiency certification tier and digital twin integration depth, separating premium runner replacements from standard commodity assemblies. Cost compression in run-of-river installations intensifies because seasonal output variability undermines power purchase agreement bankability. Industrial offtakers in Brazilian manufacturing clusters exhibit highest price sensitivity, while European utilities with refurbishment mandates show lowest sensitivity due to regulatory compliance deadlines.
Supply Chain Analysis
China's MIIT local-content rules reshape sourcing by requiring domestic assembly for GB efficiency certification, compelling foreign OEMs to joint-venture with Shanghai and Hangzhou precision casting clusters. Runner metallurgy feeds from Austrian and Swiss engineering workshops, while permanent magnet generators hinge on neodymium processing concentrated in Chinese facilities. Single-source vulnerability in rare earth magnet supply exposes turbine OEMs to price volatility and export restriction risk. Distribution runs through state-linked procurement mechanisms in China, direct vendor contracting in Brazil, and EPC-led turnkey delivery across Belt and Road corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive neodymium magnet supply and in-house precision casting capabilities determine margin defense. Players are pursuing backward integration into rare earth processing and corrosion-resistant alloy foundries to escape input cost volatility.
For Market Incumbents: Extend digital twin platform penetration into lifecycle optimization contracts, converting equipment sales into recurring service revenue. Deepen captive supply of neodymium magnets through offtake agreements with Chinese processing facilities to offset price volatility. Defend against modular system integrators by embedding predictive maintenance capabilities that commoditized hardware competitors cannot replicate.
For New Entrants and Emerging Players: The mid-tier pricing gap between GE Renewable Energy's premium digital offerings and Sinohydro's commodity turnkey deliveries creates white-space opportunity. Target Indonesian and Philippine island microgrids with containerized solar-hybrid configurations that bypass established utility procurement channels. Enter through energy-as-a-service arrangements with remote mining operations seeking captive supply without capital expenditure burden.
For Investors and Strategic Acquirers: India's CEA pumped storage obligation announcements are the leading indicator that equipment procurement demand will concentrate among compliant turbine OEMs. Frame long-term viability around refurbishment cycle capture in aging European infrastructure and modular deployment scale in emerging economy microgrids. Acquisition targets should prioritize precision casting specialists with Alpine metallurgy expertise and digital control platform developers. Monitor F-Gas Regulation enforcement intensity as the signal for European supplier qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive neodymium supply insulates turbine OEMs from Chinese export volatility and price swings. |
| Digital Twin Platform Deployment | Predictive maintenance contracts with European utilities convert hardware margins into recurring service revenue. |
| Energy-as-a-Service Contracting | Direct vendor relationships with Brazilian aluminum smelters bypass utility intermediaries and price controls. |
| GB Efficiency Certification Investment | MIIT compliance unlocks China's state-backed refurbishment procurement and Belt and Road export corridors. |
| Hybrid Solar-Hydro Microgrid Development | Philippine and Indonesian island installations reduce diesel dependence while capturing evening dispatch premiums. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and precision casting specialists underwrites the qualitative findings in this study. Primary interviews with turbine OEM procurement heads and aftermarket service directors combined with secondary validation from FERC filings, IEA hydropower databases, and MIIT equipment certification records established input parameters. Bottom-up project pipeline aggregation and top-down national capacity targets were reconciled to anchor volume estimates.
Comparable-period anchoring to historical refurbishment cycles and pumped storage commissioning timelines structured the forecast window across the analysis window. Segmentation dimensions modeled include head pressure range, dispatch flexibility mode, end-user procurement scale, and regional regulatory framework cluster. CAGRs were derived from equipment order backlogs, state planning mechanism disclosures, and interconnection queue data. Forecast inputs incorporated neodymium price trajectory assumptions and evolving grid code certification timelines.
Inputs from utility procurement databases and EPC contractor pipelines were available through the study window; gaps in modular system deployment records and remote industrial offtake contract terms introduce uncertainty bands around microgrid penetration assumptions. Forecasts reflect documented assumptions regarding MIIT mandate enforcement consistency and F-Gas Regulation phase-down schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Solar Boat Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Hybrid Power System Market