
 Automated Mooring System Market | 2026-2036
Automated Mooring System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Mooring System Market Analytics
Buyer concentration among container terminal operators is hardening as mega-ports consolidate procurement across multi-berth expansions. Cavotec SA leverages its vacuum mooring installed base to sustain service revenue across European and Asian harbor authorities. Trelleborg Marine & Infrastructure anchors its position through integrated fender-mooring packages that dominate Nordic port retrofits. MacGregor competes with shipboard automated tensioning systems that extend its crane engineering heritage into berthing operations.
Automated mooring systems mechanize vessel securing through vacuum pads, magnetic clamps, or automated line tensioners that replace manual deck crew operations with sensor-driven, remotely controlled interfaces. Hydraulic technology dominates current installations due to proven load capacity exceeding 1,000 kN per unit, though electronic control layers are displacing manual valve systems for precision tension management. Container handling applications generate the largest revenue pool given berth throughput premiums, while emergency mooring represents the fastest-expanding segment as climate-adaptation codes mandate rapid-deployment securing for extreme weather events. Fixed installations retain margin concentration through long-term service contracts, though floating systems for offshore platforms are gaining technology investment.
IMO's greenhouse gas strategy and port state control amendments under MARPOL Annex VI are tightening mooring-time limits that favor automated rapid-release systems. Classification societies including DNV and Lloyd's Register have incorporated automated mooring verification into their port infrastructure certification protocols. Stakeholders must monitor how port electrification mandates reshape power supply requirements for electrically actuated mooring units.
Market Dynamics
Port electrification mandates and IMO emissions targets are compressing berth turnaround windows, forcing terminal operators to replace manual mooring crews with sensor-driven automated systems that cut vessel securing time from 45 minutes to under 10 minutes.
Growth Catalysts
- IMO MARPOL Annex VI amendments:Tightening mooring-time limits at emission-control areas favor rapid-release automated systems over conventional line handling.
- Container terminal consolidation:Mega-port developments across Singapore, Rotterdam, and Jebel Ali are bundling multi-berth procurement decisions that favor standardized automated mooring platforms.
- Vacuum pad technology maturation:Load capacities exceeding 1,000 kN per unit now match hydraulic reliability with faster deployment cycles.
Market Restraints
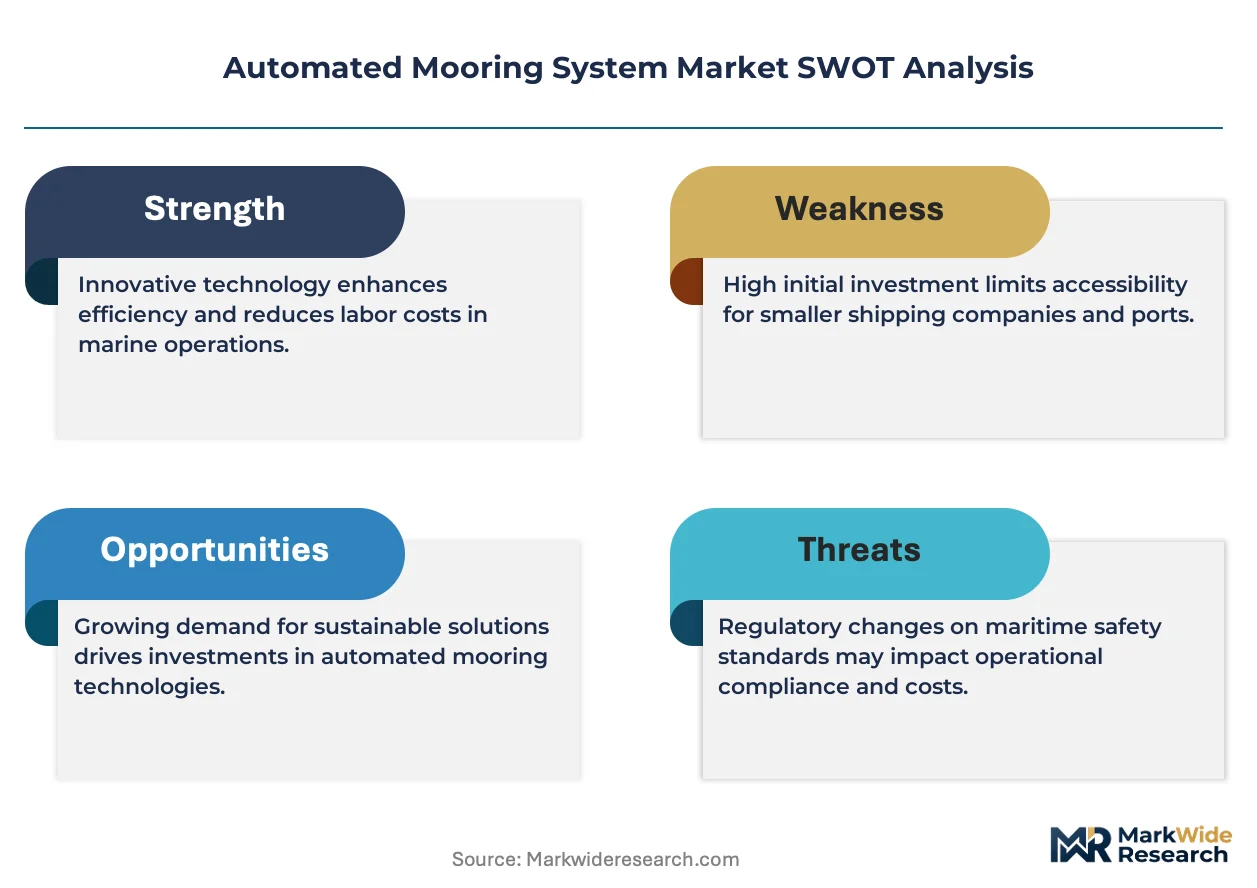
- Stainless steel and rare-earth magnet input costs:Price volatility in neodymium and specialized alloys constrains magnetic mooring system margins.
- European harbor equipment supply concentration:Three Nordic manufacturers control critical vacuum pump and seal technologies.
- Classification society certification timelines:DNV and Lloyd's Register verification protocols for automated mooring add 14-18 months to port infrastructure deployment schedules.
Strategic Opportunities
- Saudi Arabia's King Abdullah Port expansion:Next-generation berthing infrastructure commissioning creates demand for integrated vacuum-mooring installations.
- Offshore floating production platforms:Dynamic positioning vessels require automated tensioning systems for station-keeping in harsh environments.
- EU Green Deal port electrification incentives:Electrically actuated mooring units qualify for infrastructure decarbonization funding pools.
Industry Challenges
- Marine automation engineer scarcity:Port authorities struggle to recruit technicians capable of maintaining sensor-driven vacuum and magnetic control systems.
- Legacy bollard integration complexity:Retrofitting existing quay walls with automated clamps requires structural reinforcement incompatible with 1970s-era berth designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Mooring System Market |
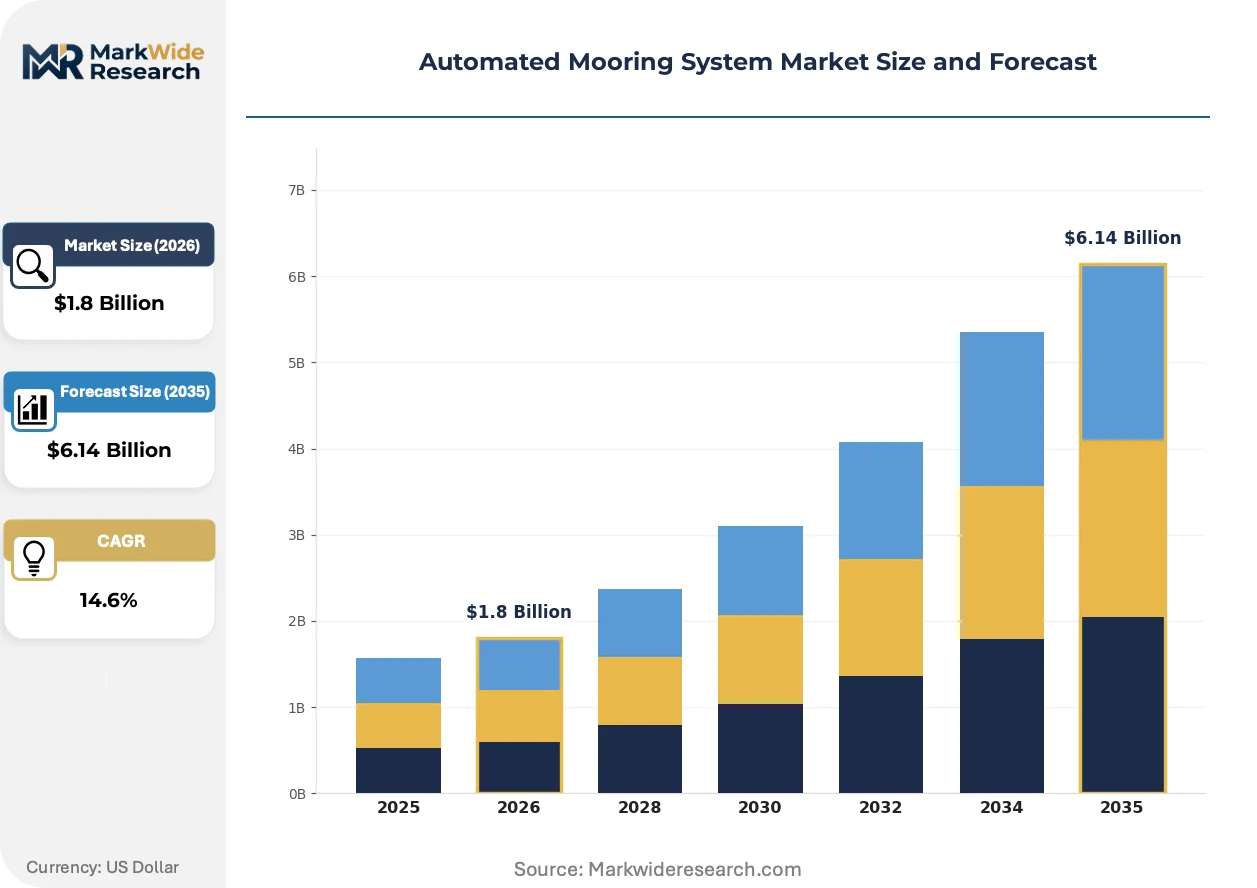
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic, Electronic, Mechanical, Pneumatic End User: Ports, Offshore Platforms, Shipbuilders, Logistics Providers Installation Type: Fixed, Floating, Semi-Floating, Mobile Application: Container Handling, Vessel Transfer, Cargo Loading, Emergency Mooring |
| Companies Covered | Cavotec SA, Trelleborg Marine & Infrastructure, MacGregor, Mampaey Offshore Industries, TTS Group ASA, Seaflex AB, ABC Moorings, ZAD Marine, C-QUIP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Mooring System Market Evolving Landscape
Sensor fusion and edge computing are redefining how mooring forces are monitored and adjusted in real time, shifting competitive advantage from mechanical load capacity to predictive tension algorithms.
Magnetic clamp systems incorporating rare-earth permanent magnets and electromagnetic quick-release mechanisms are decentralizing mooring control from central quay-side winch houses to distributed pad arrays. Offshore support vessel operators in the North Sea are piloting these configurations for rapid crew transfer operations. The technology is decentralizing maintenance responsibility from port authorities to vessel operators who retain clamp units onboard.
EU F-Gas Regulation restrictions on hydraulic fluid formulations are accelerating adoption of dry electromechanical actuators in European container terminals. Port authorities in Hamburg and Antwerp face compliance deadlines that favor all-electric mooring architectures over conventional hydraulic systems. The regulation is compressing technology replacement cycles that previously spanned 25 years.
Terminal operators are unbundling long-term service contracts from initial equipment procurement, favoring multi-vendor maintenance agreements that separate mechanical, electronic, and software support. This pattern disrupts integrated fender-mooring package vendors who historically captured 15-year service lock-in. The shift is most visible at UAE's Khalifa Port, where berth operators now contract sensor calibration and vacuum seal replacement through distinct specialist providers.
Automated Mooring System Market Segmentation
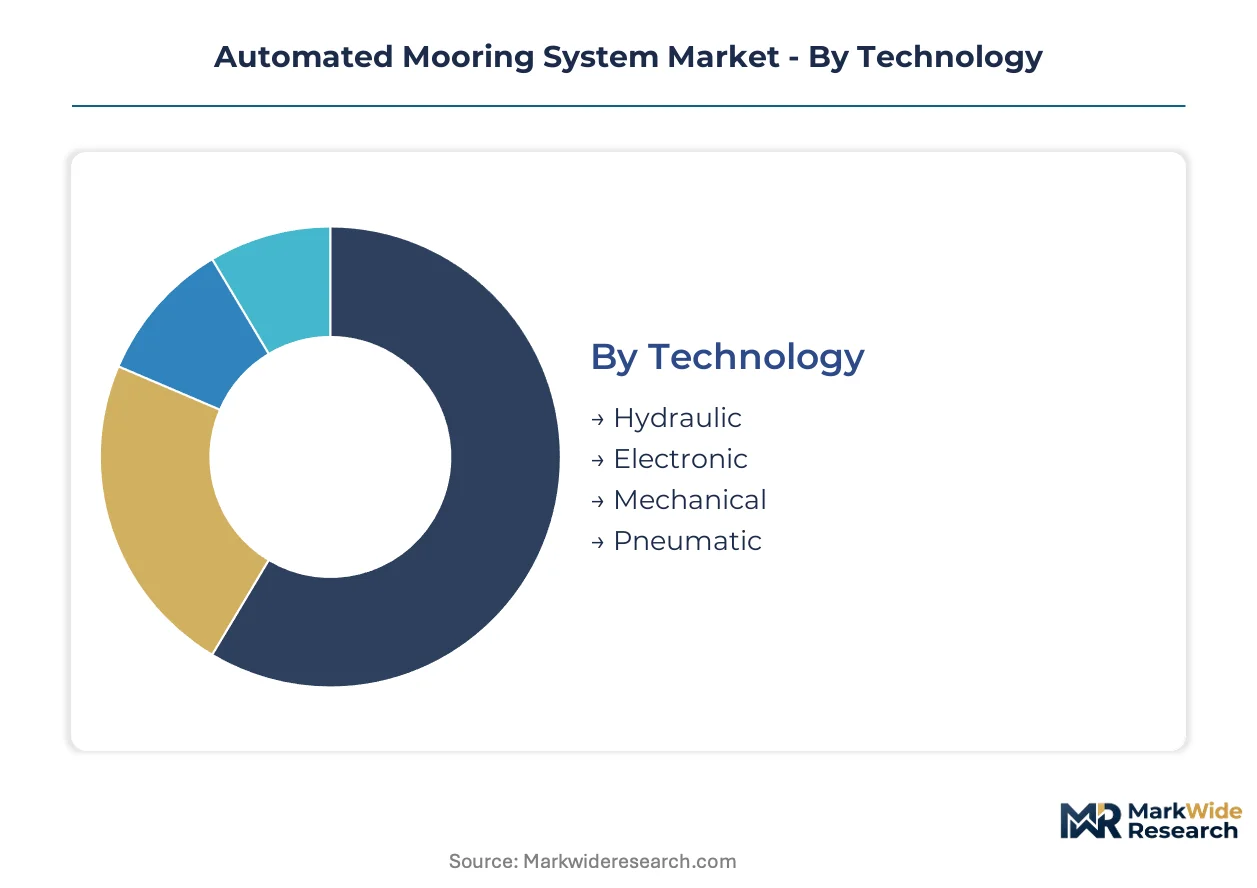
Automated mooring system procurement varies sharply by technical architecture and deployment context. Capital allocation decisions hinge on load capacity requirements, berth retrofit feasibility, and regulatory compliance timelines that differ across port, offshore, and vessel-side applications.
Technology:
Hydraulic systems demand the heaviest upfront capital outlay due to high-pressure pump infrastructure and fluid containment systems, while electronic architectures require precision sensor networks with lower mechanical footprint.
- Hydraulic:High-pressure fluid systems deliver load capacities exceeding 1,000 kN per unit through centralized pump houses and distributed cylinder arrays. Demand concentrates at Rotterdam and Singapore mega-ports where proven reliability outweighs electrification mandates.
- Electronic:Sensor-driven servo motors and variable-frequency drives enable millimeter-precision tension control with remote diagnostics capability. Hamburg and Antwerp terminal operators are accelerating procurement ahead of EU F-Gas Regulation deadlines that penalize hydraulic fluid leakage.
- Mechanical:Cam-based and ratchet tensioners serve legacy bollard retrofits where electrical infrastructure is absent.
- Pneumatic:Compressed air systems find niche deployment in explosive-atmosphere zones where spark-free operation is mandatory.
Hydraulic technology absorbs the bulk of installed capacity; electronic systems are expanding most quickly.
End User:
Port authorities dominate procurement volume through multi-berth standardization programs, while offshore operators prioritize mobility and rapid redeployment capability.
- Ports:Container terminal operators at King Abdullah Port and Khalifa Port are bundling automated mooring into integrated berth electrification packages. Saudi Arabia and UAE procurement offices are consolidating vendor selection across 12-berth expansions to capture scale economies in maintenance training.
- Offshore Platforms:Floating production units require dynamic tensioning systems that compensate for vessel motion in North Sea and Gulf of Mexico environments. Station-keeping applications favor magnetic clamp arrays that detach under emergency release protocols.
- Shipbuilders:Newbuild container vessels are integrating shipboard automated tensioning as standard equipment to reduce port dependency.
- Logistics Providers:Third-party terminal operators at secondary ports adopt mobile mooring units to avoid fixed infrastructure commitments.
Ports command the largest procurement budgets; offshore platforms are climbing the fastest as floating production investment accelerates.
Installation Type:
Fixed installations generate recurring service revenue through long-term maintenance contracts, while floating systems trade capital efficiency against weather vulnerability.
- Fixed:Permanent quay-side vacuum pad arrays dominate European and Middle Eastern mega-port developments. Cavotec SA and Trelleborg have captured retrofit markets through structural reinforcement packages that extend 1970s-era berth lifespans.
- Floating:Buoy-mounted tensioning systems serve offshore loading terminals and temporary military logistics berths. UAE and Qatar are piloting configurations for rapid-deployment humanitarian supply corridors.
- Semi-Floating:Hybrid architectures anchor to seabed piles while allowing limited vertical motion compensation.
- Mobile:Trailer-mounted units enable emergency mooring at disaster-relief ports and seasonal cruise terminals.
Fixed installations retain margin concentration through service lock-in; floating systems are gaining share fastest in offshore energy applications.
Application:
Container handling justifies premium pricing through berth throughput premiums, while emergency mooring is attracting regulatory-driven procurement.
- Container Handling:Automated vacuum mooring at Jebel Ali and Rotterdam cuts vessel securing from 45 minutes to under 10 minutes, enabling fourth daily berth rotation. Terminal operators recover capital costs through quay crane utilization premiums.
- Emergency Mooring:IMO climate-adaptation codes are mandating rapid-deployment securing systems for extreme weather events at Pacific and North Atlantic ports. Magnetic quick-release clamps allow 90-second vessel evacuation protocols.
- Vessel Transfer:Crew change and pilot boarding operations use lightweight automated tensioning at offshore wind farm service bases.
- Cargo Loading:Bulk commodity terminals deploy heavy-duty hydraulic clamps for ore carrier and LNG vessel securing.
Container handling captures the dominant revenue share; emergency mooring is expanding most steeply as classification societies incorporate climate resilience into port certification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium deposits in China's Inner Mongolia and stainless steel production clusters in Germany's Ruhr Valley anchor the automated mooring supply chain. Procurement decisions concentrate where mega-port developments intersect with stringent emissions mandates.
Saudi Arabia
King Abdullah Port's 12-berth expansion drives vacuum mooring demand for container throughput optimization. MOHAP port infrastructure codes align with IMO MARPOL Annex VI timelines. King Abdullah Economic City anchors Red Sea logistics corridors with integrated berthing electrification packages.
United Arab Emirates
Khalifa Port bundles multi-berth automated mooring procurement across Abu Dhabi terminal expansions. Federal Transport Authority regulations mandate rapid-release systems for extreme weather preparedness. Jebel Ali's fourth daily berth rotation targets depend on sub-10-minute vessel securing cycles.
Germany
Hamburg and Bremerhaven terminal operators accelerate electronic mooring procurement ahead of EU F-Gas Regulation hydraulic fluid deadlines. ECHA restrictions on synthetic ester formulations compress 25-year replacement cycles. The Port of Hamburg's Elbe River expansion integrates sensor-driven tension management.
Netherlands
Rotterdam's Maasvlakte 2 development sustains hydraulic system demand where 1,000+ kN load capacity outweighs electrification premiums. Port of Rotterdam Authority procurement standards favor proven reliability for Europe's largest container throughput. The Rhine-Meuse-Scheldt delta cluster dominates North Sea mooring technology validation.
Singapore
Tuas Port's phased opening consolidates automated mooring decisions across PSA International's terminal network. Maritime and Port Authority of Singapore mandates align with IMO greenhouse gas strategy implementation. The Tuas mega-port development bundles 65 million TEU capacity with standardized vacuum pad arrays.
Automated Mooring System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue offshore floating applications and electric actuator niches. The supplier base concentrates among Nordic harbor equipment specialists and diversified marine engineering groups. Three archetypes dominate: integrated fender-mooring package vendors, vacuum pad technology originators, and shipboard tensioning system engineers. Competitive moves center on multi-berth procurement bundling and unbundled service contract fragmentation.
Among Nordic specialists, Cavotec SA and Trelleborg Marine & Infrastructure exemplify the integrated package archetype, while MacGregor occupies a position bridging shipboard and port-side applications. These three entities anchor the competitive structure through distinct technology lineages—vacuum systems, fender-mooring bundling, and crane heritage extension—without overlapping core positioning. Mampaey Offshore Industries and TTS Group ASA represent alternative specialization vectors in offshore and lifting equipment domains respectively.
| Leading Market Players |
|---|
| Cavotec SA |
| Trelleborg Marine & Infrastructure |
| MacGregor |
| Mampaey Offshore Industries |
| TTS Group ASA |
| Seaflex AB |
| ABC Moorings |
| ZAD Marine |
| C-QUIP |
| Others |
Value Network & Pricing Analysis
Backward integration into rare-earth magnet and specialized alloy supply anchors competitive positioning for automated mooring system manufacturers, with in-house sourcing of neodymium and stainless steel feedstock insulating margins from commodity volatility while locking in capacity for vacuum pump and electromagnetic clamp production. This captive supply structure concentrates pricing power among Nordic equipment specialists who dominate critical seal and pump technologies, forcing terminal operators to accept bundled service terms or face extended lead times for multi-berth mega-port deployments.
Pricing Analysis
Warranty and service contract unbundling is fragmenting historical pricing structures, with terminal operators at UAE's Khalifa Port and Saudi Arabia's King Abdullah Port now separating mechanical maintenance from sensor calibration and software support. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and load capacity tier, with DNV-verified vacuum pad arrays commanding substantial premiums over Lloyd's Register baseline configurations. Price erosion runs through economy-tier hydraulic retrofits as Chinese component suppliers enter seal and pump markets. Port authorities with consolidated multi-berth procurement exhibit lowest price sensitivity, while third-party logistics providers at secondary terminals drive hardest bargain on mobile unit rentals.
Supply Chain Analysis
Marine automation engineer scarcity in Germany's Ruhr Valley and Sweden's industrial corridor constrains final assembly capacity for vacuum pump and electromagnetic control systems, forcing manufacturers to extend training pipelines or relocate production stages. Neodymium mining concentrates in China's Inner Mongolia and stainless steel production clusters in Germany, with rare-earth magnet supply drawing from a narrow geographic base that amplifies tariff exposure. Hydraulic fluid formulation restrictions under EU F-Gas Regulation compound input dependencies, as compliant synthetic ester alternatives source from limited specialty chemical producers. Distribution runs through direct port authority contracts for fixed installations, while floating systems reach offshore operators via marine engineering integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated mooring system supply is tightening around certified vacuum pump and electromagnetic seal manufacturing capacity, with only three Nordic producers qualified for DNV and Lloyd's Register verification protocols, propping pricing power for incumbent equipment vendors through the projection horizon.
For Market Incumbents: Lock in multi-berth procurement bundling at Saudi Arabia's King Abdullah Port and Singapore's Tuas mega-port developments before emerging electric actuator specialists capture EU Green Deal infrastructure subsidies. Extend structural reinforcement service packages for 1970s-era berth retrofits to capture 15-year maintenance lock-in that unbundling trends threaten to fragment. Prioritize in-house magnet alloy sourcing to neutralize neodymium price volatility eroding magnetic mooring margins. For New Entrants and Emerging Players: Electromechanical actuator miniaturization for shipboard tensioning systems offers the most penetrable wedge, as MacGregor's crane heritage extension leaves gaps in vessel-side automated line handling for mid-size container newbuilds. Target offshore floating production platforms in the North Sea and Gulf of Mexico where dynamic positioning station-keeping demand outpaces established port-side vendor capacity. Lead with predictive tension algorithms and edge computing diagnostics to differentiate from hydraulic reliability incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified marine engineering groups seeking port electrification exposure, with strategic acquirers from crane and fender system adjacent markets most active. Five-to-ten year viability hinges on securing classification society certification capacity that DNV and Lloyd's Register verification timelines constrain. Watch for IMO MARPOL Annex VI amendment acceleration as the inflection signal that compresses replacement cycles and expands addressable retrofit volume.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Certification Investment | DNV and Lloyd's Register verification protocols add 14-18 months to deployment but lock out unqualified competitors. |
| Rare-Earth Magnet Backward Integration | Captive neodymium supply from China's Inner Mongolia insulates margins from commodity volatility in magnetic clamp production. |
| Multi-Berth Procurement Bundling | Khalifa Port and King Abdullah Port 12-berth expansions favor standardized platforms that amortize maintenance training costs. |
| Electromechanical Actuator Development | EU F-Gas Regulation deadlines at Hamburg and Antwerp accelerate demand for dry electric architectures over hydraulic systems. |
| Sensor Fusion Platform Integration | Predictive tension algorithms leveraging edge computing redefine competitive advantage from mechanical load capacity to software-defined mooring. |
Research Methodology
Document review covered customs and trade data for hydraulic and electromagnetic mooring equipment, port authority procurement disclosures, and classification society certification registries, complemented by interviews with terminal operations directors, marine automation engineers, and harbor equipment procurement managers at Rotterdam, Singapore, and Jebel Ali. Secondary validation drew from IMO MARPOL Annex VI amendment filings, EU F-Gas Regulation compliance databases, and SEC disclosures from listed marine engineering groups. Bottom-up vessel securing time reduction metrics and top-down mega-port capital expenditure pipelines were triangulated to anchor demand estimates.
Cross-referencing historical berth electrification investment patterns against panel input from port infrastructure planners and EPC contractors shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology architecture, installation type, end-user category, and regional regulatory cluster. CAGRs were derived from deployment velocity differentials between hydraulic retrofits and greenfield electronic installations, with vacuum pad load capacity maturation and IMO emissions mandate enforcement timelines serving as primary forecast inputs.
Several conditions sit outside the modeled scope, including sudden tariff disruptions to rare-earth magnet trade flows, unanticipated classification society protocol revisions, and port authority bankruptcy events that stall multi-berth procurement programs. Forecasts reflect assumptions regarding continued IMO MARPOL Annex VI enforcement trajectory and EU F-Gas Regulation compliance deadlines without slippage. Material deviation in neodymium supply availability or DNV verification timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Tugboat Operation Market