
 Platform Supply Vessels (PSV) Market | 2026-2036
Platform Supply Vessels (PSV) Market Size, Share, and Industry Trends Forecast 2026-2036
Platform Supply Vessels (PSV) Market Intelligence
A shortage of certified marine engineers with hybrid propulsion expertise is unwinding delivery schedules across the newbuild pipeline. Tidewater Inc. leverages its Gulf of Mexico fleet concentration to sustain day-rate premiums in the Americas basin. Edison Chouest Offshore Co. anchors its competitive stance through in-house shipyard capacity and crew training academies. BOURBON Maritime competes on European offshore wind logistics contracts with a specialized shallow-draft PSV subset.
Platform Supply Vessels are offshore support ships engineered to transport cargo, equipment, and personnel to oil platforms and wind installations, typically measuring 65–95 meters in length with deck loads exceeding 2,000 tonnes and dynamic positioning class 2 or 3 certification. Their primary function centers on logistics continuity for fixed and floating energy infrastructure operating beyond port range. Diesel-electric propulsion dominates the current fleet base due to operational flexibility and fuel efficiency at variable loads, while battery-powered configurations are capturing newbuild interest as harbor emissions rules tighten. Offshore wind farm supply applications are expanding fastest among the demand categories, driven by turbine scale-up and installation campaign intensity in Northern European waters.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index and Carbon Intensity Indicator standards that compel engine upgrades or early retirements across aging PSV fleets. Classification societies including DNV and Lloyd's Register have introduced notations for battery-hybrid and methanol-ready designs that shape owner newbuild specifications and finance approval terms. Stakeholders must weigh retrofit economics against scrap values as regulatory compliance deadlines approach for vessels built during the last offshore boom cycle.
Market Dynamics
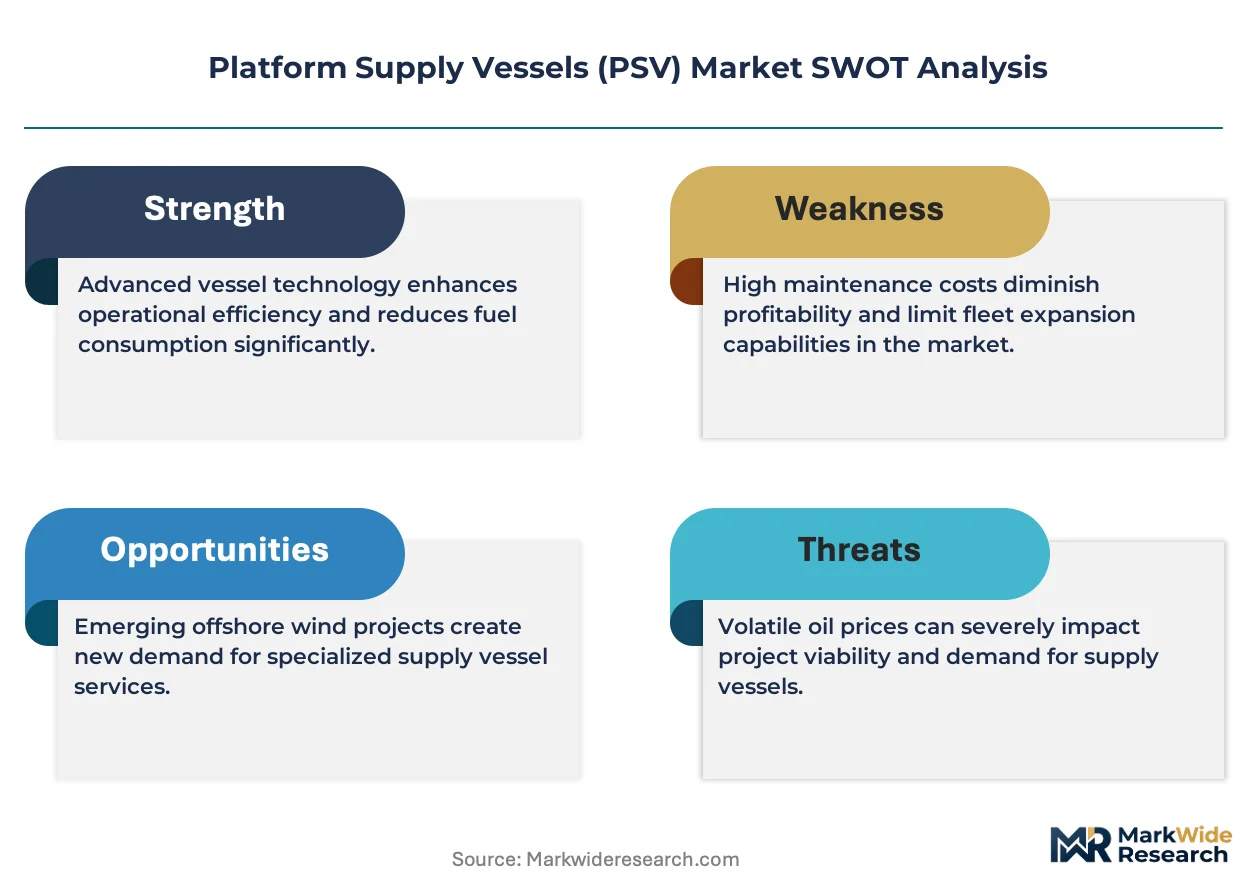
The International Maritime Organization's Carbon Intensity Indicator is compressing vessel utilization rates across aging diesel-electric fleets, forcing owners to choose between costly hybrid retrofits and accelerated scrapping decisions.
Growth Catalysts
- Offshore wind installation intensity:Turbine scale-up in Northern European waters is generating dedicated vessel demand for component transport and technician transfer operations.
- IMO EEXI compliance mandates:Engine upgrade requirements for existing vessels are sustaining aftermarket service revenue and equipment supplier order books.
- Battery-hybrid propulsion maturation:Harbor emissions regulations in Norway, the United Kingdom, and Denmark are validating shore-power integration and energy storage architectures.
Market Restraints
- Marine battery supply concentration:Korean and Chinese cell manufacturers control cathode chemistry supply, creating input cost volatility and delivery uncertainty for European shipyards.
- Methanol bunkering infrastructure gaps:Dual-fuel newbuild specifications outpace port fuel availability in the North Sea corridor, stranding capital commitments.
- Classification society divergence:DNV and Lloyd's Register apply differing notations for hybrid system safety, complicating owner specification decisions and finance approval timelines.
Strategic Opportunities
- US Gulf of Mexico reactivation:Decommissioning obligations for mature offshore platforms are generating demand for plug-and-abandonment support vessels with specialized cargo configurations.
- Walk-to-work gangway integration:Turbine technician transfer systems are converging with dynamic positioning upgrades, opening premium day-rate tiers for vessel operators.
- EU Green Deal vessel financing:Sustainable finance taxonomy alignment is unlocking green bond proceeds for newbuild projects with battery-hybrid or hydrogen-ready specifications.
Industry Challenges
- Hybrid propulsion engineering scarcity:Certified marine engineers with integrated power system expertise command wage premiums that erode shipyard margins and extend delivery schedules.
- DP-3 certification bottlenecks:Redundant machinery and control system approvals from classification societies are stretching commissioning timelines for wind farm service specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platform Supply Vessels (PSV) Market |
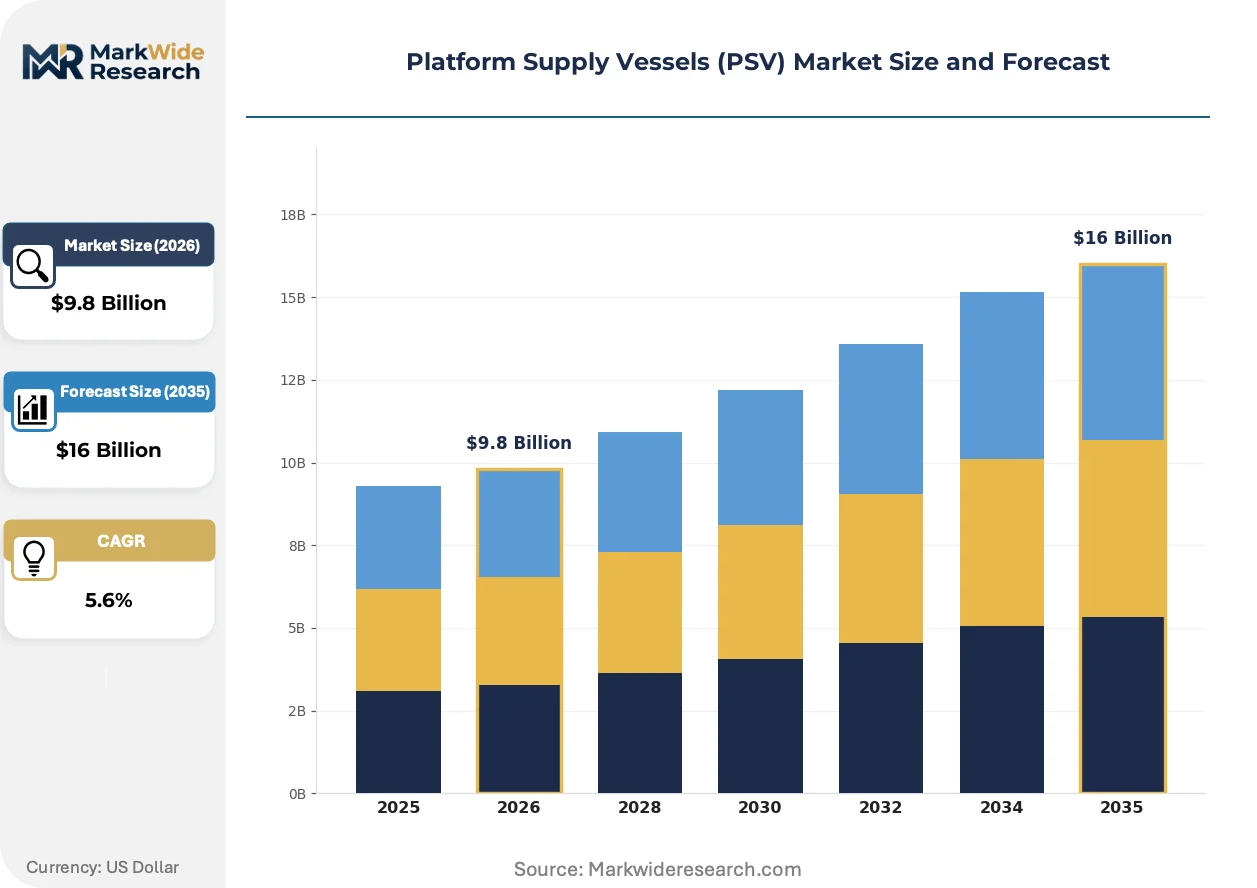
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Diesel-Electric, Hybrid, Conventional, Battery-Powered, Compressed Natural Gas Application: Oilfield Support, Offshore Wind Farm Supply, Subsea Construction, Diving Support, Emergency Response End User: Exploration Firms, Offshore Contractors, Marine Logistic Companies, Platform Operators, Salvage Companies Propulsion System: Azimuth Thrusters, Conventional Shaft, Water Jets, Voith Schneider Propeller, Cycloidal Drive |
| Companies Covered | Hornbeck Offshore Services, Edison Chouest Offshore Co., Tidewater Inc., New DOF ASA, BOURBON Maritime, Maersk Supply Service, SEACOR Marine Holdings Inc., Harvey Gulf Intl. Marine LLC, Solstad Offshore ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platform Supply Vessels (PSV) Market Strategic Shifts & Innovations
Propulsion technology diversification is fragmenting fleet standardization, with owners navigating competing decarbonization pathways while classification societies race to certify novel architectures before regulatory deadlines tighten.
Battery-hybrid configurations are fragmenting the traditional diesel-electric fleet base. These systems enable zero-emission harbor operations and load-levelling across variable transit profiles. Offshore wind developers in Denmark and Germany are specifying hybrid PSVs for turbine maintenance campaigns. The technology is fragmenting owner capital allocation between retrofit commitments and speculative newbuild orders.
The EU's Fit for 55 maritime package extends emissions trading to offshore vessels above 5,000 gross tonnage. This compels PSV operators to acquire carbon allowances or invest in abatement technologies. North Sea corridor fleets are responding with operational speed optimization and shore-power infrastructure investments at Aberdeen and Esbjerg.
Charter contracting is compressing toward campaign-specific rather than term-based structures. Offshore wind developers are unbundling vessel services from integrated installation contracts, creating spot-market exposure for owners. This pattern is most visible in German and Dutch waters where turbine OEMs directly procure logistics capacity.
Platform Supply Vessels (PSV) Market Segmentation
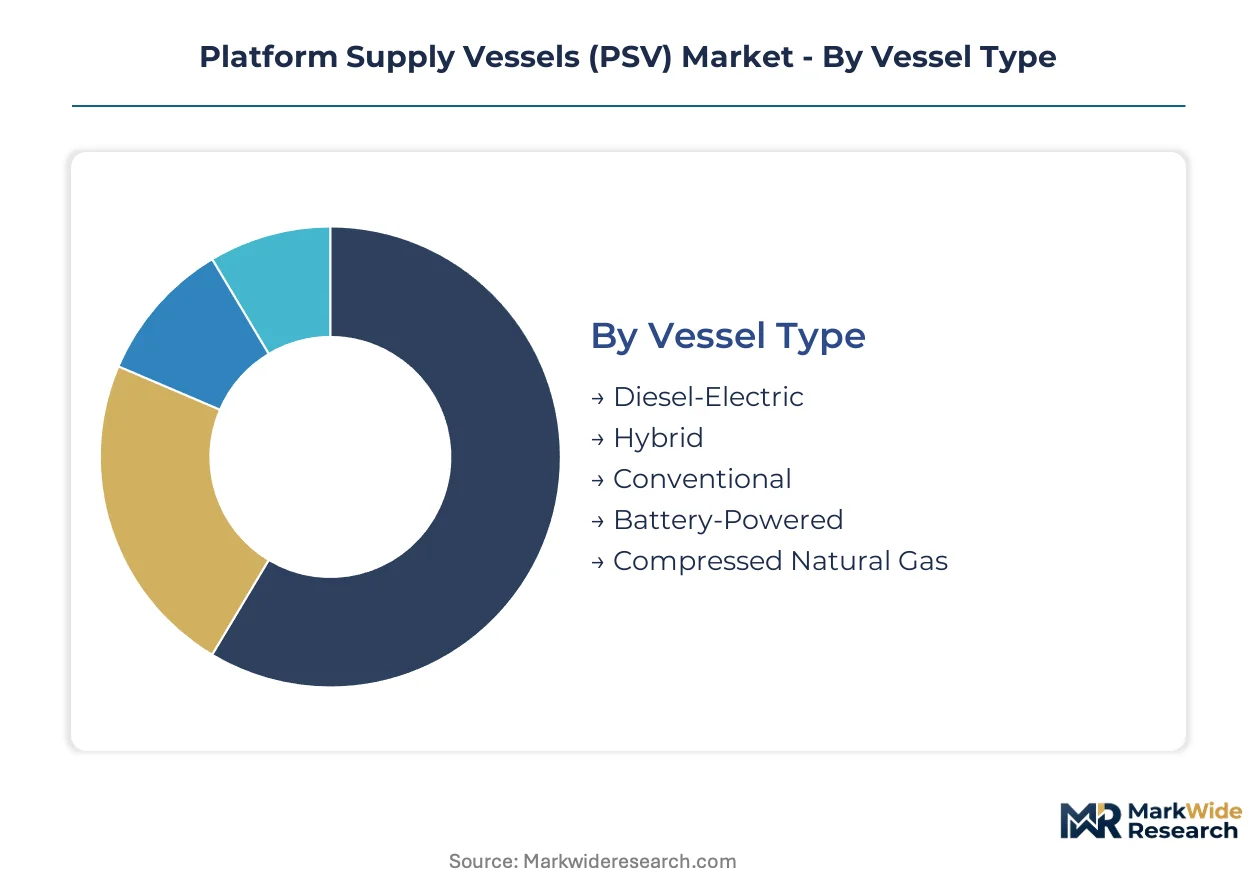
Segmentation in the PSV market reveals how propulsion technology divergence and end-use specialization are fragmenting fleet standardization. Owners must align vessel specifications with increasingly granular charter requirements across oilfield decommissioning and offshore wind logistics.
Vessel Type:
Substitution pressure from battery-hybrid architectures is most acute for aging diesel-electric units facing IMO Carbon Intensity Indicator thresholds.
- Diesel-Electric:These vessels employ multiple generator sets feeding electric propulsion motors, delivering operational flexibility across variable load profiles. Norwegian and UK North Sea operators are accelerating engine upgrades or retirements as EEXI compliance deadlines approach.
- Hybrid:Battery-diesel configurations enable zero-emission harbor operations and peak shaving during transit. Danish offshore wind developers are specifying hybrid PSVs for turbine maintenance campaigns, validating shore-power integration at Esbjerg and Aberdeen.
- Conventional:Direct mechanical propulsion systems dominate legacy fleet segments with simpler maintenance profiles but higher fuel consumption.
- Battery-Powered:Pure-electric configurations remain limited to short-range harbor and coastal operations due to energy density constraints.
- Compressed Natural Gas:Dual-fuel CNG systems offer moderate emissions reductions but face bunkering infrastructure gaps across North Sea ports.
Diesel-electric vessels anchor the volume base while hybrid configurations gain share at the steepest rate.
Application:
Cost tier differentiation separates capital-intensive subsea construction from commoditized oilfield supply runs.
- Oilfield Support:Cargo transport and personnel transfer to fixed and floating production platforms constitute the traditional revenue foundation. US Gulf of Mexico decommissioning obligations are sustaining demand for plug-and-abandonment support configurations.
- Offshore Wind Farm Supply:Turbine component logistics and technician transfer operations require walk-to-work gangway integration and dynamic positioning upgrades. German and Dutch waters are unbundling vessel services from integrated installation contracts, creating spot-market exposure.
- Subsea Construction:Heavy-lift and ROV support operations demand specialized deck arrangements and crane specifications.
- Diving Support:Saturation diving systems require hyperbaric chamber integration and extended endurance capabilities.
- Emergency Response:Standby rescue and oil spill recovery vessels command regulatory-mandated presence near production clusters.
Oilfield support retains the largest installed base while offshore wind farm supply climbs the fastest.
End User:
Procurement concentration among integrated offshore contractors is displacing fragmented spot chartering.
- Exploration Firms:Seismic survey support and drilling rig supply operations prioritize vessel availability over specification sophistication.
- Offshore Contractors:Integrated installation and maintenance providers are consolidating vessel demand under multi-year framework agreements.
- Marine Logistic Companies:Third-party vessel managers are capturing outsourcing trends from oil majors seeking operational flexibility.
- Platform Operators:Production-focused entities require predictable supply chain continuity for consumables and spare parts.
- Salvage Companies:Emergency response and wreck removal specialists maintain on-call vessel arrangements with premium day-rate structures.
Offshore contractors dominate contract value while marine logistic companies expand most quickly through outsourcing capture.
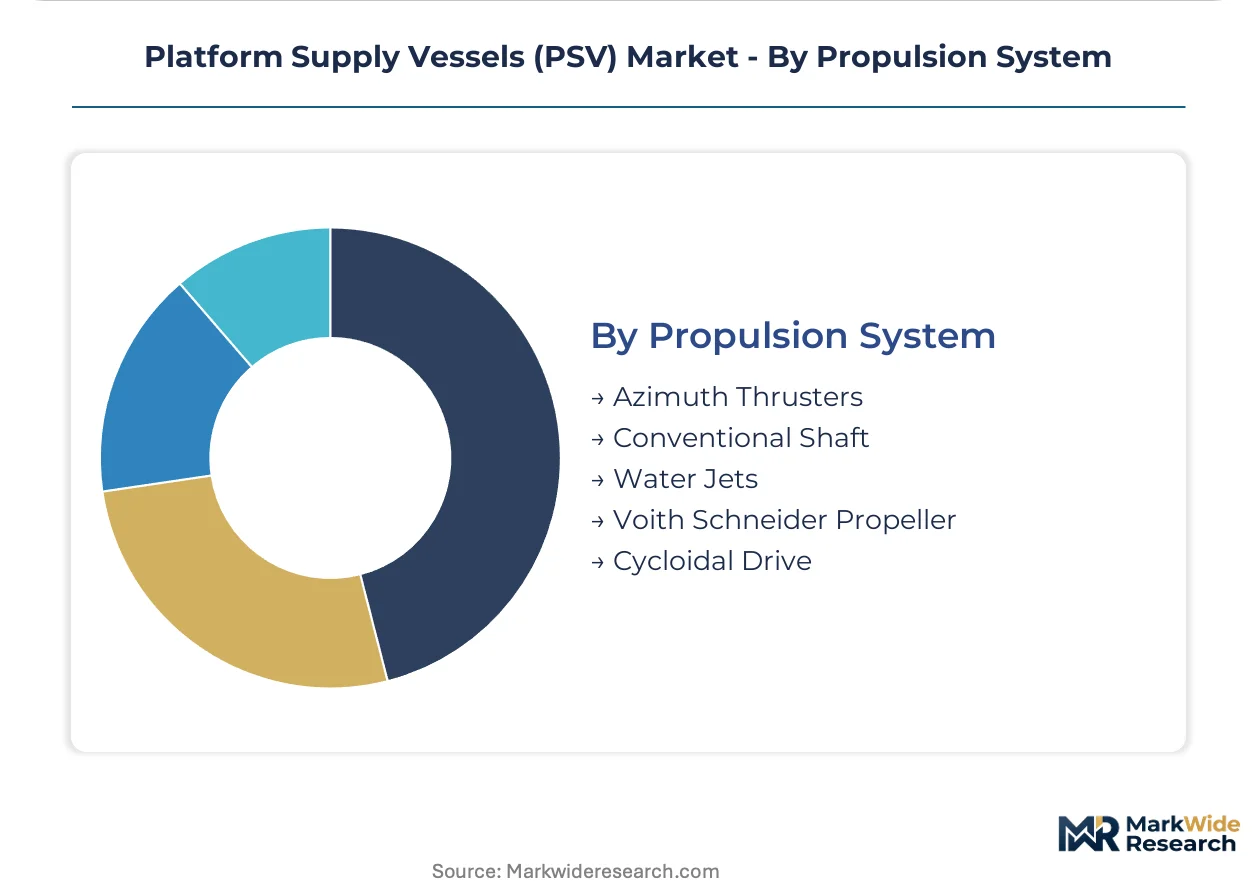
Propulsion System:
Margin compression in azimuth thruster manufacturing is intensifying competition among European and Asian suppliers.
- Azimuth Thrusters:Z-drive and L-drive configurations deliver 360-degree thrust vectoring for dynamic positioning operations. DNV and Lloyd's Register apply differing redundancy notations, complicating owner specification decisions and finance approval timelines.
- Conventional Shaft:Fixed-pitch and controllable-pitch propellers remain cost-competitive for transit-optimized vessels without station-keeping requirements.
- Water Jets:High-speed propulsion for crew transfer and fast supply vessels sacrifices payload capacity for reduced transit times.
- Voith Schneider Propeller:Cycloidal blade systems enable precise thrust magnitude and direction control for station-keeping in confined offshore wind arrays.
- Cycloidal Drive:Vertical-axis propulsion alternatives compete in ice-class and shallow-draft specifications.
Azimuth thrusters anchor the volume base while Voith Schneider Propeller systems gain share at the steepest rate in offshore wind applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Northern European operators prioritize battery-hybrid specifications for offshore wind logistics, while Gulf of Mexico demand centers on decommissioning support for aging oil infrastructure.
Norway
Offshore wind farm maintenance campaigns and North Sea oilfield decommissioning drive vessel demand. The Norwegian Maritime Authority enforces strict harbor emissions rules that validate shore-power integration at Bergen and Stavanger. Shipyards in the Haugesund cluster specialize in hybrid propulsion retrofits for existing diesel-electric fleets.
United Kingdom
Turbine installation intensity in Scottish waters and southern North Sea fields sustains charter activity. The UK Maritime and Coastguard Agency implements Carbon Intensity Indicator compliance deadlines that accelerate fleet renewal decisions. Aberdeen functions as the primary logistics hub, with vessel operators investing in walk-to-work gangway systems for technician transfer operations.
United States
Gulf of Mexico plug-and-abandonment obligations and offshore platform supply runs anchor regional demand. The Environmental Protection Agency coordinates with the Coast Guard on emissions standards for vessels operating in federal waters. Port Fourchau in Louisiana concentrates PSV berthing capacity, while Houston-based operators manage fleet deployment across the Americas basin.
Denmark
Large-scale offshore wind development in the Baltic and North Seas generates specialized vessel requirements. Danish Maritime Authority regulations mandate zero-emission harbor operations for newbuild contracts. The Port of Esbjerg hosts the primary marshalling infrastructure for turbine component logistics serving German and Dutch installation sites.
Germany
Offshore wind farm construction and maintenance in the North Sea and Baltic Sea sustain vessel utilization. Federal Maritime and Hydrographic Agency licensing requirements shape dynamic positioning certification standards for wind service specifications. Cuxhaven and Bremerhaven cluster turbine logistics operations, with developers unbundling vessel services from integrated installation contracts.
Platform Supply Vessels (PSV) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with ownership concentration highest among operators controlling in-house shipyard capacity and crew training infrastructure. The market structure rewards geographic fleet concentration that sustains day-rate premiums in specific basins. Three archetypes dominate: integrated operators with captive shipyard assets, regional specialists leveraging local regulatory knowledge, and diversified marine service conglomerates spanning multiple vessel classes. Competitive moves center on hybrid propulsion technology partnerships and strategic fleet repositioning between oilfield support and offshore wind contracts.
Among integrated operators with vertical infrastructure, Edison Chouest Offshore Co. and BOURBON Maritime exemplify the archetype of owners controlling in-house production capabilities and specialized crew academies. Tidewater Inc. anchors the regional specialist tier through concentrated Gulf of Mexico fleet positioning. These three companies represent distinct competitive vectors: integrated shipyard control, European offshore wind logistics specialization, and Americas basin day-rate optimization.
| Leading Market Players |
|---|
| Hornbeck Offshore Services |
| Edison Chouest Offshore Co. |
| Tidewater Inc. |
| New DOF ASA |
| BOURBON Maritime |
| Maersk Supply Service |
| SEACOR Marine Holdings Inc. |
| Harvey Gulf Intl. Marine LLC |
| Solstad Offshore ASA |
| Others |
Cost & Logistics Intelligence
Battery-hybrid propulsion substitution for diesel-electric architectures simultaneously redraws supply geography toward Korean and Chinese cell manufacturers and compresses pricing economics for European shipyards facing input cost volatility. This dual restructuring forces owners to recalibrate newbuild budgets against retrofit alternatives while charterers unbundle vessel services into campaign-specific contracts.
Pricing Analysis
Long-term offtake contracts with integrated offshore contractors anchor pricing stability, while spot-market exposure intensifies for campaign-specific offshore wind logistics. Three-tier pricing structure across DP-3 certified premium vessels, standard diesel-electric units, and aging conventional hulls reflects certification grade and harbor emissions compliance. Cost compression in the standard tier is intensifying because marine battery supply concentration limits yard bargaining power. Exploration firms exhibit the highest price sensitivity, whereas offshore wind developers prioritize specification sophistication over day-rate economics.
Supply Chain Analysis
Port congestion at Korean battery export terminals and container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for European shipyards assembling hybrid propulsion packages. Manufacturing concentration centers on South Korea, China, and Japan for lithium-ion cells, with Norway, the United Kingdom, and Denmark hosting final vessel integration. The supply chain draws from cathode chemistry feedstocks, azimuth thruster systems, and dynamic positioning control hardware. Single-source vulnerability in Korean cell manufacturing creates procurement risk. Distribution runs through shipyard direct sales and vessel operator framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propulsion technology divergence fragments fleet standardization, creating specialized niches for battery-hybrid retrofit specialists and offshore wind logistics providers as charter contracting compresses toward unbundled campaign structures.
For Market Incumbents: Consolidate hybrid propulsion engineering capabilities through captive training academies or strategic shipyard partnerships to defend against certified marine engineer scarcity. Lock in multi-year framework agreements with offshore wind developers before spot-market exposure erodes pricing power. Prioritize DP-3 certification investment for walk-to-work gangway integration to capture premium day-rate tiers. For New Entrants and Emerging Players: Anchor in US Gulf of Mexico decommissioning support, where plug-and-abandonment obligations sustain demand for specialized cargo configurations with lower certification barriers. Target shallow-draft PSV subsets for European offshore wind logistics contracts, where BOURBON Maritime's established position leaves room for regional specialists. Pursue direct charter relationships with turbine OEMs unbundling vessel services from integrated installation contracts. For Investors and Strategic Acquirers: The market sits at a fleet renewal phase that favors integrated operators with in-house shipyard capacity and crew training infrastructure. Long-term viability hinges on exposure to offshore wind logistics growth and regulatory compliance service revenue rather than pure oilfield support volume. Monitor IMO Carbon Intensity Indicator enforcement stringency as the signal to watch for accelerated scrapping decisions and newbuild demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Partnership | Battery-diesel integration with shore-power validation at Esbjerg and Aberdeen secures harbor emissions compliance. |
| Walk-to-Work Gangway Integration | DP-3 certified technician transfer systems unlock premium day-rate tiers with offshore wind developers. |
| In-House Crew Training Academy | Captive marine engineer pipelines address hybrid propulsion scarcity eroding shipyard delivery schedules. |
| North Sea Logistics Hub Investment | Shore-power infrastructure at Bergen and Stavanger validates zero-emission harbor operations for Norwegian contracts. |
| Decommissioning Support Configuration | Specialized cargo arrangements for Gulf of Mexico plug-and-abandonment campaigns sustain utilization through oilfield decline. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with vessel operators, shipyard procurement directors, offshore wind project developers, and classification society surveyors; and secondary validation through Lloyd's Register and DNV certification databases, IMO regulatory filings, and port authority emissions compliance records. Bottom-up vessel deployment tracking across the North Sea corridor and US Gulf of Mexico triangulated against top-down charter contract value estimates.
Across the analysis window, the forecasting framework modeled vessel type segmentation by propulsion architecture, application specialization across oilfield support and offshore wind logistics, and end-user procurement concentration among integrated offshore contractors. CAGRs were derived from fleet renewal schedules against regulatory compliance deadlines and offshore wind installation intensity projections. Key inputs included marine battery cost curves, EEXI retrofit economics versus scrap value thresholds, and harbor emissions rule enforcement timelines.
Material uncertainties — IMO regulatory amendment timing, marine battery supply disruption, and offshore wind development pace — sit outside the modeled envelope. Forecasts reflect assumptions about classification society notation convergence and charter contracting structure evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
United States Offshore Support Vessels Market